
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Asia Pacific underground mining equipment Market Size 2023 | USD 13518.2 million |
| Asia Pacific underground mining equipment Market, CAGR | 32.30% |
| Asia Pacific underground mining equipment Market Size 2032 | USD 167863.96 million |
Market Insights
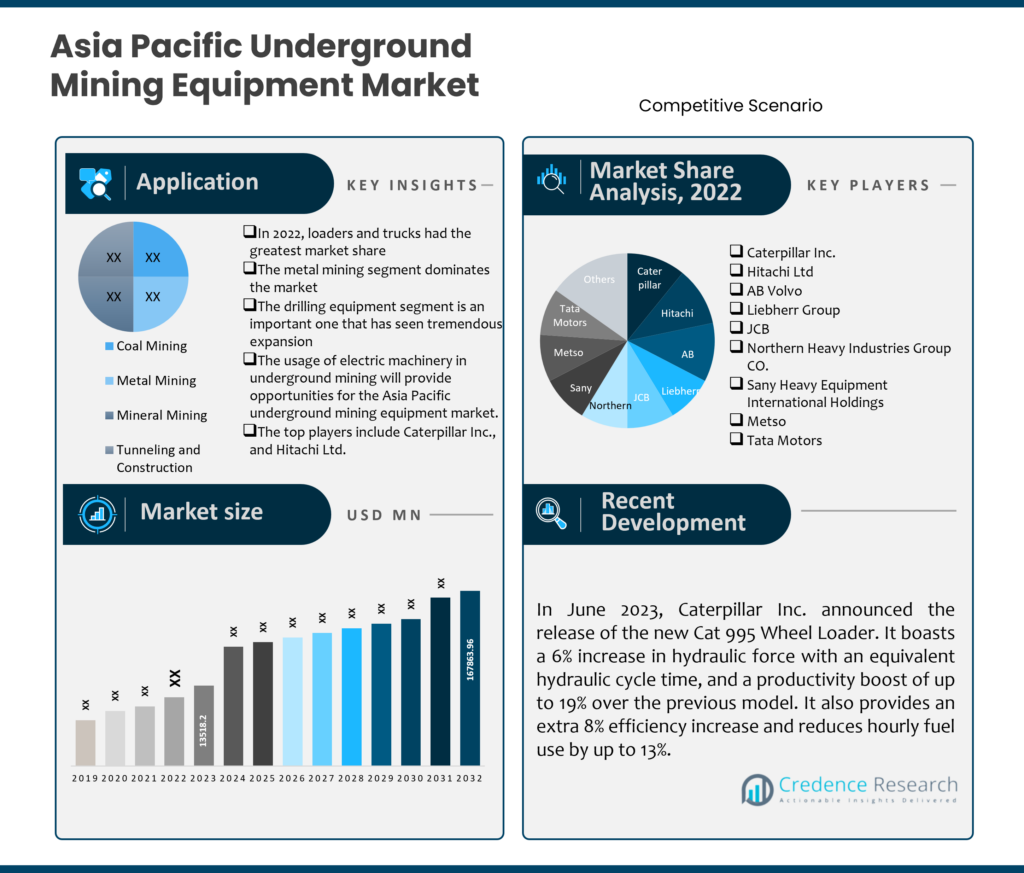
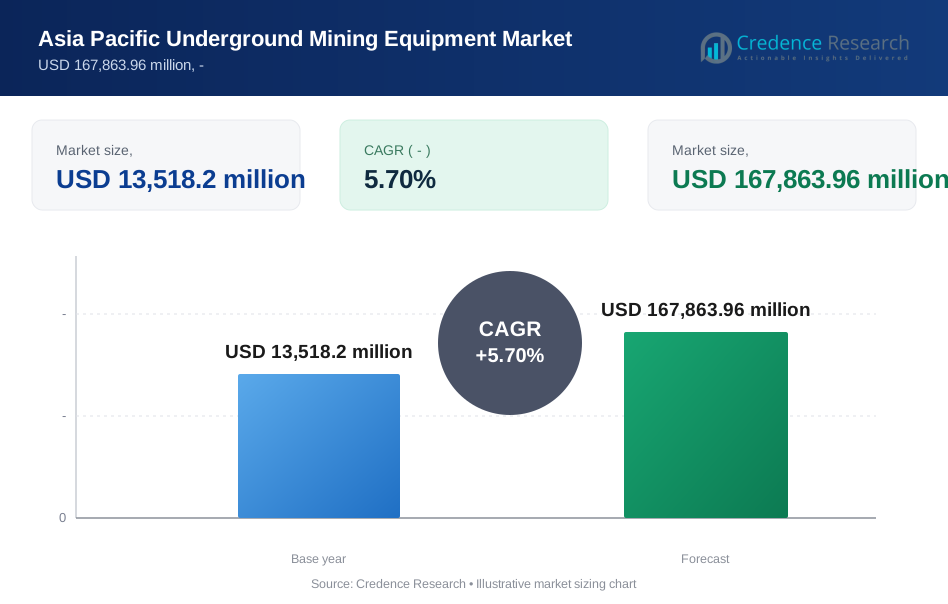
- Between 2024 and 2032, the market for Asia Pacific underground mining equipment is projected to rise at a compound annual growth rate (CAGR) of 32.30%, from an estimated USD 13518.2 million in 2023 to USD 167863.96 million in 2032.
- The largest category is loaders and trucks. Drilling equipment, on the other hand, is expected to grow at a strong CAGR.
- The metal mining category will expand at a rapid rate of growth.
- China governed the Asia Pacific underground mining equipment market.
- Regarding the market share of Asia Pacific underground mining equipment, India is expected to come second.
- In the Asia Pacific underground mining equipment market, Japan is anticipated to grow fastest.
- The robust economic growth in the Asia-Pacific region and the rising demand for metals and minerals are the main drivers of market expansion.
- Rapid urbanization has led to a rise in the need for building materials as well as the expansion of the manufacturing and industrial sectors, which has contributed to the Asia Pacific underground mining equipment market.
Executive Summary
Market Definition
Harvesting valuable minerals, resources, and commodities from under the surface of the earth involves the use of machinery in underground mining. To remove coal, metals, and minerals from below the surface of the earth, underground mining is used. For underground mining operations, equipment such as loaders, trucks, bolters, drills, scalers, and underground trains are utilized. Mining companies use these systems to remove ores and minerals. Coal, metal, and mineral mining are among the industries that use underground mining equipment.
Market Overview
The Asia Pacific underground mining equipment sector is predicted to continue its upward trend between 2024 and 2032, growing at a compound annual growth rate (CAGR) of 32.30%. From its projected USD 13518.2 million in 2023 to USD 167863.96 million in 2032, the market will continue to grow.
The supply of cutting-edge equipment for a range of applications, including metal, coal, and mineral mining, by major companies like Sandvik AB, AB Volvo, Komatsu Ltd., Caterpillar Inc., and others drives the expansion of the market. Eco-friendly and sustainable mining methods are becoming more and more important to lessen their negative effects on the environment. As a result, underground mining operations are increasingly using electric-powered machinery. Several benefits come with driving an electric car, such as decreased noise pollution, lower pollutants, and increased energy economy.
Observing real-time monitoring techniques in mining equipment, in addition to automation, Industry 4.0 penetration, Internet of Things (IoT), GPS sensing, and 3D imagination in these equipment, drives the market expansion. Equipment used in underground mining emphasizes greater operational efficiency and minimizes equipment damage. Additionally, big businesses are attempting to introduce battery- and hybrid-powered devices to the market. The expansion of the Asia Pacific underground mining equipment market is primarily driven by all of these factors.
Segmentation by Type of Equipment
- The loaders and trucks category is the market leader in terms of equipment type. The need for loaders and trucks is greatly impacted by the amount of mining activities in nations such as China, India, Australia, Indonesia, and others. These tools are more necessary as exploration, development, and manufacturing operations rise.
- The drilling equipment category will exhibit a sizable CAGR during the projected period. Mineral resources abound in the Asia-Pacific area, including coal, iron ore, copper, gold, and other materials. Exploration drilling to find new deposits and production drilling to extract minerals are the main drivers of the drilling equipment sector.
- Other types of equipment, including haulage equipment, drilling support equipment, tunneling equipment, ventilation systems, and crushing and grinding equipment, also support the need for Asia Pacific underground mining equipment.
Segmentation by Application
- Metal mining is considered the best application category. The Asia-Pacific area plays an important role in the world's mineral and metal supply lines. Major producers and exporters of metals, such as Australia, China, Indonesia, and India, provide raw materials to international markets.
- The coal mining category will likely register a significant CAGR during forecasting. Coal mining operations depend heavily on underground mining equipment to extract coal resources from below the surface of the earth.
- Other applications, such as mineral mining and tunneling and construction, also contribute to the demand for Asia Pacific underground mining equipment.
Segmentation by Country
- China leads the Asia Pacific underground mining equipment industry. China has been progressively inviting international investment and involvement in its mining industry. The entry of foreign businesses into the market stimulates innovation and competition in the underground mining equipment sector by bringing superior technology, skills, and capital.
- India is estimated to rank second in Asia Pacific in the underground mining equipment market size.
- The Asia Pacific underground mining equipment industry is predicted to flourish rapidly in Japan.
- Countries including South Korea, Southeast Asia, and the rest of Asia Pacific cover the remaining need for Asia Pacific underground mining equipment.
Based on projections, China is anticipated to control the Asia Pacific underground mining equipment market. China is the biggest producer and user of coal worldwide. The nation primarily uses coal for heating, industrial activities, and the production of power. Because of this, there is a continuous need for underground mining equipment to securely and effectively recover coal from underground mines.
The market for Asia Pacific underground mining equipment in India is anticipated to expand quickly throughout the forecast period. To encourage the expansion of the mining industry, draw in foreign investment, and boost domestic output, the Indian government has launched a number of programs and regulations. The goal of initiatives like "Make in India," "Atmanirbhar Bharat," and mining regulation reforms is to establish a favorable environment for the market for underground mining equipment.
Key Highlights of the Report
The Asia Pacific underground mining equipment market is segmented by type of equipment, application, and country. The loaders and trucks category is the market spearhead in terms of type of equipment, and metal mining is the top application category. The market is expanding mostly in China.
The increasing demand for metals and minerals has surged due to industrial development in a number of industries, including manufacturing, electronics, and the automobile industry. For these businesses to generate items and satisfy consumer demand, a consistent supply of raw materials is necessary. Furthermore, the implementation of laws and incentives by governments across the Asia Pacific has stimulated activities, leading to an increase in the exploration and extraction of minerals and metals. Substantial quantities of metals and minerals are also needed for large-scale infrastructure projects like building roads, bridges, and railroads, which increases the need for underground mining equipment to remove these materials from subterranean locations.
China is expected to account for the largest Asia Pacific underground mining equipment market. The requirement for raw materials and energy resources is supported by China's continuous economic growth and industrialization. In order to provide these resources for the industrial sectors of manufacturing, building, energy production, and others, underground mining equipment is necessary. It is also anticipated that the market will develop at the fastest rate in India. This is due to the rising demand for underground mining equipment from various industries in India.
Which Key Factors Are Driving The Asia Pacific Underground Mining Equipment Market?
Investment in the mining industry is encouraged by advancements in mining technology, funding for infrastructure projects like energy and transportation grids, and favorable laws and subsidies from the government. These reasons are driving the growth of the underground mining equipment market in Asia Pacific.
What Are The Main Challenges Confronting The Asia Pacific Underground Mining Equipment Market?
The factors preventing the market from expanding are technological limits, difficulties in creating sophisticated underground mining equipment, and disruptions in the mining equipment supply chain.
What Market Opportunities Exist For Asia Pacific Underground Mining Equipment?
Several factors, including the liberalization of mining regulations that draw foreign investment, the use of energy-efficient equipment that lowers operating costs, and the influence of mining operations on local communities and stakeholders, are influencing the Asia Pacific underground mining equipment market.
Market Drivers
Usage of Electric Machinery in Underground Mining Is Growing
The use of diesel engines in underground mining equipment can make the already uncomfortable working conditions worse because of the noise, heat, and pollutants they emit. Furthermore, adequate ventilation needs to be ensured while utilizing diesel-powered mining equipment. Because electric or battery-powered mining equipment produces no emissions and has minimal operating expenses, it ensures safer working conditions. It resolves the subterranean mine ventilation problem. For example, there is a reduction in temperature, noise, and air pollution when subterranean loaders driven by batteries are used. To continue underground mining, other batteries can be replaced by high-energy-density batteries. Without putting their health in peril, the operator can work in demanding subterranean situations in a calm, ergonomic cabin with easy, safe access to all service points.
Electric mining equipment is becoming more and more common in deep mines due to collaborations, agreements, new product releases, and supply orders between mining firms and producers of mining equipment. For example, the autonomous electric dump truck XDR80TE-AT was introduced by XCMG Group (China) in April 2023. Likewise, at Bauma Conexpo India 2023 in March 2023, Liugong India debuted the 856HEMax, an electric wheel loader.
Market Restraints
High Operating Costs and Capital Expenditure to Restrain Market Growth
The cost of buying and maintaining equipment for underground mining can be high. For mining firms, particularly smaller ones, the initial outlay needed for equipment like drills, loaders, and trucks can be a major obstacle. The expenses associated with operating and maintaining such equipment might be high. The cumulative cost of labor, fuel, energy, and maintenance can have an impact on profitability. In the area, growing knowledge of how mining affects the ecosystem has led to serious concerns.
Furthermore, the cost of underground mining equipment varies based on the type of underground mining, from USD 500,000 to USD 1.5 million. Small and medium-sized businesses are likewise unable to absorb this enormous expense. All of the above-listed reasons limit the market's ability to grow.
Opportunities
The Asia Pacific underground mining equipment sector has a plethora of promising opportunities. Among these are the following:
Use of Self-Contained Mining Equipment
The mining industry has advanced significantly, especially with the advent of autonomous mining machinery. Because mining processes are repetitive, physically demanding, precise, and time-sensitive, autonomous technology is a perfect fit for this industry. Autonomous mining trucks have to travel a predetermined path each time in order to meet material handling capacity regulations. As a result, manufacturing time is cut down, human error is less likely, safety is raised, production volume is increased, and accuracy and repeatability are improved.
Manufacturers are developing autonomous mining equipment that can report status, receive commands, and block radio signals from other equipment over a wireless connection. It guarantees higher productivity, more security, and less unplanned maintenance. Among the leading manufacturers of autonomous mining trucks that are in use are Komatsu Ltd. and Caterpillar Inc.
Competitive Landscape
Key Players
In the highly competitive Asia Pacific underground mining equipment market, there are a number of significant rivals. A few of the top market players are shown below, together with their respective market shares:
- Caterpillar Inc.
- Hitachi Ltd
- AB Volvo
- Liebherr Group
- JCB
- Northern Heavy Industries Group CO.
- Sany Heavy Equipment International Holdings
- Metso
- Tata Motors
- Others
To stay competitive, these businesses give priority to product innovation, expanding their distribution networks, and completing mergers and acquisitions.
The biggest vendors in the Asia Pacific underground mining equipment market consistently strive to keep one step ahead of the competition by creating cutting-edge ideas and goods.
In March 2023, In an effort to promote a more sustainable mining sector and cut CO2 emissions by more than 25%, Volvo Trucks and the Swedish mining company Boliden teamed up to launch battery-electric trucks for heavy underground transport in Boliden's Kankberg mine.
In December 2022, A new DD322i drill for use in underground mining was introduced by Sandvik Mining and Rock Solutions, a division of Sandvik AB. For smart tunneling and subterranean development, it is an automated, twin-boom drill that is incredibly compact. This kind of drill is utilized in mining and tunneling operations. Furthermore, it is less expensive than other systems.
How are Companies Performing in the Asia Pacific Underground Mining Equipment Market?
Several remarkable factors have contributed to the notable performance of companies in the Asia Pacific underground mining equipment market. Companies are making significant investments in R&D in an effort to produce cutting-edge products and technologies that could support future technological advancements. For example, Caterpillar has introduced a trolley assist system for mining trucks with electric drives. This is a step in the direction of stricter regulations from the government and campaigners to prevent mining-related pollution from rising.
Companies in the market, including AB Volvo, Hitachi Construction Machinery, Caterpillar Inc., and others, are launching cutting-edge underground mining equipment to boost competition and enhance the supply chain of these systems, which encourages market expansion. For example, MacLean introduced the ML5 Multi-Lift in April 2023. It is a specially designed-mining vehicle that provides productivity, safety, and versatility for underground operations. The battery-operated device boasted a 45-tonne payload capacity and a working height of 6.5 meters. Its improved features and design made it easy to use and guaranteed increased operator safety.
To diversify their product offerings and increase their market share, companies in the Asia Pacific underground mining equipment market are acquiring other businesses. For example, Energy-as-a-service (EaaS) provider Tangent Energy Solutions (US) was purchased by Caterpillar Inc. (US) in May 2022. Tangent Energy Solutions provides clients with full turnkey solutions to reduce energy costs, increase energy efficiency, reduce emissions, monetize grid support, and guarantee operational resilience. The acquisition of Tangent Energy was done in order to generate additional revenue streams. Solution's EaaS services complement Caterpillar's wide range of electric power supply, offering. Caterpillar Inc. will be able to more effectively provide its customers with energy solutions that are connected, sustainable, dependable, and efficient.
Summary of Key Findings
- Competition between equipment suppliers and manufacturers drives innovation, cost savings, and quality enhancements in underground mining equipment.
- The market is segmented by type of equipment, application, and country.
- The loaders and trucks category is estimated to develop at a significant CAGR over the forecast period.
- Metal mining is the foremost application category.
- China is leading market development; the market is highly competitive with key players including Caterpillar Inc., Hitachi Ltd, AB Volvo, Liebherr Group, JCB, Northern Heavy Industries Group CO., Sany Heavy Equipment International Holdings, Metso, Tata Motors, and Others.
Future Outlook
- The outlook is favorable for the Asia Pacific underground mining equipment market, with a notable growth predicted in China.
- The transfer of technology and experience from developed to developing markets promotes the adoption of modern equipment and strengthens capacities.
- Fluctuations in commodity prices can impact the profitability of mining projects and the demand for underground mining equipment.
- To remain competitive, major corporations must develop new products, expand their customer base, and keep their prices low.
How the Credence Research Asia Pacific Underground Mining Equipment Market Report Can Help CXOs
The Credence Research Asia Pacific Underground Mining Equipment Market Report provides CXOs with an extensive market overview and comprises the following:
- Market size and growth forecast: The study offers comprehensive market estimations for Asia Pacific underground mining equipment, broken down by type of equipment, application, and country. In addition, projections for the market through 2032 based on significant drivers and trends are included.
- Market segmentation: The Asia Pacific underground mining equipment market is divided into segments by type of equipment, application, and country in the research report. CXOs are given a detailed grasp of the market and the potential inside each sector due to this segmentation.
- Competitive landscape: The study report provides a thorough analysis of the leading businesses in the Asia Pacific underground mining equipment sector, together with details on their revenue streams, product lines, and business strategies. This information can help CXOs assess and identify their competitors.
- Key trends and drivers: The study report analyzes and highlights the key developments and elements driving the market for Asia Pacific underground mining equipment. CXOs can utilize this information to make well-informed choices regarding their plans and investments.
The Credence Research Asia Pacific Underground Mining Equipment Market Report provides CXOs with insights that they may utilize to:
- Identify growth opportunities: This analysis is likely to help CXOs find fresh growth prospects in the Asia Pacific underground mining equipment sector. For example, the research recognizes the increasing requirement for underground mining equipment from the coal mining sector as a crucial opportunity.
- Make informed investment decisions: The study aids CXOs in making informed decisions about underground mining equipment. For example, it delivers information on the key variables to consider while picking solutions and evaluating suppliers.
- Develop competitive strategies: CXOs can utilize the research report to establish competitive strategies for their Asia Pacific underground mining equipment firms. The study paper explores the primary tactics employed by Asia Pacific underground mining equipment providers to set themselves apart from their rivals.
- Track market developments: By tracking market advancements, this research report could assist CXOs in remaining ahead of the curve. For example, it provides information about the latest advancements and patterns in the Asia Pacific underground mining equipment industry.
The Credence Research Asia Pacific Underground Mining Equipment Market Report is helpful for CXOs who want to learn more about the market and identify potential opportunities.
Segmentation
-
By Type of Equipment
- Drilling Equipment
- Loaders and Trucks
- Haulage Equipment
- Drilling Support Equipment
- Tunneling Equipment
- Ventilation Systems
- Crushing and Grinding Equipment
-
By Application
- Coal Mining
- Metal Mining
- Mineral Mining
- Tunneling and Construction
-
By Country
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
Adjacent Markets
Several adjacent markets in the Asia Pacific underground mining equipment market have high revenue growth opportunities. The key adjacent markets for the Asia Pacific underground mining equipment market -
Adjacent Markets |
||
| Surface Mining Equipment | Construction Equipment | Mining Machinery Parts and Components |
| Mining Software and Technology Solutions | Industrial Automation and Robotics | Material Handling Equipment |
| Energy and Power Systems | Metal and Mineral Processing Equipment | Geotechnical Services and Engineering |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Urbanization and Industrialization
The Asia Pacific region is experiencing significant urbanization and industrial growth, which increases the demand for metals and minerals used in construction, manufacturing, and infrastructure projects. This drives the need for advanced underground mining equipment to support higher extraction rates.
Adoption of Electric and Autonomous Mining Equipment
Growing emphasis on sustainability and operational efficiency is leading to increased adoption of electric and autonomous underground mining equipment. These technologies reduce emissions, improve safety, and lower operating costs, making them attractive investments for mining companies.
Government Initiatives and Regulatory Support
Governments in countries like China and India are implementing favorable policies, incentives, and reforms to attract investment in the mining sector. These initiatives encourage modernization and expansion of underground mining operations, boosting equipment demand.
Expansion of Metal Mining Activities
Asia Pacific is a major global supplier of metals such as copper, gold, and iron ore. The expansion of metal mining activities, particularly in China, Australia, and India, is fueling the demand for specialized underground mining equipment.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How much does the Asia Pacific market currently hold for underground mining equipment?
What is the Asia Pacific underground mining equipment market's projected growth rate between 2024 and 2032?
What is the most significant market segment in terms of equipment type?
Regarding the application, which market category is in the lead?
Which type of equipment is anticipated to grow at the fastest rate throughout the projected period?
In which country is the market for Asia Pacific underground mining equipment expanding?
Who are the main players in the Asia Pacific underground mining equipment industry?
Which market factors are the primary drivers of the Asia Pacific underground mining equipment industry?
What main market challenges prevent the growth of the Asia Pacific underground mining equipment sector?
What are the main market opportunities for the Asia Pacific underground mining equipment sector?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Country
- 1.2.1 China
- 1.2.2 Japan
- 1.2.3 India
- 1.2.4 South Korea
- 1.2.5 South-east Asia
- 1.2.6 Rest of Asia Pacific
- 1.3 By Application
- 1.3.1 Coal Mining
- 1.3.2 Metal Mining
- 1.3.3 Mineral Mining
- 1.3.4 Tunneling and Construction
- 1.4 By Type of Equipment
- 1.4.1 Drilling Equipment
- 1.4.2 Loaders and Trucks
- 1.4.3 Haulage Equipment
- 1.4.4 Drilling Support Equipment
- 1.4.5 Tunneling Equipment
- 1.4.6 Ventilation Systems
- 1.4.7 Crushing and Grinding Equipment
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 13,518.2 million → 2032: USD 167,863.96 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Asia Pacific Underground Mining Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Asia Pacific Underground Mining Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Asia Pacific Underground Mining Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Asia Pacific Underground Mining Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Asia Pacific Underground Mining Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Asia Pacific Underground Mining Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Asia Pacific Underground Mining Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Asia Pacific Underground Mining Equipment Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 13,518.2 million → 2032: USD 167,863.96 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Asia Pacific Underground Mining Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Country - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 China
- 12.3.7.2 Japan
- 12.3.7.3 India
- 12.3.7.4 South Korea
- 12.3.7.5 South-east Asia
- 12.3.7.6 Rest of Asia Pacific
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Coal Mining
- 12.4.7.2 Metal Mining
- 12.4.7.3 Mineral Mining
- 12.4.7.4 Tunneling and Construction
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Equipment - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Drilling Equipment
- 12.5.7.2 Loaders and Trucks
- 12.5.7.3 Haulage Equipment
- 12.5.7.4 Drilling Support Equipment
- 12.5.7.5 Tunneling Equipment
- 12.5.7.6 Ventilation Systems
- 12.5.7.7 Crushing and Grinding Equipment
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Asia Pacific Underground Mining Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Asia Pacific Underground Mining Equipment Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Country-Level Shares, 2023
- 14.2 Country Market Size Comparison, 2023
- 14.3 Country Market Forecasts, 2023-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Asia Pacific Underground Mining Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Asia Pacific Underground Mining Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Caterpillar Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Hitachi Ltd
- 18.4 AB Volvo
- 18.5 Liebherr Group
- 18.6 JCB
- 18.7 Northern Heavy Industries Group CO.
- 18.8 Sany Heavy Equipment International Holdings
- 18.9 Metso
- 18.10 Tata Motors
- 18.11 Sandvik AB
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

