
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Pharmacovigilance Market Size 2023 | USD 9,574.26 Million |
| Pharmacovigilance Market, CAGR | 7.48% |
| Pharmacovigilance Market Size 2032 | USD 18,325.43 Million |
Market Overview
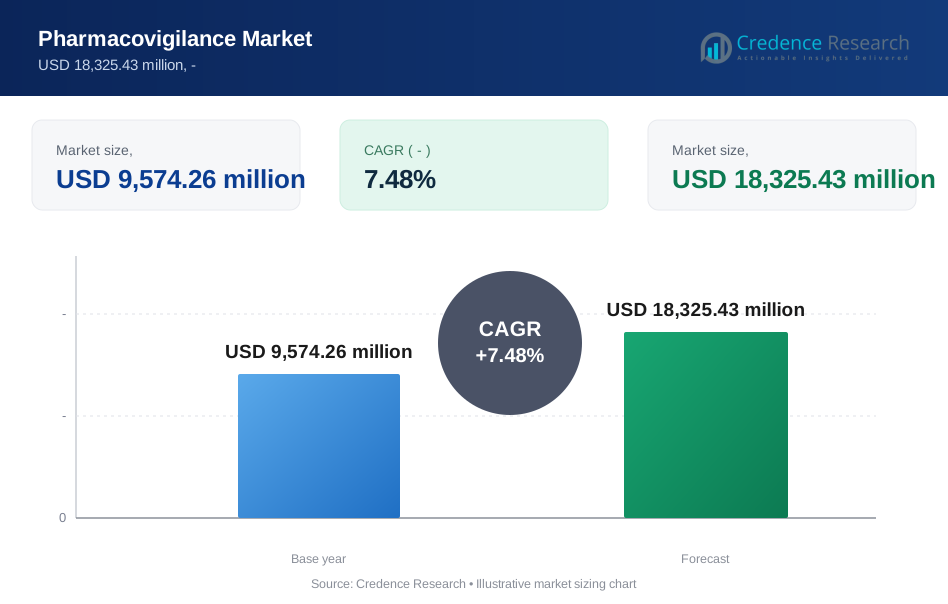
The Pharmacovigilance Market is projected to grow from USD 9,574.26 million in 2023 to USD 18,325.43 million by 2032, at a compound annual growth rate (CAGR) of 7.48%.
The Pharmacovigilance Market is driven by increasing regulatory requirements for drug safety, rising consumer awareness about adverse drug reactions, and the growing complexity of drug development processes. Enhanced focus on patient safety and the integration of advanced technologies like AI and big data analytics further support market expansion. Additionally, the increasing number of clinical trials and a higher incidence of chronic diseases globally contribute to the demand for robust pharmacovigilance systems. These factors collectively ensure rigorous monitoring and reporting of drug safety, bolstering the growth of the pharmacovigilance sector.
The Pharmacovigilance Market exhibits significant regional variations, with North America and Europe leading in market share due to stringent regulatory frameworks and advanced healthcare systems. Asia Pacific is emerging as a high-growth region due to expanding pharmaceutical industries and increasing awareness. Key players shaping the market include Accenture, IQVIA Inc., Cognizant, and ICON plc., who drive innovation and offer comprehensive pharmacovigilance solutions. These companies leverage their global reach and technological advancements to enhance drug safety monitoring and regulatory compliance across diverse geographies.
Market Drivers
Increasing Prevalence of Chronic Diseases
The growing incidence of chronic diseases, including diabetes, cardiovascular conditions, and cancer, is significantly driving the demand for medications. For instance, the CDC estimates that six in ten adults in the United States currently live with a chronic disease such as cancer, heart disease, or diabetes. As more individuals manage these conditions with prescribed treatments, there is a heightened need for effective pharmacovigilance to monitor medication safety. Rigorous safety monitoring becomes crucial to detect and address adverse drug reactions (ADRs), ensuring that the therapeutic benefits of medications outweigh potential risks. The increased reliance on drugs to manage chronic health issues underscores the necessity for comprehensive surveillance systems to safeguard patient well-being.
Rising Drug Development and Approval Rates
The pharmaceutical industry is experiencing a surge in drug innovation, with new medications continuously entering the market. For example, the Food and Drug Administration (FDA) approved 38 new drugs per year from 2010 through 2019, which is 60 percent more than the yearly average over the previous decade. This trend necessitates robust pharmacovigilance services to verify the safety and efficacy of these new drugs. Stringent regulatory frameworks mandate extensive pharmacovigilance activities as part of the drug approval process and ongoing post-market surveillance. As drug development accelerates, the need for thorough monitoring systems becomes more critical to comply with regulatory standards and ensure patient safety throughout the drug lifecycle.
Increasing Regulatory Scrutiny
Health authorities globally are imposing more stringent regulations on drug safety, compelling pharmaceutical companies to invest in comprehensive pharmacovigilance systems. This increased regulatory scrutiny is driven by a heightened focus on ensuring that drugs do not pose unforeseen risks to patients. Additionally, growing public awareness and concern about drug safety issues have intensified pressure on regulatory bodies to enforce rigorous safety standards. Companies must navigate this complex regulatory environment to maintain compliance and uphold their commitment to patient safety.
Advancements in Technology
Technological advancements, particularly in data analytics and artificial intelligence, are transforming the pharmacovigilance landscape. Big data analytics enables faster and more accurate identification of ADRs, enhancing the efficiency of safety monitoring processes. Moreover, the proliferation of digital health technologies, such as wearable devices and electronic health records, provides valuable data that supports pharmacovigilance efforts. These innovations facilitate more proactive and precise safety assessments, contributing to improved drug safety outcomes and advancing the field of pharmacovigilance.
Market Trends
Digital Transformation and Technological Advancements
The landscape of pharmacovigilance is being significantly reshaped by digital transformation, driven by the increasing availability of big data from various sources, including electronic health records, claims databases, and social media. For instance, the landscape of pharmacovigilance is being significantly reshaped by digital transformation, driven by the increasing availability of big data from various sources. These data-rich environments are enabling more sophisticated, data-driven insights into drug safety. Advanced analytics tools, powered by artificial intelligence (AI) and machine learning, are now being utilized to identify safety signals, predict adverse events, and optimize pharmacovigilance processes. AI algorithms analyze vast amounts of data to uncover patterns and predict potential risks, leading to more proactive safety measures and streamlined monitoring operations. This technological evolution is enhancing the accuracy and efficiency of pharmacovigilance, ensuring a more robust approach to drug safety.
Outsourcing Trends and Risk-Based Approaches
In response to the growing complexity of pharmacovigilance requirements, pharmaceutical companies are increasingly outsourcing these activities to specialized service providers. This trend is driven by the need to leverage external expertise and reduce operational costs. Outsourcing allows companies to tap into specialized knowledge and advanced technologies that may not be available in-house. Additionally, strategic partnerships between pharmaceutical companies, technology providers, and regulatory bodies are becoming more prevalent, aimed at addressing complex pharmacovigilance challenges collaboratively. Concurrently, the adoption of risk-based pharmacovigilance (RBPV) is gaining traction, focusing resources on drugs with higher safety risks. RBPV enhances efficiency and effectiveness by prioritizing safety monitoring based on the risk profile of various medications. This approach emphasizes proactive monitoring and risk mitigation strategies, improving overall drug safety and regulatory compliance.
Market Challenges Analysis
Data Quality, Completeness, and Privacy Concerns
A major challenge in pharmacovigilance is ensuring high data quality and completeness. Variability in data sources, including electronic health records, claims databases, and social media, can result in discrepancies in data quality and completeness. For instance, in the realm of data quality and completeness, a study titled “Pharmacovigilance in the Era of Big Data: Challenges and Opportunities” highlighted that one of the major challenges in leveraging big data for pharmacovigilance is ensuring data quality and reliability. Incomplete or missing data can significantly impede the identification and analysis of safety signals, leading to potential gaps in drug safety monitoring. Additionally, maintaining data privacy and security is paramount, as pharmacovigilance activities must adhere to stringent regulations such as GDPR and HIPAA. The risk of data breaches and unauthorized access to sensitive patient information poses a constant threat, necessitating robust security measures and compliance practices.
Global Harmonization and Technological Adoption Challenges
Efforts to harmonize pharmacovigilance regulations across different regions face challenges due to regulatory differences between countries. These discrepancies can complicate global safety monitoring and data sharing, as legal and technical barriers may hinder efficient cross-border data exchange. Furthermore, the adoption of emerging technologies, such as artificial intelligence and big data analytics, presents its own set of difficulties. Implementing these advanced technologies can be costly and require specialized technical expertise. Additionally, ethical considerations surrounding data privacy, bias, and transparency must be addressed to ensure responsible use of these technologies. Resource constraints, including budget limitations and a shortage of skilled professionals, exacerbate these challenges, making it difficult for pharmaceutical companies to invest in and maintain robust pharmacovigilance systems.
Market Segmentation Analysis:
By Product Life Cycle:
The Global Pharmacovigilance Market is segmented based on the product life cycle stages, including Pre-clinical, Phase I, Phase II, Phase III, and Phase IV. Each phase requires distinct pharmacovigilance activities to ensure drug safety and efficacy. The Pre-clinical phase involves initial safety assessments and toxicity studies before human trials. In Phase I, pharmacovigilance focuses on early safety data from a small group of healthy volunteers or patients. Phase II extends to a larger patient population to further assess safety and efficacy. The critical Phase III involves large-scale trials to confirm the drug's benefit-risk profile. Finally, Phase IV, or post-marketing surveillance, continues safety monitoring after the drug's release, addressing long-term effects and rare adverse events.
By Type:
The market also segments based on reporting and monitoring types: Spontaneous Reporting, Intensified ADR Reporting, Targeted Spontaneous Reporting, Cohort Event Monitoring, and EHR Mining. Spontaneous Reporting is the traditional method where healthcare professionals report adverse drug reactions voluntarily. Intensified ADR Reporting involves proactive measures to capture more detailed safety data. Targeted Spontaneous Reporting focuses on specific drugs or patient groups. Cohort Event Monitoring tracks safety across predefined patient groups, while EHR Mining leverages electronic health records for real-time data analysis. Each type offers unique insights and enhances the overall safety monitoring process, catering to various regulatory and research needs.
Segments:
Based on Product Life Cycle:
- Pre-clinical
- Phase I
- Phase II
- Phase III
- Phase IV
Based on Type:
- Spontaneous Reporting
- Intensified ADR Reporting
- Targeted Spontaneous Reporting
- Cohort Event Monitoring
- EHR Mining
Based on Service Provider:
- In-house
- Contract Outsourcing
Based on End-use:
- Pharmaceuticals
- Biotechnology Companies
- Medical Device Manufacturers
- Others
Based on Process Flow:
- Case Data Management
- Case Logging
- Case Data Analysis
- Medical Reviewing & Reporting
- Signal Detection
- Adverse Event Logging
- Adverse Event Analysis
- Adverse Event Review & Reporting
- Risk Management System
- Risk Evaluation System
- Risk Mitigation System
Based on Therapeutic Area:
- Oncology
- Neurology
- Cardiology
- Respiratory Systems
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America commands a substantial market share of approximately 40% in the global pharmacovigilance industry. This leadership position stems from the region's robust pharmaceutical and biotechnology sectors, stringent regulatory environment, and advanced healthcare infrastructure. The United States, in particular, drives much of North America's market growth, hosting numerous pharmaceutical giants, contract research organizations, and innovative biotech firms. These entities leverage cutting-edge technologies, including artificial intelligence and big data analytics, to enhance drug safety monitoring and adverse event reporting. North American pharmacovigilance practices benefit from significant investment in research and development, as well as a highly skilled workforce trained in the latest safety monitoring methodologies. The region's market is characterized by a strong emphasis on post-marketing surveillance and real-world evidence gathering, driven by regulatory requirements and a growing focus on patient-centric healthcare.
Europe
Europe holds a significant market share of about 30% in the global pharmacovigilance sector, demonstrating a commitment to drug safety and regulatory excellence. Countries like Germany, the United Kingdom, and Switzerland lead the European market, benefiting from a well-established pharmaceutical industry and harmonized regulatory framework under the European Medicines Agency (EMA). European pharmacovigilance practices are distinguished by their comprehensive approach, encompassing both traditional and innovative methods of safety signal detection. The region excels in developing and implementing risk management plans, with a particular focus on proactive safety measures throughout the drug lifecycle. Europe's pharmacovigilance market also benefits from strong collaboration between academic institutions, healthcare providers, and pharmaceutical companies, fostering the development of novel pharmacovigilance strategies. The continent's emphasis on data privacy and security, exemplified by regulations like GDPR, has led to the creation of robust systems for handling sensitive patient information in pharmacovigilance activities.
Key Player Analysis
- Accenture
- IQVIA Inc.
- Cognizant
- Clinquest Group B.V. (Linical Americas)
- IBM
- Laboratory Corporation of America Holdings
- ArisGlobal
- Capgemini
- ITClinical
- ICON plc.
- TAKE Solutions Limited
- Parexel International (MA) Corporation
- Wipro
- United BioSource LLC
- BioClinica Inc. (Clario)
- ClinChoice (formerly FMD K&L)
Competitive Analysis
The Global Pharmacovigilance Market is highly competitive, with key players including Accenture, IQVIA Inc., Cognizant, ICON plc., Clinquest Group B.V. (Linical Americas), and Parexel International (MA) Corporation. These leading firms leverage their extensive industry experience and technological expertise to offer comprehensive pharmacovigilance solutions. They are continuously enhancing their service portfolios by incorporating advanced technologies like artificial intelligence and big data analytics to improve drug safety and regulatory compliance. The market competition is driven by their innovation in risk management, data analysis, and regulatory adherence, positioning them to effectively meet the increasing demand for robust pharmacovigilance systems across various therapeutic areas. Their strategic initiatives, including mergers and acquisitions, further strengthen their market position and operational capabilities.
Recent Developments
- In January 2024, Accenture made a strategic investment in QuantHealth, an AI-powered clinical trial design company that simulates clinical trials in the cloud.
- In August 2024, Cognizant completed its acquisition of Belcan, a global supplier of Engineering Research & Development (ER&D) services.
- In 2024, IQVIA released a white paper discussing the impact of AI and regulatory changes on the pharmaceutical industry, with insights on the role of Generative AI in drug development and pharmacovigilance.
- In March 2024, ArisGlobal announced three cutting-edge product offerings that will transform pharmacovigilance and regulatory operations.
Market Concentration & Characteristics
The Global Pharmacovigilance Market exhibits moderate to high market concentration, with a few leading players dominating the landscape. Major firms such as Accenture, IQVIA Inc., and Cognizant significantly influence market dynamics through their extensive service offerings and advanced technological capabilities. The market is characterized by a blend of established multinational corporations and specialized service providers, contributing to a competitive environment. Key characteristics include a focus on integrating cutting-edge technologies like artificial intelligence and big data analytics into pharmacovigilance processes to enhance safety monitoring and regulatory compliance. Companies are also increasingly adopting outsourcing strategies to leverage specialized expertise and reduce operational costs. This concentration and specialization drive continuous innovation and improvements in drug safety management, ensuring that pharmacovigilance practices align with evolving regulatory standards and industry demands.
Report Coverage
The research report offers an in-depth analysis based on Product Life Cycle, Type, Service Provider, End-use, Process Flow, Therapeutic Area and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Pharmacovigilance Market is expected to grow significantly as the demand for comprehensive drug safety monitoring intensifies.
- Advancements in artificial intelligence and machine learning will increasingly drive efficiency in adverse event detection and analysis.
- The integration of big data analytics will enhance the ability to identify and manage safety signals more effectively.
- Regulatory pressures will continue to escalate, pushing companies to adopt more robust and compliant pharmacovigilance systems.
- The rise of digital health technologies will provide valuable data sources, contributing to improved pharmacovigilance practices.
- Outsourcing pharmacovigilance activities will become more prevalent as companies seek cost-effective and specialized services.
- Increased global collaboration will facilitate better data sharing and harmonization of pharmacovigilance practices across different regions.
- The growing emphasis on patient-centric approaches will drive more proactive safety monitoring and reporting.
- Emerging markets will present new opportunities and challenges as regulatory frameworks and industry practices evolve.
- Continuous innovation and adaptation to evolving technologies and regulations will be critical for maintaining effective drug safety management.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of Chronic Diseases
The rising incidence of chronic diseases such as diabetes, cardiovascular conditions, and cancer is driving the need for more medications, which in turn increases the demand for robust pharmacovigilance systems to monitor and ensure drug safety.
Rising Drug Development and Approval Rates
A surge in pharmaceutical innovation and the accelerated approval of new drugs require comprehensive pharmacovigilance to monitor safety and efficacy, both during clinical trials and after market launch.
Increasing Regulatory Scrutiny
Global health authorities are imposing stricter regulations on drug safety, compelling pharmaceutical companies to invest in advanced pharmacovigilance systems to maintain compliance and protect patient safety.
Advancements in Technology
The integration of artificial intelligence, big data analytics, and digital health technologies is transforming pharmacovigilance by enabling faster, more accurate detection of adverse drug reactions and improving overall safety monitoring processes.
Growth in Outsourcing and Specialized Services
Pharmaceutical companies are increasingly outsourcing pharmacovigilance activities to specialized service providers to access advanced expertise and technologies, reduce operational costs, and efficiently manage complex regulatory requirements.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Pharmacovigilance Market?
What factors are driving the growth of the Global Pharmacovigilance Market?
What are the key segments within the Global Pharmacovigilance Market?
What are some challenges faced by the Global Pharmacovigilance Market?
Who are the major players in the Global Pharmacovigilance Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Spontaneous Reporting
- 1.2.2 Intensified ADR Reporting
- 1.2.3 Targeted Spontaneous Reporting
- 1.2.4 Cohort Event Monitoring
- 1.2.5 EHR Mining
- 1.3 By End-use
- 1.3.1 Pharmaceuticals
- 1.3.2 Biotechnology Companies
- 1.3.3 Medical Device Manufacturers
- 1.3.4 Others
- 1.4 By Service Provider
- 1.4.1 In-house
- 1.4.2 Contract Outsourcing
- 1.5 By Product Life Cycle
- 1.5.1 Pre-clinical
- 1.5.2 Phase I
- 1.5.3 Phase II
- 1.5.4 Phase III
- 1.5.5 Phase IV
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 9,574.26 million → 2032: USD 18,325.43 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Pharmacovigilance Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Pharmacovigilance Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Pharmacovigilance Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Pharmacovigilance Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Pharmacovigilance Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Pharmacovigilance Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Pharmacovigilance Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Pharmacovigilance Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 9,574.26 million → 2032: USD 18,325.43 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Pharmacovigilance Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Spontaneous Reporting
- 12.3.7.2 Intensified ADR Reporting
- 12.3.7.3 Targeted Spontaneous Reporting
- 12.3.7.4 Cohort Event Monitoring
- 12.3.7.5 EHR Mining
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-use - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pharmaceuticals
- 12.4.7.2 Biotechnology Companies
- 12.4.7.3 Medical Device Manufacturers
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Service Provider - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 In-house
- 12.5.7.2 Contract Outsourcing
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Life Cycle - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Pre-clinical
- 12.6.7.2 Phase I
- 12.6.7.3 Phase II
- 12.6.7.4 Phase III
- 12.6.7.5 Phase IV
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Pharmacovigilance End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Pharmacovigilance Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Pharmacovigilance Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Pharmacovigilance Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Accenture
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 IQVIA Inc.
- 18.4 Cognizant
- 18.5 ICON plc.
- 18.6 Parexel International (MA) Corporation
- 18.7 ArisGlobal
- 18.8 Laboratory Corporation of America Holdings
- 18.9 Wipro
- 18.10 Capgemini
- 18.11 BioClinica Inc. (Clario)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

