
Market Overview:
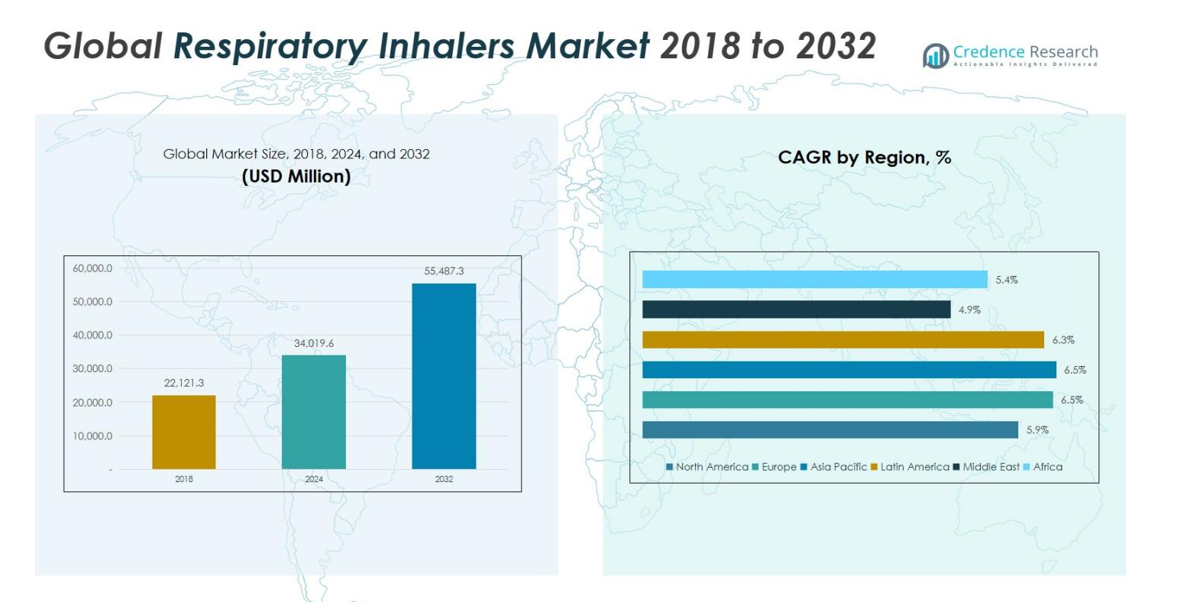
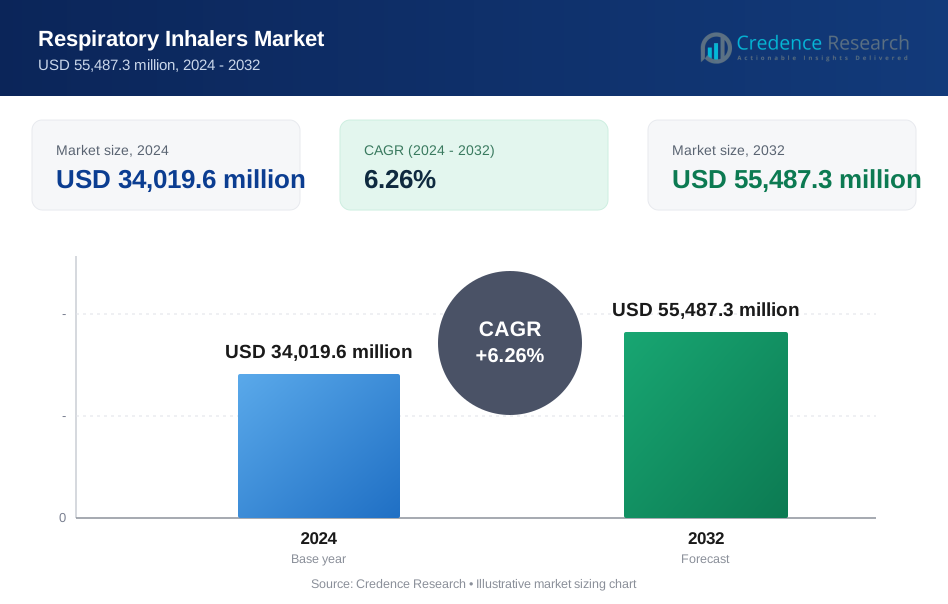
The Respiratory Inhalers Market size was valued at USD 22,121.3 million in 2018 and USD 34,019.6 million in 2024, and it is anticipated to reach USD 55,487.3 million by 2032, growing at a CAGR of 6.26% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Respiratory Inhalers Market Size 2024 | USD 34,019.6 million |
| Respiratory Inhalers Market, CAGR | 6.26% |
| Respiratory Inhalers Market Size 2032 | USD 55,487.3 million |
The Respiratory Inhalers Market is dominated by key players including GlaxoSmithKline plc, AstraZeneca plc, Boehringer Ingelheim GmbH, Teva Pharmaceutical Industries Ltd., and Cipla Ltd., which maintain strong global presence through robust product portfolios, continuous R&D investment, and strategic collaborations. These companies focus on developing advanced inhaler technologies, including digital and breath-actuated devices, to improve patient adherence and clinical outcomes. Asia Pacific emerges as the leading region, capturing 32.6% of the global market share in 2024, driven by rising prevalence of respiratory disorders, urbanization, and improved healthcare access in countries like China, India, and Japan. The combination of technological innovation, regional demand, and expanding healthcare infrastructure positions these top players to maintain competitive dominance while capitalizing on growth opportunities in emerging markets.
Market Insights
- The Respiratory Inhalers Market was valued at USD 34,019.6 million in 2024 and is projected to reach USD 55,487.3 million by 2032, growing at a CAGR of 6.26%. Metered Dose Inhalers (MDIs) dominate the product segment with 47% market share, while asthma leads the application segment with 66% share.
- Market growth is driven by the rising prevalence of asthma, COPD, and other chronic respiratory diseases, coupled with increasing air pollution, smoking rates, and awareness of early respiratory disease management.
- Key trends include the adoption of digital and connected inhalers for adherence monitoring and personalized care, along with development of eco-friendly and propellant-free inhalers to meet sustainability goals.
- Competitive analysis highlights top players such as GlaxoSmithKline plc, AstraZeneca, Boehringer Ingelheim, Teva Pharmaceutical, and Cipla, focusing on R&D, digital innovations, and strategic collaborations to strengthen global presence.
- Regional analysis shows Asia Pacific leading with 6% market share, followed by Europe and North America, supported by urbanization, improved healthcare infrastructure, and increasing patient awareness.
Market Segmentation Analysis:
By Product
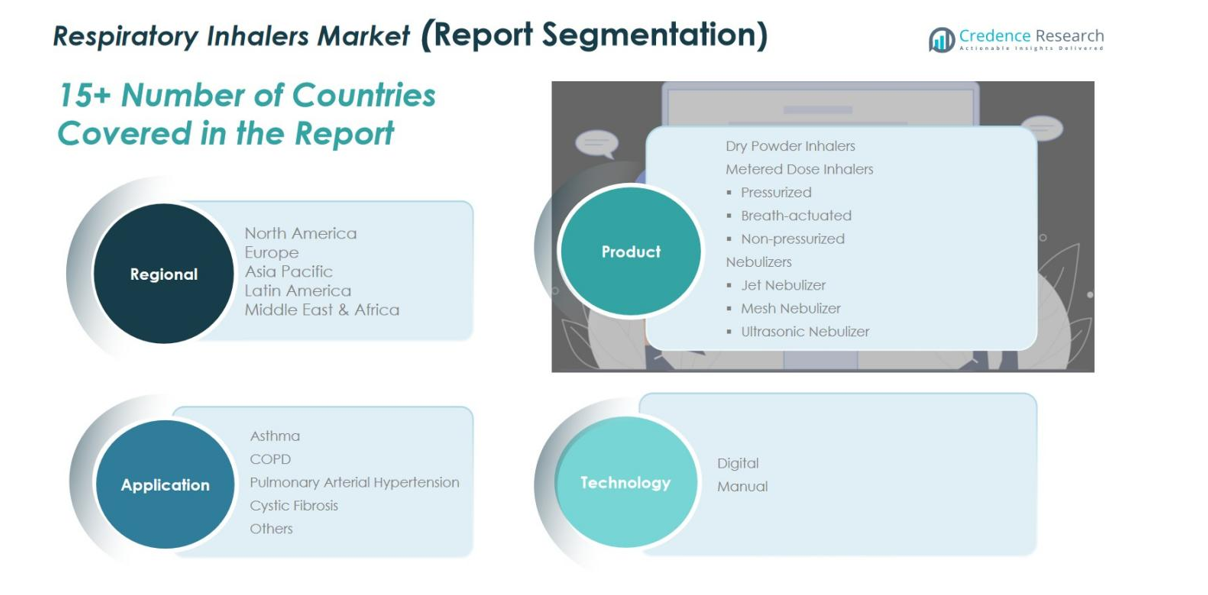
The Metered Dose Inhalers (MDIs) segment dominates the Respiratory Inhalers Market, accounting for around 47% of the total share in 2024. MDIs remain the preferred choice due to their affordability, consistent drug delivery, and broad availability across healthcare settings. Within this category, pressurized MDIs hold the largest sub-segment share, supported by robust clinical usage and established distribution channels. Growth is further driven by rising asthma and COPD prevalence and advancements in breath-actuated and digital-enabled devices designed to enhance patient adherence and minimize coordination challenges.
- For instance, Teva Pharmaceuticals’ FDA-approved QVAR® RediHaler™ breath-actuated inhaler eliminates hand-breath coordination challenges, enhancing ease of use for asthma patients.
By Application
The Asthma segment leads the market, contributing approximately 66% of total revenue in 2024, followed by Chronic Obstructive Pulmonary Disease (COPD). The dominance of asthma applications stems from its global prevalence and the necessity for long-term inhalation therapy. Increasing air pollution levels, smoking rates, and awareness of early respiratory disease management continue to propel inhaler adoption. Meanwhile, growing use of inhalers for COPD management and expanding therapeutic applications in cystic fibrosis and pulmonary arterial hypertension further strengthen overall market penetration.
- For instance, GlaxoSmithKline's Trelegy inhaler, prescribed for both asthma and COPD, saw a 26% sales growth in 2024 due to rising patient demand and market share gains.
By Technology
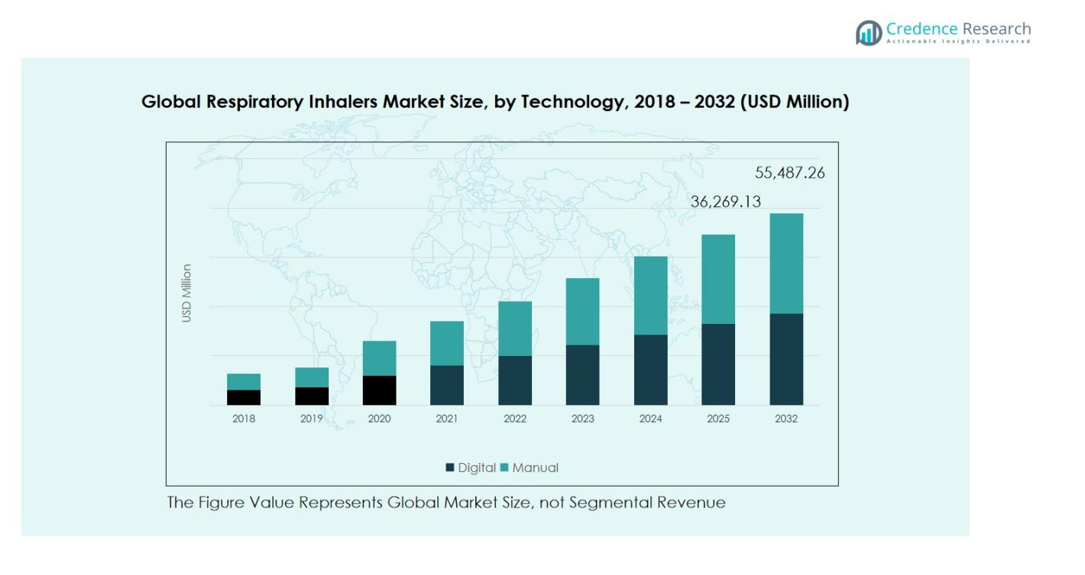
The Manual inhalers segment currently holds the largest share, accounting for nearly 50% of the market, attributed to their affordability, ease of use, and accessibility across both developed and emerging regions. However, the Digital inhalers sub-segment is the fastest-growing category, driven by the integration of smart sensors, Bluetooth connectivity, and adherence monitoring technologies. Growing emphasis on personalized medicine, remote patient management, and data-driven treatment optimization is expected to accelerate digital inhaler adoption, reshaping future market dynamics.
Key Growth Drivers
Rising Prevalence of Respiratory Disorders
The increasing incidence of asthma, COPD, and other chronic respiratory diseases is a major growth driver for the respiratory inhalers market. Rising air pollution, urbanization, and tobacco consumption have intensified the global burden of these conditions. As healthcare systems emphasize early diagnosis and long-term management, the demand for efficient and portable inhalation devices continues to expand. Public health programs promoting awareness about respiratory care and improved access to treatment options are further accelerating inhaler adoption worldwide.
- For instance, Boehringer Ingelheim’s Respimat Soft Mist inhaler offers a propellant-free alternative with a slow-moving aerosol cloud, improving drug delivery and suitability for humid climates, thus expanding treatment options for asthma and COPD patients.
Technological Advancements in Inhaler Devices
Continuous innovation in inhaler technology, including digital inhalers with dose counters, Bluetooth connectivity, and adherence tracking, is reshaping market growth. These smart devices enhance treatment accuracy, enable remote monitoring, and support patient engagement-addressing long-standing challenges in medication compliance. Manufacturers are increasingly integrating advanced sensors and data analytics to personalize therapy. Such technological improvements not only improve clinical outcomes but also create opportunities for value-based healthcare partnerships and reimbursement support.
- For instance, Aptar Pharma has developed digital dose counting inhalers with integrated sensors that provide real-time dose tracking and reminders, improving medication adherence in asthma and COPD patients.
Expansion of Home Healthcare and Self-Management Solutions
The global shift toward home healthcare is fueling the adoption of respiratory inhalers, particularly among the elderly and patients with chronic illnesses. Portable and user-friendly inhalers allow patients to manage conditions such as asthma and COPD independently, reducing hospital visits and overall treatment costs. The COVID-19 pandemic accelerated this trend, prompting healthcare providers to endorse home-based respiratory therapies. The growing preference for self-administered, cost-effective treatment options continues to strengthen market expansion.
Key Trends & Opportunities
Emergence of Digital and Connected Inhalers
The integration of connectivity features within inhaler systems has created a transformative opportunity for the market. Digital inhalers record inhalation data, monitor dosage adherence, and transmit information to healthcare providers in real time. This capability supports telehealth and remote patient management, offering improved disease control and reduced healthcare costs. Partnerships between medical device companies and digital health firms are further expanding this trend, creating a data-driven ecosystem for respiratory care management.
- For instance, Phillips Medisize has developed add-on sensing devices and integrated sensors that share real-time medication usage data across multiple healthcare providers, facilitating earlier intervention and more efficient disease management.
Sustainability and Eco-Friendly Product Development
Growing environmental concerns are driving manufacturers to develop propellant-free and recyclable inhalers. Regulatory pressure to reduce greenhouse gas emissions from hydrofluorocarbon-based inhalers has accelerated the transition toward sustainable alternatives, such as dry powder inhalers and eco-friendly propellants. This trend not only aligns with global sustainability goals but also enhances brand image and compliance readiness for manufacturers. Companies focusing on green innovation are gaining a competitive edge and expanding market presence across environmentally conscious regions.
- For instance, GSK is advancing a low carbon Ventolin inhaler that uses an innovative, low carbon propellant to reduce greenhouse gas emissions, with phase III clinical trials underway and commercial production planned at its Evreux facility in France.
Key Challenges
Stringent Regulatory Requirements and Approval Delays
The respiratory inhalers market faces challenges due to complex regulatory frameworks governing device safety, efficacy, and environmental compliance. Frequent updates in emission standards and inhalation drug formulations extend approval timelines and increase development costs. Manufacturers must adhere to evolving guidelines from agencies like the FDA and EMA, which can delay product launches and restrict market entry. These stringent regulatory processes often hinder innovation speed and limit smaller players from competing effectively.
Patient Adherence and Technique Limitations
Despite technological advancements, improper inhaler use and poor adherence remain persistent challenges in respiratory care. Many patients struggle with coordination, incorrect dosage, or inconsistent device maintenance, leading to suboptimal treatment outcomes. Lack of adequate training and awareness among users, especially in low-income regions, exacerbates this issue. To overcome this challenge, manufacturers and healthcare providers must focus on patient education, smart inhaler design, and adherence-monitoring technologies to ensure effective drug delivery and long-term disease control.
Regional Analysis
North America
North America holds a leading position in the global respiratory inhalers market due to advanced healthcare infrastructure and high disease awareness. The regional market was valued at USD 5,236.10 million in 2018 and grew to USD 7,906.64 million in 2024, projected to reach USD 12,578.96 million by 2032, expanding at a CAGR of 5.9%. The region’s strong market share is driven by technological innovations in inhaler design and increased prevalence of asthma and COPD. The U.S. dominates this growth, supported by government programs promoting chronic disease management and adoption of digital inhalers.
Europe
Europe continues to maintain a strong share in the respiratory inhalers market, supported by well-established healthcare systems and aging demographics. The market was worth USD 5,851.07 million in 2018, rising to USD 9,107.53 million in 2024, and is forecasted to reach USD 15,092.53 million by 2032, at a CAGR of 6.5%. Key markets like Germany, the U.K., and France contribute significantly to regional expansion. Increasing respiratory disorder prevalence, along with sustainable inhaler innovations and favorable reimbursement policies, enhances Europe’s market outlook and reinforces its competitive position globally.
Asia Pacific
Asia Pacific commands the largest market share in the respiratory inhalers market, driven by urbanization, pollution, and healthcare advancements. The regional market increased from USD 7,105.35 million in 2018 to USD 11,093.30 million in 2024, and is projected to reach USD 18,455.06 million by 2032, growing at a CAGR of 6.5%. Rising respiratory disease incidence in China, India, and Japan, coupled with improved healthcare access and awareness campaigns, drives demand. Increasing investment in digital healthcare technologies and local manufacturing further enhances affordability and accessibility of inhalation therapies.
Latin America
Latin America’s respiratory inhalers market shows steady progress, supported by healthcare modernization and increasing prevalence of respiratory illnesses. The market was valued at USD 2,384.67 million in 2018, reached USD 3,683.35 million in 2024, and is expected to attain USD 6,042.56 million by 2032, expanding at a CAGR of 6.3%. Brazil, Mexico, and Argentina lead regional demand through expanding healthcare infrastructure and public health initiatives. Growing awareness of chronic respiratory conditions and rising adoption of portable inhaler devices contribute to consistent market growth across the region.
Middle East
The Middle East respiratory inhalers market has been expanding gradually, supported by rising investments in healthcare infrastructure and awareness of respiratory care. The market size increased from USD 1,057.40 million in 2018 to USD 1,512.41 million in 2024, and is projected to reach USD 2,219.49 million by 2032, registering a CAGR of 4.9%. The Gulf Cooperation Council (GCC) countries dominate regional demand due to high asthma incidence and adoption of advanced medical technologies. Increasing healthcare spending and government-led screening programs are improving respiratory health outcomes and driving steady market penetration.
Africa
Africa’s respiratory inhalers market is expanding at a stable rate, driven by improved access to healthcare facilities and growing awareness of chronic respiratory diseases. Valued at USD 486.67 million in 2018, the market reached USD 716.36 million in 2024, and is projected to reach USD 1,098.65 million by 2032, with a CAGR of 5.4%. South Africa leads the market, supported by government health programs and the introduction of cost-effective generic inhalers. However, limited healthcare infrastructure in several African nations continues to constrain rapid growth, though ongoing international aid and partnerships are fostering improvement.
Market Segmentations:
Metered Dose Inhalers (MDIs)
- Pressurized
- Breath-actuated
- Non-pressurized
Nebulizers
- Jet Nebulizer
- Mesh Nebulizer
- Ultrasonic Nebulizer
By Application:
- Asthma
- Chronic Obstructive Pulmonary Disease (COPD)
- Pulmonary Arterial Hypertension
- Cystic Fibrosis
- Others
By Technology:
- Digital
- Manual
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the respiratory inhalers market features major players such as GlaxoSmithKline plc, AstraZeneca plc, Boehringer Ingelheim GmbH, Teva Pharmaceutical Industries Ltd., and Cipla Ltd. These companies dominate the market through strong product portfolios, extensive R&D investments, and strategic collaborations. Leading manufacturers are focusing on digital inhaler technologies, combination therapies, and patient-centric designs to enhance treatment adherence and clinical outcomes. For instance, companies are integrating smart sensors into inhalers for real-time monitoring and data analytics. Strategic mergers and acquisitions have also strengthened global presence, enabling access to emerging markets and advanced manufacturing capabilities. Furthermore, firms are emphasizing environmentally sustainable inhalers to comply with new regulatory standards on propellant use. The market competition remains intense, with innovation, pricing strategies, and expansion into developing economies serving as key differentiators among top players.
Key Player Analysis
- Boehringer Ingelheim GmbH
- AstraZeneca plc
- PARI Medical Holding
- Merck & Co., Inc.
- Teva Pharmaceutical Industries Ltd.
- Cipla Inc.
- GlaxoSmithKline plc
- Beximco Pharmaceuticals Ltd.
- NutraRespiro
- Wellona Pharma
Recent Developments
- In April 2024, Teva announced the discontinuation of the Digihaler product line due to commercial challenges.
- In 2023, AstraZeneca received FDA approval for Airsupra, a combination inhaler containing albuterol and budesonide for as-needed asthma treatment in adults, which became commercially available shortly after approval.
- In 2024, Aptar Pharma entered an exclusive agreement with Cambridge Healthcare Innovations to commercialize the Quattrii dry powder inhaler platform, aiming to provide a sustainable and cost-effective solution.
- In July 2025, Merck & Co. acquired Verona Pharma for approximately $10 billion, enhancing its portfolio with Verona's COPD drug, Ohtuvayre, approved in the U.S. in 2024
Report Coverage
The research report offers an in-depth analysis based on Product, Application, Technology and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The respiratory inhalers market is expected to continue growing steadily due to rising prevalence of chronic respiratory diseases.
- Increasing adoption of digital and smart inhaler technologies will enhance patient adherence and remote monitoring.
- Growth in home healthcare and self-management solutions will expand demand for portable and user-friendly inhalers.
- Technological innovations in propellant-free and eco-friendly inhalers will support sustainable market development.
- Emerging markets in Asia Pacific and Latin America will offer significant growth opportunities.
- Expansion of combination therapies and advanced formulations will drive clinical adoption.
- Regulatory focus on environmental sustainability will encourage development of greener inhaler options.
- Strategic collaborations, mergers, and acquisitions will strengthen global market presence for key players.
- Awareness campaigns and government programs for asthma and COPD management will increase market penetration.
- Integration of digital health platforms and telemedicine will further transform inhaler usage and patient care.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Respiratory Disorders
Increasing incidence of asthma, COPD, and other chronic respiratory diseases - driven by air pollution, urbanization, and tobacco use - is expanding the patient pool requiring inhalation therapy, directly boosting demand for respiratory inhalers.
Technological Advancements in Inhaler Devices
Continuous innovation, such as the integration of digital sensors, Bluetooth connectivity, and adherence monitoring, is making inhalers more effective and user-friendly, encouraging both clinicians and patients to adopt newer devices.
Expansion of Home Healthcare and Self-Management
The shift toward home-based care and self-management, especially post-pandemic, is increasing the uptake of portable and easy-to-use inhalers, reducing hospital visits and supporting chronic disease management outside clinical settings.
Sustainability and Eco-Friendly Product Development
Regulatory pressure and environmental awareness are driving manufacturers to develop propellant-free and recyclable inhalers, which not only meet compliance requirements but also appeal to environmentally conscious consumers and healthcare systems.
Improved Healthcare Access in Emerging Markets
Rapid urbanization, rising healthcare investment, and awareness campaigns in regions like Asia Pacific and Latin America are making inhalers more accessible, fueling market growth in these high-population areas.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Respiratory Inhalers Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Respiratory Inhalers Market projected to grow between 2025 and 2032?
Which Respiratory Inhalers Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Respiratory Inhalers Market?
Who are the major players in this market?
Which region commanded the largest share of the Respiratory Inhalers Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Metered Dose Inhalers (MDIs)
- 1.2.2 Nebulizers
- 1.2.3 Dry Powder Inhalers (DPIs)
- 1.2.4 Soft Mist Inhalers
- 1.3 By Technology
- 1.3.1 Manual
- 1.3.2 Digital
- 1.4 By Application
- 1.4.1 Asthma
- 1.4.2 Chronic Obstructive Pulmonary Disease (COPD)
- 1.4.3 Pulmonary Arterial Hypertension
- 1.4.4 Cystic Fibrosis
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 34,019.6 million → 2032: USD 55,487.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Respiratory Inhalers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Respiratory Inhalers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Respiratory Inhalers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Respiratory Inhalers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Respiratory Inhalers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Respiratory Inhalers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Respiratory Inhalers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Respiratory Inhalers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 34,019.6 million → 2032: USD 55,487.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Respiratory Inhalers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Metered Dose Inhalers (MDIs)
- 12.3.7.2 Nebulizers
- 12.3.7.3 Dry Powder Inhalers (DPIs)
- 12.3.7.4 Soft Mist Inhalers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Manual
- 12.4.7.2 Digital
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Asthma
- 12.5.7.2 Chronic Obstructive Pulmonary Disease (COPD)
- 12.5.7.3 Pulmonary Arterial Hypertension
- 12.5.7.4 Cystic Fibrosis
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Respiratory Inhalers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Respiratory Inhalers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Respiratory Inhalers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Respiratory Inhalers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 GlaxoSmithKline plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 AstraZeneca plc
- 18.4 Boehringer Ingelheim GmbH
- 18.5 Teva Pharmaceutical Industries Ltd.
- 18.6 Cipla Ltd.
- 18.7 Merck & Co., Inc.
- 18.8 PARI Medical Holding
- 18.9 Beximco Pharmaceuticals Ltd.
- 18.10 Aptar Pharma
- 18.11 Wellona Pharma
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

