
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Actinic Keratosis Market Size 2023 | USD 6514.2 Million |
| Actinic Keratosis Market , CAGR | 4.80% |
| Actinic Keratosis Market Size 2032 | USD 9933.73 Million |
Market Insights
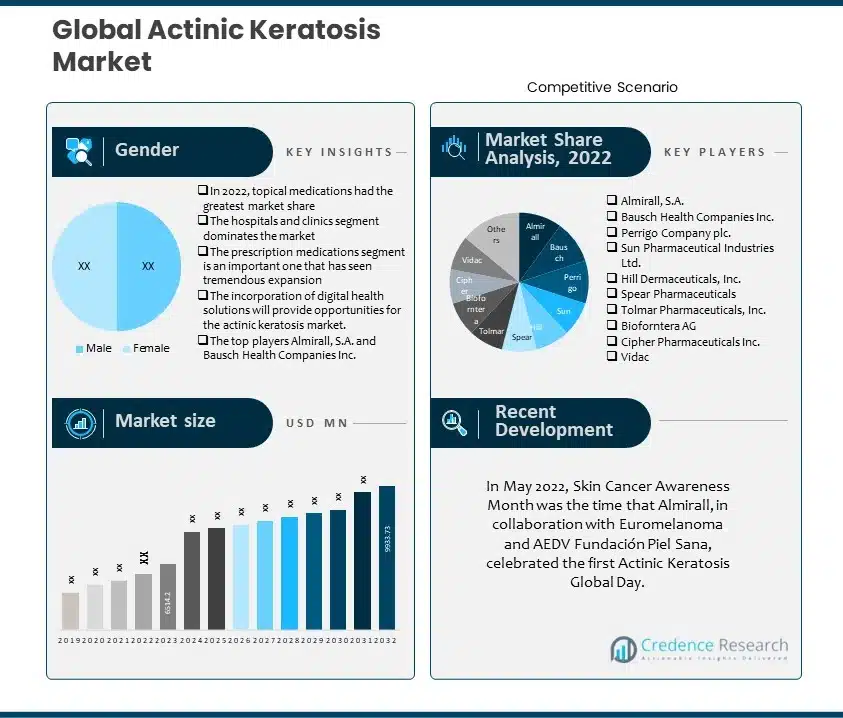
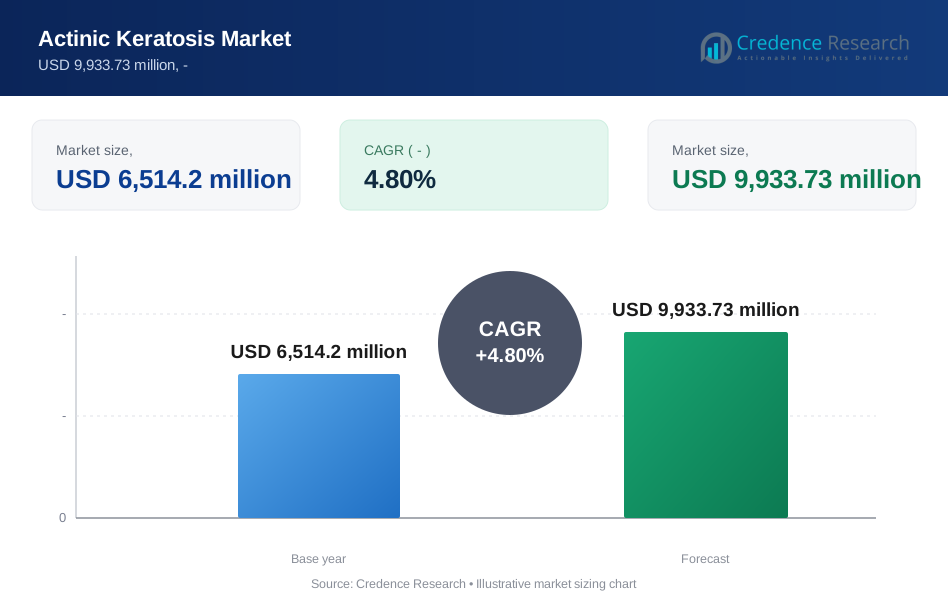
- The global market for actinic keratosis is expected to grow from its estimated USD 6514.2 million in 2023 to USD 9933.73 million in 2032 at a compound annual growth rate (CAGR) of 4.80% between 2024 and 2032.
- The largest treatment type category is topical medications. On the other hand, photodynamic therapy (PDT) is expected to grow at a strong CAGR.
- The leading distribution channel segment is hospitals and clinics.
- The CAGR for prescription medications is expected to be the highest during the projection period.
- The outpatient treatment will have the highest CAGR throughout the prediction period.
- The adult age group is estimated to have the greatest CAGR during the forecast period.
- The male category is predicted to grow fastest over the projection period.
- North America dominated the actinic keratosis market.
- Regarding the market share of actinic keratosis, Europe is expected to come second.
- In the actinic keratosis market, Asia Pacific is anticipated to grow fastest.
- The most significant factors supporting the market include expanding actinic keratosis frequency, rising desire for minimally invasive procedures, and expanding research and development for new treatment developments.
- The actinic keratosis market is driven by factors such as the expansion of treatment options, the emergence of targeted therapies, the incorporation of digital health solutions, and the exploration of nutritional supplements.
Executive Summary
Market Definition
The actinic keratosis market is the pharmaceutical and healthcare sector area dedicated to actinic keratosis (AK) diagnosis, treatment, and management. An aberrant cell growth brought on by chronic UV exposure is known as actinic keratosis. By freezing them with liquid nitrogen, actinic keratoses can be eliminated. The application of cryotherapy is advised for the treatment of individual AK lesions. On the other hand, topical medical therapies, also known as field therapy, are utilized to treat several lesions on a single sun-damaged area, with the added benefit of emphasizing and treating invisible lesions.
Market Overview
The actinic keratosis sector is estimated to develop at a 4.80% compound annual growth rate (CAGR) between 2024 and 2032, maintaining its current upward trend. The market will keep developing, rising from its estimated value of USD 6514.2 million in 2023 to USD 9933.73 million in 2032.
Some primary factors contributing to the market include escalating actinic keratosis occurrence, climbing interest in minimally invasive operations, and improving research and development for fresh treatment advancements. As per the April 2022 publication in the Indian Journal of Dermatology, actinic keratosis is an often observed symptom in the outpatient context, with over 10% of dermatology visits resulting in a diagnosis. In the United Kingdom, actinic keratosis lesions affect 15%–23% of the population; among those over 50, this number rises to 37.5%. This will probably boost the uptake of current treatments and promote early disease detection. Additionally, a June 2022 MDPI paper states that 5-aminolevulinic acid (5-ALA) photodynamic therapy (PDT) is a newly available therapeutic option for actinic keratosis. Throughout the projected period, the rise in minimally invasive treatments like photodynamic therapy brought about by the rise in actinic keratosis prevalence is anticipated to support the market expansion.
The significant market participants' most recent product launches also contribute to the market's expansion. For example, Biofrontera Inc. initiated a multicenter, randomized, double-blind, vehicle-controlled Phase 3 clinical research in November 2022 to assess the safety and effectiveness of Ameluz and BF-RhodoLED XL in the field-directed therapy for actinic keratosis (AK) on the trunk, neck, and extremities. Moreover, Almirall, S.A. introduced Klisyri (tirbanibulin) in Germany and the United Kingdom in September 2021. The Medicines & Healthcare Products Regulatory Agency (MHRA) in the United Kingdom and the European Commission approved the medicine before it may be sold to people with actinic keratosis of the scalp and face.
Segmentation by Treatment Type
- Based on the kind of treatment, topical medications lead the market. Topical medications are administered topically (to the skin or eyes) to produce the intended local therapeutic effect. Considering how efficiently the skin acts as a barrier, topical medicine administration is particularly stressful.
- The photodynamic therapy (PDT) category will exhibit a sizable CAGR during the projected period. The medical procedure known as photodynamic therapy uses a photosensitizing agent activated by light to target and kill aberrant cells. PDT is a viable therapeutic option for Actinic Keratosis (AK) to treat this precancerous skin condition.
- Other treatment types, including cryotherapy, laser therapy, and chemical peels, additionally support the need for actinic keratosis.
Segmentation by Distribution channel
- The main distribution channels are hospitals and clinics. Providing patients with prescribed medications, such as topical creams and ointments used in treating actinic keratosis, is a crucial function of hospitals and clinics offering pharmacy services in the actinic keratosis market.
- The dermatology centers category will likely register a significant CAGR during forecasting. A variety of treatment options are available for actinic keratosis at dermatology centers. Topical medicines, cryotherapy (freezing), laser therapy, photodynamic therapy, chemical peels, and surgical excision in certain situations are a few examples. The severity of AK, the patient's preferences, and other variables influence the treatment option.
- Other distribution channels, such as retail pharmacies and online retail, also contribute to the demand for actinic keratosis.
Segmentation by Prescription Status
- It is projected that the prescription medications category will grow at the fastest rate over the projection period. When it comes to treating actinic keratosis, prescription drugs are essential. Targeting and eliminating abnormal skin cells, which lowers the likelihood of skin cancer developing, is the aim of these medications.
- The need for actinic keratosis is also influenced by other prescription status, including over-the-counter (OTC) Products.
Segmentation by Patient Type
- The outpatient treatment category will likely have the highest CAGR during the projection period. Many non-residential treatments and initiatives are available for outpatient therapy to fulfill the patient's needs. In addition to individual and group counseling, family treatment, crisis intervention, patient education, case management, scheduling therapy, and discharge planning, they are all included in the services provided.
- Other patient type, such as self-administered treatment, also contribute to the demand for actinic keratosis.
Segmentation by Age Group
- The adults will be expected to have the foremost CAGR during the prediction period. Since actinic keratosis is primarily linked to cumulative sun damage, older people who have had years of prolonged sun exposure tend to have higher prevalence rates. The demographic most frequently impacted by this skin condition is reflected in the actinic keratosis market's focus on the adult age group.
- Other age groups, such as the elderly, also contribute to the demand for actinic keratosis.
Segmentation by Gender
- Males will be expected to have the foremost CAGR during the prediction period. The risk of developing AK is 2-3 times higher in men than in women. This could result from fewer sunscreen applications or increased sun exposure at work.
- Other genders, such as females, also contribute to the demand for actinic keratosis.
Segmentation by Region
- North America leads the actinic keratosis market. North America has a highly developed healthcare infrastructure, which includes research institutions, medical technologies, and well-developed healthcare systems. This promotes actinic keratosis early diagnosis, treatment, and detection, which propels market expansion.
- Europe is estimated to rank second in market size for actinic keratosis.
- Asia Pacific will witness the most rapid growth of the actinic keratosis market.
- The remaining requirement for actinic keratosis is covered by world regions such as Africa, the Middle East, and Latin America.
During the projected time, the global actinic keratosis market is anticipated to develop due to high treatment efficiency. Regulatory agencies' expanding approval of products to treat actinic keratosis is expected to encourage the global actinic keratosis market's expansion during the projected period.
Due to the rising incidence of actinic keratosis and the region's larger age demographic, North America is anticipated to account for an enormous portion of the global actinic keratosis market. For example, more than 54 million Americans over 65 live in the United States, making up 16.5% of the country's overall population, according to the 2021 America's Health Rankings data. By 2050, there will likely be 85.7 million adults in the country who are 65 years of age or older, according to projections. Furthermore, a Statistics Canada update indicates that in April 2022, 7.2 million Canadians were 65 years of age or older (19%), and 9.2 million were baby boomers (about 25%) in 2021. Furthermore, the World Bank estimated in January 2023 that 8.13% of Mexicans were 65 years of age or older in 2021.
Throughout the forecast, the actinic keratosis market in Asia-Pacific is anticipated to expand fastest. Actinic keratosis is becoming more common in the Asia-Pacific area as a result of various factors, including pollution from the environment, changing lifestyles, and increased sun exposure. Actinic keratosis treatments are, therefore, in higher demand. The actinic keratosis market is expanding due to an aging population in many Asia Pacific nations. Because actinic keratosis is more common in older people, its prevalence is predicted to increase with aging populations, propelling market growth. The Asia Pacific market has grown due to the availability of cutting-edge actinic keratosis treatment options like topical therapies, cryotherapy, photodynamic therapy, and laser therapy.
Key Highlights of the Report
The global actinic keratosis market is segmented by treatment type, distribution channel, prescription status, patient type, age group, gender, and region. As far as the treatment type is concerned, topical medications are the market spearhead. Hospitals and clinics are the top distribution channel segment. The prescription medications category is anticipated to increase at the highest CAGR throughout the projection period. The outpatient treatment industry will experience the highest CAGR during the forecast period. The actinic keratosis market is expanding mostly in North America.
The significant number of cases of actinic keratosis and the growing acceptance of minimally invasive techniques are the reasons behind the growth of the actinic keratosis market in the United Kingdom. Furthermore, most actinic keratoses are treated initially with minimally invasive operations. Several other factors will contribute to the market's development and enhance demand for actinic keratosis therapies, including affordable treatment options and favorable Medicaid and Medicare reimbursements.
North America is expected to account for the largest portion of the actinic keratosis market globally. The market continues to expand due to the participants' recent partnerships, launches, and activities. For example, Almirall introduced tirbanibulin (Klisyri, Almirall), a new microtubule inhibitor, to the US market in February 2021 for the topical treatment of actinic keratosis (AK) of the face and scalp. It is anticipated that this development will propel the Actinic Keratosis market's expansion in North America. The Asia Pacific region is also assumed to have the market's sharpest growth. Skin diseases such as actinic keratosis are becoming more common in the Asia Pacific area. The prevalence of actinic keratosis is on the rise due to factors like aging populations, population growth, and increased exposure to UV radiation.
Which Key Factors Are Driving The Global Actinic Keratosis Market?
The market for actinic keratosis is driven by several factors, including increased access to healthcare services, infrastructure improvements in the healthcare system, and growing awareness of how climate change affects skin health. The market is expanding steadily as a result of all these factors.
What Are The Main Challenges Confronting The Actinic Keratosis Market Globally?
Several factors, such as high treatment costs, limited access to healthcare in developing regions, limited funding for research, and complexity in disease management, impede the growth of the actinic keratosis industry.
What Market Opportunities Exist For Actinic Keratosis Globally?
The factors creating opportunities for the actinic keratosis market include the emergence of customized therapeutics, incorporation of digital health solutions, application of artificial intelligence, and support for skin cancer screening initiatives.
Market Drivers
Multiple factors propel the actinic keratosis industry across the globe. The primary factors propelling the global actinic keratosis market are as follows:
Increased Frequency of Actinic Keratosis
A significant market driver is the incidence of actinic keratosis. In Australian individuals over forty, actinic keratosis is prevalent in 37% to 55% of cases, according to a 2019 article published by News-Medical.net, an AZoNetwork site. The Australian population, which has relatively pale skin, is connected to increased UV exposure. Australia is known for its outdoor activities. Therefore, people there usually spend as much time in the sun as possible before playing games. Actinic keratosis is associated with various risk factors, including time spent in the sun and total sun exposure. Still, it is also suggested that men are more likely than women to get it. Furthermore, the nationwide incidence of actinic keratosis is estimated to be 10.2% in females and 26.5% in males in the United States and the United Kingdom, respectively.
The market for actinic keratosis is predicted to expand due to the condition's rising prevalence, growing awareness of illness treatment options, and growing demand for minimally invasive treatments. Actinic keratosis therapy is becoming more and more necessary as people become more aware of the negative consequences of the condition. Moreover, government and nonprofit awareness campaigns play a major role in the growth of the market. Increasing R&D efforts should also help expedite the approval of novel medications for the treatment of actinic keratosis. In addition, there is a higher frequency of detection and treatment due to the elevated risk of skin cancer associated with actinic keratosis.
Market Restraints
There are several obstacles that the global actinic keratosis market must overcome to continue growing. Among them are the following:
Low Treatment Uptake and a Shortage of Skilled Workers
The most significant obstacles hindering the market expansion for actinic keratosis are insufficient availability of qualified experts and restricted treatment uptake in developing nations. Treatment for actinic keratosis involves surgical and medical specialists performing procedures like photodynamic therapy, cryotherapy, and chemical peels. However, it is anticipated that a severe shortage of general surgeons will impede the market expansion for actinic keratosis. Furthermore, it is anticipated that greater treatment costs and a lack of knowledge about the health issue in less wealthy countries may restrict market expansion. The rise of substitute natural therapies is anticipated to impede the expansion of the industry.
Opportunities
There are plenty of potential prospects in the global actinic keratosis industry. Among these are the following:
An Increase in Medication Approvals and the Introduction of Innovative Treatments
The market for actinic keratosis will continue to grow due to more drug approvals and the release of innovative treatments for the condition. The US Food and Drug Administration (FDA) has granted approval for new medications to treat actinic keratoses. Topical fluorouracil, imiquimod, diclofenac, ingenol mebutate, and pharmacological therapy combinations are some of these medications. Due to their easy availability, strong target specificity, and low risk of scarring, topical medicines hold a significant market share in the actinic keratosis market and are predicted to show a similar trend over the projected period. Additionally, the industry is significantly influenced by the widespread use of combination treatments and possible pipeline medications. Increased use and monetization of innovative drugs are other factors anticipated to boost market growth. The market for actinic keratosis will likely develop due to enhanced R&D efforts, which are expected to accelerate the approval of innovative drugs for the condition.
Competitive Landscape
Key Players
There are several major competitors in the fiercely competitive global actinic keratosis market. The following are a few of the leading market participants and their market shares:
- Almirall, S.A.
- Bausch Health Companies Inc.
- Perrigo Company plc.
- Sun Pharmaceutical Industries Ltd.
- Hill Dermaceuticals, Inc.
- Spear Pharmaceuticals
- Tolmar Pharmaceuticals, Inc.
- Bioforntera AG
- Cipher Pharmaceuticals Inc.
- Vidac
- Athenex, Inc.
- 3M
- Mayne Pharma Group Limited
- Others
To remain competitive, these companies prioritize product innovation, distribution channel expansion, mergers, and acquisitions.
The largest suppliers in the global actinic keratosis market continuously work to keep one step beyond the competition by developing innovative concepts and products.
In December 2022, In Finland, Biofrontera AG introduced AMELUZ on a commercial basis. As part of traditional photodynamic therapy or as daylight therapy, this product launch can be used in accordance with the European approval for the treatment of actinic keratoses and basal cell carcinoma using the BF-RhodoLED lamp. The company was able to improve both its geographic presence in the European Union and its range of products thanks to this strategy.
In September 2022, Actinic keratosis KX01 license number Wei-Bu-Yao-Shu-Zi No. 028364 was approved by Taiwan's Ministry of Health and Welfare (MOHW) for PharmaEssentia Corporation as a new drug application.
Summary of Key Findings
- During the projected period, the growing elderly population globally is expected to support market expansion.
- The market is segmented by treatment type, distribution channel, prescription status, patient type, age group, gender, and region.
- The most popular treatment type in the market is topical medications.
- Hospitals and clinics are the foremost distribution channel category.
- Regarding CAGR, prescription medications are expected to grow fastest during the forecast period.
- The category for adults will likely see the highest CAGR during the anticipated time frame.
- North America is leading market development; the market is highly competitive with key players including Almirall, S.A., Bausch Health Companies Inc., Perrigo Company plc., Sun Pharmaceutical Industries Ltd., Hill Dermaceuticals, Inc., Spear Pharmaceuticals, Tolmar Pharmaceuticals, Inc., Bioforntera AG, Cipher Pharmaceuticals Inc., Vidac, Athenex, Inc., 3M, Mayne Pharma Group Limited, and Others.
Future Outlook
- The actinic keratosis industry is expected to increase significantly in North America and has a positive outlook worldwide.
- Actinic keratosis can result in squamous cell carcinoma, a kind of skin cancer that is anticipated to accelerate the expansion of the actinic keratosis market.
- During the forecast duration, one of the main challenges expected to impede the growth of the actinic keratosis market is the high treatment costs.
- To stay ahead of the competition, key enterprises must develop new products, expand their market reach, and keep their prices competitive.
How CXOs Can Benefit from the Credence Research Actinic Keratosis Market Report
CXOs may get a detailed picture of the market in the Credence Research Actinic Keratosis Market Report, which includes:
- Market size and growth forecast: The report provides detailed estimates of the global actinic keratosis market size, segmented by treatment type, distribution channel, prescription status, patient type, age group, gender, and region. It also includes forecasts for the market through 2032 based on key trends and drivers.
- Market segmentation: The research report breaks down the market for actinic keratosis into segments based on the treatment type, distribution channel, prescription status, patient type, age group, gender, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape: The research report offers a detailed analysis of the major companies in the actinic keratosis industry, including information on their business plans, line of products, and earnings. CXOs can use this information to evaluate and identify their competitors.
- Key trends and drivers: The research report identifies and evaluates the main trends and factors influencing the market for actinic keratosis. CXOs can use this information to make well-informed choices regarding their plans and investments.
CXOs can use the insights from the Credence Research Actinic Keratosis Market Report to:
- Identify growth opportunities: With the help of this analysis, CXOs may identify new growth opportunities in the actinic keratosis sector. For example, the report identifies the growing demand for actinic keratosis from dermatology centers as a key opportunity.
- Make informed investment decisions: With the help of the report, CXOs can choose actinic keratosis wisely. For example, the research study provides information on the critical factors to consider while selecting actinic keratosis solutions and evaluating actinic keratosis suppliers.
- Develop competitive strategies: The research report can be used by CXOs to develop competitive strategies for their actinic keratosis businesses. For example, the research paper outlines the main strategies suppliers of actinic keratosis utilize to differentiate themselves from competitors.
- Track market developments: CXOs may stay ahead of the curve by tracking market developments with the aid of this research report. For instance, the research report offers insights into the most recent developments and trends in the market for actinic keratosis.
In general, CXOs seeking to expand their industry knowledge and spot growth prospects will find the Credence Research Actinic Keratosis Market Report a useful tool.
Segmentation
- By Treatment Type
- Topical Medications
- Photodynamic Therapy (PDT)
- Cryotherapy
- Laser Therapy
- Chemical Peels
- By Distribution Channel
- Hospitals and Clinics
- Dermatology Centers
- Retail Pharmacies
- Online Retail
- By Prescription Status
- Prescription Medications
- Over-the-counter (OTC) Products
- By Patient Type
- Outpatient Treatment
- Self-administered Treatment
- By Age Group
- Adults
- Elderly
- By Gender
- Male
- Female
- By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- North America
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Actinic Keratosis
The increasing incidence of actinic keratosis, particularly among aging populations and individuals with high cumulative sun exposure, is directly expanding the patient pool requiring diagnosis and treatment. This trend is especially pronounced in regions such as North America, Europe, and Australia, where awareness and detection rates are high.
Advancements in Minimally Invasive Treatments
The development and adoption of minimally invasive therapies, such as photodynamic therapy (PDT) and advanced topical medications, are driving market growth by offering effective, patient-friendly alternatives to surgical procedures. These innovations improve patient compliance and outcomes, encouraging broader adoption in both outpatient and self-administered settings.
Expansion of Healthcare Infrastructure and Access
Improvements in healthcare infrastructure, particularly in emerging markets across Asia Pacific and Latin America, are increasing access to dermatological care and actinic keratosis treatments. Enhanced distribution channels, including hospitals, clinics, and online retail, are making therapies more widely available to diverse patient populations.
Regulatory Approvals and Product Launches
Frequent regulatory approvals and the introduction of new, targeted therapies by leading pharmaceutical companies are expanding the range of available treatment options. This not only stimulates competition but also accelerates market penetration and adoption of innovative products, such as new topical agents and combination therapies.
Growing Awareness and Early Detection Initiatives
Public health campaigns and educational initiatives are raising awareness about the risks of actinic keratosis and its potential progression to skin cancer. Increased screening and early detection efforts are leading to higher diagnosis rates and earlier intervention, further fueling demand for effective treatment solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How much does the global market currently hold for actinic keratosis?
What is the projected growth rate of the actinic keratosis market between 2024 and 2032?
In terms of treatment type, which market category is leading?
Regarding the distribution channel, which market category is in the lead?
Who are the main players in the actinic keratosis industry globally?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Treatment Type
- 1.2.1 Topical Medications
- 1.2.2 Photodynamic Therapy (PDT)
- 1.2.3 Cryotherapy
- 1.2.4 Laser Therapy
- 1.2.5 Chemical Peels
- 1.3 By Prescription Status
- 1.3.1 Prescription Medications
- 1.3.2 Over-the-counter (OTC) Products
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 6,514.2 million → 2032: USD 9,933.73 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Actinic Keratosis Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Actinic Keratosis Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Actinic Keratosis Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Actinic Keratosis Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Actinic Keratosis Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Actinic Keratosis Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Actinic Keratosis Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Actinic Keratosis Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 6,514.2 million → 2032: USD 9,933.73 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Actinic Keratosis Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Treatment Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Topical Medications
- 12.3.7.2 Photodynamic Therapy (PDT)
- 12.3.7.3 Cryotherapy
- 12.3.7.4 Laser Therapy
- 12.3.7.5 Chemical Peels
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Prescription Status - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Prescription Medications
- 12.4.7.2 Over-the-counter (OTC) Products
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Actinic Keratosis Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Share, 2023
- 13.2 Regional Market Forecast, 2023-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Actinic Keratosis Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Actinic Keratosis Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Almirall, S.A.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Bausch Health Companies Inc.
- 17.4 Perrigo Company plc.
- 17.5 Sun Pharmaceutical Industries Ltd.
- 17.6 Hill Dermaceuticals, Inc.
- 17.7 Spear Pharmaceuticals
- 17.8 Tolmar Pharmaceuticals, Inc.
- 17.9 Biofrontera AG
- 17.10 Cipher Pharmaceuticals Inc.
- 17.11 Mayne Pharma Group Limited
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

