
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
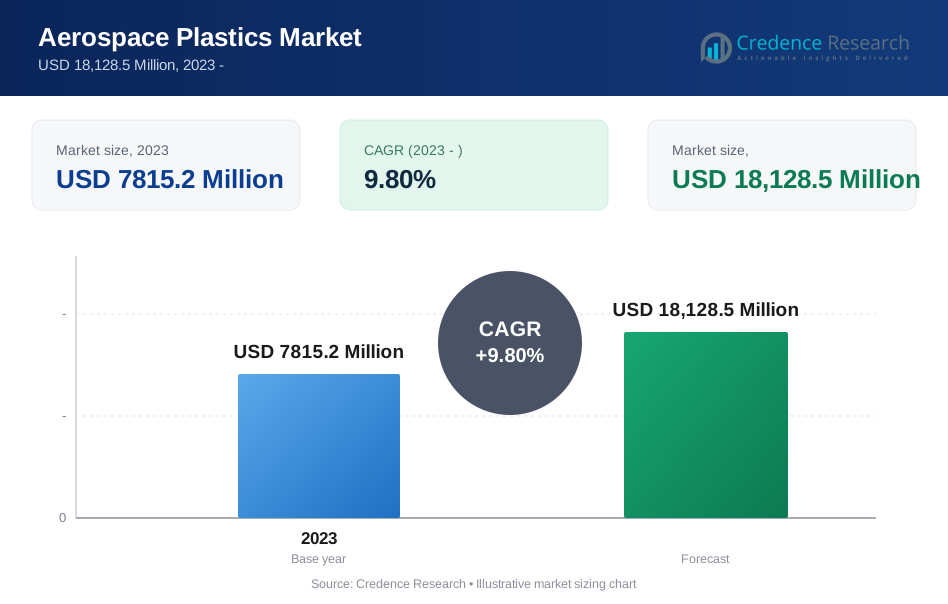
| Aerospace Plastics Market Size 2023 | USD 7815.2 Million |
| Aerospace Plastics Market, CAGR | 9.80% |
| Aerospace Plastics Market Size 2032 | USD 18128.5 Million |
Market Insights
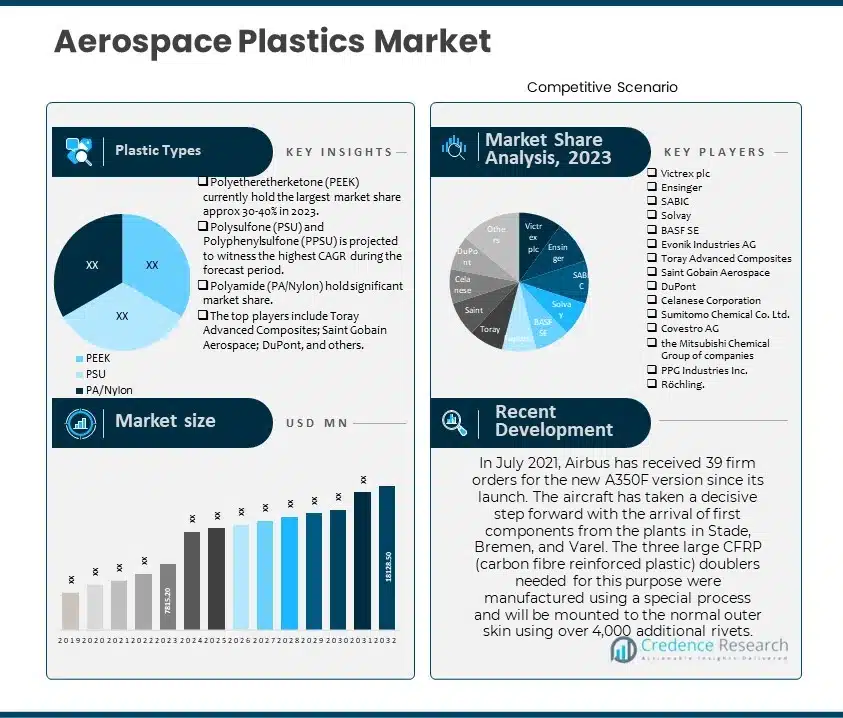
- The global Aerospace Plastics Market reached a valuation of USD 7815.2 Million in 2023 and is anticipated to surge to USD 18128.5 Million by 2032, exhibiting a robust CAGR of 9.90% from 2024 to 2032.
- Among the key segments, Polyetheretherketone (PEEK) emerged as the market leader by plastic type, constituting approximately 30-40% of the total market share in 2023. However, Polyphenylsulfone (PPSU) and Polysulfone (PSU) plastics are expected to experience rapid growth throughout the forecast period.
- Interior Components segment holds around 35% of the market share in 2023 owing to diverse uses in cabin interiors, electrical electronics & control panels, windows, and structural components.
- Injection Molding currently holds the largest share of the market in 2023, constituting approximately 25-30% of the total market.
- North America accounts for a significant share of the market in 2023, followed by Asia Pacific and Europe with a collective share of just under 55%.
- The rise in demand for aerospace plastics and the need for lightweight materials fuel the demand for Aerospace Plastics Market, augmenting growth prospects.
- Key opportunities in the market include significant growth potential in Asia Pacific, increased adoption across various aircraft components, and continuous advancements in technology, fostering market expansion.
Executive Summary
Market Definition
Aerospace plastics are synthetic materials designed and engineered for use in aircraft and spacecraft applications. They are lightweight, strong, and resistant to extreme temperatures, chemicals, and other environmental factors encountered in aerospace environments. Airplanes increasingly incorporate plastics instead of traditional materials like aluminum and steel within their structures due to several advantages such as lightweight material and cost effectives. The market for aerospace plastics is driven by the increasing demand for plastics in several aerospace applications, including cabin interiors,electrical electronics & control panels, windows, structural components, windshields, and canopies. Most aerospace plastics are polymers that provide enhanced properties such as high tensile strength, high temperature tolerance, great transparency, chemical properties, hard surface, and others.
Market Overview
- The global Aerospace Plastics Market reached a valuation of USD 7815.2 Million in 2023 and is anticipated to surge to USD 18128.5 Million by 2032, exhibiting a robust CAGR of 9.90% from 2024 to 2032.
- Among the key segments, Polyetheretherketone (PEEK) emerged as the market leader by plastic type, constituting approximately 30-40% of the total market share in 2023. However, Polyphenylsulfone (PPSU) and Polysulfone (PSU) plastics are expected to experience rapid growth throughout the forecast period.
- Interior Components segment holds around 35% of the market share in 2023 owing to diverse uses in cabin interiors, electrical electronics & control panels, windows, and structural components.
- Injection Molding currently holds the largest share of the market in 2023, constituting approximately 25-30% of the total market.
- North America accounts for a significant share of the market in 2023, followed by Asia Pacific and Europe with a collective share of just under 55%.
- The rise in demand for aerospace plastics and the need for lightweight materials fuel the demand for Aerospace Plastics Market, augmenting growth prospects.
- Key opportunities in the market include significant growth potential in Asia Pacific, increased adoption across various aircraft components, and continuous advancements in technology, fostering market expansion.
Segmentation by Plastic Types
- Polyetheretherketone (PEEK) currently hold the largest market share approx 30-40% in 2023. The market is driven by several factors such as high strength, low weight, chemical resistance, flame retardancy, and low smoke and toxic gas emission, contribute significantly to its popularity within the aerospace sector.
- Polysulfone (PSU) and Polyphenylsulfone (PPSU) is projected to witness the highest CAGR during the forecast period. Polysulfone (PSU) and Polyarylsulfone (PPSU), being lightweight materials, exhibit impressive strength-to-weight ratios that render them appealing substitutes for more cumbersome metallic counterparts.
- Polyamide (PA/Nylon) hold significant market share due to their due to its transparency, lightweight nature, and good flame retardancy.
Segmentation by Acrylonitrile Butadiene Styrene (ABS)
- Thermosetting Plastics currently hold the largest market share approx 40-45% in 2023. The market is driven by several factors such as high strength and stiffness, high-temperature resistance, and good chemical resistance.
- Fluoropolymers is projected to witness the highest CAGR during the forecast period. PTFE (Polytetrafluoroethylene) is a material that greatly reduces friction and prevents wear on important parts such as bearings and seals due to its natural ability to lubricate itself drives the market.
Segmentation by Aircraft Component Applications
- Interior Components currently hold the largest market share approx 30-32% in 2023. Interior components are a significant part of the aerospace plastics market because they are widely used in various applications like seats, panels, trays, and stowage compartments. These components offer design flexibility, weight reduction, and fuel efficiency.
- Aeroengine Components is projected to witness the highest CAGR during the forecast period. Lighter plastic materials are substituting hefty metal parts, particularly in fans' rotating blades and airflow channels (ducts), resulting in less overall aircraft weight and better fuel economy drives the market.
Segmentation by Aircraft Type
- Commercial Aircraft currently hold the largest market share approx 40-46% in 2023. Plastics are widely used in various parts of Commercial Aircraft, including interiors, exteriors, and engines. They help reduce weight, improve fuel efficiency, and have diverse applications.
- General Aviation is projected to witness the highest CAGR during the forecast period due to Cost-effectiveness, and growing demand.
Segmentation by Plastic Processing Methods
- Injection Molding currently hold the largest market share approx 38% in 2023. Injection molding ensures consistent and accurate part geometries, crucial for safety-critical applications in aerospace which further cater the demand for this market.
- Thermoforming hold significant market share due to their due to its allows for the creation of intricate shapes with high precision and accuracy.
Segmentation by Forms of Plastics
- Composite Materials currently hold the largest market share approx 55% in 2023. Composite materials are the most widely used in the aerospace plastics market because they offer a unique combination of properties like being lightweight, strong, and resistant to corrosion and fatigue which drive the market.
- Films and Sheets is projected to witness the highest CAGR during the forecast period.
Segmentation by End-User Industries
- Aircraft Manufacturing currently hold the largest market share approx 50-55% in 2023 due to high volume of new aircraft production.
- Aircraft Maintenance, Repair, and Overhaul (MRO) is projected to witness the highest CAGR during the forecast period due to advancements in repair technologies.
Segmentation by Region
- North America held largest share around 40-42% of the market in 2023. This dominance is primarily due to well-established supply chains, research & development facilities, and favorable government policies.
- Asia Pacific and Europe collectively account for just under 55% share in 2023, with Asia Pacific holding over 20% share in the same year.
- The rest of the world, including Latin America, the Middle East, and Africa, supplies the remaining demand for Aerospace Plastics.
Technological advancements within the Aerospace Plastics, such as the emergence of more efficient and sustainable products, are also contributing to market growth.
North America hold largest market share of the global aerospace plastics market due to several factors, such as significant investments in research and development, the presence of leading industry players, fuel-efficient aircraft and increasing demand for lightweight. The region has several prominent players such as Boeing and Lockheed Martin, BASF SE, and others. The market players are considerably contributing to the market growth by the adoption of various strategies including mergers & acquisitions, collaborations, funding, and new product launches, to stay competitive in the market. For instance,in July 2021, Airbus has received 39 firm orders for the new A350F version since its launch. The aircraft has taken a decisive step forward with the arrival of first components from the plants in Stade, Bremen, and Varel. The production start at these sites marks a major milestone towards A350F industrialization. The freighter lower shell is similar to the A350 passenger version, but requires additional reinforcement for flight test instrumentation. The three large CFRP (carbon fibre reinforced plastic) doublers needed for this purpose were manufactured using a special process and will be mounted to the normal outer skin using over 4,000 additional rivets. Additionally, the US government's support for the aerospace industry through initiatives such as the American Aerospace Materials Manufacturing Center further drive the aerospace plastics market in North America. For instance, in October 2023,Spokane-based American Aerospace Materials Manufacturing Center has been named the U.S. tech hub for aerospace materials manufacturing by the Department of Commerce’s Economic Development Administration (EDA). The center was selected from nearly 200 applicants, and is one of 31 awardees. The proposal was supported by nearly 50 Spokane-area organizations, including Advanced Thermoplastics Composites (ATC), Gonzaga University, and the International Association of Machinists District 751.
The Asia-Pacific region is experiencing significant growth in the aerospace plastics market due to several factors, including the demand for lighter weight and fuel-efficient aircraft, increased production rates, and the presence of prominent industry players. Key drivers contributing to this trend include the rise in commercial aviation, the need for reduced operating costs among carriers, and government investment in the aerospace industry. For instance, at Aero India 2023, Apollo Aerospace stepped up its presence as a master distributor for Ensinger plastics, offering a range of plastic solutions for the aerospace industry, including stock shapes, compounds, sintered plastics, profiles, tubes, injection molding, additive manufacturing, composites, and machined parts. With a strong focus on meeting the exacting requirements of its customers, Apollo Aerospace's sales and technical team were available to provide expert guidance and support to attendees interested in their plastic products. Moreover, the partnership and collaboration between market players further strengthens the position of the Asia Pacific region in the global aerospace plastics market. For instance, in April 2023, Solvay and GKN Aerospace extended their collaboration agreement, building on successful projects such as the TPC (thermoplastic composites) wing rib program and cost-effective AFP TPC fuselage panel. They will continue working together on next-generation TPC materials and processes for aerospace applications, focusing on high-rate manufacturing solutions for medium and large structures.
Key Highlights of the Report
The Aerospace Plastics Market is segmented by Plastic Type, Aircraft Component Application, Aircraft Type, Plastic Processing Method, Form of Plastics, Acrylonitrile Butadiene Styrene (ABS), End-User Industry, and Region. The increasing demand for lightweight and durable materials in aircraft construction is driving the adoption of aerospace plastics across various applications in the aerospace industry, including cabin interiors, structural components, and aeroengine components. This surge in demand is largely due to the advantages offered by aerospace plastics, such as their high strength-to-weight ratio and resistance to extreme conditions.
Polyetheretherketone (PEEK) holds a dominant position in the market, providing essential properties for aerospace applications, including high strength, low weight, and chemical resistance. Additionally, Polyphenylsulfone (PPSU) and Polysulfone (PSU) plastics are experiencing rapid growth, especially as substitutes for traditional metallic components in aircraft manufacturing.
Key user segments include aircraft manufacturers, maintenance, repair, and overhaul (MRO) companies, and aerospace research and development institutions, reflecting a diverse adoption of aerospace plastics across the aerospace sector. The rapid growth in aircraft manufacturing indicates an increasing trend toward lightweight materials for improved fuel efficiency and performance.
North America drives the market growth, with major players like Victrex plc, Ensinger, and SABIC leading the market. This dominance is attributed to the region's well-established aerospace industry, significant investments in research and development, and the presence of key aerospace manufacturers. Additionally, government support and technological advancements contribute to the region's leadership in the Aerospace Plastics Market.
What Are The Main Drivers Of The Global Aerospace Plastics Market?
The global Aerospace Plastics market is driven by various factors, including lightweight, high-performance plastics designed for aircraft acoustic, thermal, and chemical resistance. The increasing fleet size of commercial aircraft is also significantly contributing to the growth of the aerospace plastics market.
What Are The Major Challenges Faced By The Global Aerospace Plastics Market?
The global Aerospace Plastics market is mainly restraint by stringent regulatory standards such as aerospace-grade plastics must meet strict safety and performance criteria set forth by organizations such as UL94, FAR 25.853, ASTM, DFAR's, MIL-PRF-5425, MIL-PRF-8184, and MIL-PRF-25690. These standards require substantial investments in research and development, making it difficult for new entrants without the necessary technical expertise to participate in the market.
What Are The Growth Opportunities In The Global Aerospace Plastics Market?
The global aerospace plastics market presents numerous growth opportunities due to increasing demand for lighter, stronger, and more efficient materials in the aviation industry. The retirement of aging aircraft and the introduction of newer models require advanced materials, creating demand for aerospace plastics.
Market Drivers
The global Aerospace Plastics market is driven by several factors. The following are the key drivers of the global Aerospace Plastics market:
Adoption of Various Strategies Among Market Players
The major companies serving the global Aerospace Plastics Market are DuPont; Celanese Corporation; Sumitomo Chemical Co., Ltd.; Covestro AG, among others. The market players are considerably contributing to the market growth by the adoption of various strategies including mergers & acquisitions, collaborations, funding, and new product launches, to stay competitive in the market. For instance, in September 2023, Sumitomo Bakelite's subsidiary Vaupell has secured a contract to supply main deck cargo liners for the new Airbus A350F cargo aircraft, expanding its aircraft interiors business in Europe. This contract win highlights the company's expertise in providing innovative solutions for the aerospace industry.
Market Restraints
The global Aerospace Plastics market faces some challenges that may hinder its growth. These include the following:
Regulatory Challenges
The aerospace industry faces numerous regulatory challenges regarding the use of materials in aircraft, particularly plastics. Recent instances include the EU's ban on single-use plastics and restrictions on certain plastics in aircraft cabins due to fire safety concerns. Moreover, the Federal Aviation Administration (FAA) introduced a rule mandating that all new aircraft designs demonstrate improved fire safety standards, making it more difficult for some plastics to obtain approval for use in aerospace applications. The strict regulations governing the aerospace industry aim to ensure the safety and reliability of aircraft components, especially those used in passenger cabins. Plastics used in aerospace applications must meet stringent industry requirements related to flame retardancy, chemical resistance, low toxicity, weight, and more.
Opportunities
The global Aerospace Plastics market offers significant growth opportunities. These include the following:
Increasing Demand of Interior Components
The main factor that presents an opportunity for the Aerospace Plastics market is the increasing demand for interior components. For instance, in January 2024, Donite Plastics partnered with NITC, has developed a robotic automated assembly cell for advanced Thermoformed Twin Skin Panels (TTSP) for aircraft seating systems, improving efficiency and part quality. The technology will be introduced into the aircraft interiors assembly process, creating up to eight jobs at the Saintfield-based company. This trend presents opportunities for manufacturers to develop innovative Aerospace Plastics to meet diverse customer needs, especially in harsh environments. By offering high-quality, versatile, and accurate Aerospace Plastics solutions for interior, manufacturers can capitalize on this growing demand and expand their market share.
Competitive Landscape
Key Players
The global Aerospace Plastics market is highly competitive, with several key players. Some of the major players in the market and their market share are as follows:
- Victrex plc
- Ensinger
- SABIC
- Solvay
- BASF SE
- Evonik Industries AG
- Toray Advanced Composites
- Saint Gobain Aerospace
- DuPont
- Celanese Corporation
- Sumitomo Chemical Co. Ltd.
- Covestro AG
- the Mitsubishi Chemical Group of companies
- PPG Industries Inc.
- Röchling
- Others
These organizations prioritize product innovation, distribution channel expansion, and mergers and acquisitions to stay competitive.
The global Aerospace Plastics market's key players continually seek to stay ahead by offering new products and developments.
In July 2021, Airbus has received 39 firm orders for the new A350F version since its launch. The aircraft has taken a decisive step forward with the arrival of first components from the plants in Stade, Bremen, and Varel. The production start at these sites marks a major milestone towards A350F industrialization. The freighter lower shell is similar to the A350 passenger version, but requires additional reinforcement for flight test instrumentation. The three large CFRP (carbon fibre reinforced plastic) doublers needed for this purpose were manufactured using a special process and will be mounted to the normal outer skin using over 4,000 additional rivets.
in November 2020, Turkish Aerospace and Boeing partnered to develop thermoplastic composites for the aerospace industry. Boeing provided technical support for Turkish Aerospace to establish a production facility for thermoplastic materials. The partnership aimed to produce lightweight, energy-efficient parts using advanced manufacturing techniques.
Summary of Key Findings
- The Aerospace Plastics Market is experiencing significant growth propelled by the increasing demand for lightweight and durable materials in aircraft construction across industries such as cabin interiors, structural components, and aeroengine components. This growth is driven by the advantages offered by aerospace plastics, including their high strength-to-weight ratio and resistance to extreme conditions.
- Market segmentation is based on plastic type, aircraft component application, aircraft type, Acrylonitrile Butadiene Styrene (ABS), plastic processing method, form of plastics, end-user industry, and region, reflecting the diverse applications and specialized needs within the aerospace plastics industry.
- Polyetheretherketone (PEEK) dominates the market, providing essential properties for aerospace applications such as high strength, low weight, and chemical resistance. Additionally, Polyphenylsulfone (PPSU) and Polysulfone (PSU) plastics are experiencing rapid growth as substitutes for traditional metallic components in aircraft manufacturing.
- Key user segments include aircraft manufacturers, maintenance, repair, and overhaul (MRO) companies, and aerospace research and development institutions, indicating widespread adoption across various sectors. The increasing trend toward lightweight materials for improved fuel efficiency and performance drives growth in the aircraft manufacturing segment.
Future Outlook
- The Aerospace Plastics Market exhibits promising growth prospects, particularly in Asia Pacific, driven by rapid industrialization, urbanization, and stringent regulatory standards. Market players should capitalize on this growth potential by focusing on innovation and technological advancements.
- Anticipated challenges in the forecast period include addressing the competition between different sensor technologies and addressing the high cost and calibration needs associated with certain Aerospace Plastics.
- To stay competitive, industry players should prioritize product innovation, technological advancements, and strategic partnerships to meet evolving market demands and maintain their position in the dynamic Aerospace Plastics Market.
How CXOs Can Benefit from the Credence Research Aerospace Plastics Networks Market Report
The Credence Research Aerospace Plastics Networks Market Report provides CXOs with a comprehensive overview of the market, including:
- Market size and growth forecast: The report provides detailed estimates of the global Aerospace Plastics networks market size, segmented by Plastic Type, Acrylonitrile Butadiene Styrene (ABS), Aircraft Component Application, Aircraft Type, Plastic Processing Method, Form of Plastics, End-User Industry, and Region. It also includes forecasts for the market through 2032, based on key trends and drivers.
- Market segmentation: The report segments the Aerospace Plastics networks market by Plastic Type, Aircraft Component Application, Aircraft Type, Plastic Processing Method, Form of Plastics, End-User Industry, and Region. The increasing demand for advanced solutions is driven. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape: The report profiles the key players in the Aerospace Plastics networks market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers: The report identifies and analyzes the key trends and drivers that are shaping the Aerospace Plastics networks market. This information can help CXOs to make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research Aerospace Plastics Networks Market Report to:
- Identify growth opportunities: The report can help CXOs to identify new growth opportunities in the Aerospace Plastics networks market. For example, the report identifies the growing demand for Aerospace Plastics networks from cloud computing providers and telecom companies as a key opportunity.
- Make informed investment decisions: The report can help CXOs to make informed investment decisions about Aerospace Plastics networks. For example, the report provides insights into the key factors to consider when evaluating Aerospace Plastics providers and selecting Aerospace Plastics solutions.
- Develop competitive strategies: The report can help CXOs to develop competitive strategies for their Aerospace Plastics networks businesses. For example, the report identifies the key strategies that Aerospace Plastics providers are using to differentiate themselves from their competitors.
- Track market developments: The report can help CXOs to track market developments and stay ahead of the curve. For example, the report provides insights into the latest trends and innovations in the Aerospace Plastics networks market.
Overall, the Credence Research Aerospace Plastics Networks Market Report is a valuable resource for CXOs who are looking to gain a deeper understanding of the market and identify opportunities for growth.
Segmentation
- By Plastic Types:
- Polyetheretherketone (PEEK)
- Polycarbonate (PC)
- Polyethylene (PE) and Polypropylene (PP)
- Polyamide (PA/Nylon)
- Polysulfone (PSU) and Polyphenylsulfone (PPSU)
- By Acrylonitrile Butadiene Styrene (ABS):
- Polyvinyl Chloride (PVC)
- Thermosetting Plastics
- Fluoropolymers (e.g., PTFE)
- Aircraft Component Applications:
- Interior Components
- Exterior Components
- Structural Component
- Aeroengine Components
- By Aircraft Type:
- Commercial Aircraft
- Military Aircraft
- General Aviation
- Plastic Processing Methods:
- Injection Molding
- Compression Molding
- Thermoforming
- Extrusion
- By Forms of Plastics:
- Composite Materials
- Foams
- Films and Sheets
- By End-User Industries:
- Aircraft Manufacturing
- Aircraft Maintenance, Repair, and Overhaul (MRO)
- Aerospace Research and Development
- By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- North America
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Lightweight and High-Performance Material Demand
Aerospace plastics offer significant weight reduction compared to metals, improving fuel efficiency and reducing emissions, which is critical for both commercial and military aircraft manufacturers seeking to meet stringent environmental and operational cost targets.
Expansion of Aircraft Manufacturing and Fleet Modernization
The ongoing replacement of aging aircraft with new, more efficient models is driving demand for advanced plastics that meet modern performance and safety standards, especially as airlines and defense sectors expand their fleets.
Technological Advancements in Plastic Processing
Innovations in processing methods such as injection molding and thermoforming enable the production of complex, high-precision components, supporting the adoption of plastics in critical aerospace applications like interiors, structural parts, and aeroengine components.
Stringent Regulatory and Safety Requirements
Aerospace plastics are engineered to meet rigorous fire, smoke, toxicity, and mechanical standards, making them increasingly preferred for applications where compliance with international aviation regulations is mandatory.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global Aerospace Plastics market?
What is the expected growth rate of the Aerospace Plastics market between 2024 and 2032?
Which segment is leading the market share in terms of Aerospace Plastics Types?
Which Acrylonitrile Butadiene Styrene (ABS) Segments governs the demand for Aerospace Plastics in the world?
Who are the major players in the global Aerospace Plastics market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Plastic Type
- 1.2.1 Polyetheretherketone (PEEK)
- 1.2.2 Polycarbonate (PC)
- 1.2.3 Polyethylene (PE) and Polypropylene (PP)
- 1.2.4 Polyamide (PA/Nylon)
- 1.2.5 Polysulfone (PSU) and Polyphenylsulfone (PPSU)
- 1.3 By Plastic Processing Method
- 1.3.1 Injection Molding
- 1.3.2 Compression Molding
- 1.3.3 Thermoforming
- 1.3.4 Extrusion
- 1.4 By Aircraft Component Application
- 1.4.1 Interior Components
- 1.4.2 Exterior Components
- 1.4.3 Structural Components
- 1.4.4 Aeroengine Components
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 7815.2 Million → 2032: USD 18,128.5 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aerospace Plastics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aerospace Plastics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aerospace Plastics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aerospace Plastics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aerospace Plastics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aerospace Plastics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aerospace Plastics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aerospace Plastics Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 7815.2 Million → 2032: USD 18,128.5 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aerospace Plastics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Plastic Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Polyetheretherketone (PEEK)
- 12.3.7.2 Polycarbonate (PC)
- 12.3.7.3 Polyethylene (PE) and Polypropylene (PP)
- 12.3.7.4 Polyamide (PA/Nylon)
- 12.3.7.5 Polysulfone (PSU) and Polyphenylsulfone (PPSU)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Plastic Processing Method - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Injection Molding
- 12.4.7.2 Compression Molding
- 12.4.7.3 Thermoforming
- 12.4.7.4 Extrusion
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Aircraft Component Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Interior Components
- 12.5.7.2 Exterior Components
- 12.5.7.3 Structural Components
- 12.5.7.4 Aeroengine Components
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aerospace Plastics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aerospace Plastics Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aerospace Plastics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aerospace Plastics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Victrex plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ensinger
- 18.4 SABIC
- 18.5 Solvay
- 18.6 BASF SE
- 18.7 Evonik Industries AG
- 18.8 Toray Advanced Composites
- 18.9 Saint Gobain Aerospace
- 18.10 DuPont
- 18.11 Celanese Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

