
Market Overview
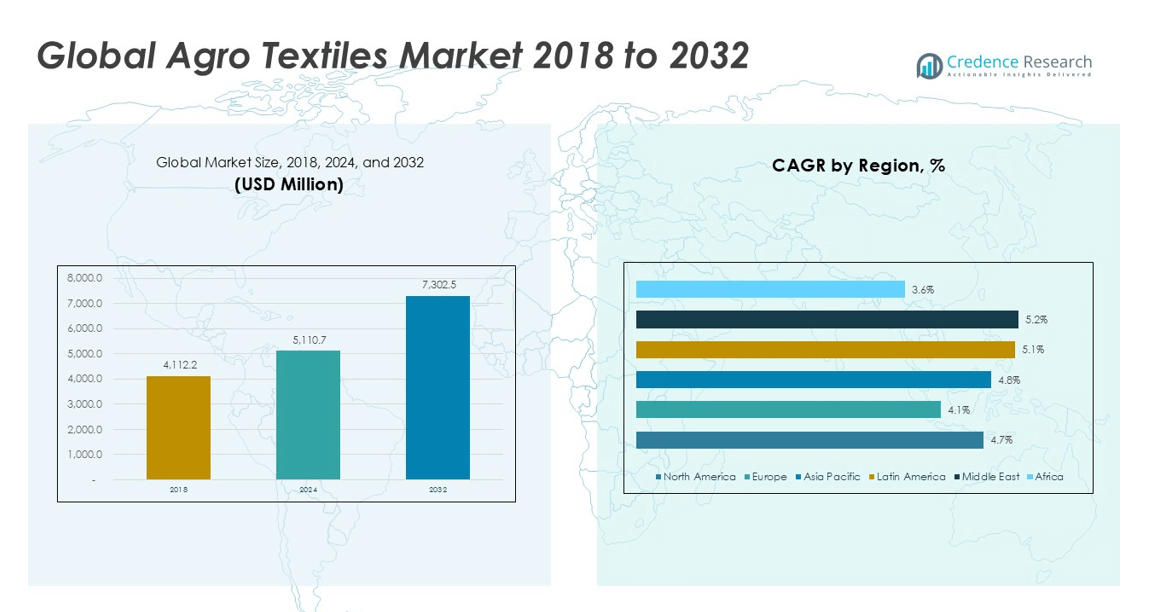
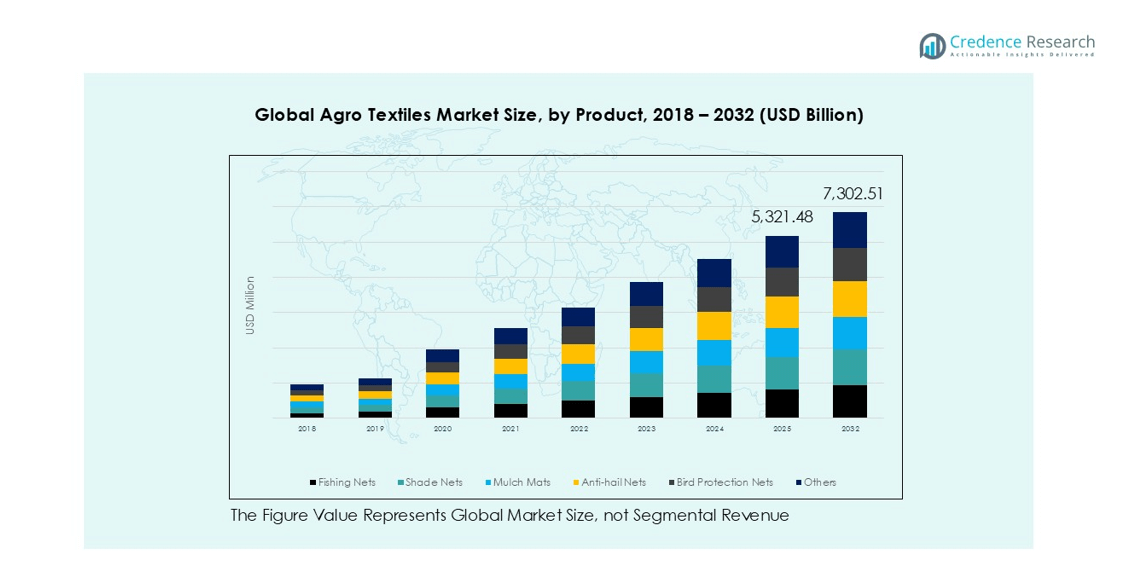
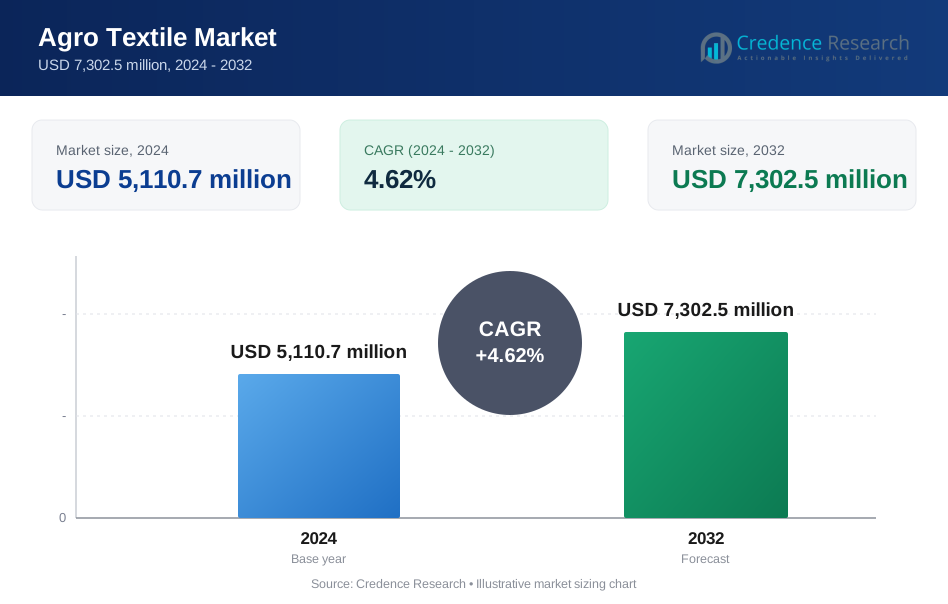
Agro Textiles market size was valued at USD 4,112.2 million in 2018 to USD 5,110.7 million in 2024 and is anticipated to reach USD 7,302.5 million by 2032, at a CAGR of 4.62% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Agro Textiles Market Size 2024 | USD 5,110.7 million |
| Agro Textiles Market, CAGR | 4.62% |
| Agro Textiles Market Size 2032 | USD 7,302.5 million |
The Agro Textiles market features a mix of global and regional manufacturers. Key players include SRF Limited, Tama, Belton Industries, Neo Corp International Limited, Diatex, Hy-Tex (UK) Limited, Aduno SRL, Siang May Pte Ltd., HELIOS GROUP S.r.l., and B&V Agro Irrigation Co. These companies compete through durable products, wide portfolios, and strong distribution networks. Asia Pacific leads the market with an exact share of 34.2%, supported by large-scale agriculture and aquaculture activity. Europe follows with a 26.7% share, driven by greenhouse and horticulture demand. North America holds a 22.9% share, supported by mechanized farming and crop protection adoption. These regions shape competitive strategies and capacity expansion plans.
Market Insights
- The Agro Textiles market was valued at USD 5,110.7 million in 2024 and is projected to reach USD 7,302.5 million by 2032, growing at a CAGR of 4.62% during the forecast period.
- Market growth is driven by rising demand for crop protection, yield improvement, and controlled farming practices, with fishing nets and shade nets holding the largest product segment share due to strong aquaculture and protected agriculture use.
- Key trends include higher adoption of UV-stabilized and durable textiles, growth of greenhouse farming, and increasing use of mulch mats to conserve water and control weeds in modern agriculture systems.
- The competitive landscape remains moderately fragmented, with players such as SRF Limited, Tama, and Belton Industries focusing on product durability, cost efficiency, and regional distribution expansion.
- Asia Pacific leads with a 34.2% regional share, followed by Europe at 26.7% and North America at 22.9%, while agriculture remains the dominant application segment across all regions.
Market Segmentation Analysis:
By Product
The Agro Textiles market shows clear variation across product categories. Fishing nets hold the dominant market share. This leadership comes from strong use in aquaculture and inland fisheries. Shade nets follow as a key segment due to demand in protected farming. Farmers use shade nets to control sunlight and temperature. Mulch mats gain steady adoption for weed control and moisture retention. Anti-hail and bird protection nets support crop safety in high-risk regions. Growth across products depends on yield improvement needs, climate risks, and rising adoption of modern farming practices.
- For instance, Garware Technical Fibres is a major global supplier of HDPE (high-density polyethylene) fishing nets and ropes for the aquaculture industry. The company provides durable netting solutions that are utilized in both inland and coastal operations. Garware's products, known for their high strength retention and resistance to biofouling, have a lifespan that can reach up to two years or more in marine conditions, especially when used in large-scale salmon farming operations across Norway, Chile, and Scotland.
By Application
Application demand reflects farming intensity and crop value. Agriculture accounts for the largest market share. Broad use across field crops supports this dominance. Farmers adopt agro textiles to improve productivity and reduce losses. Horticulture follows due to high-value fruits and vegetables. Shade control and crop protection drive demand in this segment. Floriculture shows stable growth from greenhouse expansion. Aquaculture also contributes through fishing and cage nets. Growth drivers include food security needs, controlled farming expansion, and rising focus on sustainable and efficient agricultural practices.
- For instance, Rishi FIBC Solutions Pvt. Ltd. is an established manufacturer of technical textiles and industrial packaging, with a large integrated manufacturing facility in Gujarat. The company produces a wide range of products for agricultural and building industries, including shade nets and insect nets.
Key Growth Drivers
Rising Focus on Crop Yield and Protection
Farmers face rising pressure to improve yield per hectare. Agro textiles help protect crops from weather stress. Products control sunlight, temperature, and moisture levels. These benefits support stable crop growth. Farmers reduce losses from pests and birds. Anti-hail and shade nets limit damage from extreme weather. Mulch mats help conserve soil moisture. These materials also reduce weed growth. Governments promote modern farming methods. Subsidies support protected cultivation practices. Small and large farms adopt these solutions. Demand rises across open-field and controlled farming. Food demand growth strengthens this driver. Climate change risks further accelerate adoption. Agro textiles improve productivity with lower input waste. This driver remains critical across developing and developed regions.
- For instance, Garware Technical Fibres developed its V5 Shade Net that enables 35% better light diffusion and lowers field temperature by 3°C, helping protect crops from heat stress.
Expansion of Protected and Controlled Farming
Protected farming gains strong momentum worldwide. Greenhouses and net houses expand rapidly. Agro textiles form the base of these structures. Shade nets regulate light and heat reminders. Anti-insect and bird nets improve crop safety. Controlled farming ensures year-round production cycles. Growers gain higher output consistency. Floriculture and horticulture benefit the most. High-value crops justify material investment. Urban farming also supports this trend. Governments promote protected farming to ensure food security. Limited land availability strengthens demand. Controlled farming also saves water. This driver supports long-term market stability. Adoption grows across Asia, Europe, and Latin America.
- For instance, Netafim India is involved in extensive agricultural projects, including those utilizing protected cultivation like greenhouses and net houses, to help farmers improve yield and crop duration.
Growth of Aquaculture and Fisheries
Aquaculture production continues to rise globally. Fishing nets form a core input. Inland and coastal farming expand steadily. Protein demand supports fish consumption growth. Agro textiles improve cage strength and durability. Modern nets reduce stock losses. Farmers prefer long-life synthetic materials. Aquaculture investment grows in Asia Pacific. Coastal economies rely on fish exports. Governments support sustainable fishing practices. Advanced net designs improve water flow. Disease control improves through better materials. This driver secures steady demand. Fishing nets remain the largest revenue contributor.
Key Trends & Opportunities
Shift Toward Sustainable and Durable Materials
Sustainability gains strong attention in agriculture. Farmers prefer long-lasting agro textiles. Durable materials reduce replacement costs. Recyclable polymers gain market focus. Manufacturers invest in UV-stable fabrics. These products extend service life. Reduced waste supports environmental goals. Buyers value cost efficiency over time. Regulatory pressure supports eco-friendly solutions. Innovation improves fabric strength and flexibility. This trend opens premium product opportunities. Sustainable branding attracts large farms. Long-term contracts increase supplier value. The shift improves market quality standards.
- For instance, Berry Global supplies various nonwoven and film-based products for agricultural applications (agro textiles) which require UV stabilization to ensure durability and longevity in outdoor conditions.
Technological Innovation and Product Customization
Manufacturers focus on advanced fabric designs. Mesh size customization meets crop needs. Smart textiles enable better climate control. UV-treated nets improve performance consistency. Lightweight materials ease installation. Custom solutions support diverse crops. Precision farming boosts this opportunity. Digital farming tools support textile demand. Suppliers partner with farm solution providers. Innovation helps differentiate products. Value-added features improve margins. This trend supports premium market growth. Adoption remains strong in high-value farming segments.
Key Challenges
Price Sensitivity Among Small Farmers
Cost remains a major concern for farmers. Smallholders face limited investment capacity. Agro textiles involve upfront spending. Price fluctuations affect buying decisions. Synthetic raw material costs remain unstable. Limited awareness reduces perceived value. Some farmers rely on traditional methods. Subsidy access varies by region. High-quality products appear costly initially. Replacement cycles affect budgeting. Suppliers struggle with volume sales. This challenge limits rural penetration. Education and financing remain critical needs. Overcoming price barriers stays essential for growth.
Environmental Concerns and Disposal Issues
Agro textiles rely on synthetic materials. Disposal creates environmental challenges. Improper waste handling causes pollution. Recycling infrastructure remains limited. Regulations tighten on plastic use. Farmers lack disposal guidance. Collection systems remain weak in rural areas. Environmental groups raise concerns. Manufacturers face compliance pressure. Development of biodegradable options remains costly. Product lifespan extension helps but not fully. This challenge affects brand image. Sustainable innovation becomes mandatory. Addressing disposal issues is critical for long-term acceptance.
Regional Analysis
North America
North America held about 22.9% market share in 2018. The region recorded USD 941.29 million in 2018. Strong mechanized farming supports steady demand. Farmers adopt agro textiles to improve yield stability. Shade nets and mulch mats see wide use. Climate variability increases crop protection needs. The market reached USD 1,174.43 million in 2024. It is projected to reach USD 1,686.88 million by 2032. Growth follows a CAGR of 4.7%. Government support for modern agriculture strengthens adoption. High awareness levels also support long-term demand.
Europe
Europe accounted for nearly 26.7% market share in 2018. The market size reached USD 1,099.20 million that year. Controlled farming drives steady consumption. Horticulture and floriculture lead product demand. Farmers focus on quality and yield consistency. Environmental standards shape product selection. The market reached USD 1,328.19 million in 2024. It is forecast to reach USD 1,825.63 million by 2032. The region grows at a CAGR of 4.1%. Strong greenhouse infrastructure supports stable expansion across major countries.
Asia Pacific
Asia Pacific led the market with about 34.2% share in 2018. The region recorded USD 1,407.61 million that year. Large farming bases drive high consumption. Population growth increases food demand. Protected farming expands across key economies. Fishing nets support strong aquaculture activity. The market reached USD 1,766.46 million in 2024. It is expected to reach USD 2,556.61 million by 2032. Growth follows a CAGR of 4.8%. Government programs and farm modernization remain key growth drivers.
Latin America
Latin America held nearly 9.7% market share in 2018. The market size reached USD 397.65 million that year. Export-focused agriculture supports demand growth. Shade nets and mulch mats see rising adoption. Climate exposure increases protection needs. The market reached USD 508.88 million in 2024. It is projected to reach USD 755.08 million by 2032. The region records a CAGR of 5.1%. Investment in commercial farming supports expansion. Growing awareness of yield protection improves long-term outlook.
Middle East
The Middle East captured about 4.3% market share in 2018. The market reached USD 178.47 million that year. Water scarcity drives protected cultivation. Shade nets play a critical role. Controlled farming supports food security goals. The market reached USD 229.03 million in 2024. It is forecast to reach USD 341.03 million by 2032. Growth occurs at a CAGR of 5.2%. Government investment supports advanced farming methods. Desert farming projects continue to expand demand.
Africa
Africa held around 2.1% market share in 2018. The market size reached USD 88.00 million that year. Adoption remains at an early stage. Smallholder farming dominates the region. Agro textiles support yield improvement efforts. The market reached USD 103.67 million in 2024. It is expected to reach USD 137.29 million by 2032. Growth follows a CAGR of 3.6%. Development programs encourage modern inputs. Gradual awareness growth supports steady market expansion
Market Segmentations:
By Product
- Fishing Nets
- Shade Nets
- Mulch Mats
- Anti-hail Nets
- Bird Protection Nets
- Others
By Application
- Agriculture
- Floriculture
- Horticulture
- Aquaculture
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Agro Textiles market remains moderately fragmented. Global and regional players compete on product quality, durability, and cost efficiency. Leading companies focus on shade nets, fishing nets, and mulch mats to serve core demand areas. Firms invest in UV-stabilized and high-strength materials to extend product life. Strategic partnerships with distributors improve market reach. Manufacturers expand capacity to meet rising protected farming demand. Price competition remains strong in developing regions. Innovation supports product differentiation in mature markets. Companies also strengthen after-sales support to retain customers. Sustainability efforts gain importance across portfolios. Regional players benefit from local supply chains. Competition intensifies as demand grows across agriculture, horticulture, and aquaculture segments.
Key Player Analysis
- SRF Limited
- B&V Agro Irrigation Co.
- Tama
- Belton Industries
- Neo Corp International Limited
- Diatex
- Hy-Tex (UK) Limited
- Aduno SRL
- Siang May Pte Ltd.
- HELIOS GROUP S.r.l.
Recent Developments
- In 2024, the Climate Smart Agro Textile Demonstration Center was inaugurated in Navsari, India, by the Ministry of Textiles and SASMIRA. The center, covering 15,000 sq. meters, promoted sustainable farming practices through advanced agro textile solutions. Equipped with IoT-based systems, it showcases shade nets, ground covers, pond liners, and more to boost crop productivity.
- In September 2024, Spain’s Fishing Confederation (Cepesca), National Federation of Fishermen's Guilds (FNCP), and the Galician Automotive Technology Centre (CTAG) announced that they would launch the ‘Redes de España’ project to recover over 100 tons of discarded fishing gear. Fishing net waste would also be converted into high-value materials for various sectors, including automotive, naval, and agro textiles.
Report Coverage
The research report offers an in-depth analysis based on Product, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise due to wider adoption of protected and controlled farming systems.
- Farmers will increase use of agro textiles to manage climate risks.
- Fishing nets will remain the leading product due to aquaculture growth.
- Shade nets will see strong uptake in horticulture and floriculture farming.
- Innovation will focus on UV-stable and high-durability materials.
- Sustainable and recyclable textiles will gain higher preference.
- Asia Pacific will continue to lead due to large farming activity.
- Emerging regions will adopt agro textiles through government support.
- Manufacturers will expand distribution in rural and semi-urban areas.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Focus on Crop Yield and Protection
Farmers are under increasing pressure to maximize yield per hectare and minimize losses from pests, weather, and weeds. Agro textiles such as shade nets, anti-hail nets, and mulch mats help stabilize crop growth, reduce input waste, and protect against environmental stress, driving their adoption across both developed and developing regions.
Expansion of Protected and Controlled Farming
The global shift toward greenhouses, net houses, and other protected cultivation systems is fueling demand for agro textiles, which are essential for regulating light, temperature, and pest exposure. This trend is especially strong in regions with limited arable land or harsh climates, supporting year-round production and higher-value crops.
Growth of Aquaculture and Fisheries
Rising global protein demand and the expansion of inland and coastal aquaculture are increasing the need for durable, long-life fishing nets. Modern agro textiles improve cage strength, reduce stock losses, and support sustainable fish farming, making fishing nets the largest revenue contributor in the market.
Shift Toward Sustainable and Durable Materials
There is a growing preference for UV-stabilized, recyclable, and long-lasting agro textiles that reduce replacement frequency and environmental impact. Regulatory pressures and buyer awareness are pushing manufacturers to innovate with eco-friendly materials, opening opportunities for premium products and long-term contracts.
Government Support and Subsidies for Modern Farming
Many governments are promoting the adoption of advanced agricultural practices, including the use of agro textiles, through subsidies, demonstration projects, and technical support. These initiatives help lower the cost barrier for small and large farms, accelerating market penetration and supporting food security objectives.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Agro Textile Market?
At what Compound Annual Growth Rate is the Agro Textile Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Agro Textile Market?
What are some challenges faced by the Agro Textile Market?
Who are the major players in the Agro Textile Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Fishing Nets
- 1.2.2 Shade Nets
- 1.2.3 Mulch Mats
- 1.2.4 Anti-hail Nets
- 1.2.5 Bird Protection Nets
- 1.2.6 Others
- 1.3 By Application
- 1.3.1 Agriculture
- 1.3.2 Floriculture
- 1.3.3 Horticulture
- 1.3.4 Aquaculture
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,110.7 million → 2032: USD 7,302.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Agro Textile Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Agro Textile Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Agro Textile Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Agro Textile Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Agro Textile Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Agro Textile Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Agro Textile Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Agro Textile Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,110.7 million → 2032: USD 7,302.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Agro Textile Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fishing Nets
- 12.3.7.2 Shade Nets
- 12.3.7.3 Mulch Mats
- 12.3.7.4 Anti-hail Nets
- 12.3.7.5 Bird Protection Nets
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Agriculture
- 12.4.7.2 Floriculture
- 12.4.7.3 Horticulture
- 12.4.7.4 Aquaculture
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Agro Textile End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Agro Textile Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Agro Textile Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Agro Textile Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 SRF Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Tama
- 18.4 Belton Industries
- 18.5 Neo Corp International Limited
- 18.6 Diatex
- 18.7 Hy-Tex (UK) Limited
- 18.8 Aduno SRL
- 18.9 Siang May Pte Ltd.
- 18.10 HELIOS GROUP S.r.l.
- 18.11 B&V Agro Irrigation Co.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

