
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ambulatory Care Services Market Size 2024 | USD 806.5 million |
| Ambulatory Care Services Market, CAGR | 5.10% |
| Ambulatory Care Services Market Size 2032 | USD 1,202.1million |
Market Overview:
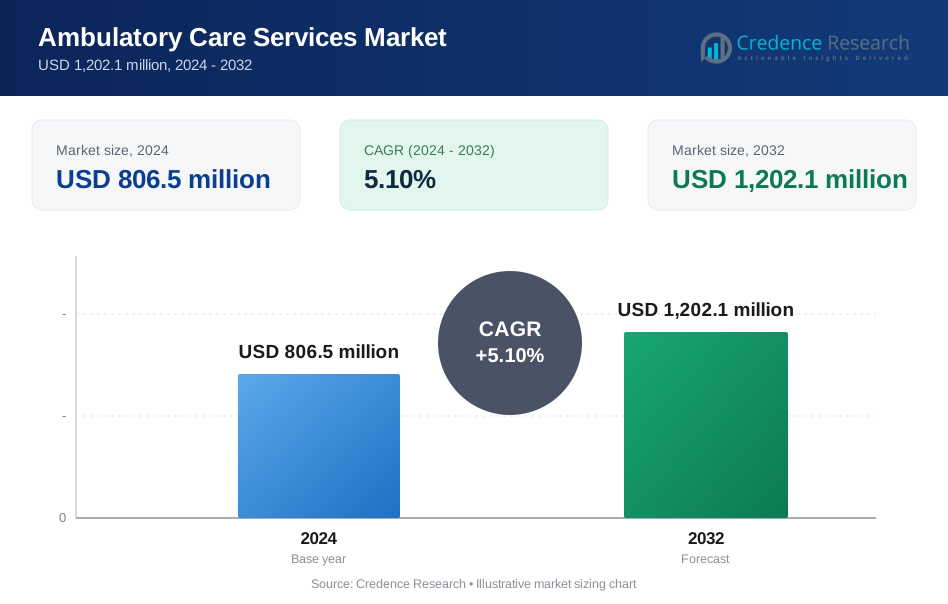
The Ambulatory Care Services Market size was valued at USD 580.5 million in 2018 to USD 806.5 million in 2024 and is anticipated to reach USD 1,202.1million by 2032, at a CAGR of 5.10% during the forecast period.
The ambulatory care services market is driven by a fundamental transformation in healthcare delivery models emphasizing accessibility, cost-efficiency, and patient convenience. A primary growth catalyst is the rising preference for outpatient care due to shorter recovery times, reduced treatment costs, and minimal hospital-associated risks. Patients increasingly seek treatments outside hospital environments, especially for minor surgeries, diagnostics, and chronic disease management. Technological innovations such as minimally invasive procedures, portable diagnostic tools, and digital health platforms have broadened the range of services offered in ambulatory settings. Chronic disease prevalence, particularly among aging populations, also necessitates frequent monitoring and care, fueling demand for outpatient visits. Furthermore, supportive government policies, value-based care initiatives, and evolving reimbursement structures incentivize providers to expand ambulatory offerings. The COVID-19 pandemic further accelerated the shift by reinforcing the need for decentralized care and digital engagement, making ambulatory services an essential, scalable, and sustainable solution across modern healthcare systems.
Regionally, North America dominates the ambulatory care services market, supported by advanced infrastructure, widespread insurance coverage, and strong regulatory frameworks. The United States, in particular, leads the global market with substantial investments in outpatient centers and high adoption of minimally invasive technologies. Europe ranks as the second-largest market, with countries like Germany, the UK, and France transitioning towards outpatient models to ease hospital burdens and control healthcare spending. Policy reforms and increased emphasis on preventive care are accelerating outpatient service expansion in the region. Asia-Pacific, however, stands out as the fastest-growing market due to rising healthcare expenditures, rapid urbanization, and growing awareness of cost-effective care options. Countries like China, India, and Japan are investing heavily in outpatient facilities and telehealth platforms to serve expanding middle-class populations. Latin America and the Middle East & Africa are gradually emerging, benefiting from public-private partnerships and digital health adoption aimed at improving access in underserved regions.
Market Insights:
- The market was valued at USD 806.5 million in 2024 and is projected to reach USD 1,202.1 million by 2032, growing at a CAGR of 5.10%.
- Outpatient care demand is increasing due to lower costs, faster recovery times, and minimal hospital-related risks.
- Technological advancements such as portable diagnostics and minimally invasive procedures are expanding the scope of ambulatory services.
- Chronic disease prevalence is driving consistent demand for outpatient monitoring, diagnostics, and follow-ups.
- Policy reforms and private investments are accelerating the development of ambulatory infrastructure worldwide.
- Workforce shortages and regulatory complexities remain key challenges, impacting service capacity and profitability.
- North America leads the market in share, while Asia-Pacific is the fastest-growing region due to healthcare investments and urban expansion.
Market Drivers:
Growing Preference for Cost-Effective and Convenient Healthcare Solutions
Patients increasingly seek healthcare options that are both affordable and accessible. The Ambulatory Care Services Market benefits from this shift, as outpatient services cost significantly less than traditional hospital stays. Consumers value the ability to receive timely care without the inconvenience of prolonged admission. It allows for faster recovery, reduced exposure to hospital-acquired infections, and lower overall healthcare spending. Payers, including insurance providers and governments, support this trend by encouraging outpatient reimbursement models. This cost-driven behavior continues to shift procedural volumes from inpatient to outpatient settings, strengthening the role of ambulatory care in modern healthcare systems.
Technological Advancements Expand the Scope of Ambulatory Procedures
Advancements in medical technology have increased the feasibility of performing complex procedures outside hospital environments. Innovations in diagnostic imaging, minimally invasive surgery, and remote monitoring have significantly broadened the capabilities of outpatient centers. It now supports services ranging from cataract removal to cardiac monitoring, once limited to inpatient settings. These developments improve care precision and patient safety while reducing time spent at medical facilities. The Ambulatory Care Services Market continues to integrate new tools and systems that enhance diagnostic accuracy and treatment efficiency. As technology becomes more portable and intelligent, outpatient facilities are better equipped to meet growing patient demands.
- For instance, Philips’ Mobile Cardiac Telemetry (MCOT) delivers up to 30 days of continuous ECG data with AI‑driven arrhythmia detection validated across 41 clinical studies.
Rising Burden of Chronic Diseases Increases Demand for Ongoing Outpatient Care
The global rise in chronic conditions such as diabetes, hypertension, and cardiovascular disorders drives consistent demand for regular medical supervision. It prompts a need for scalable and efficient care solutions that do not overwhelm hospital infrastructure. The Ambulatory Care Services Market addresses this challenge by providing ongoing disease management through check-ups, diagnostics, and follow-up visits. These services help patients maintain their health and prevent complications without the need for hospitalization. Frequent monitoring and preventive interventions align well with the outpatient model, making it a preferred channel for chronic disease care. Health systems now rely on ambulatory platforms to manage long-term patient engagement effectively.
Policy Reforms and Industry Investment Encourage Outpatient Infrastructure Expansion
Governments and private investors are actively promoting outpatient care expansion to improve healthcare delivery. Policy reforms in reimbursement, licensing, and provider incentives are lowering barriers for ambulatory center development. It has led to a significant increase in standalone surgical centers, diagnostic hubs, and specialty clinics worldwide. The Ambulatory Care Services Market gains from such policy support, which fosters competition, innovation, and broader access to care. Investors see outpatient models as scalable and efficient, supporting consistent funding for new projects. This combination of regulatory momentum and financial commitment accelerates the integration of ambulatory services into mainstream healthcare systems.
- For instance, MinuteClinic now operates over 1,100 locations, many offering primary care, vaccinations, and chronic condition services covered at low or no cost under major insurance plans.
Market Trends:
Integration of Telehealth and Virtual Care into Outpatient Services
Telehealth has transitioned from a niche offering to a core feature within outpatient care. Providers now integrate virtual consultations, remote diagnostics, and digital follow-ups into standard workflows. The Ambulatory Care Services Market reflects this evolution, with facilities adopting hybrid models that combine in-person visits and virtual care. It enhances patient engagement, particularly for those in rural or underserved areas, and reduces unnecessary travel and wait times. The shift supports chronic care monitoring, mental health services, and post-operative consultations with greater efficiency. Health systems are investing in digital infrastructure to support seamless patient-provider interaction across multiple platforms.
Expansion of Specialty Clinics and Procedure-Specific Centers
Outpatient care is moving beyond general services to include highly specialized offerings. The emergence of procedure-specific centers for orthopedics, dermatology, oncology, and fertility reflects rising demand for tailored care environments. The Ambulatory Care Services Market shows increased interest in facilities designed for single-specialty use, allowing for streamlined operations and better outcomes. It enables providers to allocate resources more efficiently and attract patients seeking focused expertise. These specialized clinics often employ advanced tools and personalized protocols, improving patient satisfaction and clinical results. The trend supports the decentralization of specialty care from large hospitals to accessible ambulatory settings.
- For instance, Oak Street Health a primary care network acquired by CVS Health-expanded to over 170 centers by 2024, with multidisciplinary teams and virtual specialty care integrations following its 2021 acquisition of RubiconMD.
Data-Driven Decision-Making and Real-Time Clinical Monitoring
Healthcare providers now rely more heavily on data analytics to guide clinical and operational decisions. Outpatient centers are integrating real-time patient data into their workflows to improve treatment planning and resource allocation. The Ambulatory Care Services Market is evolving into a digitally enabled ecosystem where predictive analytics, electronic health records, and clinical dashboards drive efficiency. It enhances diagnostic accuracy, reduces administrative errors, and supports proactive intervention. Data-sharing platforms also enable better coordination between primary care, specialists, and ancillary services. This trend supports a more personalized, outcomes-focused approach to ambulatory care delivery.
Growing Role of Private Equity and Retail Healthcare Chains
Private investors and consumer-facing health brands are entering the outpatient care space with aggressive growth strategies. Retail healthcare chains, pharmacy-backed clinics, and investor-owned ambulatory centers are transforming service models. The Ambulatory Care Services Market is becoming more competitive, with non-traditional players introducing new operational standards and customer experiences. It leads to increased clinic accessibility, extended hours, and transparent pricing structures aimed at consumer convenience. These entrants often bring retail best practices, such as streamlined check-in processes and customer feedback systems. Their presence is reshaping expectations around how outpatient care is delivered and consumed.
- For instance, CVS Health’s acquisition of Oak Street Health in May 2023 for USD 10.6 billion exemplifies strong investor confidence in retail‑oriented outpatient models.
Market Challenges Analysis:
Workforce Shortages and Operational Constraints Affect Service Quality
Staffing challenges continue to strain the efficiency and scalability of outpatient care centers. The Ambulatory Care Services Market faces rising demand, yet struggles with shortages of skilled professionals such as nurses, anesthesiologists, and technicians. It creates scheduling bottlenecks, limits procedure volumes, and increases provider burnout. Many centers operate with lean teams, making it difficult to maintain consistent quality during peak hours or unexpected surges in patient flow. Training requirements for new technologies and outpatient procedures further add to the burden. Without adequate staffing and workflow optimization, many facilities risk compromising patient experience and clinical outcomes.
Regulatory Complexity and Reimbursement Uncertainty Slow Market Expansion
Ambulatory providers must navigate a complex regulatory environment that varies widely across regions and service types. The Ambulatory Care Services Market encounters obstacles from inconsistent licensing rules, evolving accreditation standards, and shifting reimbursement policies. It can delay new facility launches, discourage investment, and reduce profitability. Many outpatient centers rely on reimbursement from public or private insurers, yet face delays, denials, or coverage limitations that impact cash flow. Smaller and independent clinics often lack the administrative capacity to manage compliance requirements and appeals processes efficiently. These regulatory and financial uncertainties hinder the long-term planning and scalability of ambulatory care operations.
Market Opportunities:
Expansion into Underserved and Rural Areas Presents Growth Potential
A significant opportunity lies in expanding outpatient services to underserved and rural regions. These areas often lack access to hospital-based care, creating unmet demand for diagnostics, minor procedures, and chronic disease management. The Ambulatory Care Services Market can address this gap by establishing decentralized, low-cost facilities with targeted service offerings. It allows healthcare providers to extend reach while reducing strain on urban hospitals. Mobile units, satellite clinics, and telehealth integration can help deliver scalable care models. Governments and private investors are increasingly supporting initiatives aimed at bridging the rural healthcare divide.
Rising Demand for Preventive and Wellness-Oriented Care Creates New Avenues
The growing focus on preventive health and wellness creates new business models for outpatient services. Patients seek regular screenings, vaccinations, lifestyle counseling, and early intervention services without hospital involvement. The Ambulatory Care Services Market stands to benefit from this shift toward proactive care delivery. It supports integrated service lines that combine diagnostics, health education, and follow-up within a single outpatient visit. Employers, insurers, and health-conscious consumers are driving demand for preventive offerings. These trends align well with ambulatory care’s strengths in speed, accessibility, and efficiency.
Market Segmentation Analysis:
The Ambulatory Care Services Market comprises a diverse range of services segmented by both service type and application, each contributing uniquely to market growth.
By service type, primary care offices form the backbone of outpatient services, delivering preventive and routine care to a broad patient base. Outpatient departments offer diagnostic and follow-up services in hospitals without requiring overnight stays, while emergency departments handle acute, non-life-threatening cases, easing the load on full-scale emergency rooms. Surgical specialty centers support same-day procedures with minimal complications, expanding the market’s scope through cost-effective interventions.
- For instance, U.S. hospitals perform over 23 million procedures annually via ambulatory surgery centers and hospital outpatient departments, reflecting widespread reliance on these platforms.
By application, ophthalmology holds a substantial share due to the rising prevalence of cataracts and age-related vision issues. Orthopedics follows closely, with outpatient joint procedures and rehabilitation gaining traction. Gastroenterology benefits from a high volume of routine screenings and minor endoscopic procedures. Pain management services address chronic conditions with non-invasive therapies, offering alternatives to long-term hospital care. Other applications, including dermatology and urology, continue to grow as outpatient models evolve, reinforcing the market’s adaptability and reach.
- For instance, cataract surgery now accounts for approximately 18.7% of Medicare-covered ASC procedures, making it the most frequent ASC procedure in 2022.
Segmentation:
By Service Type:
- Primary Care Offices
- Outpatient Departments
- Emergency Departments
- Surgical Specialty
By Application:
- Ophthalmology
- Orthopedics
- Gastroenterology
- Pain Management
- Other Applications
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The North America Ambulatory Care Services Market size was valued at USD 191.55 million in 2018 to USD 266.89 million in 2024 and is anticipated to reach USD 399.23 million by 2032, at a CAGR of 5.1% during the forecast period. North America holds the largest share of the global Ambulatory Care Services Market, accounting for nearly 33% in 2024. It benefits from a mature healthcare infrastructure, a strong payer system, and widespread adoption of outpatient surgical centers and urgent care facilities. The U.S. drives regional growth with increased investments in value-based care and outpatient reimbursement models. It also leads in the integration of digital health platforms, enabling more efficient care delivery. Demand for minimally invasive procedures and preventive services continues to rise. The region’s established regulatory framework and innovation-driven environment further support the long-term expansion of ambulatory care services.
The Europe Ambulatory Care Services Market size was valued at USD 155.45 million in 2018 to USD 202.93 million in 2024 and is anticipated to reach USD 276.49 million by 2032, at a CAGR of 3.9% during the forecast period. Europe holds a 25% share of the global Ambulatory Care Services Market in 2024, driven by increasing public healthcare expenditure and the decentralization of care. Countries like Germany, the United Kingdom, and France continue to expand outpatient networks to reduce pressure on hospitals. It is supported by favorable policy reforms aimed at improving efficiency and cutting healthcare costs. Patient preference is shifting toward faster, community-based care for diagnostics and routine procedures. Efforts to integrate outpatient care into national health systems enhance coordination across services. Investment in ambulatory infrastructure and digital record-keeping continues to strengthen regional capabilities.
The Asia Pacific Ambulatory Care Services Market size was valued at USD 120.50 million in 2018 to USD 175.18 million in 2024 and is anticipated to reach USD 276.49 million by 2032, at a CAGR of 5.9% during the forecast period. Asia Pacific accounts for 22% of the Ambulatory Care Services Market in 2024 and represents the fastest-growing region globally. It benefits from rising urbanization, healthcare digitization, and expanding middle-class populations demanding accessible care. China, India, and Japan lead regional development, with growing investments in diagnostic clinics, ambulatory surgical centers, and telehealth platforms. It supports rapid service expansion in both public and private sectors. Population aging and increasing chronic disease prevalence further push outpatient service demand. The region’s growth is supported by strategic healthcare policies and infrastructure development across key economies.
The Latin America Ambulatory Care Services Market size was valued at USD 61.06 million in 2018 to USD 86.51 million in 2024 and is anticipated to reach USD 132.23 million by 2032, at a CAGR of 5.4% during the forecast period. Latin America contributes 11% to the global Ambulatory Care Services Market in 2024. Brazil and Mexico lead the region with a rising number of private outpatient clinics and specialty centers. It reflects a shift toward cost-effective and convenient care, particularly among urban populations. Regional growth is supported by government partnerships and investment in mobile clinics and community-based health programs. Challenges in rural access are prompting innovations in telehealth and decentralized care delivery. Outpatient service models continue to evolve in response to high demand for basic diagnostics, maternal health, and chronic disease care.
The Middle East Ambulatory Care Services Market size was valued at USD 36.80 million in 2018 to USD 55.49 million in 2024 and is anticipated to reach USD 91.36 million by 2032, at a CAGR of 6.4% during the forecast period. The Middle East accounts for approximately 7% of the global Ambulatory Care Services Market in 2024 and shows strong growth potential. Countries such as the UAE and Saudi Arabia are rapidly building outpatient infrastructure within broader national healthcare transformation strategies. It supports demand for preventive care, wellness services, and day surgeries across growing urban centers. Investment from public-private partnerships is accelerating the establishment of high-quality outpatient facilities. Medical tourism and digital health integration further enhance service delivery. The region’s favorable regulatory reforms and focus on localized care models drive sustained market growth.
The Africa Ambulatory Care Services Market size was valued at USD 15.09 million in 2018 to USD 19.55 million in 2024 and is anticipated to reach USD 26.33 million by 2032, at a CAGR of 3.8% during the forecast period. Africa holds a 3% share of the Ambulatory Care Services Market in 2024, with development primarily concentrated in South Africa, Nigeria, and Kenya. It faces persistent healthcare access challenges but shows gradual progress in expanding outpatient care. Community health programs and donor-funded initiatives are helping scale basic services. It increasingly leverages mobile health units and digital platforms to reach underserved populations. The private sector plays a growing role in developing urban outpatient clinics. While growth remains modest, long-term potential exists with continued investment and policy support for decentralized healthcare delivery.
Key Player Analysis:
- Aspen Healthcare
- Healthway Medical Group
- Medical Facilities Corporation
- NueHealth
- Sheridan Healthcare
- DaVita Healthcare
- LVL Medical Group
- Sonic Healthcare Limited
- Tenet Health
- HCA Holdings, Inc.
- Surgery Partners, LLC
- Other Key Players
Competitive Analysis:
The Ambulatory Care Services Market is highly competitive, with a mix of hospital-owned outpatient departments, independent centers, and specialized clinics. Key players include HCA Healthcare, Tenet Healthcare, Universal Health Services, Mayo Clinic, and Kaiser Permanente. It features continuous expansion through acquisitions, partnerships, and the development of procedure-specific facilities. Companies focus on improving service efficiency, integrating telehealth solutions, and enhancing patient experience to gain a competitive edge. Strategic investments in digital infrastructure, electronic health records, and real-time data analytics support operational scalability. Independent providers compete by offering specialized services and flexible care models. The market remains dynamic, driven by innovation, regulatory shifts, and evolving consumer expectations.
Recent Developments:
- In January 2025, Ardent Health announced the acquisition of 18 urgent care clinics from NextCare Urgent Care, expanding its ambulatory operations across New Mexico and Oklahoma. This move significantly increases Ardent Health’s presence in the urgent care segment, supporting its mission to create a consumer-focused ecosystem and provide more convenient access points for patients.
- In January 2024, AmSurg, a leader in ambulatory surgery center services, acquired an ownership interest in Texarkana Surgery Center. This acquisition is part of AmSurg’s ongoing strategy to strengthen its ambulatory surgery center portfolio and expand its reach in key outpatient markets.
- In January 2024, Veradigm acquired Koha Health, enhancing its expertise in musculoskeletal medicine and improving its ability to deliver revenue cycle services to ambulatory healthcare providers and surgical centers. This acquisition supports Veradigm’s goal to offer comprehensive solutions for ambulatory practice.
- In December 2023, Cleveland Clinic (London) announced the launch of a new medical care center dedicated to outpatient activities. This development marks a significant expansion of their ambulatory care services, aiming to provide advanced outpatient care and enhance patient access to specialized medical services.
Market Concentration & Characteristics:
The Ambulatory Care Services Market is moderately fragmented, characterized by a diverse mix of large healthcare systems, private equity-backed outpatient networks, and independent specialty clinics. It features low entry barriers in some regions, encouraging regional players and niche providers to operate alongside major health systems. The market offers high service flexibility, supports rapid patient turnover, and relies heavily on operational efficiency. It continues to evolve with advancements in minimally invasive procedures, digital health integration, and patient-centered care models. It shows strong adaptability to policy shifts, consumer behavior, and technological adoption, shaping its dynamic structure and growth potential.
Report Coverage:
The research report offers an in-depth analysis based on Services Type and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market will expand with increasing demand for outpatient procedures due to rising healthcare costs and patient preference for convenience.
- Technological innovation will enhance service capabilities, enabling more complex diagnostics and treatments in ambulatory settings.
- Telehealth integration will become a standard component, improving access and continuity of care across urban and rural areas.
- Private equity investment will intensify, driving consolidation and modernization of independent clinics and specialty centers.
- Value-based care models will encourage further transition from inpatient to outpatient services.
- Specialized ambulatory centers will gain prominence, focusing on high-demand areas like orthopedics, oncology, and cardiology.
- Emerging markets in Asia, Latin America, and the Middle East will offer significant growth opportunities through infrastructure development.
- Artificial intelligence and data analytics will streamline operations, optimize scheduling, and enhance patient outcomes.
- Regulatory reforms will shape market dynamics by redefining reimbursement, quality standards, and facility accreditation.
- Consumer expectations for transparent pricing and personalized experiences will influence service delivery and competitive positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Preference for Cost-Effective and Convenient Healthcare Solutions
Patients and payers are increasingly opting for outpatient care due to its lower costs, faster recovery times, and reduced risk of hospital-acquired infections. This shift is moving procedural volumes from inpatient to ambulatory settings, strengthening the market.
Technological Advancements Expand the Scope of Ambulatory Procedures
Innovations in minimally invasive surgery, portable diagnostics, and digital health platforms have enabled more complex procedures to be performed safely outside hospitals, broadening the range of services ambulatory centers can offer.
Rising Burden of Chronic Diseases
The increasing prevalence of chronic conditions such as diabetes and cardiovascular diseases requires frequent monitoring and follow-up, which ambulatory care centers are well-positioned to provide efficiently and cost-effectively.
Policy Reforms and Industry Investment
Supportive government policies, value-based care initiatives, and private investments are accelerating the development and expansion of ambulatory care infrastructure, making outpatient services more accessible and scalable.
Integration of Telehealth and Virtual Care
The adoption of telehealth and digital platforms in ambulatory care settings is improving access, especially in rural and underserved areas, and enabling hybrid care models that enhance patient engagement and continuity of care.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Ambulatory Care Services Market?
What are the key segments within the Ambulatory Care Services Market?
What are some challenges faced by the Ambulatory Care Services Market?
Who are the major players in the Ambulatory Care Services Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Ophthalmology
- 1.2.2 Orthopedics
- 1.2.3 Gastroenterology
- 1.2.4 Pain Management
- 1.2.5 Other Applications
- 1.3 By Service Type
- 1.3.1 Primary Care Offices
- 1.3.2 Outpatient Departments
- 1.3.3 Emergency Departments
- 1.3.4 Surgical Specialty Centers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 806.5 million → 2032: USD 1,202.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ambulatory Care Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ambulatory Care Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Ambulatory Care Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Ambulatory Care Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ambulatory Care Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ambulatory Care Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ambulatory Care Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ambulatory Care Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 806.5 million → 2032: USD 1,202.1 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ambulatory Care Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Ophthalmology
- 12.3.6.2 Orthopedics
- 12.3.6.3 Gastroenterology
- 12.3.6.4 Pain Management
- 12.3.6.5 Other Applications
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Primary Care Offices
- 12.4.6.2 Outpatient Departments
- 12.4.6.3 Emergency Departments
- 12.4.6.4 Surgical Specialty Centers
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ambulatory Care Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Ambulatory Care Services Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Ambulatory Care Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Ambulatory Care Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 HCA Healthcare
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Tenet Healthcare
- 18.4 Universal Health Services
- 18.5 Mayo Clinic
- 18.6 Kaiser Permanente
- 18.7 Sonic Healthcare Limited
- 18.8 DaVita Healthcare
- 18.9 Surgery Partners, LLC
- 18.10 Aspen Healthcare
- 18.11 Healthway Medical Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

