
Market Overview:
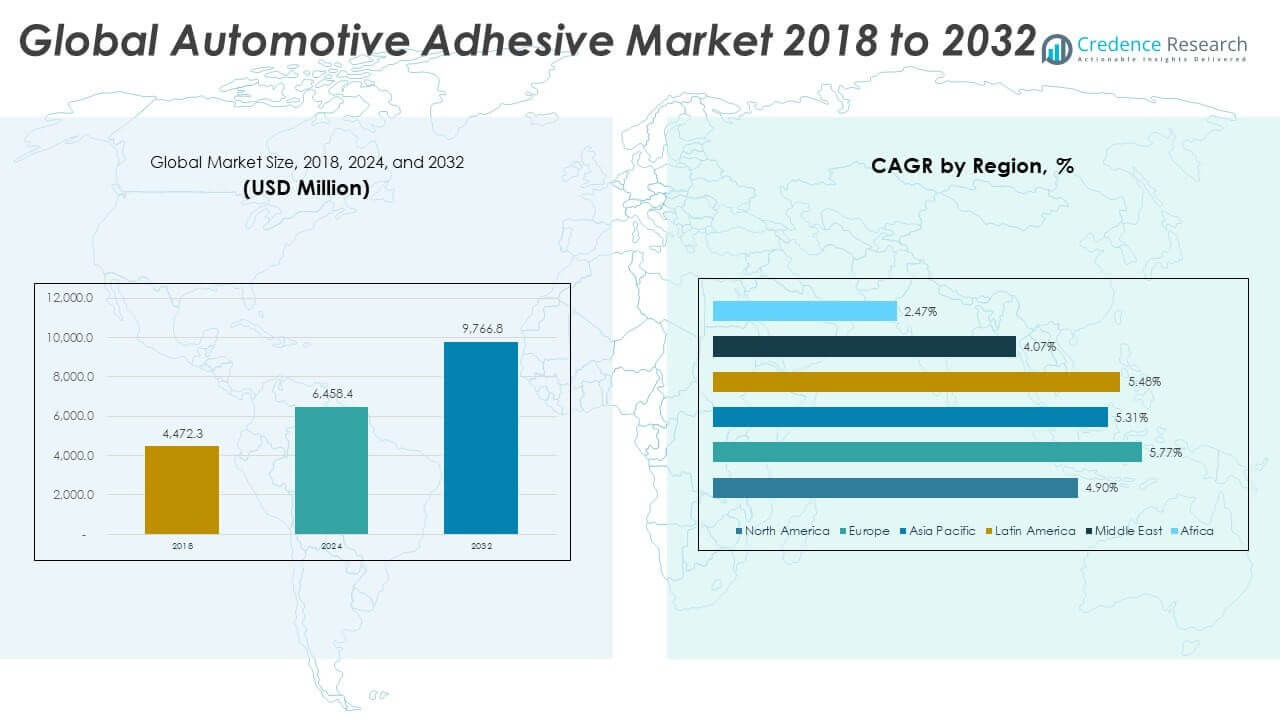
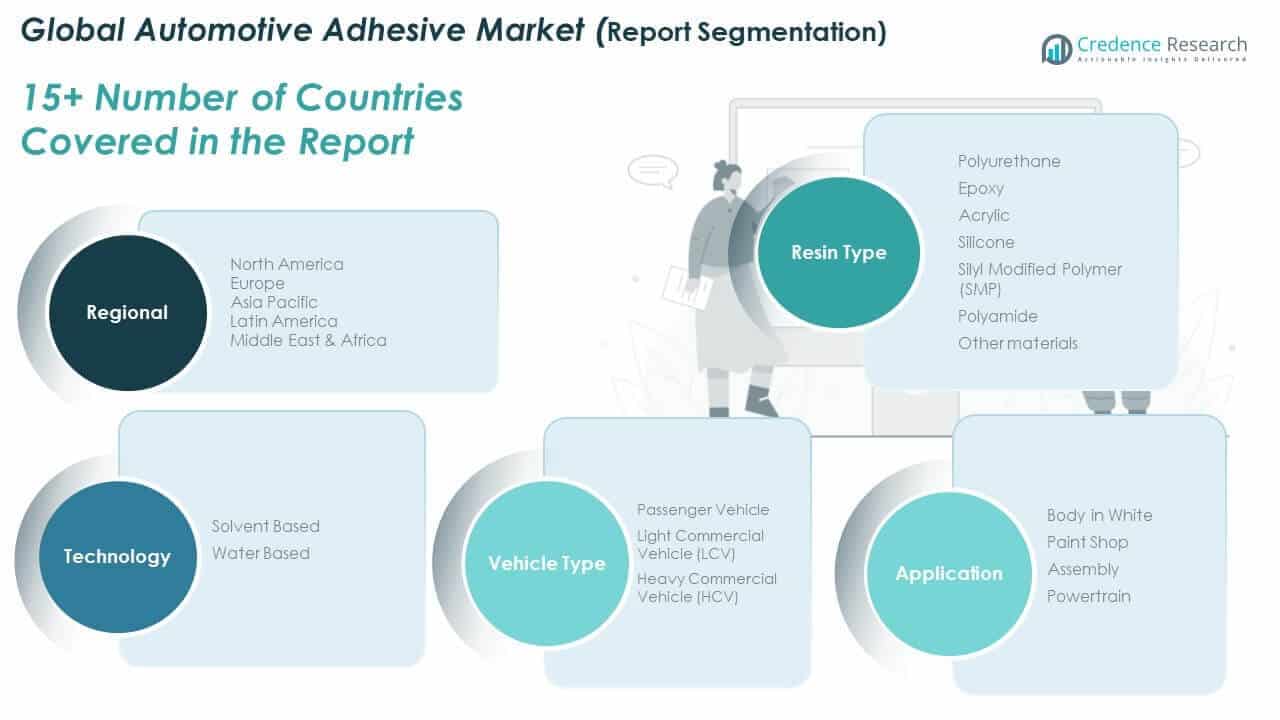
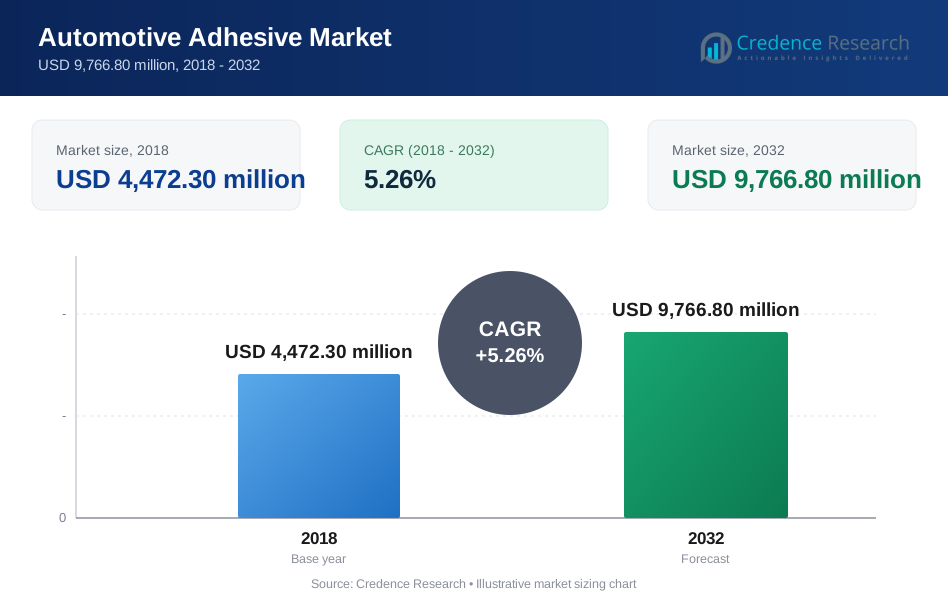
The Global Automotive Adhesive Market size was valued at USD 4,472.30 million in 2018 to USD 6,458.40 million in 2024 and is anticipated to reach USD 9,766.80 million by 2032, at a CAGR of 5.26% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Adhesive Market Size 2024 | USD 6,458.40 million |
| Automotive Adhesive Market, CAGR | 5.26% |
| Automotive Adhesive Market Size 2032 | USD 9,766.80 million |
Market growth is driven by lightweight vehicle design priorities across automakers. Manufacturers replace mechanical fasteners with adhesives to reduce weight and improve fuel efficiency. Electric vehicle production increases adhesive use in battery packs and structural parts. Safety standards encourage stronger bonding solutions for crash performance. Automakers seek noise and vibration reduction through advanced bonding systems. Adhesives support mixed-material bonding in aluminum, composites, and plastics. Automation in assembly lines also favors adhesive solutions. These factors sustain consistent demand growth.
Asia Pacific leads the market due to high vehicle production volumes and strong OEM presence. China, Japan, and South Korea drive demand through mass manufacturing and electric vehicle expansion. Europe follows with focus on lightweight engineering and emission reduction policies. Germany and France support advanced adhesive adoption in premium vehicles. North America shows steady demand from electric and pickup vehicle production. Emerging markets in Latin America and Southeast Asia gain traction due to rising automotive manufacturing investments.
Market Insights:
- The Global Automotive Adhesive Market was valued at USD 4,472.30 million in 2018, reached USD 6,458.40 million in 2024, and is projected to hit USD 9,766.80 million by 2032, growing at a CAGR of 5.26%.
- Asia Pacific leads with about 34.9% share due to high vehicle production, Europe follows with around 27.8% driven by lightweight and premium vehicle focus, and North America holds nearly 23.6% supported by electric vehicle adoption and advanced manufacturing.
- Europe is the fastest-growing region with a 27.8% share, supported by the highest CAGR of 5.77%, strict emission norms, and strong adoption of structural bonding technologies.
- By technology, water-based adhesives account for nearly 55% share, reflecting OEM preference for low-emission and safer formulations across assembly and interior applications.
- Solvent-based adhesives hold about 45% share, supported by continued use in high-strength and durability-critical automotive applications.
Market Drivers:
Rising Lightweight Vehicle Design And Structural Efficiency Requirements
The Global Automotive Adhesive Market benefits from strong lightweight design priorities. Automakers reduce vehicle mass to meet fuel efficiency targets. Adhesives replace welds and bolts across body structures. This shift improves load distribution and joint durability. Carmakers prefer bonding for aluminum and composite panels. Structural bonding supports modern crash safety designs. Assembly flexibility improves across multi-material platforms. These factors strengthen adhesive adoption across vehicle programs.
- For instance, the BMW 7 Series body-in-white incorporates a "Carbon Core" using approximately 130 meters of structural adhesives to join carbon fiber-reinforced plastic, aluminum, and high-strength steel. This advanced multi-material construction method reduced the body-in-white weight by 40 kg compared to its predecessor.
Growing Electric Vehicle Production And Battery Assembly Demand
The Global Automotive Adhesive Market gains traction from electric vehicle expansion. Electric platforms require advanced bonding for battery modules. Adhesives improve thermal stability and vibration control. Cell-to-pack designs rely on high-performance bonding systems. Automakers prefer adhesives for insulation and safety protection. Lightweight battery enclosures support driving range goals. Battery durability remains a key design focus. This trend sustains steady adhesive demand.
- For instance, Tesla’s structural battery pack bonds cells directly into the pack, increasing rigidity and reducing parts count.
Stricter Vehicle Safety And Durability Performance Standards
The Global Automotive Adhesive Market responds to stricter safety regulations. Governments enforce higher crash and durability benchmarks. Adhesives enhance energy absorption during impact events. Bonded joints reduce stress concentration across structures. Carmakers adopt adhesives to meet long-term reliability goals. Structural integrity supports passenger protection outcomes. Safety testing favors uniform load transfer. These requirements reinforce adhesive integration.
Expansion Of Automated And High-Speed Vehicle Assembly Lines
The Global Automotive Adhesive Market aligns with advanced manufacturing automation. Modern plants demand faster and cleaner assembly methods. Adhesives support robotic dispensing and curing systems. Consistent bond quality improves production repeatability. Reduced rework supports cost efficiency targets. Assembly speed increases without compromising joint strength. Process control remains a key benefit. Automation trends sustain adhesive usage growth.
Market Trends:
Shift Toward Low Emission And Sustainable Adhesive Formulations
The Global Automotive Adhesive Market trends toward eco-friendly product development. Manufacturers reduce solvent content and emissions. Water-based and reactive systems gain preference. Sustainability goals influence supplier selection decisions. Carmakers assess lifecycle environmental impact carefully. Regulatory pressure supports cleaner chemistry adoption. Material transparency improves across supply chains. Sustainability shapes future adhesive portfolios.
- For instance, Henkel reports that many LOCTITE water-based automotive adhesives cut solvent emissions by over 50%.
Rising Customization Across Vehicle Models And Platforms
The Global Automotive Adhesive Market reflects growing platform customization. Carmakers design flexible architectures for multiple variants. Adhesives support adaptable bonding across different components. Mixed designs require versatile bonding performance. Platform sharing increases across regions and brands. Adhesive suppliers tailor solutions for modular builds. Production complexity favors flexible materials. Customization trends influence product innovation.
- For instance, Volkswagen's MQB platform supports over 40 models (such as the VW Golf, Tiguan, Audi A3, and SEAT Leon) using common, standardized production processes, including extensive adhesive bonding techniques.
Increased Focus On Noise Vibration And Harshness Control
The Global Automotive Adhesive Market sees higher focus on cabin comfort. Carmakers target quieter and smoother ride quality. Adhesives dampen vibration and reduce noise transfer. Interior bonding improves acoustic insulation performance. Consumer expectations shape comfort-related design choices. Premium vehicle segments lead this trend. Comfort enhancements extend into mass-market models. Adhesives support this evolving focus.
Digital Simulation And Virtual Validation In Adhesive Selection
The Global Automotive Adhesive Market adopts digital engineering tools. Carmakers use simulation to test bond performance early. Virtual validation reduces physical prototyping needs. Design teams assess stress and fatigue digitally. Adhesive behavior prediction improves material selection accuracy. Development timelines shorten with digital support. Engineering confidence increases across programs. Digital tools shape purchasing decisions.
Market Challenges Analysis:
Complex Surface Preparation And Material Compatibility Requirements
The Global Automotive Adhesive Market faces material compatibility challenges. Vehicle designs use diverse substrates and coatings. Surface preparation remains critical for bond strength. Inconsistent preparation leads to performance risks. Automakers demand strict process control standards. Training gaps affect assembly quality outcomes. Environmental factors impact curing reliability. These issues increase operational complexity.
Price Sensitivity And Qualification Time For New Adhesive Systems
The Global Automotive Adhesive Market experiences pricing pressure. Carmakers negotiate aggressively on material costs. Adhesives undergo long qualification cycles before approval. Testing and validation increase supplier entry barriers. Cost reduction targets strain supplier margins. Platform lock-in limits rapid material switching. Innovation cycles face delays due to approvals. These constraints slow adoption pace.
Market Opportunities:
Growth Potential Across Emerging Automotive Manufacturing Regions
The Global Automotive Adhesive Market finds opportunity in emerging regions. Automotive production expands in Southeast Asia and Latin America. New plants adopt modern bonding technologies from launch. Infrastructure investment supports advanced assembly practices. Local sourcing initiatives increase regional demand. OEM expansion creates supplier partnership opportunities. Technology transfer supports faster market penetration. These regions offer long-term growth potential.
Advancement In Smart Adhesives And Functional Bonding Solutions
The Global Automotive Adhesive Market benefits from functional material innovation. Smart adhesives offer sensing and thermal management features. Multifunctional bonding reduces component count. Carmakers explore integrated performance materials actively. Functional bonding supports next-generation vehicle design. Innovation aligns with electric and autonomous platforms. Value-added features improve supplier differentiation. This area presents strong opportunity space.
Market Segmentation Analysis:
By Resin Type
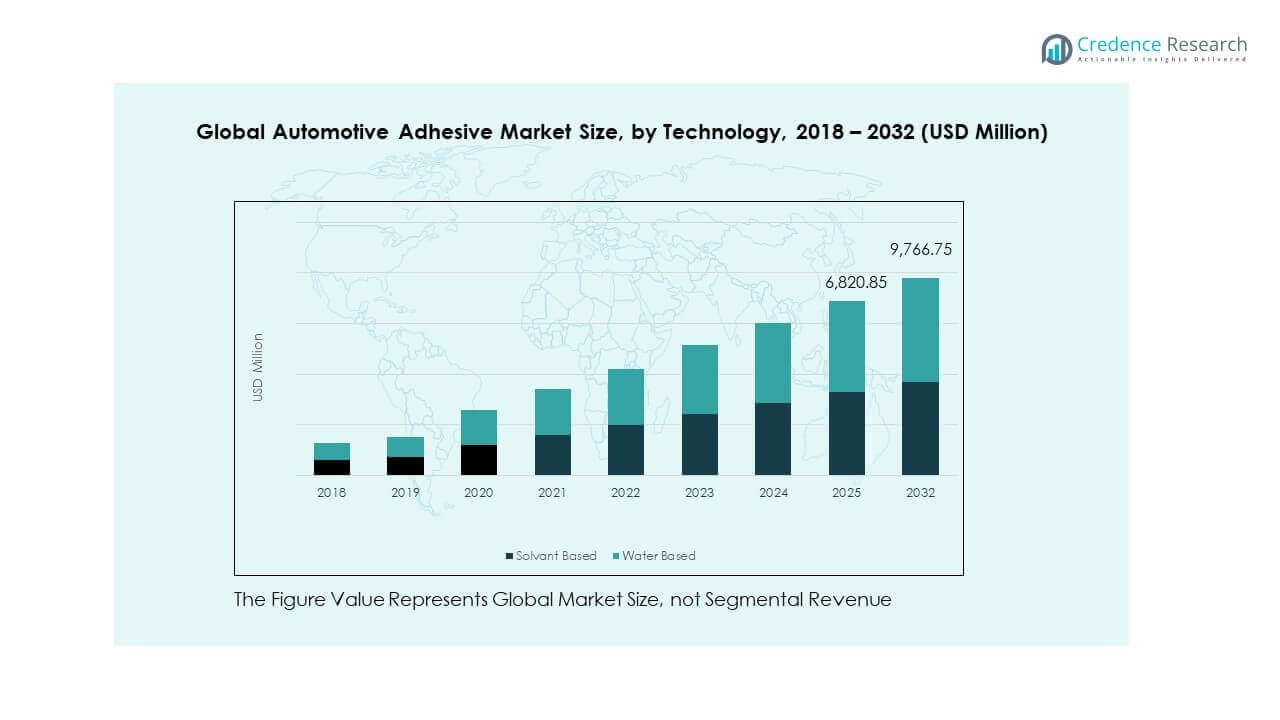
The Global Automotive Adhesive Market shows diverse demand across resin types. Polyurethane leads due to flexibility, durability, and strong structural bonding. Epoxy supports high-strength joints in load-bearing applications. Acrylic offers fast curing and surface tolerance across mixed materials. Silicone serves thermal resistance and sealing needs. Silyl Modified Polymer supports elasticity and weather resistance. Polyamide finds use in heat-resistant applications. Other materials address niche performance needs across specialized components.
- For instance, Sika adhesive technologies "light the way" for more than 35 million vehicles annually through headlamp bonding, while their structural body shop adhesives make over 25 million vehicles stronger and safer each year.
By Technology
Solvent-based adhesives retain use in high-strength automotive applications. These systems support durability under harsh operating conditions. Water-based adhesives gain preference due to low emissions and regulatory alignment. Carmakers adopt water-based systems for interior and lightweight components. Production lines value safer handling and lower environmental impact. Technology selection depends on performance needs and compliance goals.
By Vehicle Type
Passenger vehicles account for the largest adhesive demand. High production volumes and design complexity drive usage. Light commercial vehicles adopt adhesives for weight reduction and durability. Heavy commercial vehicles rely on adhesives for structural stability and vibration control. Vehicle electrification increases adhesive use across all categories. Platform standardization supports consistent material adoption.
By Application
Body in white represents a core application area. Structural bonding improves rigidity and crash performance. Paint shop applications support sealing and corrosion protection. Assembly operations use adhesives for interior and exterior parts. Powertrain applications demand heat and chemical resistance. Application diversity supports steady demand across vehicle systems.
Segmentation:
By Resin Type- Polyurethane
- Epoxy
- Acrylic
- Silicone
- Silyl Modified Polymer (SMP)
- Polyamide
- Other Materials
- Solvent Based
- Water Based
- Passenger Vehicle
- Light Commercial Vehicle (LCV)
- Heavy Commercial Vehicle (HCV)
- Body in White
- Paint Shop
- Assembly
- Powertrain
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Automotive Adhesive Market size was valued at USD 1,078.27 million in 2018 to USD 1,526.39 million in 2024 and is anticipated to reach USD 2,246.35 million by 2032, at a CAGR of 4.90% during the forecast period. The Global Automotive Adhesive Market in North America holds nearly 23.6% market share. The United States drives regional demand through advanced vehicle manufacturing. Automakers adopt adhesives for lightweight and safety-focused designs. Electric vehicle platforms support higher adhesive usage. Canada supports demand through stable OEM operations. Mexico benefits from cross-border automotive production. Technology adoption remains high across assembly plants. Regulatory clarity supports material standardization. Supplier partnerships remain strong across the region.
Europe
The Europe Global Automotive Adhesive Market size was valued at USD 1,207.52 million in 2018 to USD 1,796.35 million in 2024 and is anticipated to reach USD 2,822.59 million by 2032, at a CAGR of 5.77% during the forecast period. The Global Automotive Adhesive Market in Europe accounts for about 27.8% market share. Germany leads through premium and performance vehicle output. France and Italy support demand via structural bonding adoption. Emission norms push lightweight material usage. Adhesives support multi-material vehicle platforms. OEM focus on safety strengthens structural bonding demand. Innovation centers influence material selection. Strong supplier compliance supports growth. Regional demand remains technology driven.
Asia Pacific
The Asia Pacific Global Automotive Adhesive Market size was valued at USD 1,555.46 million in 2018 to USD 2,252.31 million in 2024 and is anticipated to reach USD 3,418.36 million by 2032, at a CAGR of 5.31% during the forecast period. The Global Automotive Adhesive Market in Asia Pacific leads with nearly 34.9% market share. China dominates through large-scale vehicle production. Japan and South Korea support advanced adhesive applications. India shows rising adoption due to manufacturing expansion. Electric mobility strengthens adhesive demand across platforms. Cost-efficient production attracts global OEMs. Local suppliers gain technical capability. High volumes support consistent material demand.
Latin America
The Latin America Global Automotive Adhesive Market size was valued at USD 333.19 million in 2018 to USD 487.24 million in 2024 and is anticipated to reach USD 749.11 million by 2032, at a CAGR of 5.48% during the forecast period. The Global Automotive Adhesive Market in Latin America represents around 7.5% market share. Brazil anchors regional automotive output. Mexico supports export-driven vehicle assembly. Adhesive use grows in structural and interior parts. OEM investments improve material standards. Cost control remains a key focus. Technology transfer supports quality improvement. Demand shows steady upward movement.
Middle East
The Middle East Global Automotive Adhesive Market size was valued at USD 213.78 million in 2018 to USD 289.89 million in 2024 and is anticipated to reach USD 400.44 million by 2032, at a CAGR of 4.07% during the forecast period. The Global Automotive Adhesive Market in the Middle East holds about 4.5% market share. GCC countries lead regional demand. Vehicle assembly and aftermarket support growth. Infrastructure projects increase commercial vehicle usage. Adhesives support durability in harsh climates. Import reliance shapes supply dynamics. Technology adoption remains selective. Growth follows gradual industrial expansion.
Africa
The Africa Global Automotive Adhesive Market size was valued at USD 84.08 million in 2018 to USD 106.19 million in 2024 and is anticipated to reach USD 129.90 million by 2032, at a CAGR of 2.47% during the forecast period. The Global Automotive Adhesive Market in Africa accounts for nearly 1.6% market share. South Africa leads automotive manufacturing activity. Local assembly plants drive basic adhesive demand. Cost sensitivity influences material selection. Import dependence affects supply consistency. Technology penetration remains limited. Gradual industrial development supports future growth. Demand remains stable across key hubs.
Key Player Analysis:
Competitive Analysis:
The Global Automotive Adhesive Market features strong competition among multinational and regional suppliers. Leading players focus on performance reliability and long-term OEM relationships. Companies compete through product breadth across resin types and technologies. Innovation centers support customized solutions for vehicle platforms. Strategic pricing remains important due to OEM cost pressure. Brand reputation influences supplier selection in safety-critical uses. Global players leverage scale and technical support networks. Regional firms compete through localized supply and cost efficiency. It reflects a balanced mix of innovation and operational strength.
Recent Developments:
- In December 2025, Henkel launched Loctite MS 9650, a next-generation adhesive and sealant designed specifically for lightweight structural bonding in automotive display components. This silane-modified polymer-based product cures through moisture reaction, forming a soft elastic product capable of bonding diverse substrates including glass, metal, painted surfaces, and plastics with excellent UV resistance. The adhesive delivers superior creep behavior comparable to silicone-based products and includes improved curing speed capabilities through Teroson MS 9371B accelerators, enabling applications previously unsuitable for one-component adhesives due to processing time constraints. The product's low-VOC, isocyanate-free, and PVC-free formula supports environmental sustainability while proving suitable for lightweight vehicle assemblies.
- In November 2025, Henkel expanded its electric vehicle thermal management portfolio with the launch of Loctite SI 5643 and Loctite SI 5637, two-component, fast-curing, low-viscosity thermally conductive silicone potting compounds specifically engineered for high-performance power electronics in EV powertrains. These solutions address the industry's challenge of integrating multiple powertrain components including motors, inverters, and on-board chargers into compact units. Both products feature exceptionally fast-flowing characteristics with self-leveling capabilities, enabling them to fill small gaps while delivering exceptional heat transfer for thermal management. Their very low Shore hardness and flexibility protect electrical components against vibration without inducing mechanical stress during thermal cycling, making them ideal for next-generation power electronics and EV battery designs.
- Following its strategic separation announcement in January 2025, DuPont is targeting November 1, 2025, to complete the spin-off of its Electronics business (to be named "Qnity"), creating a new independent, publicly traded company. After this separation, the new DuPont will center its development around high-growth businesses including Water and Healthcare, alongside other market-leading industrial product lines with applications in advanced adhesive and sealant solutions for diverse end markets.
Report Coverage:
The research report offers an in-depth analysis based on resin type, technology, vehicle type, and application segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Electric vehicle growth will raise demand for high-performance bonding solutions.
- Lightweight vehicle platforms will increase adhesive use over fasteners.
- Water-based technologies will gain wider OEM acceptance.
- Structural bonding will expand in safety-critical vehicle parts.
- Asia Pacific will remain the key production-driven region.
- Automation will favor precision adhesive systems.
- Sustainability goals will shape product development priorities.
- Custom solutions will support modular vehicle platforms.
- Supplier partnerships with OEMs will deepen further.
- Innovation will focus on multifunctional adhesive performance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Lightweight Vehicle Design and Structural Efficiency Requirements
Automakers are increasingly replacing mechanical fasteners with adhesives to reduce vehicle weight, improve fuel efficiency, and enhance crash safety. This shift is especially important for bonding aluminum and composite panels, supporting modern multi-material vehicle architectures.
Growing Electric Vehicle Production and Battery Assembly Demand
The expansion of electric vehicle manufacturing drives demand for advanced adhesives in battery modules, power electronics, and structural parts. Adhesives provide thermal management, vibration control, and insulation, which are critical for EV safety and performance.
Stricter Vehicle Safety and Durability Performance Standards
Tighter global safety regulations require improved crashworthiness and long-term durability, leading automakers to adopt adhesives that enhance energy absorption, distribute loads more evenly, and maintain structural integrity under stress.
Expansion of Automated and High-Speed Vehicle Assembly Lines
Modern automotive plants are increasingly automated, favoring adhesive solutions that support robotic dispensing, faster curing, and consistent bond quality. This trend improves production efficiency and reduces rework, sustaining adhesive demand.
Shift Toward Low Emission and Sustainable Adhesive Formulations
OEMs and regulators are pushing for lower emissions and safer manufacturing environments, driving the adoption of water-based and low-VOC adhesives. This aligns with sustainability goals and regulatory compliance, especially in Europe and Asia Pacific.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Automotive Adhesive Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Automotive Adhesive Market projected to grow between 2025 and 2032?
Which Global Automotive Adhesive Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Automotive Adhesive Market?
Who are the leading companies in the Global Automotive Adhesive Market?
Which region commanded the largest share of the Global Automotive Adhesive Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Resin Type
- 1.2.1 Polyurethane
- 1.2.2 Epoxy
- 1.2.3 Acrylic
- 1.2.4 Silicone
- 1.2.5 Silyl Modified Polymer (SMP)
- 1.2.6 Polyamide
- 1.2.7 Other Materials
- 1.3 By Technology
- 1.3.1 Solvent Based
- 1.3.2 Water Based
- 1.4 By Application
- 1.4.1 Body in White
- 1.4.2 Paint Shop
- 1.4.3 Assembly
- 1.4.4 Powertrain
- 1.5 By Vehicle Type
- 1.5.1 Passenger Vehicle
- 1.5.2 Light Commercial Vehicle (LCV)
- 1.5.3 Heavy Commercial Vehicle (HCV)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 4,472.30 million → 2032: USD 9,766.80 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Adhesive Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Adhesive Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Adhesive Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Adhesive Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Adhesive Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Adhesive Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Adhesive Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Adhesive Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 4,472.30 million → 2032: USD 9,766.80 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Adhesive Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Resin Type - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Polyurethane
- 12.3.7.2 Epoxy
- 12.3.7.3 Acrylic
- 12.3.7.4 Silicone
- 12.3.7.5 Silyl Modified Polymer (SMP)
- 12.3.7.6 Polyamide
- 12.3.7.7 Other Materials
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Solvent Based
- 12.4.7.2 Water Based
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Body in White
- 12.5.7.2 Paint Shop
- 12.5.7.3 Assembly
- 12.5.7.4 Powertrain
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Vehicle Type - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Passenger Vehicle
- 12.6.7.2 Light Commercial Vehicle (LCV)
- 12.6.7.3 Heavy Commercial Vehicle (HCV)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Adhesive End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automotive Adhesive Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automotive Adhesive Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automotive Adhesive Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Henkel
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Arkema
- 18.4 3M
- 18.5 DuPont
- 18.6 H.B. Fuller
- 18.7 Sika AG
- 18.8 HP Adhesives
- 18.9 Yashbond Adhesives
- 18.10 TESA
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

