
Cargo Handling Equipment Market Overview:
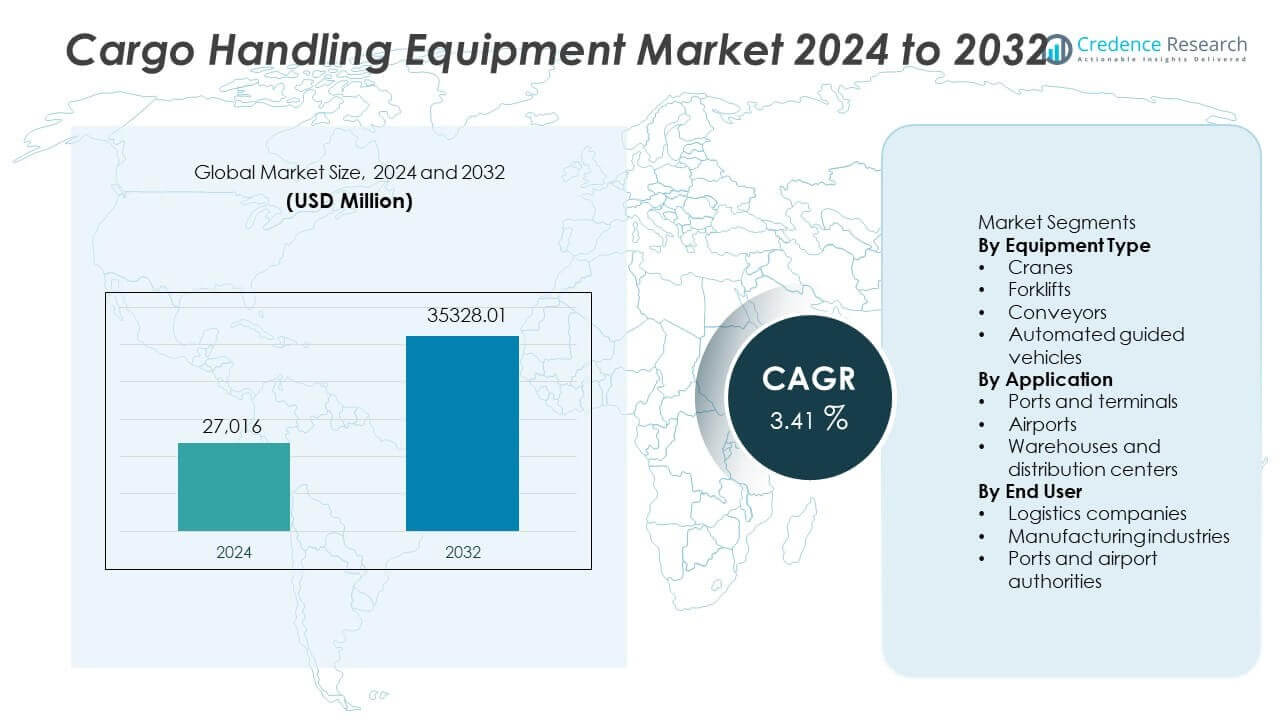
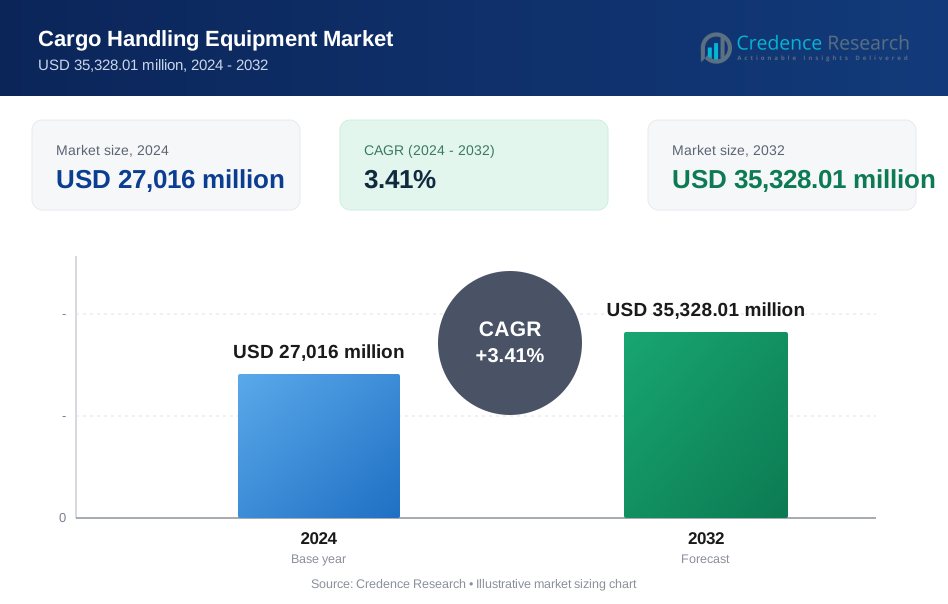
The cargo handling equipment market was valued at USD 27,016 million in 2024 and is expected to reach USD 35,328.01 million by 2032. The market is projected to grow at a CAGR of 3.41% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cargo Handling Equipment Market Size 2024 | USD 27,016 million |
| Cargo Handling Equipment Market, CAGR | 3.41% |
| Cargo Handling Equipment Market Size 2032 | USD 35,328.01 million |
The cargo handling equipment market features strong participation from leading players such as Konecranes, Liebherr Group, Toyota Industries Corporation, Hyster-Yale Materials Handling, Jungheinrich AG, Mitsubishi Logisnext, Kalmar (Cargotec), SANY Group, Terex Corporation, and Daifuku Co., Ltd. These companies compete through automation, electrification, and global service capabilities. Asia Pacific leads the market with a 42% share, supported by large-scale port expansion, manufacturing growth, and rising e-commerce activity. North America follows with a 24% share, driven by warehouse automation and logistics infrastructure upgrades. Europe holds a 22% share, benefiting from port modernization and strong adoption of energy-efficient handling equipment.
Cargo Handling Equipment Market Insights
- The market reached USD 27,016 million in 2024 and is projected to grow at a CAGR of 3.41% during the forecast period, supported by steady trade and logistics expansion.
- Growth drivers include rising global trade, port modernization, and e-commerce expansion, with forklifts leading the equipment type segment at a 44% share due to versatility and high utilization.
- Key trends focus on automation and electrification, as warehouses and distribution centers adopt automated guided vehicles and electric forklifts to improve efficiency and meet emission rules.
- The competitive landscape remains concentrated, with leading suppliers investing in smart equipment, fleet management software, and strong after-sales networks to secure long-term contracts.
- Asia Pacific leads with a 42% share, followed by North America at 24% and Europe at 22%, while high capital costs and maintenance needs act as key market restraints.
Cargo Handling Equipment Market Segmentation Analysis:
By Equipment Type
Forklifts dominate the cargo handling equipment market with a 44% share. This leadership reflects widespread use across warehouses, ports, and manufacturing sites. Forklifts offer flexibility, lower acquisition costs, and ease of operation. Electric models gain traction due to emission rules and indoor use needs. High replacement cycles support steady demand. Cranes follow, driven by port expansion and heavy-lift needs. Conveyors support fixed facilities with high throughput. Automated guided vehicles grow in advanced sites but remain smaller. Overall, forklifts lead due to versatility, scalability, and strong adoption across end users.
- For instance, Toyota Industries deployed lithium-ion forklifts supporting 8-hour continuous operation and 1.5-ton load capacity.
By Application
Warehouses and distribution centers hold the largest share at 47%. E-commerce growth and omnichannel logistics drive automation and throughput needs. Facilities invest in forklifts, conveyors, and automated systems to speed order fulfillment. Rising inventory turnover increases equipment utilization. Labor shortages further accelerate mechanization. Ports and terminals follow, supported by container traffic growth and port modernization. Airports represent a smaller share, focused on baggage and cargo terminals. Despite diversification, warehouses lead due to rapid logistics expansion and continuous capacity additions worldwide.
- For instance, Daifuku installed large-scale automated storage systems with high storage capacity for an e-commerce hub, significantly increasing operational efficiency and accuracy.
By End User
Logistics companies account for a dominant 52% share of the market. Third-party logistics providers invest heavily to improve handling speed and efficiency. Contract logistics growth drives fleet expansion and upgrades. Operators prioritize flexible equipment to handle varied cargo profiles. Technology adoption improves uptime and safety. Manufacturing industries follow, driven by internal material flow needs. Ports and airport authorities invest selectively for infrastructure upgrades. Logistics companies lead due to high asset intensity, fast expansion, and continuous demand for efficient cargo movement solutions.
Key Growth Drivers
Expansion of Global Trade and Port Infrastructure
Rising global trade volumes drive strong demand for cargo handling equipment. Ports expand capacity to manage higher container throughput. Governments invest in port modernization and logistics corridors. Cranes, forklifts, and automated systems support faster cargo movement. Growth in intermodal transport increases handling requirements. Developing economies upgrade port infrastructure to improve competitiveness. Higher vessel sizes require advanced lifting solutions. Continuous infrastructure investment supports equipment replacement and upgrades. As trade flows grow, demand for efficient cargo handling equipment increases steadily.
- For instance, Liebherr supplied ship-to-shore cranes with 65-meter outreach and 65-ton twin-lift capacity for mega container vessels.
Growth of E-commerce and Warehouse Automation
E-commerce expansion increases demand for efficient material handling. Warehouses require high-throughput equipment to manage rising order volumes. Forklifts and conveyors support rapid inventory movement. Automation improves picking accuracy and speed. Distribution centers invest in scalable handling systems. Urban fulfillment centers adopt compact and electric equipment. Labor shortages accelerate automation adoption. Technology improves safety and productivity. As e-commerce grows, warehouses continue to expand equipment fleets. This trend strongly supports market growth.
- For instance, Jungheinrich deployed electric reach trucks with 13-meter lift height for dense storage operations.
Industrialization and Manufacturing Output Growth
Manufacturing expansion drives internal cargo handling needs. Industries require reliable equipment for raw materials and finished goods. Forklifts and conveyors support continuous production flow. Growth in automotive, metals, and consumer goods boosts demand. Industrial plants upgrade equipment to improve efficiency. Safety regulations encourage modern handling solutions. Energy-efficient equipment gains preference. Capacity expansions increase equipment utilization. Manufacturing output growth remains a steady driver for cargo handling equipment demand.
Key Trends & Opportunities
Adoption of Automation and Smart Handling Systems
Automation transforms cargo handling operations. Automated guided vehicles reduce labor dependency. Smart systems improve accuracy and safety. Sensors enable real-time equipment monitoring. Integration with warehouse management systems enhances efficiency. Operators adopt automation to reduce operating costs. Advanced systems support high-volume facilities. This trend creates opportunities for technology-driven suppliers. Demand grows for scalable automated solutions. Smart handling systems shape future market opportunities.
- For instance, Kalmar installed automated straddle carriers operating continuously for 20 hours per day.
Shift Toward Electric and Energy-Efficient Equipment
Environmental regulations drive adoption of electric cargo handling equipment. Electric forklifts reduce emissions and noise. Energy efficiency lowers operating costs. Indoor facilities prefer clean equipment. Battery technology improvements extend operating time. Charging infrastructure expands across logistics sites. Sustainability goals influence purchasing decisions. Manufacturers develop low-emission solutions. This shift creates opportunities for innovation. Energy-efficient equipment supports long-term market growth.
- For instance, Hyster-Yale supplied electric lift trucks with 2,500 kg rated load capacity for warehouse use.
Key Challenges
High Capital Investment and Maintenance Costs
Cargo handling equipment requires significant upfront investment. High costs affect small operators. Maintenance expenses impact total ownership cost. Downtime disrupts operations. Financing constraints delay upgrades. Replacement cycles depend on budget availability. Advanced automation increases capital requirements. Cost sensitivity limits adoption in developing markets. Managing equipment lifecycle costs remains challenging. High investment acts as a market restraint.
Operational Complexity and Skilled Labor Shortages
Advanced handling systems require skilled operators. Labor shortages affect equipment utilization. Training increases operational costs. Automation reduces labor needs but requires technical expertise. System integration complexity slows adoption. Safety compliance demands skilled handling. Smaller firms face challenges in workforce development. Operational complexity impacts productivity. Addressing skills gaps is critical. Labor challenges constrain market expansion.
Regional Analysis
North America
North America holds a 24% share of the cargo handling equipment market, driven by advanced logistics infrastructure and high automation adoption. The United States leads regional demand due to strong warehouse expansion and port upgrades. E-commerce growth increases investment in forklifts, conveyors, and automated systems. Airports modernize cargo terminals to improve throughput. Labor shortages accelerate automation and electric equipment adoption. Strong safety standards support replacement demand. Manufacturers focus on energy-efficient solutions. Robust capital availability enables fleet upgrades. These factors sustain steady growth across logistics, ports, and industrial facilities in the region.
Europe
Europe accounts for a 22% share, supported by well-developed ports and strict environmental regulations. Germany, the Netherlands, and France drive demand through port modernization and warehouse automation. Sustainability goals push adoption of electric forklifts and low-emission equipment. Cross-border trade increases handling needs at logistics hubs. Airports invest in cargo infrastructure upgrades. Automation improves efficiency amid labor constraints. Strong manufacturing activity supports internal handling demand. Regulatory compliance shapes purchasing decisions. Europe maintains stable growth through technology upgrades and green logistics initiatives.
Asia Pacific
Asia Pacific leads with a 42% share of the cargo handling equipment market, driven by rapid industrialization and high trade volumes. China, India, Japan, and Southeast Asia dominate regional demand. Large port expansions increase crane and terminal equipment purchases. E-commerce growth accelerates warehouse construction and automation. Manufacturing output boosts internal material handling needs. Governments invest in logistics corridors and smart ports. Cost-competitive production supports equipment adoption. Automation adoption rises in high-volume facilities. Asia Pacific’s scale and infrastructure spending reinforce market leadership.
Latin America
Latin America holds a 7% share, supported by developing logistics and port infrastructure. Brazil and Mexico lead demand through port upgrades and warehouse growth. Trade recovery increases cargo volumes. Logistics firms invest selectively in forklifts and conveyors. Automation adoption remains gradual due to cost sensitivity. Manufacturing and agribusiness support handling needs. Airport cargo terminals see incremental upgrades. Financing constraints limit rapid expansion. Regulatory improvements enhance investment confidence. The region shows steady growth potential as infrastructure development progresses.
Middle East & Africa
The Middle East and Africa account for a 5% share, reflecting an emerging market stage. Gulf countries drive demand through large port and airport projects. Trade hubs invest in cranes and automated terminals. Logistics zones expand to support regional distribution. Energy and construction sectors increase handling needs. Equipment imports dominate supply. Automation adoption grows in flagship projects. Limited skilled labor influences purchasing decisions. Infrastructure diversification supports demand. Long-term investments position the region for gradual market expansion.
Cargo Handling Equipment Market Segmentations:
By Equipment Type
- Cranes
- Forklifts
- Conveyors
- Automated guided vehicles
By Application
- Ports and terminals
- Airports
- Warehouses and distribution centers
By End User
- Logistics companies
- Manufacturing industries
- Ports and airport authorities
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights a competitive market led by key players such as Konecranes, Liebherr Group, Toyota Industries Corporation, Hyster-Yale Materials Handling, Jungheinrich AG, Mitsubishi Logisnext, Kalmar (Cargotec), SANY Group, Terex Corporation, and Daifuku Co., Ltd. These companies compete through broad product portfolios, global service networks, and strong engineering capabilities. Market leaders focus on automation, electrification, and digital solutions to improve productivity and safety. Investment in R&D supports smart equipment, fleet management software, and energy-efficient systems. Strategic partnerships with ports, logistics providers, and manufacturers strengthen long-term contracts. Geographic expansion targets high-growth regions with rising trade and e-commerce activity. After-sales service and lifecycle support remain key differentiators. Pricing competitiveness and financing options influence purchasing decisions. Continuous innovation and operational reliability shape competitive positioning in the cargo handling equipment market.
Key Player Analysis
- Konecranes
- Liebherr Group
- Toyota Industries Corporation
- Hyster-Yale Materials Handling
- Jungheinrich AG
- Mitsubishi Logisnext
- Kalmar (Cargotec)
- SANY Group
- Terex Corporation
- Daifuku Co., Ltd.
Recent Developments
- In September 2025, the Liebherr Group entered a 10-year partnership agreement with Transnet Port Terminals (TPT) in South Africa for the supply of port equipment and an associated 20-year asset management programme.
- In June 2025, Konecranes won a major order for its electric empty container handlers in Bangladesh, expanding its electric cargo equipment reach.
- In 2025, Konecranes secured a contract to supply 30 E-Hybrid RTG cranes to a new container terminal in India.
Report Coverage
The research report offers an in-depth analysis based on Equipment Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Global trade growth will sustain demand for cargo handling equipment.
- Automation adoption will increase across ports and warehouses.
- Electric and low-emission equipment will gain wider acceptance.
- E-commerce expansion will drive warehouse equipment investments.
- Smart and connected systems will improve operational efficiency.
- Asia Pacific will remain the largest consumption region.
- Port modernization projects will support crane and terminal equipment demand.
- Labor shortages will accelerate automated handling solutions.
- Manufacturers will focus on improving equipment reliability and uptime.
- Service and lifecycle management will become key competitive factors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Cargo Handling Equipment market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cargo Handling Equipment market projected to grow between 2024 and 2032?
Which Cargo Handling Equipment market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cargo Handling Equipment market?
Who are the leading companies in the Cargo Handling Equipment market?
Which region commanded the largest share of the Cargo Handling Equipment market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cargo Handling Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cargo Handling Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 27,016 million → 2032: USD 35,328.01 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cargo Handling Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cargo Handling Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cargo Handling Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cargo Handling Equipment Market Drivers
- 3.3 Cargo Handling Equipment Market Restraints & Challenges
- 3.4 Cargo Handling Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cargo Handling Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cargo Handling Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cargo Handling Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cargo Handling Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cargo Handling Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cargo Handling Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cargo Handling Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cargo Handling Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cargo Handling Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cargo Handling Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cargo Handling Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cargo Handling Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cargo Handling Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cargo Handling Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cargo Handling Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cargo Handling Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cargo Handling Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cargo Handling Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cargo Handling Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
