
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electronic Adhesives Market Size 2024 | USD 4,707.1 million |
| Electronic Adhesives Market, CAGR | 5.80% |
| Electronic Adhesives Market Size 2032 | USD 7,399.3 million |
Market Overview
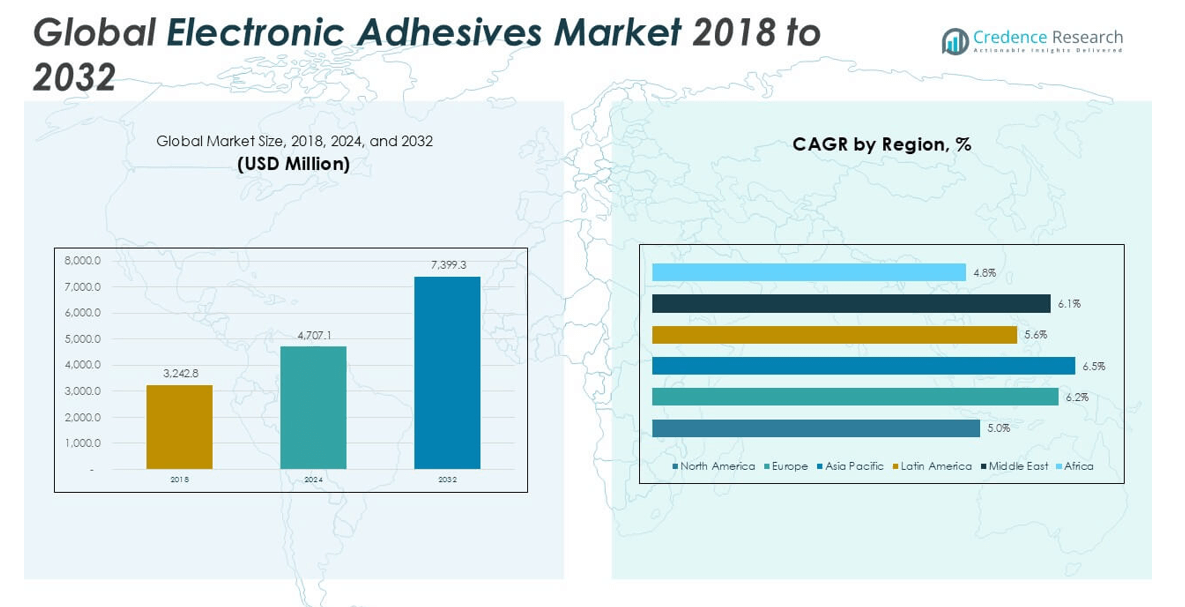
The Global Electronic Adhesives Market is projected to grow from USD 4,707.1 million in 2024 to an estimated USD 7,399.3 million by 2032, with a compound annual growth rate (CAGR) of 5.80% from 2025 to 2032.
Key drivers fueling this market include the rapid technological advancements in wearable devices, smartphones, and automotive electronics. Additionally, the growth of electric vehicles (EVs) and the broader adoption of 5G infrastructure are increasing the demand for reliable and efficient bonding solutions. Market trends also highlight a shift toward environmentally friendly and low-VOC (volatile organic compound) adhesive formulations to meet regulatory standards. Manufacturers are investing in R\&D to create innovative adhesive materials tailored for high-frequency applications and advanced packaging technologies.
Geographically, the Asia Pacific region dominates the Global Electronic Adhesives Market due to its strong electronics manufacturing base, especially in countries like China, South Korea, and Japan. North America and Europe are also experiencing steady growth, driven by advancements in medical devices and automotive electronics. Key players in the market include Henkel AG & Co. KGaA, H.B. Fuller, 3M, Dow Inc., Sika AG, and Dymax Corporation, all of which are focusing on product innovation and strategic collaborations to strengthen their market position.
Market Insights
- The Global Electronic Adhesives Market is projected to grow from USD 4,707.1 million in 2024 to USD 7,399.3 million by 2032, with a CAGR of 5.80% from 2025 to 2032.
- Growth is driven by increasing use of smartphones, wearables, and smart devices, which require high-performance bonding solutions.
- The adoption of EVs and 5G technology accelerates demand for adhesives with thermal conductivity and high reliability.
- The shift toward low-VOC and eco-friendly adhesives is shaping product development to comply with environmental regulations.
- Challenges in curing behavior, substrate compatibility, and long-term durability limit some advanced adhesive applications.
- Asia Pacific holds the largest market share due to its strong electronics manufacturing base in China, South Korea, and Japan.
- Key companies like Henkel, H.B. Fuller, and 3M continue to invest in R\&D and partnerships to maintain competitive advantage.
Market Drivers
Rising Demand for Consumer Electronics and Miniaturization Driving Adhesive Innovation
The Global Electronic Adhesives Market is experiencing strong growth due to the increasing demand for smartphones, tablets, wearable devices, and smart home technologies. These compact and high-performance devices require precise bonding solutions that offer thermal stability, electrical conductivity, and mechanical strength. The trend toward miniaturization in electronics has intensified the need for adhesives that can perform under extreme operating conditions without compromising device integrity. Manufacturers are developing advanced formulations to cater to the diverse requirements of consumer electronics. Adhesives with fast-curing properties and compatibility with flexible substrates are gaining preference. This demand continues to stimulate R\&D and the launch of tailored adhesive products.
- For instance, a 2023 industry survey reported that more than 9,400 metric tons of electronic adhesives were consumed globally in the production of smartphones and wearable devices, with over 1,200 new adhesive formulations launched to support miniaturized and flexible electronics that year.
Growth in Automotive Electronics and Electric Vehicles Boosting Market Expansion
The expansion of automotive electronics, especially in electric vehicles (EVs), has become a major growth driver for the electronic adhesives market. Modern vehicles increasingly rely on complex electronic systems for safety, entertainment, navigation, and performance. It needs adhesives that can withstand vibration, temperature fluctuations, and exposure to harsh environments. The shift toward EVs demands lightweight, heat-resistant bonding solutions for battery management systems and power control modules. This trend has led to increased collaboration between automakers and adhesive manufacturers. Regulatory support for EV adoption further contributes to the market’s momentum.
- For instance, according to automotive industry data from 2023, more than 3,600 metric tons of electronic adhesives were used in the assembly of electric vehicle battery packs and control modules worldwide, with over 500 automotive OEMs and suppliers adopting advanced adhesive solutions for next-generation EV platforms.
Advancements in Semiconductor Packaging and Assembly Techniques Creating New Opportunities
Technological advancements in semiconductor packaging, including 3D integration and system-in-package (SiP) designs, have created a need for more reliable adhesive materials. It plays a vital role in die attach, encapsulation, and thermal interface applications. High thermal conductivity and low outgassing are key attributes sought by chip manufacturers. As devices become smaller and more powerful, adhesives must meet strict performance specifications. The growing demand for AI, IoT, and data processing devices continues to drive semiconductor innovation. Adhesive solutions are evolving to keep pace with these high-performance requirements.
Focus on Sustainable and Low-VOC Adhesive Solutions Influencing Product Development
Environmental regulations and industry standards are pushing manufacturers toward sustainable adhesive formulations. The market is witnessing a shift toward low-VOC and solvent-free products that minimize environmental impact. It encourages companies to innovate in bio-based and recyclable adhesive materials. The push for greener electronics also aligns with broader ESG goals across industries. Manufacturers are responding by investing in eco-friendly production methods and greener raw materials. This trend is expected to shape the future direction of the Global Electronic Adhesives Market.
Market Trends
Shift Toward Flexible and Stretchable Electronics Enhancing Adhesive Requirements
The rise of flexible and stretchable electronics is reshaping product design and functionality across various industries. Wearable devices, foldable smartphones, and smart textiles demand adhesives that maintain strong bonds while accommodating repeated bending and stretching. The Global Electronic Adhesives Market is responding by introducing formulations with high elasticity, strong adhesion to flexible substrates, and durability under dynamic stress. It supports innovations in healthcare wearables, flexible sensors, and rollable displays. Manufacturers are investing in advanced polymer chemistry to meet these emerging performance needs. This trend continues to redefine product engineering standards.
- For instance, leading electronics manufacturers such as Apple and Samsung have incorporated flexible, stretchable adhesives into millions of wearable devices and foldable smartphones annually, with over 29 billion flexible electronic components produced globally in 2024 for applications ranging from smartwatches to medical sensors
Integration of 5G and High-Frequency Communication Devices Driving Technical Improvements
The rollout of 5G networks and development of high-frequency communication devices require adhesives that function reliably at higher thermal and electrical loads. These applications often involve complex multi-layer circuit boards and components with high heat generation. It increases the need for thermally conductive adhesives with precise dielectric properties. The Global Electronic Adhesives Market is seeing growing demand for materials that can ensure signal integrity and support faster data transmission. Adhesives must now meet stricter performance thresholds to align with 5G and advanced RF technologies. This trend is accelerating material innovation and testing protocols.
- For instance, more than 2,300,000 5G base stations were deployed worldwide by mid-2024, each requiring advanced adhesives for reliable thermal management and signal integrity in high-frequency communication equipment
Growing Role of Automation in Electronics Manufacturing Demanding Process-Compatible Adhesives
The adoption of automated manufacturing processes across the electronics sector is influencing adhesive selection and application methods. High-speed assembly lines require adhesives with fast cure times, consistent viscosity, and compatibility with dispensing and jetting systems. The Global Electronic Adhesives Market is adjusting to support automation by offering materials that reduce cycle times and improve efficiency. It helps manufacturers maintain precision while lowering production costs. Adhesive suppliers are also developing customized solutions for robotics and surface-mount technologies. This alignment with automation is becoming essential for large-scale production facilities.
Emphasis on Reliability and Longevity of Electronic Components Guiding Adhesive Development
Increased expectations around the lifespan and reliability of electronic products are shaping adhesive development strategies. Applications in aerospace, medical devices, and industrial controls require adhesives that perform consistently over extended periods. The Global Electronic Adhesives Market is addressing this by enhancing thermal aging resistance, moisture barrier properties, and chemical stability. It enables manufacturers to meet quality assurance standards and reduce failure rates. Long-term durability is now a key differentiator in material selection. This trend is prompting adhesive makers to offer performance certifications and rigorous testing data.
Market Challenges
Volatility in Raw Material Prices and Supply Chain Disruptions Impacting Production Costs
Fluctuating prices of raw materials such as epoxy resins, silicones, and acrylics continue to challenge manufacturers in the Global Electronic Adhesives Market. It affects profit margins and complicates long-term pricing strategies. Frequent supply chain disruptions, driven by geopolitical tensions and logistical constraints, further strain material availability. Delays in sourcing high-purity inputs hinder production schedules and slow product delivery timelines. Companies must maintain strong supplier networks and diversify sourcing strategies to mitigate these risks. The market faces pressure to balance cost control with maintaining consistent quality.
- For instance, in 2024, over 1,600 electronic adhesive manufacturers worldwide experienced average delays of 18 days in raw material deliveries, with more than 420 companies citing shortages of high-purity epoxy resins and silicones as the primary reason for missed production targets, according to procurement data and supply chain monitoring reports.
Technical Limitations in Performance and Application Processes Restricting Adoption
Adhesives in high-performance electronics must meet stringent requirements related to conductivity, thermal stability, and curing behavior. It remains difficult to develop materials that consistently perform across all applications and environments. Challenges in achieving optimal adhesion on next-generation substrates such as flexible films or composite materials limit broader adoption. Application processes like jet dispensing and UV curing require precise formulation compatibility, which not all adhesives can provide. The Global Electronic Adhesives Market continues to face barriers in scaling innovative products without compromising reliability. These limitations hinder integration into advanced device architectures.
Market Opportunities
Expansion in Electric Vehicle and Renewable Energy Applications Providing Growth Avenues
The Global Electronic Adhesives Market benefits from the rapid expansion of electric vehicle production and renewable energy installations. It requires bonding solutions that withstand high temperatures and vibrations in battery packs and power inverters. Growth in EV manufacturing opens opportunities to supply adhesives for battery management systems and motor control units. Renewable energy sector players seek durable adhesives for photovoltaic module assembly and wind turbine electronics. Collaborative projects between automakers and adhesive developers increase the pace of product qualification. Companies can tailor formulations to meet stringent industry standards and secure long-term contracts. This shift toward green transportation and energy infrastructure presents significant revenue potential.
Emergence of High-Density and Miniaturized Electronics Creating New Niches
The Global Electronic Adhesives Market finds opportunities in the ongoing trend toward high-density, miniaturized device architectures. It drives demand for ultra-thin, high-performance adhesives in system-in-package (SiP) designs and advanced semiconductor modules. Miniaturization trend pushes adhesive providers to optimize thermal conductivity and reduce component footprint. Challenges in die-attach and underfill applications create niches for specialized materials. Development of low-profile adhesives compatible with surface-mount technology enhances assembly precision. Partnerships between device makers and chemical companies accelerate commercialization of novel adhesive systems. Novel adhesive chemistries that support higher wiring densities and signal integrity will capture emerging market segments.
Market Segmentation Analysis
By Form
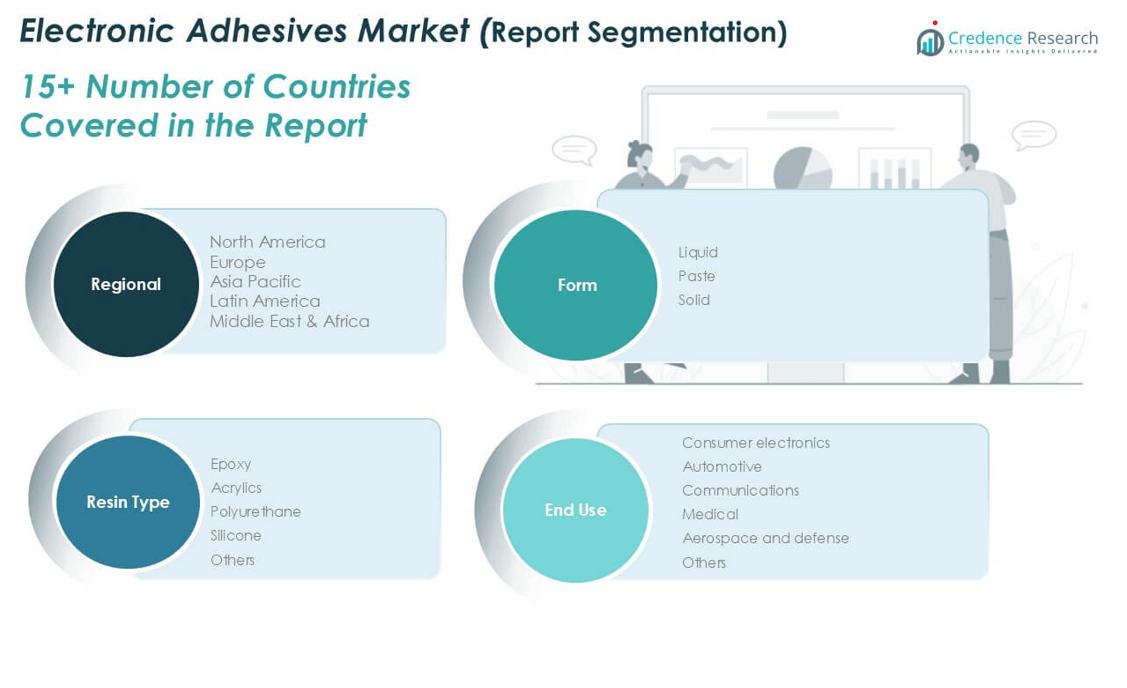
The Global Electronic Adhesives Market is segmented by form into liquid, paste, and solid. Liquid adhesives hold a significant share due to their ease of application and ability to flow into complex geometries, making them ideal for high-density circuit boards and encapsulation. Paste adhesives are commonly used in surface-mount devices, offering controlled viscosity and strong bonding strength for electronic packaging. Solid adhesives, such as films and tapes, are preferred for applications requiring clean, precise, and consistent application without mess or waste. It continues to see increased demand for liquid and paste forms, driven by automated dispensing systems and high-volume manufacturing.
- For instance, Henkel reported that in 2024, its electronics division supplied over 16,000 metric tons of liquid and paste adhesives for use in circuit board assembly and semiconductor packaging, reflecting the scale of demand for these forms in global electronics manufacturing.
By Resin Type
The market is further categorized by resin type, including epoxy, acrylics, polyurethane, silicone, and others. Epoxy adhesives dominate the segment due to their high mechanical strength, thermal stability, and compatibility with a wide range of substrates. Acrylic adhesives are gaining traction for their fast curing and environmental resistance, especially in outdoor and automotive applications. Silicone adhesives offer flexibility and high-temperature resistance, making them suitable for critical electronic assemblies. Polyurethane adhesives serve niche applications requiring toughness and impact resistance. It is expanding its resin portfolio to cater to evolving industry requirements and environmental regulations.
- For instance, a 2024 industry survey found that global electronics manufacturers consumed more than 8,500 metric tons of epoxy-based adhesives for printed circuit board and component assembly, underscoring the dominance of epoxy resins in the sector.
By End Use
By end use, the Global Electronic Adhesives Market is divided into consumer electronics, automotive, communications, medical, aerospace and defense, and others. Consumer electronics represent the largest segment due to rising global demand for smartphones, wearables, and smart home devices. The automotive segment is growing steadily with the rise of electric vehicles and advanced driver-assistance systems (ADAS). Communications benefit from the expansion of 5G infrastructure. The medical segment uses adhesives for compact, high-reliability devices, while aerospace and defense applications require materials with extreme durability. It supports innovation across sectors by offering performance-specific adhesive solutions.
Segments
Based on Form
- Liquid
- Paste
- Solid
Based on Resin Type
- Epoxy
- Acrylics
- Polyurethane
- Silicone
- Others
Based on End Use
- Consumer electronics
- Automotive
- Communications
- Medical
- Aerospace and defense
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Electronic Adhesives Market
North America accounted for approximately 32.7% of the global Electronic Adhesives Market in 2024, reaching a market size of USD 1,538.43 million, and is projected to grow to USD 2,277.50 million by 2032 at a CAGR of 5.0%. The United States leads the region, supported by a strong consumer electronics industry and high R\&D spending in semiconductor technologies. Demand for high-performance adhesives in automotive electronics and defense applications continues to grow. It supports complex manufacturing environments that require consistent adhesive performance across varied applications. Technological innovation and strict regulatory standards drive the adoption of reliable, low-VOC adhesive formulations. The region’s well-established manufacturing base ensures steady market growth.
Europe Electronic Adhesives Market
Europe represented 22.3% of the global market in 2024, valued at USD 1,049.83 million, and is expected to reach USD 1,701.83 million by 2032, growing at a CAGR of 6.2%. Germany, France, and the UK contribute heavily due to their advanced automotive and aerospace sectors. It benefits from the region’s focus on sustainability, which fuels demand for eco-friendly adhesives. The market is witnessing increased adoption in electric vehicles, medical devices, and 5G infrastructure. Europe’s emphasis on clean energy and green electronics supports innovation in material science. Manufacturers are aligning with EU regulations to meet evolving environmental and performance standards.
Asia Pacific Electronic Adhesives Market
Asia Pacific held the largest regional share of 27.6% in 2024, with a market size of USD 1,298.90 million, projected to reach USD 2,145.79 million by 2032, growing at a CAGR of 6.5%. China, Japan, South Korea, and Taiwan are major contributors due to their leadership in electronics manufacturing and semiconductor fabrication. The Electronic Adhesives Market thrives in this region due to mass production of consumer devices and rapid industrial digitization. It benefits from cost-efficient manufacturing and strong domestic demand. High investment in 5G rollout and electric vehicles fuels further growth. Regional governments continue to support advanced manufacturing through subsidies and policy incentives.
Latin America Electronic Adhesives Market
The Latin America market accounted for 10.0% of global revenue in 2024, standing at USD 469.64 million, and is forecasted to reach USD 725.13 million by 2032, registering a CAGR of 5.6%. Brazil and Mexico dominate the regional landscape due to expanding electronics assembly industries and rising automotive exports. The Electronic Adhesives Market here is influenced by increasing foreign investment and regional partnerships in consumer electronics. It faces challenges related to raw material availability and limited local production capabilities. However, infrastructure improvements and growing demand for smart technologies offer opportunities. The region is moving toward localized manufacturing to reduce import dependency.
Middle East Electronic Adhesives Market
The Middle East contributed 5.5% to the global Electronic Adhesives Market in 2024, valued at USD 258.42 million, with projections indicating a rise to USD 415.10 million by 2032, at a CAGR of 6.1%. The market is driven by rising demand for electronics in security systems, telecom, and renewable energy infrastructure. Gulf countries such as the UAE and Saudi Arabia are investing in advanced electronics manufacturing zones. It experiences increased adhesive usage in LED lighting, smart home systems, and defense electronics. Government-led digital transformation programs further expand market potential. Companies are exploring joint ventures to expand local production and distribution.
Africa Electronic Adhesives Market
Africa accounted for the smallest share of 1.9% in 2024, with a market value of USD 91.92 million, expected to grow to USD 133.93 million by 2032, at a CAGR of 4.8%. South Africa and Nigeria are leading markets, supported by the rising adoption of mobile devices and growing local electronics assembly hubs. It sees steady demand in telecommunications and consumer electronics applications. Limited infrastructure and low investment in R\&D hinder faster adoption. International players are expanding presence through regional partnerships and distributor networks. Focus on low-cost, durable adhesive solutions supports market expansion in the price-sensitive segments.
Key players
- Henkel AG
- Arkema SA
- 3M
- Parker Hannifin Corporation
- The Dow Chemical Company
- HB Fuller
- Indium Corporation
- Kyocera Chemical Corporation
- LG Chemicals Ltd.
- Mitsui Chemicals
Competitive Analysis
The Global Electronic Adhesives Market is highly competitive, with key players focusing on innovation, product development, and strategic partnerships to strengthen their positions. Henkel AG, 3M, and The Dow Chemical Company lead the market through expansive product portfolios, advanced R\&D capabilities, and strong global distribution networks. It faces growing competition from regional players and niche manufacturers offering specialized adhesive solutions for high-performance applications. Companies like Indium Corporation and Kyocera Chemical Corporation focus on thermal and conductive adhesives for the semiconductor sector. Strategic acquisitions, sustainable product lines, and technology-driven collaborations remain critical growth strategies. Market players continuously invest in eco-friendly formulations and automation-compatible adhesives to meet evolving industrial needs and regulatory standards.
Recent Developments
- In Q1 2025, Henkel AG reported 1.1% organic sales growth in its Adhesive Technologies business, reaching €2,715 million.
- In January 2025, 3M did indeed report strong first-quarter results, exceeding profit expectations and initiating a $1.5 billion share buyback program. This positive performance was partly attributed to robust demand for adhesives and other industrial products.
Market Concentration and Characteristics
The Global Electronic Adhesives Market exhibits moderate to high market concentration, with a few multinational corporations such as Henkel AG, 3M, and Dow Chemical dominating a significant share. It is characterized by intense competition, ongoing technological innovation, and high entry barriers due to specialized formulation requirements and capital-intensive R&D. The market prioritizes performance reliability, thermal stability, and compatibility with advanced electronic manufacturing processes. Customization, environmental compliance, and miniaturization are key differentiating factors. It sees frequent product launches and strategic alliances to address evolving applications in automotive, consumer electronics, and 5G infrastructure. The demand for automation-compatible and sustainable adhesives continues to shape competitive dynamics.
Report Coverage
The research report offers an in-depth analysis based on Form, Resin Type, End Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for high-performance adhesives will continue to rise with the expansion of consumer electronics, including smartphones, wearables, and IoT devices across global markets.
- The electronic adhesives market will benefit from the growing production of electric vehicles, where adhesives play a critical role in battery systems, sensors, and electronic control modules.
- Miniaturization of electronic components will drive the need for adhesives with precise application capability, superior thermal conductivity, and low-profile bonding solutions.
- Adhesives tailored for high-frequency and thermal-sensitive environments will gain prominence as 5G and next-generation communication technologies advance.
- Eco-friendly, low-VOC, and solvent-free adhesive formulations will dominate future product development to meet stringent environmental regulations.
- The growth of advanced packaging technologies such as system-in-package (SiP) and fan-out wafer-level packaging will increase demand for specialized adhesives.
- Future production lines will require adhesives with consistent curing profiles and automation compatibility to support high-speed, precision manufacturing processes.
- Asia Pacific will remain the leading market, while Latin America, Middle East, and Africa will experience accelerated adoption of electronic adhesives driven by industrial development.
- Companies will increasingly pursue partnerships and acquisitions to expand their technological capabilities, product lines, and geographic reach in a competitive landscape.
- Future adhesives will target high-reliability sectors such as aerospace, defense, and medical devices, where performance consistency and regulatory certification are essential.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in Consumer Electronics
The proliferation of smartphones, wearables, and smart home devices is driving demand for high-performance electronic adhesives that offer thermal stability, electrical conductivity, and miniaturization compatibility. As devices become more compact and complex, advanced adhesives are required to ensure reliable assembly and long-term durability.
Growth of Electric Vehicles and Automotive Electronics
The rapid expansion of electric vehicles and the integration of sophisticated electronic systems in modern automobiles are fueling demand for adhesives that can withstand vibration, temperature extremes, and harsh environments. Adhesives play a critical role in battery management systems, sensors, and control modules, supporting the shift toward electrification.
Adoption of 5G and High-Frequency Communication Devices
The rollout of 5G infrastructure and the development of high-frequency communication equipment require adhesives with superior thermal conductivity and dielectric properties. These adhesives are essential for maintaining signal integrity and managing heat in densely packed, high-speed electronic assemblies.
Shift Toward Eco-Friendly and Low-VOC Adhesive Formulations
Increasing regulatory pressure and industry focus on sustainability are prompting manufacturers to develop low-VOC, solvent-free, and bio-based adhesive solutions. This trend is shaping product development and driving market growth as companies seek to comply with environmental standards and meet customer preferences for greener electronics.
Advancements in Semiconductor Packaging and Miniaturization
Innovations in semiconductor packaging, such as 3D integration and system-in-package designs, are creating new requirements for adhesives with high thermal conductivity, low outgassing, and compatibility with advanced substrates. The ongoing trend toward miniaturization in electronics is expanding opportunities for specialized adhesive solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Electronic Adhesives Market in 2024 and 2032, and what is its CAGR?
Which industries are the major end users of electronic adhesives?
Which region dominates the Global Electronic Adhesives Market?
Who are the key players in the Global Electronic Adhesives Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Liquid
- 1.2.2 Paste
- 1.2.3 Solid
- 1.3 By End Use
- 1.3.1 Consumer electronics
- 1.3.2 Automotive
- 1.3.3 Communications
- 1.3.4 Medical
- 1.3.5 Aerospace and defense
- 1.3.6 Others
- 1.4 By Resin Type
- 1.4.1 Epoxy
- 1.4.2 Acrylics
- 1.4.3 Polyurethane
- 1.4.4 Silicone
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,707.1 million → 2032: USD 7,399.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electronic Adhesives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electronic Adhesives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electronic Adhesives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electronic Adhesives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electronic Adhesives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electronic Adhesives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electronic Adhesives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electronic Adhesives Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,707.1 million → 2032: USD 7,399.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electronic Adhesives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Liquid
- 12.3.7.2 Paste
- 12.3.7.3 Solid
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Consumer electronics
- 12.4.7.2 Automotive
- 12.4.7.3 Communications
- 12.4.7.4 Medical
- 12.4.7.5 Aerospace and defense
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Resin Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Epoxy
- 12.5.7.2 Acrylics
- 12.5.7.3 Polyurethane
- 12.5.7.4 Silicone
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electronic Adhesives End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Electronic Adhesives Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Electronic Adhesives Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Electronic Adhesives Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Henkel AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 3M
- 18.4 The Dow Chemical Company
- 18.5 HB Fuller
- 18.6 Arkema SA
- 18.7 Parker Hannifin Corporation
- 18.8 Indium Corporation
- 18.9 Kyocera Chemical Corporation
- 18.10 LG Chemicals Ltd.
- 18.11 Mitsui Chemicals
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

