
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electromagnetic Interference (EMI) Shielding Materials Market Size 2024 | USD 8,444 million |
| Electromagnetic Interference (EMI) Shielding Materials Market, CAGR | 7.77% |
| Electromagnetic Interference (EMI) Shielding Materials Market Size 2032 | USD 15,364.95 million |
Market Overview:
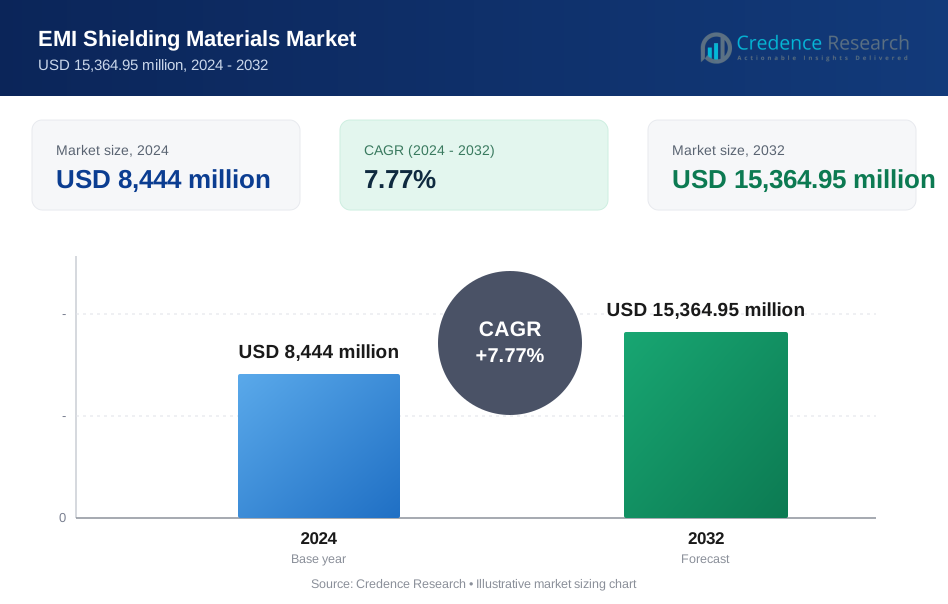
The Electromagnetic Interference (EMI) Shielding Materials Market is projected to grow from USD 8,444 million in 2024 to USD 15,364.95 million by 2032, with a compound annual growth rate (CAGR) of 7.77%.
The Electromagnetic Interference (EMI) Shielding Materials Market is driven by the increasing demand for advanced electronic devices, the rise of 5G technology, and the growing awareness of the need to mitigate electromagnetic interference in various industries. The widespread adoption of electric vehicles, aerospace technologies, and wearable devices further fuels the market, as these sectors require enhanced EMI protection for reliable performance. Additionally, stringent government regulations regarding electromagnetic emissions and the development of energy-efficient, high-performance materials are contributing to market growth. Key trends include the increasing use of lightweight, flexible materials, as well as advancements in nanotechnology and carbon-based materials that offer improved shielding effectiveness. The shift towards environmentally friendly and sustainable solutions is also shaping the market, with manufacturers focusing on eco-friendly, recyclable materials for EMI shielding. As technology continues to advance, the need for more effective and efficient EMI shielding solutions remains a critical factor in the market's expansion.
The Electromagnetic Interference (EMI) Shielding Materials Market is geographically diverse, with North America holding the largest share due to high demand from industries such as electronics, automotive, and telecommunications. Europe follows closely, driven by advancements in electric vehicles and aerospace technologies. Asia-Pacific, led by countries like China, Japan, and South Korea, is the fastest-growing region due to the booming electronics market and the expansion of 5G infrastructure. The Rest of the World (RoW) is also seeing growth, particularly in Latin America and the Middle East, fueled by increasing industrialization. Key players in these regions include 3M Company, Laird Performance Materials, Parker Hannifin Corporation, and Henkel AG & Co. KGaA, each playing a vital role in regional market expansion and technological innovation in EMI shielding solutions.
Market Insights:
- The EMI Shielding Materials Market is expected to grow from USD 8,444 million in 2024 to USD 15,364.95 million by 2032, at a CAGR of 7.77%.
- Increasing adoption of advanced electronic devices, including smartphones, laptops, and IoT products, is a key driver of market growth.
- The rollout of 5G technology is fueling demand for EMI shielding materials due to higher frequencies and potential interference.
- The rise of electric vehicles (EVs) and advancements in aerospace technologies are boosting the need for effective EMI shielding in these sectors.
- Stringent government regulations on electromagnetic emissions and the increasing focus on sustainability are contributing to market expansion.
- High costs of advanced materials like carbon nanotubes and graphene remain a challenge, limiting broader adoption of certain EMI shielding solutions.
- Geographically, North America holds the largest market share (35% in 2024), followed by Asia-Pacific (30%), Europe (25%), and Rest of the World (10%).
Market Drivers:
Increasing Adoption of Advanced Electronics:
The growing demand for advanced electronic devices, such as smartphones, laptops, and IoT-enabled products, is a significant driver of the Electromagnetic Interference (EMI) Shielding Materials Market. These devices are highly susceptible to electromagnetic interference, which can affect their performance and reliability. As the electronics industry continues to evolve, the need for effective EMI shielding solutions to protect these sensitive devices becomes more crucial. The rapid advancement in consumer electronics and the demand for seamless connectivity further drive the need for robust EMI shielding materials to ensure uninterrupted functionality.
Emergence of 5G Technology:
The rollout of 5G technology is one of the key factors propelling the growth of the EMI shielding materials market. 5G networks operate at higher frequencies, which increase the potential for electromagnetic interference. As telecommunications companies expand their 5G infrastructure, the demand for shielding materials to mitigate interference in both consumer and industrial applications rises. For instance, Heraeus Printed Electronics developed a silver ink that can be applied with high precision to shield components at the package level, ensuring that high-frequency chips can transmit data quickly, which is essential for 5G communications. This trend is particularly important in the development of devices such as smartphones, wearables, and autonomous vehicles, where reliable, interference-free communication is essential.
Growth of Electric Vehicles and Aerospace Industries:
The rise of electric vehicles (EVs) and advancements in the aerospace industry contribute significantly to the demand for EMI shielding materials. EVs, which rely heavily on electronics for propulsion, battery management, and driver assistance systems, require effective EMI shielding to ensure the safe and efficient operation of their components. Similarly, the aerospace sector, with its complex systems and high-performance requirements, mandates EMI shielding to prevent interference that could compromise safety and functionality.
Regulatory Standards and Environmental Considerations:
Stringent government regulations concerning electromagnetic emissions are another key driver in the market. For instance, PPG Industries introduced PPG TESLIN EMI/RF shielding material for electronic passports and other electronic security documents in November 2020. These regulations mandate the use of EMI shielding materials to ensure that electronic devices and systems comply with emission standards. Furthermore, as industries increasingly prioritize sustainability, there is a growing focus on developing environmentally friendly and recyclable EMI shielding solutions. This shift towards green technologies not only aligns with regulatory pressures but also caters to the rising consumer demand for eco-conscious products.
Market Trends:
Adoption of Flexible and Lightweight Materials:
A notable trend in the Electromagnetic Interference (EMI) Shielding Materials Market is the increasing adoption of flexible and lightweight materials. As the demand for smaller, more compact electronic devices grows, manufacturers are focusing on materials that provide effective EMI shielding while maintaining flexibility and reducing weight. For instance, SiAT partnered with Japan's Zeon Corporation to launch a single-walled carbon nanotube (SWCNT) conductive paste that enhances Lithium-ion battery performance and is applicable for transparent films and EMI shielding. Flexible shielding materials, such as conductive fabrics and films, are gaining popularity, particularly in wearable devices and flexible electronics. This trend enables manufacturers to design more innovative, portable, and user-friendly products without compromising on performance.
Integration of Advanced Nanotechnology:
Nanotechnology is revolutionizing the EMI shielding materials market by enabling the development of advanced, high-performance materials. Nanomaterials, such as carbon nanotubes, graphene, and metallic nanoparticles, are being incorporated into shielding solutions to improve their effectiveness and durability. These materials offer superior electromagnetic absorption and reflection properties while maintaining a lightweight profile. The integration of nanotechnology is paving the way for more efficient, compact, and cost-effective EMI shielding solutions, making them increasingly viable for a wide range of applications, from consumer electronics to automotive systems.
Sustainability and Eco-Friendly Solutions:
Sustainability is a growing trend in the EMI shielding materials market, with manufacturers prioritizing the development of eco-friendly and recyclable materials. As industries face increasing pressure to meet environmental standards and reduce their carbon footprints, there is a push toward creating shielding materials that are both high-performing and environmentally responsible. For instance, Omega Shielding® Products adheres to strict environmental regulations, promotes the use of eco-friendly materials, and implements sustainable manufacturing practices. Recyclable metals, biodegradable polymers, and sustainable production methods are gaining traction as the market shifts towards greener alternatives. This trend reflects broader global movements towards sustainability and aligns with consumer preferences for eco-conscious products.
Smart Materials and Adaptive Shielding Technologies:
The use of smart materials and adaptive shielding technologies is emerging as a trend within the EMI shielding market. These materials can adjust their shielding properties in response to changes in electromagnetic conditions, providing dynamic protection. This adaptability is especially useful in environments where electromagnetic interference levels fluctuate, such as in industrial applications and telecommunications. The development of smart shielding solutions is enhancing the overall performance of electronic devices and systems, offering tailored, real-time protection against EMI.
Market Challenges Analysis:
High Cost of Advanced Materials:
One of the primary challenges facing the Electromagnetic Interference (EMI) Shielding Materials Market is the high cost associated with advanced materials such as carbon nanotubes, graphene, and other nanomaterials. While these materials offer superior shielding properties, their production remains expensive, making them less accessible for widespread adoption, particularly in cost-sensitive industries. The complexity of manufacturing and the need for specialized equipment further increase production costs, which can significantly affect the overall cost of devices that require EMI protection. As a result, manufacturers may face challenges in balancing cost-efficiency with the performance requirements of EMI shielding materials, particularly in consumer electronics, automotive, and other mass-market sectors. The price of these advanced materials also hampers the adoption of EMI shielding in regions with lower manufacturing budgets, limiting the market's global reach.
Performance vs. Size and Weight Trade-offs:
Another challenge in the EMI shielding materials market lies in the trade-offs between shielding performance, size, and weight. As consumer demand for smaller, lighter, and more powerful electronic devices grows, manufacturers face difficulties in maintaining optimal EMI shielding without compromising on the device's design and functionality. In applications such as wearable technology, flexible electronics, and compact gadgets, achieving high-performance shielding in a thin, lightweight form factor presents significant engineering challenges. This balance is particularly crucial in industries like aerospace and automotive, where stringent performance and weight limitations must be met. For instance, Astrodyne TDI notes that thicker shields generally offer better EMI shielding, but this comes with the trade-off of increased weight in the design. Additionally, some shielding materials, while effective, may not offer the desired mechanical properties, such as flexibility or durability, necessary for these advanced applications. Overcoming these performance vs. size challenges is vital for the continued growth and evolution of the EMI shielding materials market, requiring innovative solutions to deliver both effective EMI protection and minimal design compromises.
Market Opportunities:
The Electromagnetic Interference (EMI) Shielding Materials Market presents significant opportunities driven by technological advancements and increasing regulatory pressures across industries. As the adoption of 5G technology continues to expand globally, there is a growing need for effective EMI shielding solutions to manage the higher frequencies and potential interference associated with 5G networks. This opens up substantial growth prospects for the market, particularly in telecommunications, consumer electronics, and automotive sectors, where high-performance shielding is crucial to maintain device reliability and signal integrity. Additionally, the rise of electric vehicles (EVs) and autonomous driving technologies further amplifies the demand for EMI shielding materials to protect the sensitive electronic systems within these vehicles, creating long-term growth potential for specialized shielding solutions.
Another promising opportunity lies in the increasing focus on sustainability and eco-friendly solutions within the market. As industries and consumers alike become more environmentally conscious, there is a growing demand for EMI shielding materials that are not only effective but also recyclable and biodegradable. This trend is particularly relevant in the electronics and automotive industries, where manufacturers are under increasing pressure to meet sustainability standards. The development of new, sustainable shielding materials, such as recyclable metals and biodegradable polymers, provides manufacturers with the opportunity to differentiate themselves and cater to the rising consumer preference for environmentally friendly products. Moreover, the continued miniaturization of electronic devices presents an opportunity to create more compact and efficient shielding materials, catering to the evolving needs of industries such as wearables, medical devices, and consumer electronics.
Market Segmentation Analysis:
By Components The Electromagnetic Interference (EMI) Shielding Materials Market is segmented based on materials such as metals, conductive polymers, and coatings. Metals like aluminum, copper, and steel dominate the market due to their excellent shielding properties and cost-effectiveness. However, conductive polymers and coatings are gaining traction due to their lightweight and flexible properties, especially in applications requiring lightweight shielding, such as in mobile devices and wearables.
By Industry The EMI shielding materials market serves various industries, including electronics, automotive, aerospace, and telecommunications. The electronics industry is the largest consumer, driven by the increasing demand for consumer electronics and IoT devices. In automotive and aerospace, the growth of electric vehicles and advanced aviation technologies boosts demand for effective EMI shielding to protect sensitive electronic systems. Telecommunications, particularly with the advent of 5G technology, also plays a significant role in expanding market opportunities.
Segments:
By Components
- Conductive Coatings and Paints
- EMI Shielding Tapes & Laminates
- Conductive Polymers
- Metal Shielding Products
- EMI Filters
By Application
- Consumer Electronics
- Telecommunication and IT
- Automotive
- Healthcare
- Aerospace and Defense
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America North America is expected to hold a significant market share in the Electromagnetic Interference (EMI) Shielding Materials Market, accounting for 35% of the total market in 2024. The region benefits from a robust demand for high-tech electronics, automotive innovations, and telecommunications, particularly with the ongoing expansion of 5G infrastructure. The United States, as a technological leader, drives the demand for advanced EMI shielding materials, particularly in sectors like aerospace, automotive, and consumer electronics. Furthermore, stringent regulatory standards for electromagnetic emissions and increased investments in electric vehicles and autonomous systems are fueling the market's growth in the region. The presence of major electronics and automotive manufacturers, along with ongoing research and development initiatives, positions North America as a key market for EMI shielding materials.
Europe Europe is another prominent region in the Electromagnetic Interference (EMI) Shielding Materials Market, expected to account for 25% of the market share in 2024. The region is witnessing steady growth due to the increasing adoption of electric vehicles (EVs), advancements in aerospace technologies, and high demand for consumer electronics. Countries like Germany, the UK, and France are at the forefront of this growth, with stringent environmental and emission regulations driving the need for effective EMI protection. Additionally, Europe’s emphasis on sustainability and eco-friendly manufacturing practices is creating opportunities for innovative and green EMI shielding solutions. The region's strong automotive and electronics sectors continue to push the market's expansion.
Asia-Pacific Asia-Pacific is projected to be the fastest-growing region in the EMI shielding materials market, with a market share of 30% in 2024. The region’s rapid industrialization, expanding consumer electronics market, and increasing adoption of 5G technology are key factors contributing to this growth. China, Japan, and South Korea are major players in the market, with China being the largest producer and consumer of electronics. The rising demand for mobile devices, wearables, and automotive electronics, along with government initiatives to develop 5G networks, drives the demand for EMI shielding materials. Furthermore, Asia-Pacific is a hub for manufacturing, making it a significant market for cost-effective EMI shielding materials.
Rest of the World (RoW) The Rest of the World (RoW), which includes regions such as the Middle East, Africa, and Latin America, is expected to hold 10% of the market share in 2024. Although this market segment is smaller compared to North America, Europe, and Asia-Pacific, it is growing due to increasing industrialization, particularly in the automotive and electronics sectors. Latin America’s expanding telecom sector and the Middle East’s investments in infrastructure are expected to drive the demand for EMI shielding materials in the coming years.
Key Player Analysis:
- Omega Shielding Products
- HEICO Corp.
- Tech-Etch Inc.
- Huntsman International LLC
- PPG Industries
- ETS-Lindgren
- RTP Company
- Laird Technologies Inc.
- Henkel AG & Co. KGaA
- 3M Company
- Parker Hannifin Corp
Competitive Analysis:
The Electromagnetic Interference (EMI) Shielding Materials Market is highly competitive, with leading players striving to innovate and capture market share through strategic investments, acquisitions, and product development. Companies such as 3M Company, Laird Performance Materials, Parker Hannifin Corporation, and Henkel AG & Co. KGaA are key contenders, each offering a range of EMI shielding solutions across various industries, including automotive, aerospace, telecommunications, and consumer electronics. 3M, for instance, is known for its innovative conductive films and adhesive materials, while Laird Performance Materials focuses on high-performance shielding solutions for mobile and wireless technologies. Parker Hannifin Corporation and Henkel AG are also strengthening their positions by introducing advanced materials and eco-friendly options to meet rising demand for sustainable solutions. These companies are investing heavily in R&D to introduce next-generation materials, such as graphene and carbon-based shielding technologies, to maintain a competitive edge. Strategic partnerships and geographic expansions are also common approaches to enhance their market presence.
Recent Developments:
- In April 2023, Nolato AB revealed that it is acquiring P&P Technology, a UK-based company specializing in electronic shielding solutions with EMC components and materials. This acquisition will enhance Nolato AB’s production capabilities, expand its customer portfolio, and strengthen its market presence in the UK.
- In July 2024, Tech Etch, a leading provider of precision-engineered components and assemblies, announced DigiKey as its new distribution partner. This strategic collaboration is set to broaden access to Tech Etch’s innovative products and solutions, serving a wider global customer base.
- In October 2023, PPG’s SEM Products division unveiled the GLADIATOR XC Matte Extreme Coating, a high-performance, low-gloss urethane protective coating. Designed for a variety of industries, including automotive, light industrial, marine, recreational vehicles, emergency vehicles, and recreational equipment, it promises superior durability and protection.
- In September 2023, Henkel introduced the multifunctional Bergquist Gap Pad TGP EMI4000, a silicone-free thermal gap pad that offers both high thermal conductivity (4W/mK) and EMI shielding capabilities, effective up to 77 GHz frequencies.
Market Concentration & Characteristics:
The Electromagnetic Interference (EMI) Shielding Materials Market is moderately concentrated, with a mix of established global players and emerging companies driving innovation. Leading players, including 3M Company, Laird Performance Materials, and Henkel AG & Co. KGaA, hold significant market shares due to their advanced technologies and established brand presence. These companies leverage their extensive R&D capabilities to develop cutting-edge materials, such as nanomaterials, conductive polymers, and carbon-based materials, to stay competitive. Additionally, the market is characterized by strong competition in terms of product differentiation, with companies focusing on offering customizable, high-performance shielding solutions tailored to specific industry needs. Smaller companies often target niche segments, developing innovative solutions for unique applications in electronics, automotive, and aerospace. As demand for EMI shielding grows, especially with the rise of 5G technology and electric vehicles, the market is likely to witness both consolidation and further innovation, with increased investments in sustainable and cost-effective materials.
Report Coverage:
The research report offers an in-depth analysis based on Material, Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for EMI shielding materials will continue to rise with the growing adoption of 5G technology and its associated devices.
- Electric vehicles (EVs) and autonomous vehicles will increasingly require advanced EMI shielding solutions to ensure reliable operation of their electronic systems.
- The need for EMI shielding will grow in wearable electronics and medical devices as these products become more integrated with advanced technologies.
- Companies will focus on developing lightweight and flexible EMI shielding materials to cater to the needs of compact and portable electronic devices.
- The development of eco-friendly and recyclable materials will become a key trend in the market as sustainability gains importance.
- Continued advancements in nanotechnology and carbon-based materials will drive the creation of more efficient EMI shielding solutions.
- Regulatory standards governing electromagnetic emissions will tighten, prompting industries to adopt better EMI shielding technologies.
- Asia-Pacific will lead market growth, driven by high demand in manufacturing hubs like China, Japan, and South Korea.
- Increased investments in research and development by key players will lead to continuous innovation in EMI shielding materials.
- The market will see more strategic partnerships and collaborations between companies to enhance product offerings and expand geographic reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Electromagnetic Interference (EMI) Shielding Materials Market?
What factors are driving the growth of the Electromagnetic Interference (EMI) Shielding Materials Market?
What are some challenges faced by the Electromagnetic Interference (EMI) Shielding Materials Market?
What are some challenges faced by the EMI Shielding Materials Market?
Who are the major players in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 EMI Shielding Materials Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global EMI Shielding Materials Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,444 million → 2032: USD 15,364.95 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 EMI Shielding Materials Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. EMI Shielding Materials Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 EMI Shielding Materials Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 EMI Shielding Materials Market Drivers
- 3.3 EMI Shielding Materials Market Restraints & Challenges
- 3.4 EMI Shielding Materials Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 EMI Shielding Materials Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 EMI Shielding Materials Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, EMI Shielding Materials category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 EMI Shielding Materials Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. EMI Shielding Materials Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the EMI Shielding Materials market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 EMI Shielding Materials Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 EMI Shielding Materials Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 EMI Shielding Materials Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in EMI Shielding Materials (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New EMI Shielding Materials Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global EMI Shielding Materials Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America EMI Shielding Materials Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe EMI Shielding Materials Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific EMI Shielding Materials Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America EMI Shielding Materials Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East EMI Shielding Materials Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa EMI Shielding Materials Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. EMI Shielding Materials Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
