
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Floating Solar Panels Market Size 2023 | USD 1958.20 Million |
| Floating Solar Panels Market, CAGR | 16.20% |
| Floating Solar Panels Market Size 2032 | USD 7563.32 Million |
Market Insights
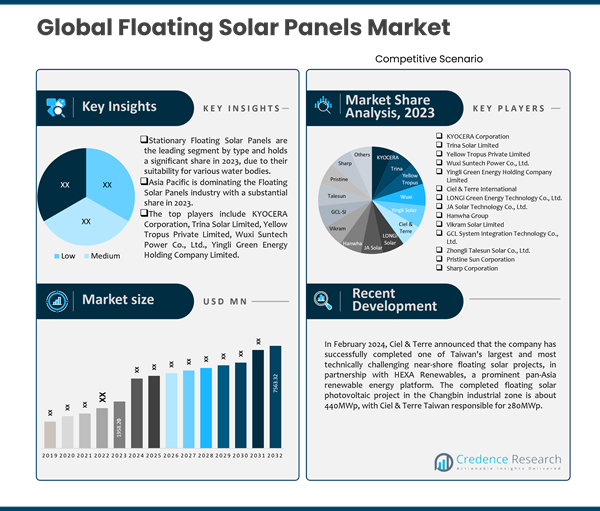
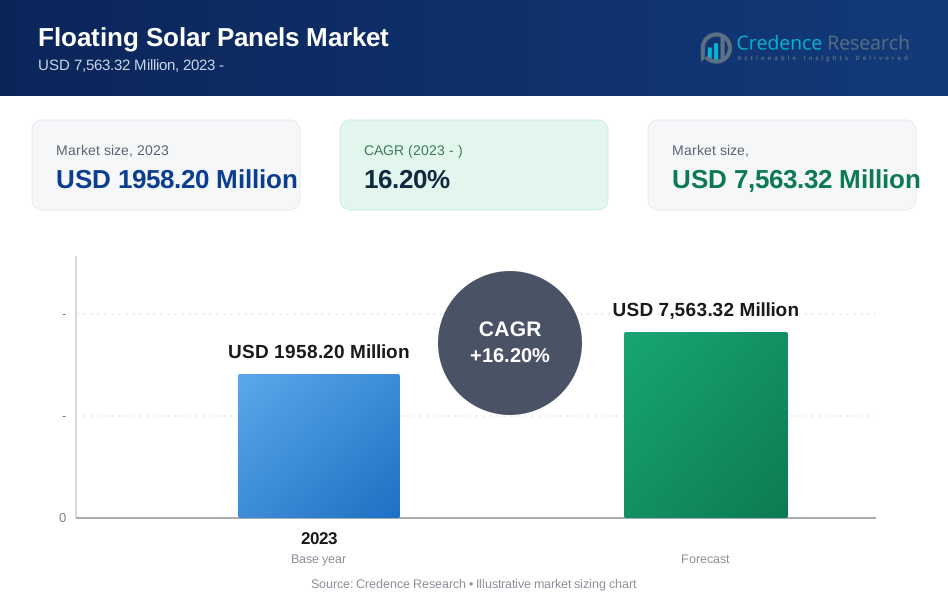
- The global demand for floating solar panels was valued at USD 1958.20 Million in 2023 and is expected to reach USD 7563.32 Million in 2032, growing at a CAGR of 16.20% between 2024 and 2032.
- The stationary floating solar panels are the market leader by type, accounting for a significant portion of total value in 2023, while the solar tracking floating solar panels segment is expected to grow rapidly throughout the forecast period.
- The 5 MW - 50 MW segment dominates the market in terms of capacity, accounting for a significant portion in 2023. The above 50 MW segment is predicted to expand at a high CAGR.
- Over the projection period, monocrystalline silicon technology is expected to expand at the highest rate, while polycrystalline silicon dominates the market in 2023 with a substantial share.
- Asia Pacific is dominating the floating solar panels industry with a substantial share in 2023, while Asia Pacific is expected to grow at the highest rate during the forecast period.
- The market's primary possibilities include innovative floating structures that maximize energy capture, advanced photovoltaic technologies that increase efficiency, scalable installation solutions to meet varying energy demands, and integrated energy storage systems to ensure consistent power supply.
Executive Summary
Market Definition
Floating solar panels, also known as floating photovoltaic (FPV) systems, are solar panels mounted on bodies of water, such as lakes, reservoirs, and ponds, instead of being installed on land. These systems utilize the water surface to host photovoltaic modules, which convert sunlight into electricity through semiconductor materials like silicon.
Floating solar panels work similarly to traditional land-based solar arrays but offer unique advantages. They benefit from the natural cooling effect of water, which enhances solar panel efficiency and lifespan by reducing heat-induced degradation.
Additionally, their installation helps to conserve land space, making them particularly suitable for densely populated areas where land availability is limited. Floating solar panels also reduce water evaporation from reservoirs and provide opportunities for dual land-water use, such as combining solar energy generation with water resource management. This innovative approach to solar energy production contributes to sustainable energy practices while leveraging underutilized water surfaces for renewable power generation.
Market Overview
The global floating solar panels market has witnessed steady growth in recent years and is expected to grow at a CAGR of 16.20% between 2024 and 2032. The market was valued at USD 1958.20 million in 2023 and is expected to reach USD 7563.32 million in 2032.
The floating solar panels market is experiencing significant growth due to the limited availability of land for traditional solar panel installations in several densely populated regions. Floating solar panels offer a solution by utilizing water surfaces such as lakes, reservoirs, and other bodies of water. Moreover, by using water surfaces, the environmental impact associated with land use is minimized. This leads to less deforestation, habitat disruption, and soil degradation.
Furthermore, government investments and policies are significant in driving the growth of the floating solar panels market. Financial incentives, such as subsidies, grants, and tax credits, significantly offset the initial costs of installing floating solar panels, making these investments more attractive. Regulatory support, including renewable energy mandates and simplified permitting processes, creates a favorable environment for the adoption of floating solar technology. Additionally, public funding for research and development (R&D) helps drive innovation and reduce costs, further enhancing the competitiveness of floating solar solutions.
In addition, continuous technological advancements and innovations in the field of solar energy are further driving the global floating solar panels market. The development of more efficient and cost-effective photovoltaic (PV) technologies has significantly enhanced the viability and attractiveness of floating solar panels. Innovations such as bifacial solar panels, which can capture sunlight from both sides and advancements in floating structures that withstand harsh aquatic environments are making floating solar installations more durable and efficient, thereby increasing their adoption.
Segmentation by type
- Stationary Floating Solar Panels are the leading segment by type and hold a substantial share in 2023. These panels are simpler in design, easier to install, and generally more cost-effective compared to solar tracking systems. Their widespread adoption is driven by their suitability for various water bodies, including reservoirs, lakes, and ponds, making them the dominant segment in the market.
- Solar tracking floating solar panels are the fastest-growing segment due to their higher efficiency and energy output, as these systems can adjust the angle of the panels to follow the sun's trajectory throughout the day. Moreover, advancements in tracking technology, increasing demand for maximizing energy generation, and the growing interest in large-scale renewable energy projects are driving the rapid adoption of solar tracking floating solar panels.
Segmentation by Capacity
- The 5 MW - 50 MW segment boasts the dominating position in the floating solar panels industry, holding a massive share in 2023. Projects within this capacity range are optimal for balancing cost, installation complexity, and energy output, making them popular for both commercial and utility-scale applications. This segment's broad applicability to various settings and its ability to meet significant energy demands contribute to its dominant market share.
- The above 50 MW segment is expected to grow with the highest CAGR during the projected period due to the increasing number of large-scale projects aimed at maximizing renewable energy output. Governments and private sectors are investing heavily in large floating solar farms to meet rising energy needs and sustainability goals. Advances in technology and economies of scale are making high-capacity floating solar projects more feasible and attractive, thus driving the growth of this segment.
- The below 5 MW capacity segment holds a lower share compared to the 5MW-50MW segment.
Segmentation by Technology
- Polycrystalline silicon boasts the dominating position in the floating solar panels industry, holding an immense share in 2023 as they are widely used due to their cost-effectiveness and relatively high efficiency. They are easier and less expensive to manufacture compared to other panels, making them a popular choice for large-scale installations on water bodies.
- Monocrystalline Silicon is expected to grow at the highest rate due to the increasing demand for higher efficiency and better performance in solar panels. Monocrystalline panels offer higher efficiency and longer lifespan compared to polycrystalline and thin-film panels, making them increasingly attractive for new floating solar projects. As technology advances and production costs decrease, more projects are opting for monocrystalline silicon to maximize energy output and overall system performance.
- Thin film technology and other technologies contribute significantly to the growth of the market.
Segmentation by Region
- Asia Pacific is fuelling the growth of the floating solar panels industry with a massive share in 2023 due to
- Moreover, the Asia Pacific market is expected to grow at the highest rate during the forecasted period.
- The rest of the world, including Latin America, the Middle East, and Africa, supplies the remaining demand for the floating solar panels industry.
Asia Pacific holds the dominant share of the floating solar panels market and is expected to maintain its dominance during the forecast period. Moreover, the region is anticipated to be the fastest-growing market for floating solar panels during the forecast period. This growth can be attributed to increasing government initiatives and support, which are driving the adoption of floating solar panels across the region. For instance, in February 2022, the Government of India announced that under its Panchamrita agenda, the country aims to target of installing 500 gigawatts (GW) of renewable energy by 2030, including floating solar panels. In March 2024, the government of India laid the foundation stone for its largest floating solar power plant with a capacity of 15MW/22MWp.
Moreover, the presence of leading market players such as Trina Solar, Yellow Tropus Pvt. Ltd., Wuxi Suntech Power Co., Ltd., and LONGi Solar are continuously developing innovative floating solar technologies and expanding their business in the Asia Pacific region is further boosting the growth of the Market. For instance, in August 2022, Trina Solar secured a 50 MWac (71 MWdc) Floating Solar Photovoltaic (FPV) project in the Malaysian state of Sarawak. The project will be located at the Batang Ai Hydroelectric Plant and will be built on the plant's reservoir surface of 191.12 hectares.
Key Highlights of the Report
The global Floating Solar Panels Market is segmented by type, capacity, technology, and region. Stationary Floating Solar Panels are the most popular segment, while 5 MW - 50 MW is the primary capacity range. In addition, polycrystalline silicon is the most demanding technology, with the Asia Pacific region leading the market share.
The floating solar panels market is driven by limited land availability for traditional solar installations in densely populated areas. Additionally, government investments and policies play a crucial role in the market growth, offering financial incentives like subsidies, grants, and tax credits, as well as regulatory support through renewable energy mandates and streamlined permitting processes. Furthermore, technological advancements, including more efficient photovoltaic technologies and durable floating structures, improve the viability and appeal of floating solar panels, increasing their adoption.
Nonetheless, Asia Pacific is anticipated to have the greatest share of the worldwide Floating Solar Panels Market, driven by increasing government initiatives and support. Moreover, the presence of leading market players who are developing innovative technologies and expanding their businesses in the region further boosts market growth.
What Are the Main Drivers of the Global Floating Solar Panels Market?
The growth of the Floating Solar Panels Market is propelled by the limited land availability for traditional solar installations in densely populated regions. Moreover, government investments and policies also play a crucial role in market growth, offering financial incentives such as subsidies, grants, and tax credits and providing regulatory support through renewable energy mandates and simplified permitting processes. Additionally, technological advancements, including more efficient photovoltaic technologies and durable floating structures, enhance the viability and attractiveness of floating solar panels, boosting their adoption.
What Are the Major Challenges Faced by the Global Floating Solar Panels Market?
The global floating solar panels market faces significant restraint due to the high initial investment and installation costs. These expenses are substantially higher compared to traditional ground-mounted solar systems, as they require specialized materials and technologies to ensure stability and durability on water surfaces. Additionally, there are technical challenges and maintenance issues associated with water-based environments. These include the need for regular cleaning due to biofouling, potential corrosion from water exposure, and the complexity of anchoring and mooring systems, which can increase operational costs and deter potential investors.
What Are the Growth Opportunities in the Global Floating Solar Panels Market?
The integration of floating solar panels with other renewable energy technologies, such as wind or hydroelectric power, presents a significant opportunity for the global market. Hybrid systems can maximize energy production by leveraging the complementary nature of different energy sources. For instance, combining floating solar with hydroelectric plants can optimize water usage and energy generation, especially during dry seasons when water levels are low. This approach enhances overall energy efficiency and provides a more stable and reliable power supply. Additionally, hybrid systems can reduce the variability associated with solar energy, making renewable energy solutions more attractive to grid operators and utility companies.
Market Drivers
Growing Government Investment and Projects
One of the significant drivers propelling the global floating solar panels market is the increasing government investments and projects aimed at expanding renewable energy infrastructure. For instance, in April 2024, the U.S. government announced a funding of USD 19.5 million for multiple federal projects focusing on the deployment of solar panels over irrigation canals. This initiative is part of a broader strategy to enhance the country's renewable energy capacity and optimize land use.
These projects play a crucial role in boosting the market for floating solar panels. By leveraging existing water bodies such as irrigation canals, the installation of solar panels mitigates land use conflicts, reduces water evaporation, and enhances energy generation efficiency. Moreover, such government-backed projects provide financial support and create a favorable regulatory environment, encouraging private-sector participation and innovation in floating solar technology, thereby driving the growth of the market.
Market Restraints
High Installation and Maintenance Cost
The floating solar panels market faces significant restraint due to the high initial investment and installation costs associated with these systems. Unlike traditional ground-mounted or rooftop solar installations, floating solar systems require specialized equipment and materials to ensure durability and efficiency in water-based environments. The construction of floating platforms, anchoring systems, and electrical infrastructure capable of withstanding water exposure contributes to the elevated costs. Additionally, logistical challenges, such as transporting materials to remote water bodies and ensuring proper installation, further increase the initial expenditure. These factors often deter potential investors and project developers, especially in regions with limited financial resources or higher perceived risks, thereby slowing market growth.
Floating solar panels also encounter technical challenges and maintenance issues that can hinder their widespread adoption. Operating in aquatic environments subjects these systems to unique stresses, such as constant exposure to moisture, fluctuating water levels, and the potential for biofouling, where aquatic organisms accumulate on surfaces. These conditions can compromise the efficiency and longevity of solar panels, requiring more frequent maintenance and specialized cleaning methods to ensure optimal performance.
Additionally, the anchoring and mooring systems must be robust enough to withstand water currents, wind, and potentially extreme weather events, adding complexity and cost to the design and upkeep. These ongoing technical and maintenance challenges can lead to increased operational costs and downtime, making floating solar projects less attractive compared to traditional land-based solar installations.
Opportunities
Development of Hybrid Solar Systems Combining Floating Solar with Other Renewable Technologies
The development of hybrid solar systems presents a significant opportunity in the global floating solar panels market. By integrating floating solar panels with other renewable energy technologies, such as wind, hydro, or energy storage systems, the efficiency and reliability of power generation can be significantly enhanced. These hybrid systems can take advantage of complementary generation profiles, where solar power can be harnessed during sunny days, and wind or hydropower can compensate for cloudy or rainy conditions. This integration not only optimizes energy production but also provides a more consistent and reliable power supply, addressing one of the key challenges of renewable energy-intermittency. Moreover, the co-location of different renewable technologies can lead to shared infrastructure and maintenance costs, further driving down the overall expenses and making renewable energy projects more financially viable.
Additionally, the combination of floating solar with other renewable technologies can maximize the utilization of available space and resources. For instance, floating solar panels can be installed on reservoirs used for hydroelectric power, leveraging existing infrastructure and grid connections. This approach minimizes land use conflicts and can be particularly beneficial in regions with limited land availability but abundant water bodies. Furthermore, hybrid systems can enhance the energy resilience of local communities by providing a diversified energy mix, reducing dependency on a single power source. As the demand for clean and sustainable energy continues to grow, the development of such innovative hybrid systems will play a crucial role in advancing the adoption of renewable energy worldwide, making the floating solar panels market an attractive prospect for investors and stakeholders.
Competitive Landscape
Key Players
The global floating solar panels market is highly competitive, with several key players. Some of the major players in the market are as follows:
- KYOCERA Corporation
- Trina Solar Limited
- Yellow Tropus Private Limited
- Wuxi Suntech Power Co., Ltd.
- Yingli Green Energy Holding Company Limited (Yingli Solar)
- Ciel & Terre International
- LONGi Green Energy Technology Co., Ltd. (LONGi Solar)
- JA Solar Technology Co., Ltd.
- Hanwha Group
- Vikram Solar Limited
- GCL System Integration Technology Co., Ltd. (GCL-SI)
- Zhongli Talesun Solar Co., Ltd. (Talesun)
- Pristine Sun Corporation
- Sharp Corporation
These organizations prioritize business expansions, partnerships, and collaborations to stay competitive.
The global floating solar panels market's key players continually seek to stay ahead by expanding their businesses globally.
In February 2024, Ciel & Terre announced that the company has successfully completed one of Taiwan's largest and most technically challenging near-shore floating solar projects in partnership with HEXA Renewables, a prominent pan-Asia renewable energy platform. The completed floating solar photovoltaic project in the Changbin industrial zone is about 440MWp, with Ciel & Terre Taiwan responsible for 280MWp.
In September 2022, JA Solar announced that the company had completed the installation of a 10.7-MW floating solar park at the Tel Yitzhak Reservoir in Israel on behalf of local project developer S'energy. This project was part of a previously signed deal between the two companies for a total of 50 MW of capacity. The floating solar park utilizes JA Solar's DeepBlue 3.0 PV modules, which offer steady performance in high temperatures and humidity.
How are Companies Performing in the Floating Solar Panels Market?
The global floating solar panels market is highly competitive, with several key players.
Startups are playing a pivotal role in shaping the landscape of the floating solar panels industry, bringing innovation and fresh perspectives to the market.
Ocean Sun, a Norwegian startup, employs flexible floating structures equipped with silicon solar modules and proprietary non-permeable membranes. This design enhances thermal efficiency by maximizing contact with water bodies, offering a durable and cost-effective solution for floating solar power generation.
HelioRec, a French startup, pioneers end-to-end solar projects integrated with hydropower, focusing on minimizing carbon footprints and deployment costs. Their approach includes comprehensive feasibility studies and the use of recycled materials, reinforcing sustainability across their floating solar installations.
HELIOFLOAT, an Austrian startup, introduces floating concentrated solar power (CSP) platforms designed for offshore applications. These platforms maximize solar efficiency by minimizing shading issues and allowing natural cooling of solar panels, ensuring optimal performance and system reliability.
Summary of Key Findings
- The floating solar panels market is driven by limited land availability for traditional solar installations in densely populated areas. Additionally, government investments and policies play a crucial role in the market growth, offering financial incentives like subsidies, grants, and tax credits, as well as regulatory support through renewable energy mandates and streamlined permitting processes. Furthermore, technological advancements, including more efficient photovoltaic technologies and durable floating structures, improve the viability and appeal of floating solar panels, increasing their adoption.
- Market segmented by type, capacity, technology, and region.
- Asia Pacific is leading market growth; the market is highly competitive with key players, including KYOCERA Corporation, Trina Solar Limited, Yellow Tropus Private Limited, Wuxi Suntech Power Co., Ltd., Yingli Green Energy Holding Company Limited (Yingli Solar), Ciel & Terre International, LONGi Green Energy Technology Co., Ltd. (LONGi Solar), JA Solar Technology Co., Ltd., Hanwha Group, Vikram Solar Limited, GCL System Integration Technology Co., Ltd. (GCL-SI), Zhongli Talesun Solar Co., Ltd. (Talesun), Pristine Sun Corporation, and Sharp Corporation.
Future Outlook
- Positive outlook for the global floating solar panels market with significant growth potential in the Asia Pacific region.
- One of the main factors promoting the market's expansion is limited land availability for traditional solar installations, along with favorable government investments and policies.
- During the forecast period, High initial investment and installation costs, coupled with technical challenges and maintenance issues in water-based environments, act as significant restraints in the global floating solar panels market
- To stay competitive, key firms in the Floating Solar Panels Market should prioritize innovation in technology, cost-effective solutions, strategic partnerships, and sustainable practices.
How CXOs Can Benefit from the Credence Research Floating Solar Panels Market Report
The Credence Research Floating Solar Panels Market Report provides CXOs with a comprehensive overview of the market, including:
- Market size and growth forecast:The report provides detailed estimates of the global floating solar panels market size, segmented by type, capacity, technology, and region. It also includes forecasts for the market through 2032 based on key trends and drivers.
- Market segmentation:The report segments the Floating Solar Panels Market by type, capacity, application, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive Landscape:The report profiles the key players in the Floating Solar Panels Market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers:The report identifies and analyses the key trends and drivers shaping the Floating Solar Panels Market. This information can help CXOs make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research Floating Solar Panels Market Report to:
- Identify growth opportunities:The report can help CXOs to identify new growth opportunities in the Floating Solar Panels Market. For example, the report identifies emerging trends in floating solar panel technologies, regional market dynamics influencing adoption rates, and strategic partnerships that can enhance market penetration and technological innovation in the industry.
- Make informed investment decisions:The report can help CXOs make informed investment decisions about the floating solar panels industry. For example, it provides insights into the key factors to consider when evaluating and selecting floating solar panel providers.
- Develop competitive strategies:The report can help CXOs develop competitive strategies for their floating solar panels businesses. For example, the report identifies the key strategies that floating solar panel providers are using to differentiate themselves from their competitors.
- Track market developments:The report can help CXOs monitor market developments and stay ahead of the curve. For example, it provides insights into the latest trends and innovations in the Floating Solar Panels Market.
Overall, the Credence Research Floating Solar Panels Market Report is a valuable resource for CXOs who are looking to gain a deeper understanding of the market and identify opportunities for growth.
Segmentation
- By Type
- Stationary Floating Solar Panels
- Solar Tracking Floating Solar Panels
-
By Capacity
- Below 5 MW
- 5 MW - 50 MW
- Above 50 MW
-
By Technology
- Monocrystalline Silicon
- Polycrystalline Silicon
- Thin Film
- Others
-
By Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Adjacent Markets
In the Floating Solar Panels Market, several adjacent markets have high revenue growth opportunities. The key adjacent markets for Floating Solar Panels Market -
Adjacent Markets |
||
| Traditional Solar Panels Market | Wind Energy Market | Hydroelectric Power Market |
| Energy Storage Market | Water Management Systems Market | Marine Engineering Market |
| Electricity Grid Infrastructure Market | Environmental Monitoring Market | Desalination Plant Market |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Limited Land Availability in Densely Populated Regions
Floating solar panels utilize underused water surfaces, making them ideal for regions where land is scarce or expensive, such as parts of Asia and Europe. This enables solar energy expansion without competing for valuable land resources.
Government Investments and Policy Support
Subsidies, grants, tax credits, and renewable energy mandates from governments significantly reduce the financial barriers to floating solar adoption. Regulatory support and public funding for R&D further accelerate market growth by encouraging private sector participation.
Technological Advancements in Photovoltaics and Floating Structures
Innovations such as bifacial panels, improved floating platforms, and advanced anchoring systems have increased the efficiency, durability, and cost-effectiveness of floating solar installations, making them more attractive for large-scale deployment.
Integration with Existing Water Infrastructure
Floating solar panels can be installed on reservoirs, irrigation canals, and hydroelectric dams, leveraging existing infrastructure for dual use. This not only optimizes space but also reduces water evaporation and can enhance the efficiency of both energy and water management systems.
Rising Demand for Hybrid Renewable Systems
The ability to combine floating solar with other renewables, such as hydropower or energy storage, creates hybrid systems that maximize energy output and grid stability. This integration addresses intermittency issues and increases the overall appeal of floating solar projects to utilities and investors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global floating solar panels market?
What is the expected growth rate of the floating solar panels market between 2024 and 2032?
Which segment is leading the market share in terms of Type?
Which segment is leading the market share in terms of Capacity?
Which segment is expected to post the highest CAGR during the forecast period in terms of Technology?
Which region is dominating the floating solar panels market share?
Who are the major players in the global floating solar panels market?
What are the major market drivers of the global floating solar panels market?
What is the major market restraint of the Floating Solar Panels Market?
What are the major market opportunities of the global floating solar panels market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Stationary Floating Solar Panels
- 1.2.2 Solar Tracking Floating Solar Panels
- 1.3 By Capacity
- 1.3.1 Below 5 MW
- 1.3.2 5 MW - 50 MW
- 1.3.3 Above 50 MW
- 1.4 By Technology
- 1.4.1 Monocrystalline Silicon
- 1.4.2 Polycrystalline Silicon
- 1.4.3 Thin Film
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1958.20 Million → 2032: USD 7,563.32 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Floating Solar Panels Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Floating Solar Panels Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Floating Solar Panels Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Floating Solar Panels Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Floating Solar Panels Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Floating Solar Panels Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Floating Solar Panels Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Floating Solar Panels Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1958.20 Million → 2032: USD 7,563.32 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Floating Solar Panels Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Stationary Floating Solar Panels
- 12.3.7.2 Solar Tracking Floating Solar Panels
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Capacity - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Below 5 MW
- 12.4.7.2 5 MW - 50 MW
- 12.4.7.3 Above 50 MW
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Monocrystalline Silicon
- 12.5.7.2 Polycrystalline Silicon
- 12.5.7.3 Thin Film
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Floating Solar Panels Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Share, 2023
- 13.2 Regional Market Forecast, 2023-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Floating Solar Panels Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Floating Solar Panels Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Trina Solar Limited
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 KYOCERA Corporation
- 17.4 Wuxi Suntech Power Co., Ltd.
- 17.5 LONGi Green Energy Technology Co., Ltd. (LONGi Solar)
- 17.6 JA Solar Technology Co., Ltd.
- 17.7 Ciel & Terre International
- 17.8 Yingli Green Energy Holding Company Limited (Yingli Solar)
- 17.9 Hanwha Group
- 17.10 Vikram Solar Limited
- 17.11 Sharp Corporation
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

