
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Food Blenders and Mixers Market Size 2024 | USD 9,899.00 Million |
| Food Blenders and Mixers Market, CAGR | 6.10% |
| Food Blenders and Mixers Market Size 2032 | USD 15,896.97 Million |
Market Overview:
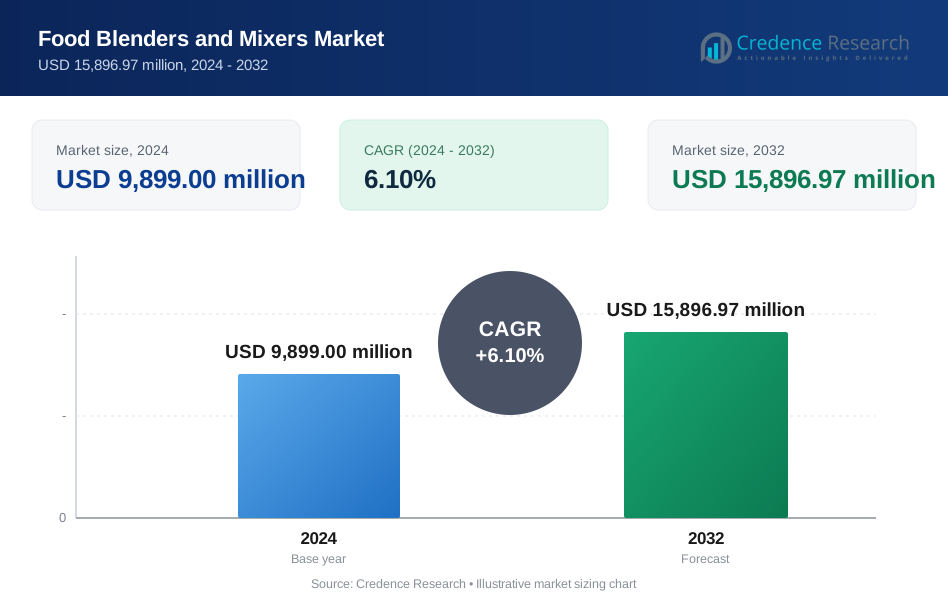
The food blender and mixer market is projected to grow significantly from USD 9,899.00 million in 2024 to USD 15,896.97 million by 2032, reflecting a Compound Annual Growth Rate (CAGR) of 6.10%.
This growth is driven by the increasing demand for efficient and versatile kitchen appliances in both residential and commercial settings. Food blenders and mixers, known for their ability to emulsify, mix, and crush food products, are becoming essential tools in modern kitchens. The market’s expansion is further supported by technological advancements that enhance the performance and convenience of these appliances.
The primary drivers of the food blender and mixer market include the rising consumption of processed and convenience foods, the growing health consciousness among consumers, and the increasing adoption of advanced kitchen appliances. The expanding food processing industry, coupled with the rising demand for ready-to-eat products, is significantly boosting the market. Additionally, the integration of smart technologies, such as the Internet of Things (IoT) and touchscreens, in food blenders and mixers is enhancing their functionality and user experience. For instance, the growing trend of consuming healthy beverages like smoothies and freshly squeezed juices is driving the demand for high-performance blenders and mixers.
The food blender and mixer market is geographically segmented into North America, Europe, Asia Pacific, South America, and the Middle East and Africa. Asia Pacific is anticipated to hold the largest market share during the forecast period, driven by rapid industrialization, urbanization, and the increasing adoption of modern kitchen appliances in countries like China, India, and Japan. North America and Europe are also expected to witness substantial growth due to the rising health consciousness among consumers and the presence of key market players in these regions. The Middle East and Africa, along with South America, are projected to experience moderate growth, supported by the expanding food processing industry and the increasing demand for convenience foods.
Market Drivers:
Rising Demand for Processed and Convenience Foods:
The increasing consumption of processed and convenience foods is a significant driver of the food blender and mixer market. As lifestyles become busier, consumers are seeking quick and easy meal solutions. For instance, a government survey in the United States reported that 60% of households regularly purchase ready-to-eat meals. This trend is driving the demand for food blenders and mixers, which are essential in the preparation of a wide range of processed foods, including smoothies, sauces, and soups.
Growing Health Consciousness Among Consumers:
Health consciousness is on the rise globally, leading to an increased demand for kitchen appliances that support healthy eating habits. Food blenders and mixers enable consumers to prepare nutritious meals and beverages at home. For example, a survey conducted by the UK government found that 45% of respondents are more inclined to prepare fresh juices and smoothies at home to ensure they consume their daily intake of fruits and vegetables. This growing focus on health and wellness is boosting the adoption of food blenders and mixers.
Technological Advancements in Kitchen Appliances:
Technological innovations are significantly enhancing the functionality and convenience of food blenders and mixers. Modern appliances are equipped with features such as touchscreens, smart controls, and wireless connectivity. For instance, GE Profile launched a smart mixer with Auto Sense technology in December 2022, which was recognized as a CES Innovations Awards Honoree in January 2023. These advancements are making food blenders and mixers more user-friendly and efficient, driving their demand in both residential and commercial settings.
Expansion of the Food Processing Industry:
The food processing industry is expanding rapidly, further driving the demand for food blenders and mixers. Governments worldwide are investing in the development of the food processing sector to boost economic growth. For example, the Indian government launched the Pradhan Mantri Kisan SAMPADA Yojana, aiming to create modern infrastructure for food processing and reduce wastage. Such initiatives are propelling the growth of the food blender and mixer market by increasing the need for efficient food processing equipment.
Market Trends:
Rise in Home Cooking:
The recent pandemic has significantly increased the trend of home cooking, nurturing the food blender and mixer market. As people spent more time at home, they rediscovered the joy of preparing meals from scratch. For instance, a survey conducted by the UK government in 2021 revealed that households reported cooking more frequently at home compared to pre-pandemic times. This shift has driven the demand for efficient kitchen appliances like blenders and mixers, which simplify meal preparation and enhance the cooking experience.
Surge in Health and Wellness Awareness:
There is a growing awareness of health and wellness among consumers, leading to an increased demand for kitchen appliances that support healthy eating habits. Food blenders and mixers enable the preparation of nutritious meals and beverages at home. For example, a government survey in the United States found that 45% of respondents are more inclined to prepare fresh juices and smoothies at home to ensure they consume their daily intake of fruits and vegetables. This trend is boosting the adoption of food blenders and mixers as essential tools for maintaining a healthy lifestyle.
Technological Advancements:
Technological innovations are significantly enhancing the functionality and convenience of food blenders and mixers. Modern appliances are equipped with features such as touchscreens, smart controls, and wireless connectivity. GE Profile launched a smart mixer with Auto Sense technology in December 2022, which was recognized as a CES Innovations Awards Honoree in January 2023. These advancements are making food blenders and mixers more user-friendly and efficient, driving their demand in both residential and commercial settings.
Growth of E-commerce:
The expansion of the e-commerce sector is leading to increased sales of food blenders and mixers. Online platforms provide consumers with a wide range of options and the convenience of home delivery. For example, a report by the Indian government highlighted a increase in online sales of kitchen appliances during the festive season of 2022. This growth in e-commerce is making it easier for consumers to access and purchase food blenders and mixers, further driving market growth.
Market Challenges Analysis:
Supply Chain Disruptions:
One of the significant challenges faced by the food blender and mixer market is supply chain disruptions. These disruptions can lead to delays in the production and delivery of components, affecting the overall manufacturing process. For instance, the COVID-19 pandemic highlighted the vulnerability of global supply chains, causing significant delays and increased costs for manufacturers.
Stringent Regulations:
Complying with stringent regulations on food safety and labelling is another major restraint. Governments worldwide have implemented strict regulations to ensure the safety and quality of food products. These regulations require manufacturers to adhere to specific standards, which can increase production costs and complicate the manufacturing process.
High Installation Costs:
The large footprint and high installation costs associated with food blenders and mixers make it challenging for small-scale industrial players to afford their implementation. This financial barrier limits the adoption of advanced food processing equipment among smaller enterprises, restricting market growth.
Fluctuating Raw Material Prices:
The food blender and mixer market is also affected by fluctuating raw material prices. The rising cost of energy and power, along with the volatility in the prices of raw materials such as stainless steel and other metals, can significantly impact production costs. These fluctuations can lead to increased prices for end consumers, potentially reducing demand.
Environmental Concerns:
Environmental imbalance and the rising cost of energy and power are additional challenges. Manufacturers are under pressure to adopt sustainable practices and reduce their carbon footprint. This transition requires significant investment in new technologies and processes, which can be a financial burden for many companies.
Market Segmentation Analysis:
By Type:
The food blender and mixer market is segmented into high shear mixers, shaft mixers, ribbon blenders, double cone blenders, planetary mixers, and screw mixers. High shear mixers hold a significant market share due to their efficiency in emulsifying and homogenizing food products. Shaft mixers and ribbon blenders are also widely used in the food processing industry for their ability to handle high-viscosity materials and provide uniform mixing.
By Technology:
The market is categorized based on processing technologies such as batch and continuous mixing. Batch mixing technology dominates the market, accounting for approximately 62.3% of the market share in 2022. This technology is preferred for its precision, consistency, and flexibility in production. Continuous mixing technology is also gaining traction due to its high output, efficiency, and automation-friendly features, making it suitable for large-scale food processing operations.
By End User:
The end-user segment of the food blender and mixer market includes the food and beverage industry, bakeries and confectioneries, and the pharmaceutical industry. The food and beverage industry is the largest end-user, driven by the demand for efficient and versatile kitchen appliances. Bakeries and confectioneries also contribute significantly to the market, utilizing blenders and mixers for various applications such as dough mixing and batter preparation. Additionally, the pharmaceutical industry is adopting these appliances for their precision and consistency in mixing ingredients.
Segmentations:
By Type,
- High Shear Mixers
- Shaft Mixers
- Ribbon Blenders
- Double Cone Blenders
- Planetary Mixers
- Screw Mixers
- Others
By Technology,
- Batch Mixing
- Continuous Mixing
By Application,
- Bakery Products
- Dairy Products
- Beverages
- Confectioneries
- Others
By Mode of Operation
- Semi-automatic
- Automatic
By Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America:
The North American food blender and mixer market is expected to witness substantial growth, driven by the increasing adoption of advanced kitchen appliances and the rising health consciousness among consumers. The United States and Canada are the major contributors to the market in this region. The presence of key market players and the growing emphasis on healthy eating habits are significant factors propelling market growth. North America holds a market share of approximately 25%.
Europe:
Europe is another prominent region in the food blender and mixer market, with countries like Germany, France, the United Kingdom, and Italy leading the way. The region’s focus on reducing carbon emissions and promoting sustainable practices is driving the demand for energy-efficient kitchen appliances. Additionally, the growing trend of home cooking and the increasing popularity of healthy beverages like smoothies and juices are boosting the market. Europe accounts for around 30% of the global market share.
Asia Pacific:
The Asia Pacific region is anticipated to dominate the food blender and mixer market during the forecast period, holding the largest market share of approximately 35%. Rapid industrialization, urbanization, and the increasing adoption of modern kitchen appliances in countries like China, India, and Japan are the primary drivers of market growth. The expanding middle-class population and the rising disposable incomes are also contributing to the increased demand for food blenders and mixers in this region.
South America:
South America is expected to experience moderate growth in the food blender and mixer market, with Brazil being the major contributor. The region’s focus on infrastructure development and the increasing adoption of modern kitchen appliances are driving market growth. South America holds a market share of around 5%.
Middle East and Africa:
The Middle East and Africa region is projected to witness steady growth in the food blender and mixer market, supported by ongoing infrastructure projects and the rising demand for high-performance kitchen appliances in various industries. Countries like the United Arab Emirates and South Africa are leading the market in this region. The Middle East and Africa account for approximately 5% of the global market share.
Key Player Analysis:
- GEA Group
- Tetra Laval
- SPX Flow
- Alfa Laval
- Marel
- Krones AG
- Sulzer Ltd
- Buhler
- JBT
- KHS Group
Competitive Analysis:
The food blender and mixer market is characterized by intense competition among key players striving to enhance their market presence through innovation and strategic partnerships. Companies like GEA Group, Tetra Laval, and SPX Flow are leading the market with their advanced technologies and high-quality products. These players focus on continuous product development and expanding their product portfolios to cater to diverse industry needs. Additionally, collaborations with research institutions and investments in R&D are common strategies to stay ahead in the market. The competitive landscape is further shaped by the entry of new players, which intensifies the competition and drives innovation. Overall, the market dynamics are influenced by the need for cost-effective, high-performance kitchen appliances, and the ability of companies to meet these demands through technological advancements and strategic initiatives.
Recent Developments:
- In February 2024 BlendJet, a leading brand in portable blenders, expanded its market reach by entering the Indian market. The company aims to achieve a revenue surge of USD 1.5 million in the region, capitalizing on the growing demand for convenient and healthy food options.
- In December 2023 GE Profile launched its innovative Smart Mixer with Auto Sense technology. This advanced mixer, recognized as a CES Innovations Awards Honoree in January 2023, features smart controls and automatic shut-off capabilities, enhancing user convenience and efficiency.
- In July 2022 Kamenny Vek introduced a new line of basalt fibre products with enhanced thermal stability and tensile strength. These products are targeted at the renewable energy sector, particularly for use in wind turbine blades. The company reported that initial trials showed a 20% improvement in performance compared to traditional materials.
Market Concentration & Characteristics:
The food blender and mixer market exhibit a moderate level of concentration, with several key players dominating the market. Companies such as GEA Group, Tetra Laval, and SPX Flow hold significant market shares due to their advanced technologies and extensive product portfolios. The market is characterized by continuous innovation, driven by the need for efficient and versatile kitchen appliances. Technological advancements, such as the integration of smart controls and IoT, are enhancing the functionality and user experience of food blenders and mixers. Additionally, the market is influenced by the growing demand for healthy and convenient food options, which is driving the adoption of these appliances in both residential and commercial settings. Despite the presence of established players, new entrants are also making their mark by offering innovative solutions and catering to niche markets.
Report Coverage:
The research report offers an in-depth analysis based on Type, Technology, Application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The food blender and mixer market is projected to grow significantly, with an estimated market value of USD 9,899.00 million in 2024, reaching USD 15,896.97 million by 2032.
- The market is expected to witness a Compound Annual Growth Rate (CAGR) of 6.10% during the forecast period from 2024 to 2032.
- Increasing demand for efficient and versatile kitchen appliances in both residential and commercial settings will drive market growth.
- The rising consumption of processed and convenience foods will boost the demand for food blenders and mixers.
- Technological advancements, such as the integration of smart controls and IoT, will enhance the functionality and user experience of these appliances.
- The growing health consciousness among consumers will lead to increased adoption of food blenders and mixers for preparing nutritious meals and beverages.
- The expansion of the food processing industry will further propel the market, driven by the demand for efficient food processing equipment.
- The Asia Pacific region is anticipated to dominate the market, driven by rapid industrialization, urbanization, and the increasing adoption of modern kitchen appliances.
- Collaborations and partnerships among key players will foster innovation and expand market reach.
- The growing emphasis on environmental sustainability will make energy-efficient food blenders and mixers a preferred choice.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the food blender mixer market?
What factors are driving the growth of the food blender mixer market?
What are some challenges faced by the food blender mixer market?
Who are the major players in the food blender mixer market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Food Blenders and Mixers Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Food Blenders and Mixers Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9,899.00 million → 2032: USD 15,896.97 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Food Blenders and Mixers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Food Blenders and Mixers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Food Blenders and Mixers Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Food Blenders and Mixers Market Drivers
- 3.3 Food Blenders and Mixers Market Restraints & Challenges
- 3.4 Food Blenders and Mixers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Food Blenders and Mixers Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Food Blenders and Mixers Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Food Blenders and Mixers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Food Blenders and Mixers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Food Blenders and Mixers Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Food Blenders and Mixers. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Food Blenders and Mixers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Food Blenders and Mixers Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Food Blenders and Mixers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Food Blenders and Mixers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Food Blenders and Mixers
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Food Blenders and Mixers Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Food Blenders and Mixers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Food Blenders and Mixers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Food Blenders and Mixers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Food Blenders and Mixers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Food Blenders and Mixers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Food Blenders and Mixers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Food Blenders and Mixers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
