
Market Overview
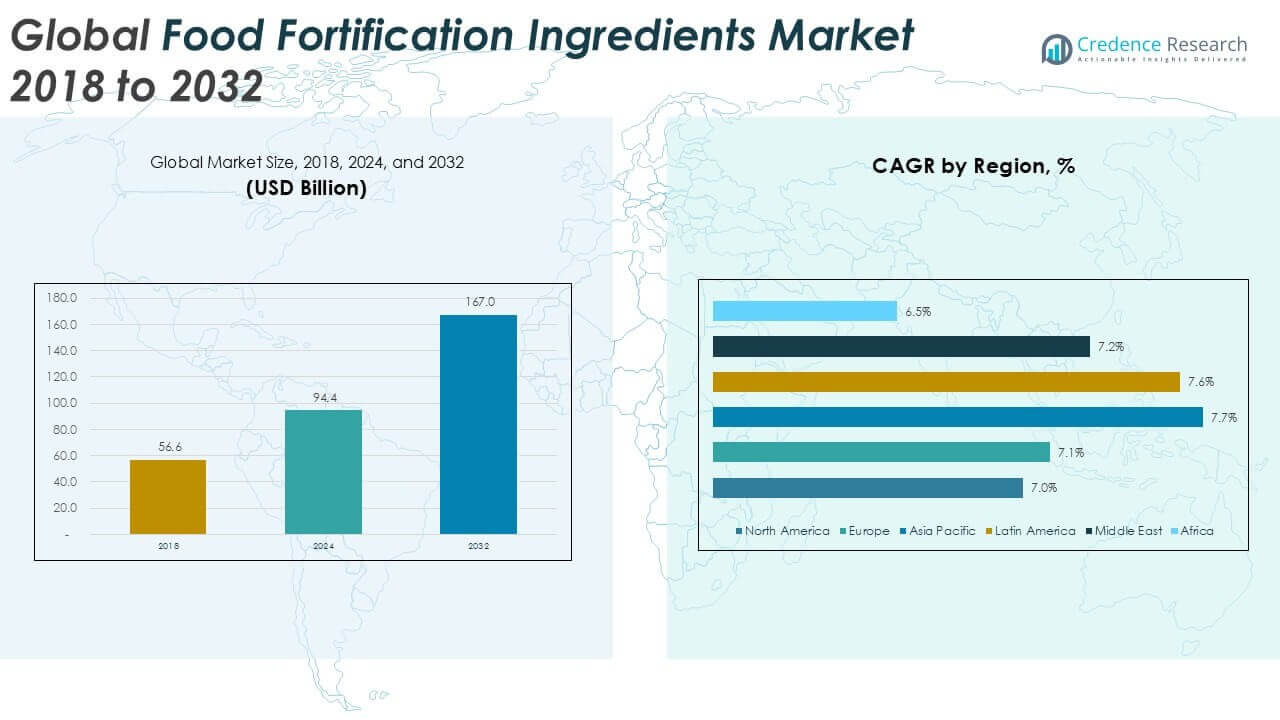
The Food Fortification Ingredients market size was valued at USD 56.6 Billion in 2018, increased to USD 94.4 Billion in 2024, and is anticipated to reach USD 167.0 million by 2032, growing at a CAGR of 7.33% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Fortification Ingredients Market Size 2024 | USD 94.4 Billion |
| Food Fortification Ingredients Market, CAGR | 7.33% |
| Food Fortification Ingredients Market Size 2032 | USD 167.0 Billion |
The Food Fortification Ingredients market is led by key players such as Cargill Incorporated, Archer Daniels Midland Company, Kerry Group, DuPont, BASF SE, DSM Nutritional Products, Glanbia PLC, Ingredion Incorporated, and General Mills, Inc. These companies drive market growth through innovation in nutrient delivery technologies, strategic partnerships, and regional expansion. Asia Pacific emerged as the leading region in 2024, commanding a 36.8% share of the global market, driven by large-scale government-led nutrition programs and rising consumer demand for functional foods. North America and Europe followed with 17.2% and 21.5% shares, respectively, supported by strong regulatory frameworks and high health awareness.
Market Insights
- The Food Fortification Ingredients market was valued at USD 94.4 billion in 2024 and is projected to reach USD 167.0 billion by 2032, growing at a CAGR of 7.33% during the forecast period.
- Rising awareness of micronutrient deficiencies and increasing government initiatives to fortify staple foods are key drivers fueling market growth globally.
- Technological advancements in nutrient encapsulation and bioavailability are supporting the demand for fortified functional foods, especially in urban and health-conscious populations.
- Asia Pacific holds the largest regional share at 36.8% in 2024, followed by Europe (21.5%) and North America (17.2%), while vitamins remain the leading product segment, accounting for over 30% of the market.
- High production costs, regulatory complexities, and concerns over altered taste and texture in fortified foods act as key restraints, particularly in cost-sensitive and developing markets.
Market Segmentation Analysis:
By Product:
The Vitamins sub-segment dominated the food fortification ingredients market in 2024, accounting for over 30% of the market share. This dominance is primarily driven by widespread use in addressing micronutrient deficiencies, especially in developing countries. The increasing prevalence of lifestyle-related disorders and growing awareness of the benefits of fortified foods have boosted demand for vitamin-enriched products. Vitamins A, D, and B complex are frequently added to dairy, cereal, and beverage products. Other sub-segments like Proteins & Amino Acids and Prebiotics & Probiotics are also experiencing steady growth due to rising interest in functional foods.
- For instance, DSM Nutritional Products developed Quali®-D, a patented form of vitamin D3, and reported supplying over 1,200 metric tons of this fortification ingredient annually for global food and beverage applications.
By Application
The Food & Beverages segment held the largest market share in 2024, contributing more than 50% of total revenue. The segment’s growth is supported by the rising trend of health-conscious consumption and governmental policies mandating nutrient fortification in staple foods such as flour, milk, and salt. Fortified beverages and ready-to-eat foods have seen strong consumer adoption, particularly in urban areas. Dietary Supplements are gaining traction due to the growing aging population and demand for convenient nutrition, while Animal Nutrition is expanding with increasing livestock productivity and pet health awareness.
- For instance, BASF SE's fortification solutions were integrated into over 250 food and beverage brands globally in 2023 through its Human Nutrition business, enhancing vitamin and mineral content across more than 45 countries.
By Distribution Channel
Online Retailers emerged as the fastest-growing distribution channel in 2024, capturing a significant portion of the market share due to convenience, broader product selection, and increasing internet penetration. E-commerce platforms have made fortified products more accessible, especially in remote regions. However, Departmental Stores remained the leading distribution channel, accounting for more than 40% of sales, supported by consumer preference for physical inspection and immediate purchase. The Others category, including pharmacies and specialty stores, serves a niche but growing market for targeted nutritional products.
Market Overview
Key Growth Drivers
Rising Prevalence of Micronutrient Deficiencies
The growing global burden of micronutrient deficiencies-especially in iron, iodine, vitamin A, and folic acid-is a primary driver for the food fortification ingredients market. Governments and health organizations are increasingly advocating for the inclusion of essential nutrients in staple foods to combat malnutrition. Initiatives such as mandatory fortification of flour, salt, and milk in various countries have significantly increased demand for fortification ingredients. These interventions aim to improve population health, particularly among children and pregnant women, thereby boosting the market’s growth trajectory.
- For instance, Cargill's food fortification initiative has supplied over 60,000 metric tons of iron and vitamin A premixes annually to national fortification programs in regions such as Sub-Saharan Africa and Southeast Asia.
Increasing Consumer Awareness and Health-Consciousness
Consumers are becoming more aware of the role nutrition plays in long-term health and disease prevention. This shift has accelerated demand for fortified foods and beverages that support immunity, cognitive development, and energy levels. Health-conscious individuals are actively seeking products with added functional benefits, driving food manufacturers to incorporate fortification ingredients across various product categories. The trend is particularly strong in urban populations and developed markets, where consumers are willing to pay a premium for products offering added nutritional value.
- For instance, Glanbia PLC reported that its Bioferrin® iron supplement was used in over 300 million servings of fortified health and wellness beverages sold globally in 2023, responding to growing consumer focus on iron and energy support.
Government Support and Regulatory Mandates
Government-led programs and regulations mandating food fortification are crucial growth enablers for the market. Many countries have implemented mandatory or voluntary fortification policies, especially for staple foods, to address public health concerns. For example, India’s Food Safety and Standards Authority (FSSAI) and the U.S. FDA have guidelines in place to regulate nutrient enrichment. Additionally, funding from global institutions like the WHO and UNICEF supports infrastructure development and awareness campaigns, fostering wider adoption of food fortification practices worldwide.
Key Trends & Opportunities
Technological Advancements in Fortification Methods
Innovations in microencapsulation, nano-delivery systems, and bioavailability-enhancing techniques are transforming how ingredients are added to foods without affecting taste, texture, or shelf life. These technologies improve nutrient stability and ensure better absorption, encouraging manufacturers to fortify even complex food matrices. This opens up new opportunities for premium and functional food segments, such as plant-based and clean-label products, thereby broadening the market potential across various consumer demographics.
- For instance, Ingredion Incorporated introduced its Ultra-Sperse® M technology, which allows micronutrients to be evenly dispersed in high-moisture food systems, and has been used in over 600 million units of fortified soups and sauces since its launch.
Expansion into Emerging Economies
Emerging markets in Asia, Africa, and Latin America offer untapped opportunities due to high malnutrition rates and growing middle-class populations. Governments in these regions are increasingly partnering with NGOs and private players to implement large-scale fortification programs. Rising disposable incomes and urbanization are also creating demand for fortified packaged foods, especially among younger consumers and working professionals. Market players can capitalize on these dynamics by investing in localized product development and targeted marketing strategies.
- For instance, Archer Daniels Midland (ADM) partnered with UNICEF and local governments in India to distribute fortified flour and edible oil, reaching over 20 million beneficiaries across rural and semi-urban areas as part of their regional nutrition initiative.
Key Challenges
Cost and Supply Chain Constraints
One of the major challenges in the food fortification ingredients market is the high cost associated with sourcing, processing, and maintaining ingredient quality. Fortification requires precise formulations, often involving expensive micronutrients and specialized technologies. These added costs can be a barrier for small and mid-sized food manufacturers, particularly in cost-sensitive markets. Additionally, supply chain disruptions and limited access to high-quality raw materials in developing regions further hinder consistent product availability.
Consumer Skepticism and Taste Alteration Concerns
Despite increasing awareness, some consumers remain skeptical about the safety and efficacy of fortified foods. Misconceptions about synthetic additives and fears of overconsumption can impact market penetration, especially in traditionally health-conscious segments. Moreover, certain fortification ingredients may alter the taste, color, or texture of foods, affecting consumer acceptance. Addressing these concerns requires transparent labeling, public education, and advances in formulation techniques to deliver seamless taste and health benefits.
Regulatory Compliance and Standardization Issues
The lack of uniform global standards and regulatory frameworks creates barriers for international trade and product standardization. Food manufacturers must navigate complex and varying regulations across countries, which adds to compliance costs and delays market entry. Furthermore, inconsistent testing and monitoring practices can affect product quality and credibility. Ensuring harmonized fortification guidelines and stronger regulatory support remains critical for maintaining consumer trust and enabling global market expansion.
Regional Analysis
North America
North America accounted for approximately 17.2% of the global food fortification ingredients market in 2024, with a value of USD 16.25 million, up from USD 9.93 million in 2018. The region is projected to reach USD 28.02 million by 2032, expanding at a CAGR of 7.0%. Growth is primarily driven by increasing health awareness, government-led nutrition programs, and the widespread availability of fortified products. The U.S. leads the regional market due to its advanced food processing industry and stringent nutritional labeling laws. Consumers' growing demand for functional and value-added foods continues to support steady market expansion.
Europe
Europe held a 21.5% share of the global market in 2024, with revenue rising from USD 12.33 million in 2018 to USD 20.29 million. It is expected to reach USD 35.26 million by 2032, registering a CAGR of 7.1% during the forecast period. Strong regulatory frameworks, coupled with a well-established food and beverage sector, support robust growth in the region. European consumers are increasingly inclined toward clean-label and health-oriented products, encouraging manufacturers to incorporate fortification ingredients. Countries such as Germany, the UK, and France are at the forefront, backed by favorable EU policies and rising functional food demand.
Asia Pacific
Asia Pacific dominated the global market in 2024 with a commanding 36.8% share, generating USD 34.78 million, up from USD 20.45 million in 2018. The region is projected to reach USD 63.13 million by 2032, growing at a leading CAGR of 7.7%. Rapid urbanization, a rising middle class, and widespread micronutrient deficiencies are propelling demand for fortified foods. Government-led nutritional programs, particularly in India and China, play a significant role in expanding market reach. In addition, increasing consumer awareness and the expansion of food retail infrastructure are accelerating the adoption of fortified food products across the region.
Latin America
Latin America captured approximately 12.7% of the global market in 2024, with revenues growing from USD 7.11 million in 2018 to USD 12.04 million, and expected to reach USD 21.71 million by 2032 at a CAGR of 7.6%. Countries like Brazil and Mexico are witnessing growing demand for nutrient-rich foods due to increased focus on public health and changing dietary habits. Government regulations promoting fortification of flour and milk have also contributed to growth. Urban consumers’ rising preference for functional foods, along with expanding food processing capabilities, is fueling demand for fortification ingredients in the region.
Middle East
The Middle East represented 5.4% of the global food fortification ingredients market in 2024, with a market value of USD 5.07 million, up from USD 3.06 million in 2018. It is forecast to reach USD 8.92 million by 2032, growing at a CAGR of 7.2%. Increasing lifestyle-related health issues, such as diabetes and obesity, are pushing demand for nutrient-enriched foods. Regional governments are increasingly supporting fortification programs, particularly for staple foods. The Gulf Cooperation Council (GCC) countries lead the regional market due to higher per capita income, health awareness, and growing investments in the food and beverage sector.
Africa
Africa accounted for approximately 6.3% of the global market in 2024, growing from USD 3.74 million in 2018 to USD 5.97 million, with an anticipated value of USD 9.93 million by 2032 at a CAGR of 6.5%, the slowest among all regions. Despite having a high prevalence of malnutrition, the market faces challenges due to underdeveloped infrastructure and limited consumer purchasing power. However, efforts by international organizations and governments to implement large-scale fortification programs are gradually improving market conditions. Countries like Nigeria and South Africa are seeing rising demand, driven by growing awareness and public-private nutrition initiatives.
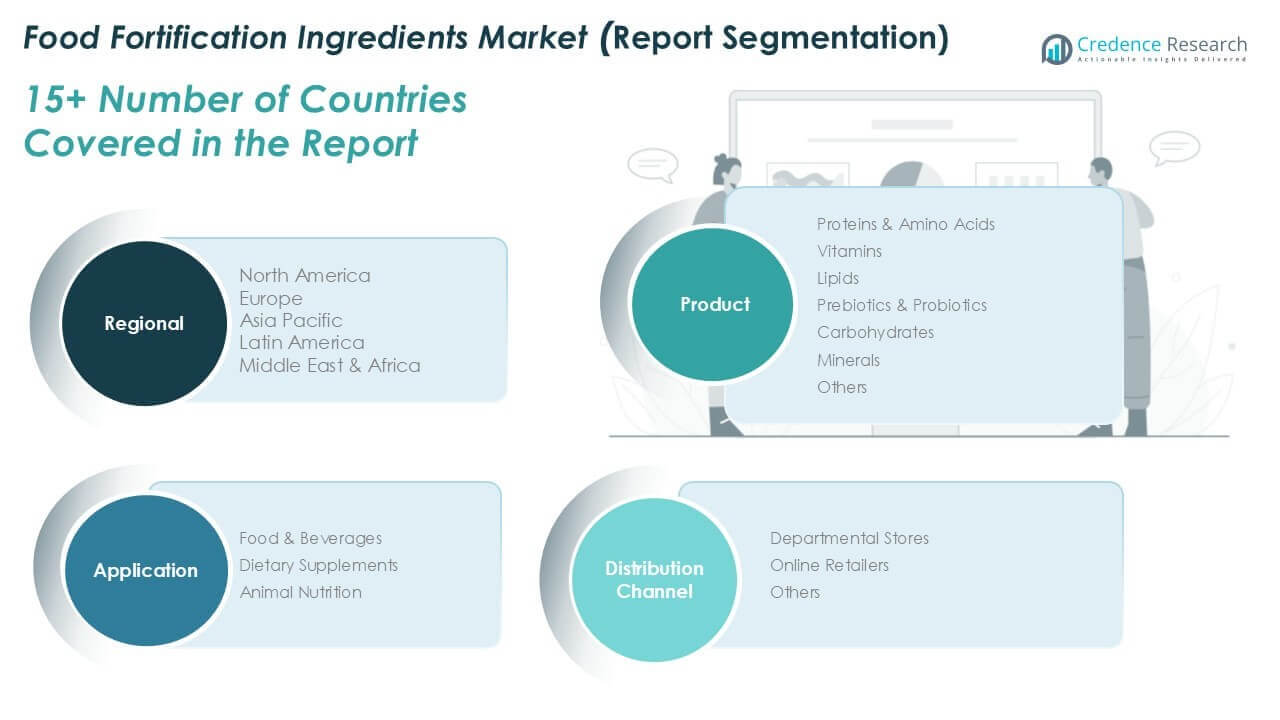
Market Segmentations:
By Product
- Proteins & Amino Acids
- Vitamins
- Lipids
- Prebiotics & Probiotics
- Carbohydrates
- Minerals
- Others
By Application
- Food & Beverages
- Dietary Supplements
- Animal Nutrition
By Distribution Channel
- Departmental Stores
- Online Retailers
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The food fortification ingredients market is moderately consolidated, with key players focusing on innovation, partnerships, and global expansion to strengthen their market positions. Companies such as Cargill Incorporated, Archer Daniels Midland Company, Kerry Group, DuPont, and BASF SE dominate the market with diverse product portfolios and extensive distribution networks. These firms invest heavily in R&D to develop advanced fortification solutions that enhance nutrient stability and bioavailability without compromising taste or texture. Strategic acquisitions and collaborations are common, allowing players to expand into emerging markets and align with regional regulatory standards. Additionally, companies like DSM Nutritional Products and Glanbia PLC are leveraging advancements in encapsulation and clean-label formulations to meet evolving consumer demands. With growing emphasis on health and wellness, competition is intensifying, prompting both global and regional players to focus on cost-efficiency, quality assurance, and customized solutions to capture a larger share of the expanding fortified food and beverage industry.
Key Player Analysis
- Cargill Incorporated
- Archer Daniels Midlands
- Kerry Group
- Dupont
- Ingredion Incorporated
- General Mills, Inc.
- The Archer Daniels Midland Company
- DSM Nutritional Products
- BASF SE
- Glanbia PLC
Recent Developments
- In March 2025, Cargill Incorporated introduced new functional blends for snacks, bakery, confectionery, dairy, and ice cream at AAHAR 2025, including a dent corn-based modified starch for sauces, a cost-effective pectin replacer for gummies and jellies, and bake-stable fillings. These innovations focus on improving sensory qualities, cost-effectiveness, and product performance for B2B clients in India.
- In February 2024, ADM (US) closed its acquisition of Fuerst Day Lawson (FDL), and its capabilities in the fortified ingredients market improved. With FDL's diverse skills in the development of custom flavours, energy blends, and fortification solutions, ADM was able to expand its options in that regard, especially in terms of natural taste and nutrition. This will help strengthen its international presence as well as new markets available throughout Europe, the U.S. and Asia and will further advance ADM's leadership in human and animal nutrition.
- In November 2022, Glanbia plc. (Ireland) developed FerriUp, a whey protein concentrate enhanced with the added benefits of lactoferrin and vitamin B12. This one squarely targeted the active woman. This innovation helped put Glanbia on more solid footing in the fortified ingredients market-iron and energy levels demand were considerable; the demographic in sports nutrition was largely underserved.
- In May 2022, dsm-firmenich (Switzerland) and the World Food Programme extended partnership to further boost global rice fortification and better nutrition for vulnerable populations. Through this collaboration, dsm-firmenich is able to bring their technical know-how and assets to support 35 million people per year and creates a stronger presence in fortified ingredients as DSM addresses nutritional gaps while supporting local food systems for the betterment of communities and DSM's drive in nutrition.
Market Concentration & Characteristics
The Food Fortification Ingredients Market demonstrates moderate to high market concentration, with several dominant players controlling a significant share of global revenue. Leading companies such as Cargill Incorporated, Archer Daniels Midland Company, Kerry Group, DuPont, BASF SE, and DSM Nutritional Products possess strong distribution networks, advanced technological capabilities, and diverse product portfolios. It is characterized by a growing demand for micronutrient-enriched foods across both developed and developing regions, driven by rising health awareness and regulatory support for nutritional interventions. The market reflects strong innovation dynamics, particularly in nutrient delivery systems like microencapsulation and bioavailability enhancement. Regional differences in regulatory standards and consumer preferences influence product development and positioning strategies. Asia Pacific holds the largest market share due to large-scale public health programs and expanding middle-class populations. Companies operating in this space focus on strategic partnerships and localized solutions to meet evolving nutritional needs. High entry barriers related to compliance, formulation expertise, and capital investment shape its competitive environment.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for fortified foods will continue to grow as consumers prioritize health and wellness in their daily diets.
- Government-mandated fortification programs are expected to expand across emerging and low-income economies.
- Technological advancements will enhance nutrient stability, taste, and bioavailability in fortified products.
- Functional and clean-label fortification ingredients will gain popularity among health-conscious consumers.
- Asia Pacific will remain the fastest-growing regional market due to rising urbanization and nutritional awareness.
- Market players will increasingly invest in R&D and innovation to meet evolving dietary needs.
- E-commerce and online retail will play a stronger role in distributing fortified food products globally.
- Collaborations between public health bodies and private companies will drive mass fortification initiatives.
- Regulatory harmonization across countries will support international trade and product standardization.
- Fortification of plant-based and alternative protein foods will create new growth opportunities.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Micronutrient Deficiencies
The global burden of micronutrient deficiencies, particularly in iron, iodine, vitamin A, and folic acid, is prompting governments and organizations to mandate and promote food fortification, significantly increasing demand for fortification ingredients.
Government Support and Regulatory Mandates
Mandatory and voluntary fortification policies, along with funding and guidelines from health authorities, are driving widespread adoption of fortified foods, especially in staple products like flour, milk, and salt.
Increasing Consumer Health Awareness
Consumers are more aware of the role of nutrition in disease prevention and wellness, leading to higher demand for fortified foods and beverages that offer functional health benefits, particularly in urban and developed markets.
Technological Advancements in Fortification Methods
Innovations in nutrient encapsulation, nano-delivery, and bioavailability enhancement are enabling manufacturers to add fortification ingredients without compromising taste or texture, expanding the range of fortified products.
Expansion into Emerging Economies
Rapid urbanization, rising disposable incomes, and large-scale government nutrition programs in Asia, Africa, and Latin America are creating new opportunities for market growth as fortified foods become more accessible and in demand.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Food Fortification Ingredients Market?
What factors are driving the growth of the Food Fortification Ingredients Market?
What are the key segments within the Food Fortification Ingredients Market?
What are some challenges faced by the Food Fortification Ingredients Market?
Who are the major players in the Food Fortification Ingredients Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Proteins & Amino Acids
- 1.2.2 Vitamins
- 1.2.3 Lipids
- 1.2.4 Prebiotics & Probiotics
- 1.2.5 Carbohydrates
- 1.2.6 Minerals
- 1.2.7 Others
- 1.3 By Application
- 1.3.1 Food & Beverages
- 1.3.2 Dietary Supplements
- 1.3.3 Animal Nutrition
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 94.4 Billion → 2032: USD 167.0 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Food Fortification Ingredients Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Food Fortification Ingredients Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Food Fortification Ingredients Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Food Fortification Ingredients Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Food Fortification Ingredients Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Food Fortification Ingredients Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Food Fortification Ingredients Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Food Fortification Ingredients Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 94.4 Billion → 2032: USD 167.0 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Food Fortification Ingredients Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Proteins & Amino Acids
- 12.3.7.2 Vitamins
- 12.3.7.3 Lipids
- 12.3.7.4 Prebiotics & Probiotics
- 12.3.7.5 Carbohydrates
- 12.3.7.6 Minerals
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Food & Beverages
- 12.4.7.2 Dietary Supplements
- 12.4.7.3 Animal Nutrition
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Food Fortification Ingredients End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Food Fortification Ingredients Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Food Fortification Ingredients Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Food Fortification Ingredients Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cargill Incorporated
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Archer Daniels Midland Company
- 18.4 Kerry Group
- 18.5 DuPont
- 18.6 BASF SE
- 18.7 DSM Nutritional Products
- 18.8 Glanbia PLC
- 18.9 Ingredion Incorporated
- 18.10 General Mills, Inc.
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

