
Market Overview
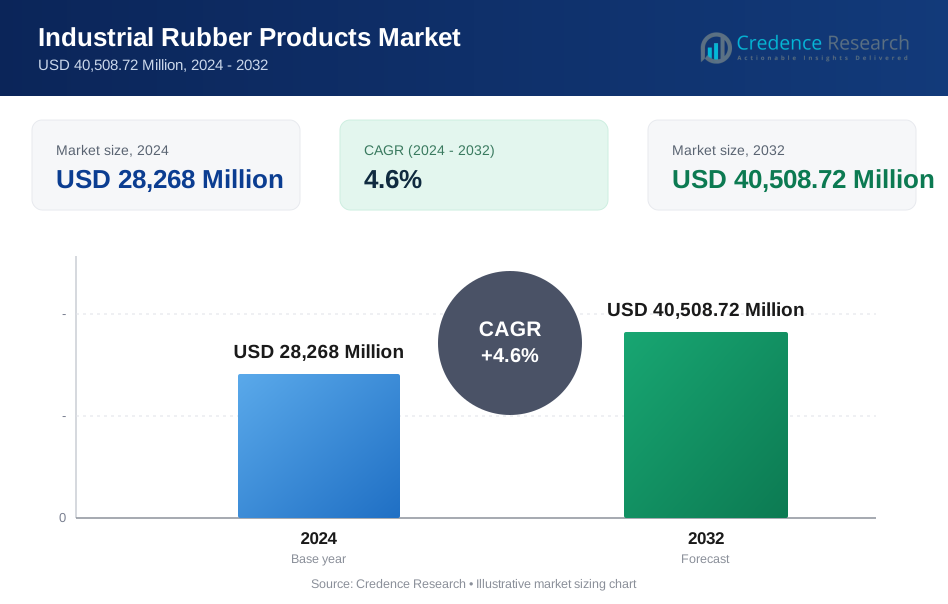
Industrial Rubber Products market size was valued at USD 28,268 Million in 2024 and is anticipated to reach USD 40,508.72 Million by 2032, at a CAGR of 4.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Industrial Rubber Products Market Size 2024 | USD 28,268 Million |
| Industrial Rubber Products Market, CAGR | 4.6% |
| Industrial Rubber Products Market Size 2032 | USD 40,508.72 Million |
Industrial Rubber Products market is shaped by leading manufacturers such as Bridgestone Corporation, Freudenberg SE, Semperit, Bando Chemical Industries, ALFAGOMMA SpA, Dayco Products LLC, American High Performance Seals, Bangkok Synthetics Co., Ltd., ABG Rubber & Plastics Ltd, and Amp Impex Private Limited, all of which play a crucial role in supplying high-performance rubber materials and components across global industries. Asia-Pacific emerged as the dominant region with 38.6% share in 2024, driven by its strong automotive production, expanding industrial base, and cost-efficient manufacturing capabilities. North America and Europe followed, supported by advanced industrial infrastructure and consistent demand for engineered rubber solutions in automotive, energy, and construction sectors.
Market Insights
- Industrial Rubber Products market was valued at USD 28,268 million in 2024 and is projected to reach USD 40,508.72 million by 2032, registering a 4.6% CAGR during the forecast period.
- Market growth is driven by rising demand from automotive, construction, and industrial manufacturing sectors, with Mechanical Rubber Goods leading the product segment at 48.2% share due to widespread applications in sealing, insulation, and vibration control.
- Key trends include the adoption of sustainable rubber materials, recyclable compounds, and advanced elastomers, alongside increasing integration of digital manufacturing and predictive testing technologies.
- Major players such as Bridgestone Corporation, Freudenberg SE, Semperit, Bando Chemical Industries, and ALFAGOMMA SpA strengthen the market through product innovation, capacity expansion, and high-performance synthetic rubber formulations.
- Regionally, Asia-Pacific dominates with 38.6% share, followed by North America at 27.4% and Europe at 24.1%, supported by strong automotive output, industrial growth, and increasing adoption of engineered rubber components.
Market Segmentation Analysis
By Product
Mechanical Rubber Goods dominated the Industrial Rubber Products market in 2024 with an 48.2% share, driven by their extensive use in sealing, vibration control, insulation, and protective components across automotive, machinery, and industrial equipment. Their durability, flexibility, and high resistance to heat, chemicals, and abrasion make them indispensable in demanding operational environments. Rubber Hose & Belting followed, supported by rising applications in material handling and fluid transfer systems, particularly in construction and mining. The Others category captured a smaller share, driven by niche applications in consumer goods and specialized manufacturing.
- For instance, Continental AG reported that its vibration control and sealing systems are widely adopted in automotive powertrain and chassis applications to reduce noise, vibration, and harshness, supporting OEM demand for durable mechanical rubber components.
By Type
Natural Rubber accounted for the largest share at 34.6% in 2024, owing to its superior tensile strength, elasticity, and fatigue resistance, which make it ideal for tires, vibration mounts, and pressure-sensitive applications. Styrene Butadiene Rubber (SBR) also maintained strong demand due to its cost efficiency and wide usage in tire manufacturing. Meanwhile, Polybutadiene and Ethylene-Propylene rubbers gained traction in high-performance applications requiring enhanced durability and weather resistance. Nitrile Butadiene Rubber (NBR) continued to expand in oil-resistant components used across automotive, energy, and industrial machinery sectors.
- For instance, Bridgestone reported significant use of natural rubber in premium tire lines due to its high tensile strength and exceptional heat buildup resistance, critical for heavy-duty performance and longevity.
By End User
The Automotive sector dominated the Industrial Rubber Products market with 41.3% share in 2024, driven by extensive use of rubber components in tires, seals, gaskets, belts, hoses, and vibration-damping systems. Growth in electric vehicles further amplified demand for high-performance rubber materials with enhanced heat and chemical resistance. Construction & Infrastructure followed, supported by rising investments in building materials, insulation systems, and industrial equipment. The Energy and Aerospace segments demonstrated steady growth driven by demand for specialized rubber products capable of withstanding extreme temperatures, high pressure, and corrosive environments, while Others contributed through diversified industrial applications.
Key Growth Drivers
Rising Demand from Automotive and Transportation Industries
The automotive sector remains a primary growth engine for the Industrial Rubber Products market, driven by increasing production of passenger vehicles, commercial fleets, and electric vehicles. Rubber components are essential in tires, hoses, gaskets, belts, mounts, and sealing systems, all of which require durability, heat resistance, and vibration absorption. The shift toward EVs increases the need for advanced rubber formulations capable of handling higher thermal loads, electrical insulation, and reduced noise levels. Additionally, expanding logistics and transportation activities worldwide boost demand for heavy-duty tires, conveyor belts, and industrial rubber goods. As global vehicle parc continues to grow and OEMs adopt lightweight, high-performance materials, consumption of engineered rubber products is expected to rise substantially.
- For instance, Michelin expanded its portfolio of EV-optimized tires featuring enhanced rubber compounds designed to handle higher torque, reduced rolling resistance, and improved wear performance for battery-powered vehicles.
Expansion of Construction, Infrastructure, and Industrial Manufacturing Activities
Rapid urbanization, infrastructure modernization, and industrial expansion significantly contribute to market growth by creating strong demand for rubber hoses, belts, seals, flooring, insulation materials, and protective components. Construction sectors rely heavily on rubber-based products for machinery, material handling systems, waterproofing applications, vibration isolation, and structural protection. Government-backed investments in transportation networks, smart cities, energy systems, and industrial automation further accelerate product adoption. Growing manufacturing output particularly in Asia-Pacific also increases the need for durable rubber materials used in equipment maintenance, process engineering, and safety systems. As industries prioritize efficiency and operational uptime, high-quality industrial rubber goods strengthen overall market momentum.
- For instance, Larsen & Toubro (L&T) incorporated advanced rubber waterproofing membranes and vibration-damping materials across major metro rail and infrastructure projects, supporting long-term durability and structural performance.
Technological Advancements and Innovation in High-Performance Rubber Materials
Continuous improvements in synthetic rubber formulations, compounding technologies, and material science enable manufacturers to deliver products with superior strength, heat stability, abrasion resistance, and chemical durability. Innovations such as advanced EPDM, nitrile, and hydrogenated nitrile rubbers support applications in harsh environments across oil & gas, aerospace, chemical processing, and heavy engineering. The integration of nanomaterials, bio-based additives, and recyclable rubber compounds aligns with sustainability goals while enhancing performance. Digitalization in production through predictive maintenance, automated mixing, and precision molding further improves efficiency and consistency. These advancements allow industrial rubber products to meet evolving industry standards, extend service life, and reduce operational costs, positioning innovation as a major driver.
Key Trends & Opportunities
Shift Toward Sustainable, Recyclable, and Bio-Based Rubber Materials
Sustainability is emerging as a transformative trend, creating strong opportunities for eco-friendly rubber formulations that reduce environmental impact. Manufacturers increasingly adopt recycled rubber, devulcanized materials, and bio-based feedstocks such as alternatives derived from guayule and dandelion. Growing regulatory pressure to minimize carbon emissions and promote circular economy practices accelerates investment in green rubber technologies. Companies are developing low-VOC processes and energy-efficient production systems to meet global sustainability targets. Automotive, construction, and industrial sectors are actively seeking environmentally compliant materials, opening new avenues for innovative rubber solutions with lower lifecycle costs. As corporate ESG mandates expand, demand for sustainable industrial rubber products is expected to rise significantly.
- For instance, Bridgestone advanced commercial-scale development of guayule-based natural rubber, confirming successful harvest and rubber extraction trials as part of its long-term sustainable materials strategy.
Increasing Adoption of Smart Manufacturing and Advanced Testing Technologies
Automation, IoT-enabled testing, and digital monitoring tools are transforming production and quality control processes in the industrial rubber sector. Smart manufacturing systems enhance precision in mixing, curing, and molding, reducing defects and improving product reliability. Advanced testing technologies including real-time stress analysis, automated dimensional inspections, and predictive failure modeling support the development of high-performance rubber components tailored for demanding environments. These technologies also minimize downtime, improve operational efficiency, and lower production costs. High-reliability industries like aerospace, automotive, and energy are driving adoption of these advanced capabilities, creating strong opportunities for technologically differentiated industrial rubber solutions.
- For instance, Bi-State Rubber employs IoT technologies for real-time equipment monitoring and predictive maintenance, alongside digital twin technology that creates virtual replicas of physical assets to optimize performance without halting production.
Key Challenges
Volatility in Raw Material Prices and Supply Chain Disruptions
Fluctuations in prices of natural and synthetic rubber pose a major challenge, directly affecting production costs and pricing strategies. Natural rubber supply is highly dependent on climate conditions, plantation health, and geopolitical factors, while synthetic rubber relies on petrochemical feedstocks vulnerable to oil price instability. Global supply chain disruptions driven by geopolitical tensions, logistics delays, and material shortages further complicate procurement planning. These uncertainties force manufacturers to adopt flexible sourcing strategies, maintain larger inventories, and balance cost pressures with quality requirements. Ensuring consistent availability of high-quality raw materials remains crucial for maintaining production stability.
Stringent Regulatory Compliance and Quality Standards
The Industrial Rubber Products market faces increasing regulatory scrutiny regarding environmental impact, chemical content, durability, and safety compliance. Regulations such as REACH, EPA mandates, and industry-specific certifications require continuous updates to formulations and production processes. Manufacturers must eliminate hazardous substances, enhance thermal and chemical resistance, and meet strict testing criteria to maintain market access. Non-compliance can lead to product recalls, financial penalties, and reputational damage. Furthermore, sectors like automotive, aerospace, and energy impose stringent performance standards, requiring substantial investment in R&D, quality assurance, and testing infrastructure. Navigating this evolving regulatory environment remains a significant operational challenge for the industry.
Regional Analysis
North America
North America held 27.4% share of the Industrial Rubber Products market in 2024, supported by strong demand across automotive, construction, aerospace, and energy sectors. The U.S. remains the primary contributor due to its large automotive aftermarket, advanced manufacturing base, and continuous investments in oil & gas infrastructure. The region’s emphasis on high-performance materials, stringent quality standards, and modernization of industrial equipment drives adoption of engineered rubber goods. Growth in EV production and renewable energy facilities further boosts demand for heat-resistant, durable, and specialty rubber components across mission-critical applications.
Europe
Europe accounted for 24.1% share in 2024, driven by a robust automotive industry, expanding industrial automation, and strict regulatory requirements promoting high-quality and sustainable rubber materials. Germany, France, and Italy remain central markets due to their strong manufacturing ecosystems and high adoption of advanced sealing, insulation, and vibration-control products. The region’s focus on decarbonization and eco-compliant materials accelerates investment in recyclable and bio-based rubber solutions. Additionally, the aerospace and energy sectors contribute to steady demand for high-temperature-resistant and precision-engineered rubber components.
Asia-Pacific
Asia-Pacific dominated the Industrial Rubber Products market with 38.6% share in 2024, driven by rapid industrialization, expanding automotive production, and large-scale infrastructure development. China, India, Japan, and South Korea lead consumption due to their strong manufacturing bases and high investment in machinery, transportation, and construction sectors. Growing demand for industrial hoses, belts, seals, and tire-related rubber products strengthens market growth. The region also benefits from abundant raw material availability and cost-effective production capabilities. Rising adoption of EVs, renewable energy systems, and industrial automation further accelerates demand for advanced rubber materials.
Latin America
Latin America captured 5.6% share in 2024, supported by gradual economic recovery, expanding mining activities, and increasing investments in construction and industrial machinery. Brazil and Mexico remain key markets due to their sizable automotive and manufacturing industries. Demand for rubber hoses, belting systems, and sealing components grows as industrial facilities upgrade equipment to improve efficiency and safety. The region also experiences rising consumption of durable rubber products in agriculture, energy, and transportation sectors. Despite moderate growth, improving trade policies and industrialization trends are expected to strengthen market prospects.
Middle East & Africa
The Middle East & Africa region held 4.3% share in 2024, driven by strong demand from oil & gas, construction, and mining industries. Countries such as Saudi Arabia, UAE, and South Africa increasingly adopt high-performance rubber hoses, seals, and belting systems required for harsh operating environments. Large infrastructure development projects, energy diversification initiatives, and industrial expansion contribute to steady growth. The need for heat-resistant, corrosion-resistant, and pressure-tolerant rubber products remains high across petrochemical and heavy engineering sectors. Although the market is still emerging, rising industrial investments are expected to enhance long-term growth potential.
Market Segmentations
By Product
- Mechanical Rubber Goods
- Rubber Hose & Belting
- Others
By Type
- Natural
- Styrene Butadiene
- Polybutadiene
- Ethylene-Propylene
- Nitrile Butadiene
By End User
- Automotive
- Construction & Infrastructure
- Energy
- Aerospace
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Industrial Rubber Products market features a diverse and well-established competitive landscape, driven by global manufacturers focused on product innovation, material advancements, and expansion into high-growth industrial sectors. Key players such as Bridgestone Corporation, Freudenberg SE, Semperit, Bando Chemical Industries, ALFAGOMMA SpA, Dayco Products LLC, American High Performance Seals, Bangkok Synthetics Co., Ltd., ABG Rubber & Plastics Ltd, and Amp Impex Private Limited actively strengthen their market positions through strategic partnerships, capacity expansions, and development of high-performance synthetic rubber materials. Companies increasingly invest in enhanced formulations such as EPDM, NBR, and advanced elastomers to meet rising demand from automotive, construction, energy, and aerospace applications. Sustainability initiatives, including recyclable compounds and bio-based rubber alternatives, further shape competitive strategies. Moreover, many players adopt digital manufacturing, automated testing, and predictive quality systems to improve operational efficiency and deliver precision-engineered products, supporting long-term competitiveness in a rapidly evolving industrial environment.
Key Player Analysis
- ALFAGOMMA SpA
- Semperit
- Amp Impex Private Limited
- ABG Rubber & Plastics Ltd
- Freudenberg SE
- Dayco Products LLC
- Bando Chemical Industries, Ltd.
- American High Performance Seals, Inc.
- Bangkok Synthetics Co., Ltd.
- Bridgestone Corporation
Recent Developments
- In September 2025, LANXESS announced expansion of its US rubber-production capacity at its Bushy Park facility in South Carolina, with new rubber processing promoters and expected additional production lines by November 2025.
- In August 2025, American Rheinmetall expanded its rubber-product portfolio after acquiring Loc Performance adding custom compounding and high-performance rubber solutions for industrial, construction, agriculture and defence applications.
- In May 2025, Yokohama Rubber acquired a former tyre manufacturing facility in Romania for USD 35 million, aiming to expand its European off-highway tyre and industrial rubber product operations
Report Coverage
The research report offers an in-depth analysis based on Product, Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth driven by rising demand across automotive, construction, and manufacturing industries.
- Adoption of advanced synthetic rubber materials will expand to support high-performance industrial applications.
- Sustainability initiatives will accelerate the shift toward recyclable, bio-based, and low-emission rubber products.
- Digital manufacturing technologies will enhance production efficiency and product consistency.
- EV expansion will increase demand for heat-resistant, lightweight, and durable rubber components.
- Infrastructure modernization projects will fuel consumption of hoses, belts, seals, and vibration-control materials.
- Global players will invest more in R&D to develop specialized elastomers for harsh operating environments.
- Supply chain diversification will become a priority to mitigate raw material price volatility.
- Regulatory pressures will drive manufacturers to adopt cleaner formulations and comply with stricter performance standards.
- Asia-Pacific will continue to lead growth due to industrial expansion and strong manufacturing capabilities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Industrial Rubber Products market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Industrial Rubber Products market projected to grow between 2024 and 2032?
Which Industrial Rubber Products market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Industrial Rubber Products market?
Who are the leading companies in the Industrial Rubber Products market?
Which region commanded the largest share of the Industrial Rubber Products market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Industrial Rubber Products Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Industrial Rubber Products Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 28,268 Million → 2032: USD 40,508.72 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Industrial Rubber Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Industrial Rubber Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Industrial Rubber Products Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Industrial Rubber Products Market Drivers
- 3.3 Industrial Rubber Products Market Restraints & Challenges
- 3.4 Industrial Rubber Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Industrial Rubber Products Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Industrial Rubber Products Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Industrial Rubber Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Industrial Rubber Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Industrial Rubber Products Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Industrial Rubber Products market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Industrial Rubber Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Industrial Rubber Products Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Industrial Rubber Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Industrial Rubber Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Industrial Rubber Products Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Industrial Rubber Products Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Industrial Rubber Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Industrial Rubber Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Industrial Rubber Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Industrial Rubber Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Industrial Rubber Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Industrial Rubber Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Industrial Rubber Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
