
Market Overview:
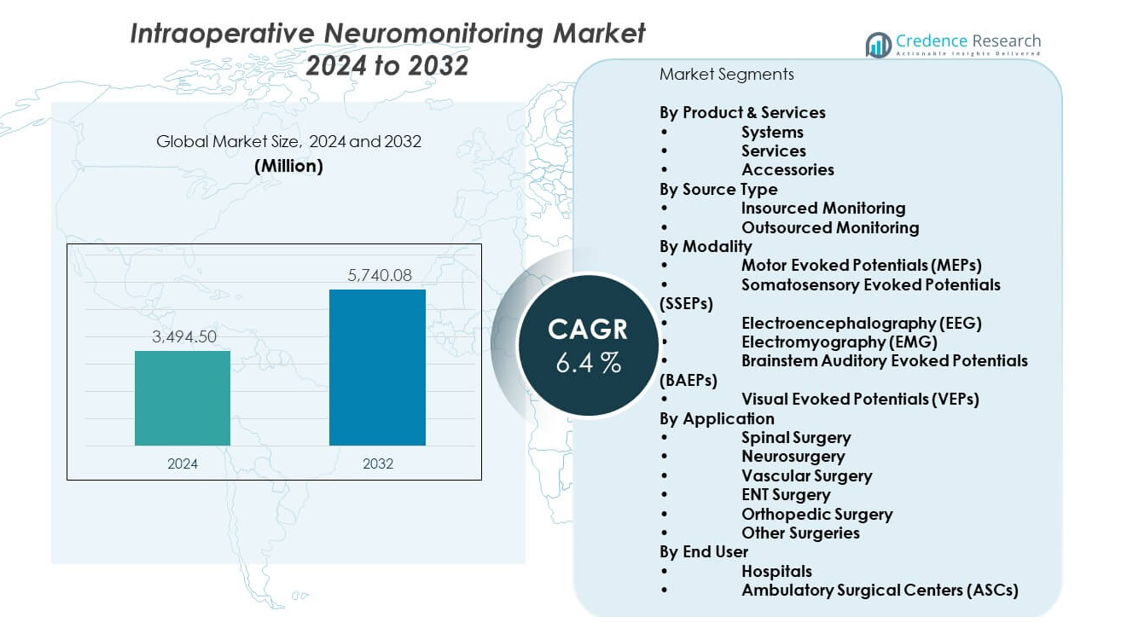
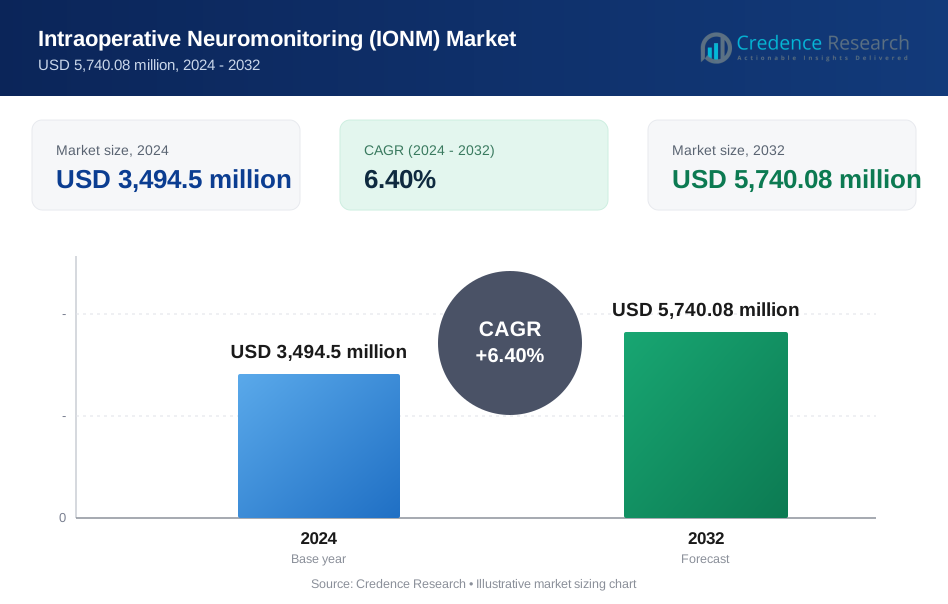
The Intraoperative neuromonitoring market is projected to grow from USD 3,494.5 million in 2024 to an estimated USD 5,740.08 million by 2032, with a compound annual growth rate (CAGR) of 6.4% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Intraoperative Neuromonitoring Market Size 2024 | USD 3,494.5 million |
| Intraoperative Neuromonitoring Market, CAGR | 6.4% |
| Intraoperative Neuromonitoring Market Size 2032 | USD 5,740.08 million |
Strong demand comes from the need to prevent postoperative complications during complex procedures. Healthcare providers rely on neuromonitoring to protect nerve pathways in high-risk surgeries, which boosts system adoption. Awareness grows among surgeons who seek better accuracy through EMG, EEG, and evoked potential techniques. Expanding use in ambulatory surgical centers supports market momentum. Rising focus on patient safety strengthens uptake across developed and developing healthcare systems.
North America leads the market due to high surgical volumes, strong reimbursement, and early adoption of monitoring technologies. Europe follows with robust demand from advanced neurosurgical and orthopedic centers. Asia Pacific emerges as the fastest-growing region as countries expand specialty care and invest in modern operating rooms. China, India, and South Korea record rising adoption because healthcare providers upgrade surgical infrastructure. Latin America and the Middle East show steady growth supported by improving clinical capabilities and rising specialty surgery rates.
Market Insights:
- The Intraoperative neuromonitoring market is valued at USD 3,494.5 million in 2024 and is expected to reach USD 5,740.08 million by 2032, growing at a 4% CAGR due to rising complex surgical procedures and stronger adoption of multimodal monitoring.
- North America holds 38–40%, Europe holds 28–30%, and Asia-Pacific holds 22–25%, driven by high surgical volumes, strong hospital infrastructure, and wider adoption of advanced monitoring technologies.
- Asia-Pacific is the fastest-growing region, supported by rapid upgrades in surgical facilities, rising patient loads, and broader investment in modern operating rooms across China, India, Japan, and South Korea.
- By product, Systems account for nearly 55% of the market due to high demand for multimodal monitoring platforms, while Services hold about 35% as outsourced and remote monitoring gain wider acceptance.
- By application, Spinal Surgery contributes about 40% of total procedures, while Neurosurgery holds nearly 28%, reflecting the need for accurate nerve protection in high-risk surgical interventions.
Market Drivers:
Growing Use of Monitoring in Complex Surgical Procedures
The Intraoperative neuromonitoring market expands due to rising complex surgeries. Surgeons rely on real-time feedback for safer outcomes. Demand grows in spine, neuro, and ENT procedures. Hospitals upgrade systems to reduce nerve injury risks. Monitoring teams support surgical accuracy through multimodal tools. Awareness grows among specialists across regions. Training programs help improve clinical adoption. It drives strong preference for advanced monitoring platforms.
- For instance, Medtronic’s NIM-Eclipse system can support up to 32 channels for electromyography (EMG) monitoring and manage numerous modalities, delivering high-resolution signals used in major spine and ENT procedures. The system can be used in either a Surgeon Directed (SD) or Neurophysiologist Supported (NS) configuration, offering extensive support for various surgeries including minimally invasive spinal procedures and head and neck cases.
Rising Focus on Patient Safety and Surgical Precision
Patient safety concerns encourage wider neuromonitoring use. Hospitals adopt systems that reduce postoperative deficits. Surgeons value clear signals during high-risk procedures. Monitoring supports confident decision-making in difficult cases. Providers use structured protocols for better protection. Health systems promote standardized monitoring guidelines. Demand increases from rising surgical expectations. It strengthens adoption in both large and mid-size facilities.
- For instance, NuVasive’s Pulse platform provides real-time EMG feedback with less than 2-millisecond latency, helping surgeons track neural responses during complex spine surgery.
Higher Surgical Volumes Driven by Aging Populations
Growing elderly populations push surgical numbers higher. Degenerative disorders lead many patients to surgical care. Surgeons adopt monitoring to avoid nerve complications. Hospitals invest in modern systems for repeat cases. Providers track outcomes through improved digital tools. Demand rises across orthopedic and neurological units. Insurance groups support safer surgical practices. It encourages consistent neuromonitoring use across care levels.
Technology Improvements Boost Clinical Confidence
Device makers advance signal quality and software tools. New systems offer stable baseline readings. Surgeons rely on accurate alarms during critical phases. Automated analysis reduces manual interpretation time. Hospitals use portable units for multiple rooms. Improved electrodes support cleaner signal capture. Faster setup increases procedure efficiency. It leads to higher adoption across surgical centers.
Market Trends:
Rising Integration of AI-Enhanced Monitoring Platforms
AI tools support faster interpretation in many surgeries. Systems detect subtle signal changes quickly. Automated alerts improve early response during procedures. Surgeons gain clarity in high-stress moments. Hospitals adopt AI modules to support teams. Improved analysis offers stronger predictive insight. Trend grows across advanced surgical units. The Intraoperative neuromonitoring market gains stable traction from these upgrades.
Shift Toward Remote Neuromonitoring Services
Many hospitals choose remote support models. Specialists monitor signals from central hubs. Smaller centers gain access to skilled teams. Surgeons receive expert guidance during key steps. Remote teams handle multiple cases daily. Providers lower staffing gaps through remote links. Adoption grows in ambulatory facilities. It supports wider service reach across regions.
- For instance, SpecialtyCare delivers remote IONM coverage for over 110,000 to 115,000 surgeries each year, giving hospitals access to certified technologists across regions. The company is the largest provider of IONM services in the U.S. and has monitored over a million cases in total since its founding.
Growing Demand for Multimodal Monitoring Setups
Clinicians prefer setups with multiple signal types. Combined EMG, EEG, and EP tools guide decisions. Surgeons value integrated dashboards. Hospitals choose units that support varied surgeries. Multimodal systems reduce device clutter. Training becomes easier with unified design. Providers gain consistent readings in long cases. It builds confidence in modern neuromonitoring solutions.
Expansion of Monitoring in Ambulatory Surgical Centers
Ambulatory centers adopt neuromonitoring for safety. Rising outpatient surgeries push demand. Centers focus on protecting patients with limited recovery time. Monitoring reduces risks in delicate procedures. Portable systems support these fast environments. Staff rely on simple workflows and fast setup. Adoption spreads across emerging care clusters. It strengthens demand for compact neuromonitoring systems.
Market Challenges Analysis:
High Operational Costs and Skilled Workforce Limitations
The Intraoperative neuromonitoring market faces cost pressures. Hospitals manage high expenses for equipment and staff. Skilled technologists remain limited in many regions. Training demands slow adoption in smaller centers. Providers struggle with inconsistent staffing levels. System maintenance adds financial strain yearly. Budget limits affect procurement cycles. It creates adoption barriers in developing markets.
Variability in Signal Interpretation and Regulatory Constraints
Signal interpretation varies between teams. Inexperienced staff face difficulty with complex readings. Surgeons need consistent data flow during procedures. Regulatory demands differ across countries. Many hospitals face long approval processes. Quality rules increase procurement time. Small facilities find compliance tasks difficult. It slows expansion in regulated healthcare segments.
Market Opportunities:
Expansion of Monitoring Use in Emerging Healthcare Systems
Growth rises in regions building surgical capacity. Hospitals upgrade operating rooms for advanced care. Providers adopt monitoring to match global standards. Demand grows in spine and neuro specialties. Training programs expand regional workforce size. Policymakers support safer surgical practices overall. It creates strong penetration potential across emerging markets.
Adoption of Portable and Wireless Monitoring Technologies
New portable devices support flexible room use. Wireless systems reduce setup constraints. Surgeons gain cleaner workspaces and better mobility. Hospitals prefer systems with low installation demands. Compact units help centers handle rising cases. Device makers design user-friendly interfaces for teams. It opens strong innovation opportunities across product lines.
Market Segmentation Analysis:
By Product & Services
The Intraoperative neuromonitoring market shows strong demand across systems, services, and accessories. Systems hold steady growth because hospitals adopt advanced platforms for multimodal monitoring. Services gain wider use due to rising outsourcing among facilities that need skilled technologists. Accessories such as electrodes and sensors support recurring demand and create consistent revenue cycles. Hospitals prefer integrated setups that combine hardware and service support. Service providers expand their presence across high-volume surgical centers. It strengthens market penetration across diverse care settings.
- For instance, the Nihon Kohden Neuromaster system offers up to 32 channels for acquisition, with the capacity to use up to four breakout boxes for a total of 64 inputs for broad neurophysiological monitoring in surgical settings. The specific number of channels can be configured as either 16 or 32 depending on the amplifier unit selected.
By Source Type
Insourced monitoring remains important in large hospitals with in-house teams. Skilled staff manage signals directly during complex procedures. Outsourced monitoring grows faster because many facilities rely on remote specialists for accurate interpretation. Outsourcing reduces staffing gaps in smaller and mid-sized centers. Providers choose external teams for predictable quality during high-risk surgeries. Remote coverage supports flexible scheduling. It widens access across regions with limited neuromonitoring expertise.
- For instance, the Mayo Clinic Department of Neurosurgery performs more than 9,300 complex surgical procedures each year. Many of these intricate surgeries, especially those involving the spine and brainstem, necessitate intraoperative neuromonitoring (IONM) to help minimize the risk of nerve damage. The procedures are supported by a team of trained professionals, and the hospital system uses advanced technology for this purpose.
By Modality
Motor evoked potentials and somatosensory evoked potentials lead usage in spine and neuro procedures. EEG and EMG support detailed nerve and brain function tracking. BAEPs and VEPs remain vital for delicate cranial surgeries. Surgeons choose multimodal setups to improve precision. Hospitals prefer platforms that handle varied modalities in one system. Providers integrate signals through unified dashboards. It improves decision-making during long procedures.
By Application and End User
Spinal and neurosurgery create the highest procedure volume. Vascular, ENT, and orthopedic surgeries follow with rising adoption. Hospitals remain the primary users because they handle complex surgeries. ASCs increase use for outpatient spine and orthopedic procedures. Providers invest in portable units for flexible room usage. Demand grows across centers focused on safer surgical outcomes. It supports strong adoption across both large and emerging care environments.
Segmentation:
By Product & Services
- Systems
- Services
- Accessories
By Source Type
- Insourced Monitoring
- Outsourced Monitoring
By Modality
- Motor Evoked Potentials (MEPs)
- Somatosensory Evoked Potentials (SSEPs)
- Electroencephalography (EEG)
- Electromyography (EMG)
- Brainstem Auditory Evoked Potentials (BAEPs)
- Visual Evoked Potentials (VEPs)
By Application
- Spinal Surgery
- Neurosurgery
- Vascular Surgery
- ENT Surgery
- Orthopedic Surgery
- Other Surgeries
By End User
- Hospitals
- Ambulatory Surgical Centers (ASCs)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The Intraoperative neuromonitoring market records its highest share in North America with nearly 38–40%. Hospitals in the United States lead adoption due to high surgical volumes and strong access to skilled technologists. Providers invest in advanced systems that support complex spine and neuro procedures. Canada and Mexico expand use as surgical safety programs gain importance. Reimbursement support in the United States strengthens adoption across large hospital networks. Training availability improves clinician confidence. It keeps North America in a dominant position across global demand.
Europe
Europe holds an estimated 28–30% share driven by structured surgical protocols and early technology adoption. Germany, the UK, and France lead usage due to robust neurosurgical and orthopedic care infrastructure. Hospitals in Italy and Spain adopt monitoring systems to support higher procedure accuracy. Providers expand multimodal monitoring in high-risk units across major cities. Demand grows for standardized services that support nerve protection in complex procedures. Cross-border clinical programs encourage monitoring use across specialized centers. It positions Europe as a steady growth contributor.
Asia-Pacific
Asia-Pacific accounts for around 22–25% and remains the fastest-growing regional segment. China, Japan, and South Korea lead adoption with rapid upgrades in surgical infrastructure. India and Australia expand clinical use due to rising complex procedures in private and public hospitals. Healthcare systems invest in modern operating rooms to improve surgical safety. Demand rises for outsourced monitoring services where local technologists remain limited. Providers adopt portable systems to support expanding surgical departments. It drives a strong upward trajectory across emerging Asia-Pacific markets.
Key Player Analysis:
- Medtronic plc
- Natus Medical Incorporated
- NuVasive, Inc.
- Accurate Monitoring LLC
- SpecialtyCare
- Nihon Kohden Corporation
- Neuromonitoring Technologies
- inomed Medizintechnik GmbH
- Neurosoft
- Ambu A/S
- Brainlab AG (Dr. Langer Medical GmbH)
- Computational Diagnostics, Inc.
- IntraNerve, LLC
- Cadwell Industries
- GE HealthCare
Competitive Analysis:
The Intraoperative neuromonitoring market remains competitive with strong participation from device manufacturers, service providers, and software solution companies. Global leaders focus on advanced multimodal platforms that support complex neuro, spine, and vascular surgeries. Service-focused firms expand remote and outsourced monitoring coverage to meet rising demand across hospitals and ASCs. Companies invest in training programs to improve workforce capability and support consistent signal interpretation. Product developers focus on improving signal clarity, automation, and integration with surgical navigation tools. Strategic partnerships help firms expand clinical reach in high-volume surgical centers. It strengthens competitive positioning across established and emerging regions by aligning technology upgrades with rising surgical safety requirements.
Recent Developments:
- In June 2025, inomed Medizintechnik GmbH received FDA 510(k) clearance (K242852) for ALM Tube, EMG endotracheal tubes used for recording EMG activity of the laryngeal musculature while providing an open airway for patient ventilation when connected to an appropriate neuromonitoring device. As of 2024, inomed continues to develop and manufacture medical technology products across three business areas-Intraoperative Neuromonitoring, Functional Neurosurgery, and Pain Treatment-with devices used in over 5,000 hospitals in 100 countries worldwide.
- In February 2025, Medtronic received U.S. Food and Drug Administration (FDA) approval for its BrainSense™ Adaptive Deep Brain Stimulation (aDBS) system, marking the world's first adaptive deep brain stimulation technology for Parkinson's disease patients. In this groundbreaking development, BrainSense™ Adaptive DBS personalizes therapy based on a patient's brain activity in real time, both in clinical settings and in daily life, with the approval also including the BrainSense electrode identifier that helps reduce time spent by patients in clinic to program their DBS settings by 85% compared to traditional electrode selection. In October 2025, Medtronic's BrainSense™ Adaptive DBS technology was named one of TIME Magazine's Best Inventions of 2025, recognizing it as one of the year's most important medical innovations and representing the largest commercial launch of brain-computer interface (BCI) technology ever, with more than 40,000 DBS patients worldwide receiving Medtronic Percept devices.
Report Coverage:
The research report offers an in-depth analysis based on By Product & Services and By Modality. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising surgical volumes will push higher adoption across spine and neuro procedures.
- Growth in outsourced monitoring services will improve access for mid-size hospitals.
- AI-based signal interpretation tools will support faster intraoperative decisions.
- Portable multimodal systems will gain traction in ASCs and emerging care units.
- Workforce training programs will strengthen clinical reliability across regions.
- Hospitals will integrate neuromonitoring with navigation and imaging platforms.
- Demand for single-use accessories will grow due to infection-control preferences.
- Emerging markets will upgrade operating rooms to support advanced monitoring.
- Remote monitoring networks will expand coverage across high-volume centers.
- Technology partnerships will help companies enhance signal quality and workflow automation
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Use of Monitoring in Complex Surgical Procedures
The increasing number of complex spine, neuro, and ENT surgeries drives demand for intraoperative neuromonitoring, as surgeons rely on real-time feedback to reduce nerve injury risks and improve surgical outcomes.
Rising Focus on Patient Safety and Surgical Precision
Hospitals and surgeons are prioritizing patient safety by adopting neuromonitoring systems that help prevent postoperative neurological deficits, supporting confident decision-making during high-risk procedures.
Higher Surgical Volumes Driven by Aging Populations
Aging populations are leading to more degenerative disorders and higher surgical volumes, particularly in orthopedic and neurological specialties, which in turn increases the need for neuromonitoring to avoid nerve complications.
Technology Improvements Boost Clinical Confidence
Advancements in signal quality, automation, and multimodal monitoring platforms are making intraoperative neuromonitoring more reliable and easier to use, encouraging broader adoption across hospitals and surgical centers.
Expansion of Monitoring in Ambulatory Surgical Centers
The shift toward outpatient and ambulatory surgeries is fueling demand for portable and easy-to-use neuromonitoring systems, as these centers seek to maintain high safety standards in fast-paced environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Intraoperative neuromonitoring market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Intraoperative neuromonitoring market projected to grow between 2024 and 2032?
Which segment holds a very small application for intraoperative neuromonitoring (IONM)s in the world?
Which segment is expected to post the highest CAGR during the forecast period?
Who are the major players in the global intraoperative neuromonitoring (IONM) market?
What are the major market drivers of the intraoperative neuromonitoring (IONM) industry?
What are the major market restraints of the intraoperative neuromonitoring (IONM) industry?
What are the major market opportunities of the intraoperative neuromonitoring (IONM) industry?
Who are the leading companies in the Intraoperative neuromonitoring market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Ambulatory Surgical Centers (ASCs)
- 1.3 By Modality
- 1.3.1 Motor Evoked Potentials (MEPs)
- 1.3.2 Somatosensory Evoked Potentials (SSEPs)
- 1.3.3 Electroencephalography (EEG)
- 1.3.4 Electromyography (EMG)
- 1.3.5 Brainstem Auditory Evoked Potentials (BAEPs)
- 1.3.6 Visual Evoked Potentials (VEPs)
- 1.4 By Application
- 1.4.1 Spinal Surgery
- 1.4.2 Neurosurgery
- 1.4.3 Vascular Surgery
- 1.4.4 ENT Surgery
- 1.4.5 Orthopedic Surgery
- 1.4.6 Other Surgeries
- 1.5 By Product & Services
- 1.5.1 Systems
- 1.5.2 Services
- 1.5.3 Accessories
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,494.5 million → 2032: USD 5,740.08 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Intraoperative Neuromonitoring (IONM) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Intraoperative Neuromonitoring (IONM) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Intraoperative Neuromonitoring (IONM) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Intraoperative Neuromonitoring (IONM) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Intraoperative Neuromonitoring (IONM) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Intraoperative Neuromonitoring (IONM) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Intraoperative Neuromonitoring (IONM) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Intraoperative Neuromonitoring (IONM) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,494.5 million → 2032: USD 5,740.08 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Intraoperative Neuromonitoring (IONM) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Ambulatory Surgical Centers (ASCs)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Modality - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Motor Evoked Potentials (MEPs)
- 12.4.7.2 Somatosensory Evoked Potentials (SSEPs)
- 12.4.7.3 Electroencephalography (EEG)
- 12.4.7.4 Electromyography (EMG)
- 12.4.7.5 Brainstem Auditory Evoked Potentials (BAEPs)
- 12.4.7.6 Visual Evoked Potentials (VEPs)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Spinal Surgery
- 12.5.7.2 Neurosurgery
- 12.5.7.3 Vascular Surgery
- 12.5.7.4 ENT Surgery
- 12.5.7.5 Orthopedic Surgery
- 12.5.7.6 Other Surgeries
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product & Services - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Systems
- 12.6.7.2 Services
- 12.6.7.3 Accessories
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Intraoperative Neuromonitoring (IONM) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Intraoperative Neuromonitoring (IONM) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Intraoperative Neuromonitoring (IONM) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Intraoperative Neuromonitoring (IONM) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Natus Medical Incorporated
- 18.4 NuVasive, Inc.
- 18.5 SpecialtyCare
- 18.6 Nihon Kohden Corporation
- 18.7 inomed Medizintechnik GmbH
- 18.8 Cadwell Industries
- 18.9 Ambu A/S
- 18.10 Brainlab AG (Dr. Langer Medical GmbH)
- 18.11 GE HealthCare
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

