
Intraosseous Devices Market Overview:
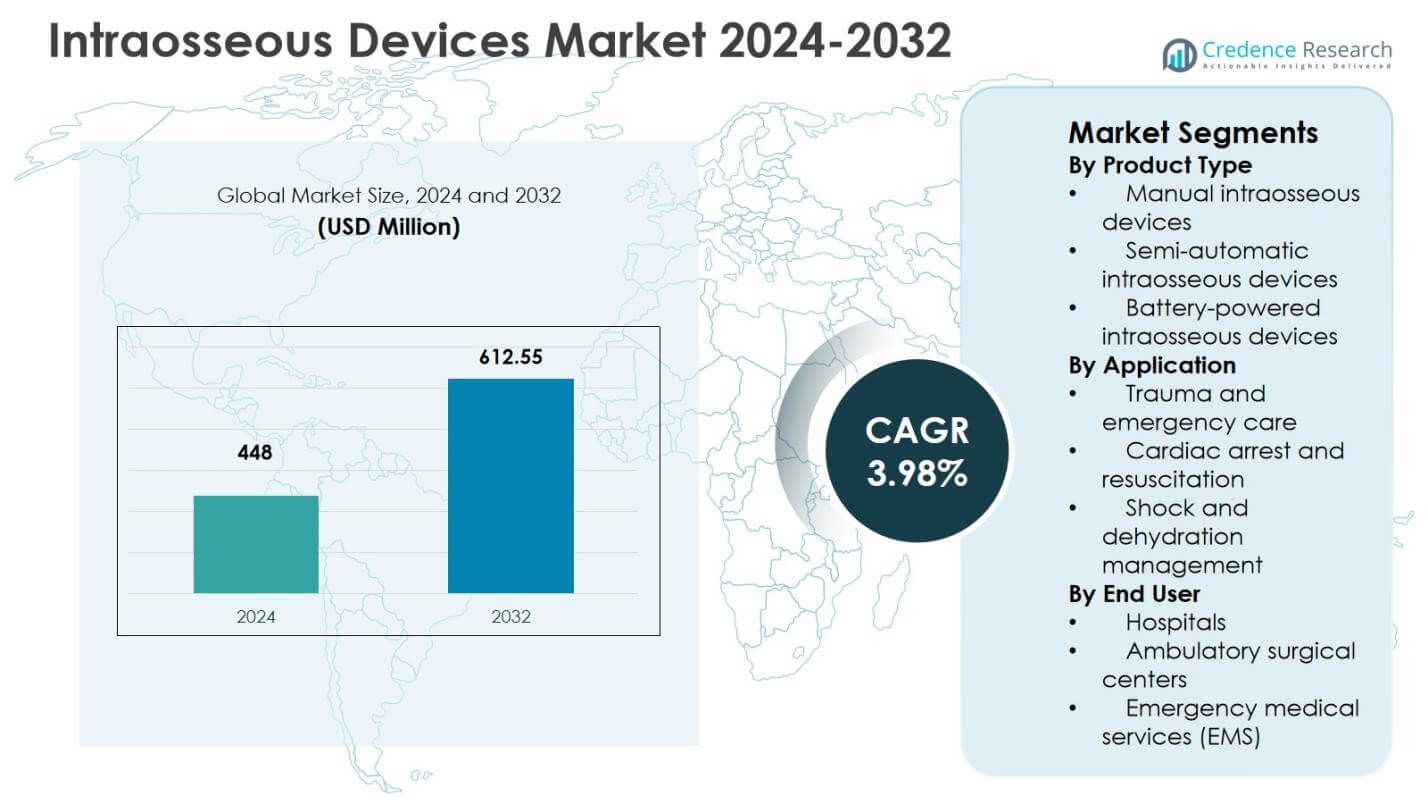
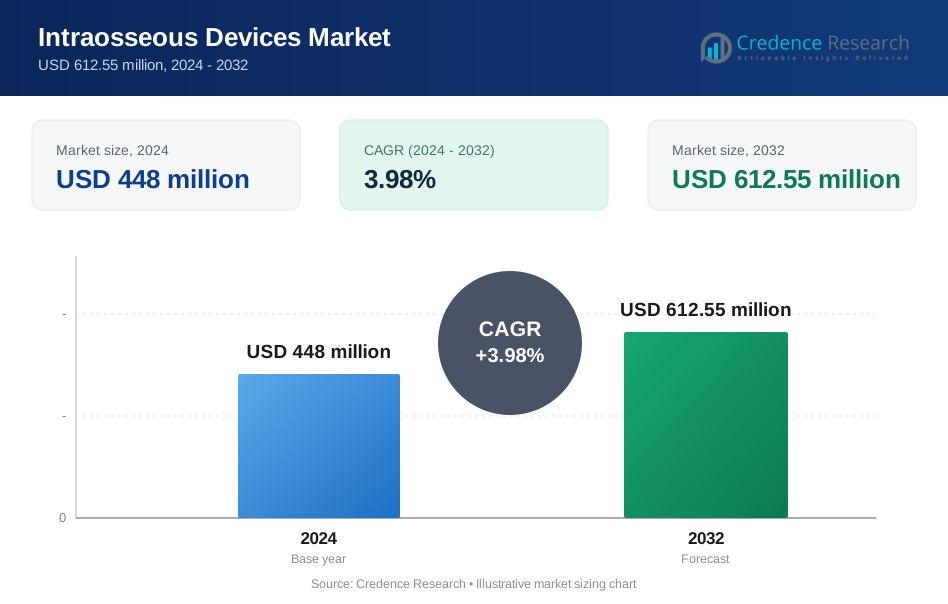
The Intraosseous Devices Market size was valued at USD 448 million in 2024 and is anticipated to reach USD 612.55 million by 2032, growing at a CAGR of 3.98% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Intraosseous Devices Market Size 2024 | USD 448 million |
| Intraosseous Devices Market, CAGR | 3.98% |
| Intraosseous Devices Market Size 2032 | USD 612.55 million |
Intraosseous Devices Market is led by established medical device manufacturers including Teleflex Incorporated, Becton, Dickinson and Company, Cook Medical, PerSys Medical, Pyng Medical Corp., SAM Medical, Aero Healthcare AU Pty Ltd., and Argon Medical Devices, Inc., all of which focus on product innovation, clinical reliability, and strong hospital and emergency service penetration. These players emphasize battery-powered and semi-automatic systems to enhance speed, safety, and success rates in emergency vascular access. Regionally, North America dominates the Intraosseous Devices Market with a 42.6% market share in 2024, driven by advanced emergency care infrastructure, high trauma incidence, and widespread adoption of intraosseous access in hospital and pre-hospital settings. Europe follows with 27.8% share, supported by standardized emergency protocols and strong clinician training across major healthcare systems.
Intraosseous Devices Market Insights
- The Intraosseous Devices Market was valued at USD 448 million in 2024 and is projected to reach USD 612.55 million by 2032, growing at a CAGR of 3.98% during the forecast period.
- Market growth is driven by rising emergency cases, increased trauma incidents, and strong adoption of intraosseous access for rapid vascular delivery in hospitals and emergency medical services.
- Battery-powered intraosseous devices led the market with a 8% segment share in 2024, supported by faster insertion and higher clinical success, while trauma and emergency care accounted for 49.6% application share.
- Market competition is shaped by product innovation, clinician training, and expansion of battery-powered and semi-automatic systems by leading manufacturers to improve procedural efficiency.
- Regionally, North America dominated with a 6% share in 2024, followed by Europe at 27.8% and Asia Pacific at 19.4%, driven by advanced emergency infrastructure and expanding trauma care systems.
Intraosseous Devices Market Segmentation Analysis:
By Product Type:
The Intraosseous Devices Market by product type is led by battery-powered intraosseous devices, which accounted for 56.8% of the market share in 2024, driven by their rapid insertion capability, consistent penetration force, and higher success rates in critical care settings. These devices are widely adopted in emergency departments and pre-hospital care due to reduced procedure time and minimal operator dependency. Semi-automatic intraosseous devices held 27.4% share, supported by cost-effectiveness and controlled deployment, while manual intraosseous devices captured 15.8% share, primarily used in low-resource settings owing to their simple design and lower acquisition cost.
- For instance, Teleflex's EZ-IO system achieved a 96.2% success rate for intraosseous access and infusion in 106 pediatric cases, with a mean device use duration of 60 hours and only 1.9% adverse events.
By Application:
By application, trauma and emergency care dominated the Intraosseous Devices Market with a 49.6% market share in 2024, supported by the rising incidence of road accidents, mass-casualty events, and the need for immediate vascular access when intravenous routes fail. Cardiac arrest and resuscitation accounted for 31.2% share, driven by protocol inclusion of intraosseous access in advanced life support guidelines. Shock and dehydration management represented 19.2% share, benefiting from increased use in pediatric and geriatric emergencies where peripheral venous access is challenging and rapid fluid administration is critical.
- For instance, PerSys Medical's Bone Injection Gun (B.I.G.) established IO access in under 60 seconds for adult trauma patients, providing high-flow infusion rates similar to peripheral IVs with a simple position-and-press mechanism.
By End User:
The end-user segment is dominated by hospitals, which held a 61.4% market share in 2024, due to high patient inflow, availability of trained professionals, and integration of intraosseous access into emergency and critical care protocols. Emergency medical services (EMS) accounted for 26.7% share, driven by growing adoption in pre-hospital trauma care and cardiac emergencies requiring rapid intervention. Ambulatory surgical centers represented 11.9% share, supported by their expanding role in urgent care procedures and increasing preparedness for emergency vascular access in outpatient surgical environments.
Key Growth Drivers
Rising Demand for Rapid Vascular Access in Emergency Care
The Intraosseous Devices Market is strongly driven by the growing need for rapid and reliable vascular access in emergency and critical care settings. In trauma cases, cardiac arrest, and severe shock, traditional intravenous access often fails due to collapsed veins or time constraints. Intraosseous devices enable immediate access to the vascular system through bone marrow, ensuring fast drug and fluid delivery. Increasing emergency admissions, road accidents, and cardiac emergencies globally are accelerating adoption across hospitals and pre-hospital settings, making intraosseous access a standard component of advanced life support protocols.
- For instance, BD's system delivered controlled insertions in EMS training for adults and pediatrics, featuring needlestick prevention during high-stress resuscitations. It enabled rapid fluid delivery when IV failed in critical emergencies.
Expansion of Pre-Hospital and Emergency Medical Services
The expanding role of emergency medical services significantly fuels growth in the Intraosseous Devices Market. EMS providers increasingly rely on intraosseous access as a first-line solution during pre-hospital care when intravenous insertion is not feasible. Growing investments in ambulance infrastructure, trauma response systems, and paramedic training across developed and emerging economies are reinforcing demand. Standardization of intraosseous device usage in emergency response guidelines further supports widespread adoption, particularly in time-critical scenarios where rapid intervention directly influences patient survival outcomes.
- For instance, Southwestern Ontario EMS agencies reported 83.7% successful prehospital IO access using semi-automatic devices in pediatric patients aged 0-17, with a median insertion time of 4 minutes.
Technological Advancements in Device Design
Continuous technological innovation is a major driver enhancing the growth of the Intraosseous Devices Market. Manufacturers are focusing on battery-powered and semi-automatic systems that improve insertion accuracy, reduce procedure time, and minimize complications. Ergonomic designs, single-use sterile kits, and enhanced safety features are improving clinician confidence and ease of use. These advancements are increasing acceptance across diverse healthcare settings, including emergency rooms, intensive care units, and field operations, while also supporting broader adoption among less-experienced healthcare professionals.
Key Trends & Opportunities
Integration of Intraosseous Access into Clinical Protocols
A prominent trend shaping the Intraosseous Devices Market is the formal integration of intraosseous access into clinical guidelines for emergency and resuscitation care. Advanced cardiac life support and trauma management protocols increasingly recommend intraosseous devices when intravenous access is delayed or unsuccessful. This institutional endorsement is creating long-term opportunities for manufacturers to expand hospital contracts and EMS deployments. Additionally, rising awareness and training initiatives among healthcare professionals are improving procedural familiarity, supporting consistent device utilization across adult and pediatric emergency care pathways.
- For instance, Training programs like those using the BD Intraosseous Vascular Access System achieve 93-97% first-pass success rates post short sessions with video and simulation, enabling paramedics and nurses to integrate IO into prehospital resuscitation for both adults and pediatrics when IV access delays occur.
Growth Opportunities in Emerging Healthcare Markets
Emerging economies present significant growth opportunities for the Intraosseous Devices Market due to expanding healthcare infrastructure and improving emergency care capabilities. Governments and private healthcare providers are investing in trauma centers, ambulance services, and emergency preparedness programs. Increasing access to affordable intraosseous devices and localized manufacturing initiatives further support market penetration. As awareness of rapid vascular access solutions improves, demand is expected to rise in both urban and semi-urban regions, creating opportunities for manufacturers to broaden their geographic footprint.
- For instance, Teleflex Incorporated collaborated with the Indian Society of Anesthesiologists in 2018 to conduct workshops on intraosseous infusion using the Arrow EZ-IO system for anesthesiologists across India.
Key Challenges
High Device Costs and Budget Constraints
High acquisition costs of advanced intraosseous devices pose a key challenge for market growth, particularly in cost-sensitive healthcare systems. Battery-powered systems and disposable components increase overall treatment expenses, limiting adoption in smaller hospitals and resource-limited settings. Budget constraints often force healthcare providers to prioritize conventional intravenous tools, slowing market penetration. Cost-effectiveness concerns also affect procurement decisions in public healthcare systems, creating pressure on manufacturers to balance innovation with affordability.
Risk of Complications and Limited Skilled Workforce
Despite clinical benefits, the Intraosseous Devices Market faces challenges related to potential complications such as infection, extravasation, and improper placement. Limited availability of adequately trained healthcare professionals in certain regions restricts safe and effective usage. Inconsistent training standards across healthcare facilities can reduce clinician confidence and hinder adoption. Addressing this challenge requires continuous education programs, standardized protocols, and improved device designs that minimize user dependency and procedural risks.
Regional Analysis
North America
North America dominated the Intraosseous Devices Market with a 42.6% market share in 2024, supported by advanced emergency care infrastructure, high adoption of trauma protocols, and widespread availability of trained healthcare professionals. The United States drives regional growth due to strong integration of intraosseous access in advanced cardiac life support and emergency medical services. High emergency admission rates, favorable reimbursement frameworks, and continuous technological adoption further support market leadership. Canada also contributes steadily through expanding pre-hospital care systems and increasing awareness of rapid vascular access solutions across emergency and critical care facilities.
Europe
Europe accounted for a 27.8% market share in 2024, driven by well-established healthcare systems and increasing standardization of emergency response protocols. Countries such as Germany, the United Kingdom, and France are key contributors due to rising trauma cases and strong adoption in hospital emergency departments and ambulance services. Regional growth is supported by government investments in emergency preparedness and growing emphasis on clinician training. The increasing use of battery-powered intraosseous devices across both adult and pediatric care settings continues to strengthen Europe’s position in the global market.
Asia Pacific
Asia Pacific captured a 19.4% market share in 2024, reflecting rapid improvements in healthcare infrastructure and emergency care capabilities. Countries including China, Japan, India, and Australia are witnessing rising demand due to increasing road accidents, urbanization, and expanding emergency medical services. Government initiatives to strengthen trauma care networks and growing awareness of intraosseous access among clinicians are key growth drivers. The region also benefits from a large patient population and rising investments in hospital expansion, positioning Asia Pacific as the fastest-growing regional market.
Latin America
Latin America held a 6.1% market share in 2024, supported by gradual improvements in emergency healthcare access and trauma management systems. Brazil and Mexico lead regional demand due to expanding hospital networks and increasing adoption of standardized emergency protocols. Growth is driven by rising incidence of accidents and efforts to enhance pre-hospital emergency response. However, budget constraints and uneven access to advanced devices limit faster adoption. Ongoing investments in healthcare modernization and training programs are expected to strengthen the regional presence of intraosseous devices.
Middle East & Africa
The Middle East & Africa accounted for a 4.1% market share in 2024, driven by increasing investments in emergency and trauma care infrastructure, particularly in Gulf Cooperation Council countries. Expansion of ambulance services, military medical preparedness, and growing awareness of rapid vascular access solutions support regional growth. South Africa contributes significantly due to its developing trauma care systems. However, limited access to advanced devices and workforce shortages in parts of Africa restrain broader adoption, keeping the region’s market share comparatively lower.
Intraosseous Devices Market Segmentations:
By Product Type
- Manual intraosseous devices
- Semi-automatic intraosseous devices
- Battery-powered intraosseous devices
By Application
- Trauma and emergency care
- Cardiac arrest and resuscitation
- Shock and dehydration management
By End User
- Hospitals
- Ambulatory surgical centers
- Emergency medical services (EMS)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape of the Intraosseous Devices Market is characterized by the presence of key players such as Teleflex Incorporated, Becton, Dickinson and Company, Cook Medical, PerSys Medical, Pyng Medical Corp., SAM Medical, Aero Healthcare AU Pty Ltd., and Argon Medical Devices, Inc. These companies focus on strengthening their market position through product innovation, portfolio expansion, and strategic partnerships with hospitals and emergency medical services. Battery-powered and semi-automatic device advancements remain central to competition, as manufacturers aim to improve ease of use, insertion success rates, and procedural safety. Leading players emphasize regulatory approvals, clinician training programs, and global distribution expansion to enhance adoption. Competitive intensity is further shaped by pricing strategies and the introduction of single-use sterile kits to meet infection control standards. Emerging players compete by offering cost-effective solutions, particularly targeting developing healthcare markets, while established firms leverage strong brand recognition and clinical validation to maintain leadership.
Key Player Analysis
- Teleflex Incorporated
- Becton, Dickinson and Company
- Cook Medical
- PerSys Medical
- Biopsybell S.R.L. (BPB Medica)
- Pyng Medical Corp.
- Aero Healthcare AU Pty Ltd.
- PAVmed Inc.
- SAM Medical
- Argon Medical Devices, Inc.
Recent Developments
- In May 2024, Teleflex Incorporated launched the Arrow™ EZ-IO™ Intraosseous Access Procedure Tray, a sterile, single-use kit that includes a battery-powered driver and complete set of components for streamlined intraosseous vascular access procedures, enhancing clinician workflow in critical care settings.
- In October 2024, Becton, Dickinson and Company (BD) introduced an enhanced BD® IO System designed to provide rapid vascular access for adult and pediatric patients, featuring integrated passive needle tip safety and a rechargeable battery-powered driver to improve safety and performance in emergency care.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Intraosseous Devices Market will continue to benefit from increasing reliance on rapid vascular access in emergency and critical care settings.
- Adoption of intraosseous access will expand further across pre-hospital emergency medical services due to time-critical intervention requirements.
- Technological advancements will focus on improving device safety, insertion accuracy, and ease of use for diverse clinical environments.
- Battery-powered and semi-automatic devices will gain stronger preference over manual systems in advanced healthcare facilities.
- Growing inclusion of intraosseous access in standardized clinical and resuscitation protocols will support sustained demand.
- Emerging economies will witness faster adoption as healthcare infrastructure and trauma care capabilities improve.
- Training programs and simulation-based education will enhance clinician proficiency and confidence in device usage.
- Manufacturers will increasingly emphasize cost-optimized products to improve penetration in budget-constrained healthcare systems.
- Strategic collaborations with hospitals and emergency service providers will strengthen market presence and distribution reach.
- Focus on pediatric and geriatric emergency care applications will create new growth opportunities for intraosseous device manufacturers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Emergency and Pre-Hospital Care
The growing need for rapid vascular access in trauma, cardiac arrest, and critical emergencies is driving adoption of intraosseous devices in both hospital and pre-hospital settings, especially as EMS systems expand and protocols increasingly recommend IO access when IV fails.
Technological Advancements in Device Design
Innovations such as battery-powered and semi-automatic intraosseous devices are improving insertion speed, accuracy, and safety, making these devices more attractive for clinicians and supporting broader adoption in diverse clinical environments.
Integration into Clinical Protocols
Formal inclusion of intraosseous access in advanced cardiac life support and trauma management guidelines is institutionalizing its use, leading to increased procurement by hospitals and EMS providers and ensuring consistent utilization in emergency care.
Growth in Emerging Healthcare Markets
Rising investments in healthcare infrastructure, trauma centers, and emergency preparedness in emerging economies are increasing access to intraosseous devices, supported by localized manufacturing and training initiatives that drive market penetration.
Focus on Pediatric and Geriatric Emergency Care
The challenges of vascular access in pediatric and elderly patients during emergencies are leading to greater reliance on intraosseous devices, as they offer rapid, reliable access when peripheral veins are difficult to cannulate.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Intraosseous Devices Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Intraosseous Devices Market projected to grow between 2024 and 2032?
Which Intraosseous Devices Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Intraosseous Devices Market?
Who are the leading companies in the Intraosseous Devices Market?
Which region commanded the largest share of the Intraosseous Devices Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Ambulatory surgical centers
- 1.2.3 Emergency medical services (EMS)
- 1.3 By Application
- 1.3.1 Trauma and emergency care
- 1.3.2 Cardiac arrest and resuscitation
- 1.3.3 Shock and dehydration management
- 1.4 By Product Type
- 1.4.1 Manual intraosseous devices
- 1.4.2 Semi-automatic intraosseous devices
- 1.4.3 Battery-powered intraosseous devices
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 448 million → 2032: USD 612.55 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Intraosseous Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Intraosseous Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Intraosseous Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Intraosseous Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Intraosseous Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Intraosseous Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Intraosseous Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Intraosseous Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 448 million → 2032: USD 612.55 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Intraosseous Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Ambulatory surgical centers
- 12.3.7.3 Emergency medical services (EMS)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Trauma and emergency care
- 12.4.7.2 Cardiac arrest and resuscitation
- 12.4.7.3 Shock and dehydration management
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Manual intraosseous devices
- 12.5.7.2 Semi-automatic intraosseous devices
- 12.5.7.3 Battery-powered intraosseous devices
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Intraosseous Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Intraosseous Devices Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Intraosseous Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Intraosseous Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Teleflex Incorporated
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Becton, Dickinson and Company
- 18.4 Cook Medical
- 18.5 PerSys Medical
- 18.6 Pyng Medical Corp.
- 18.7 SAM Medical
- 18.8 Aero Healthcare AU Pty Ltd.
- 18.9 Argon Medical Devices, Inc.
- 18.10 Biopsybell S.R.L. (BPB Medica)
- 18.11 PAVmed Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

