
Market Overview
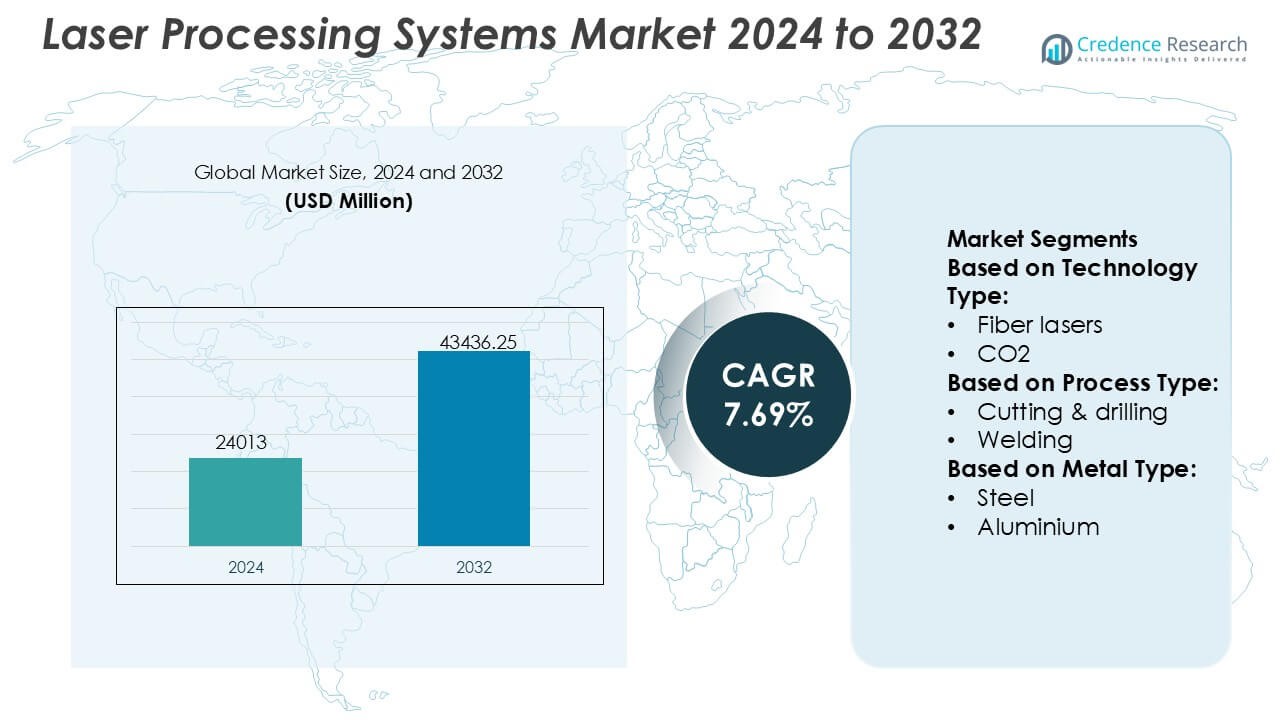
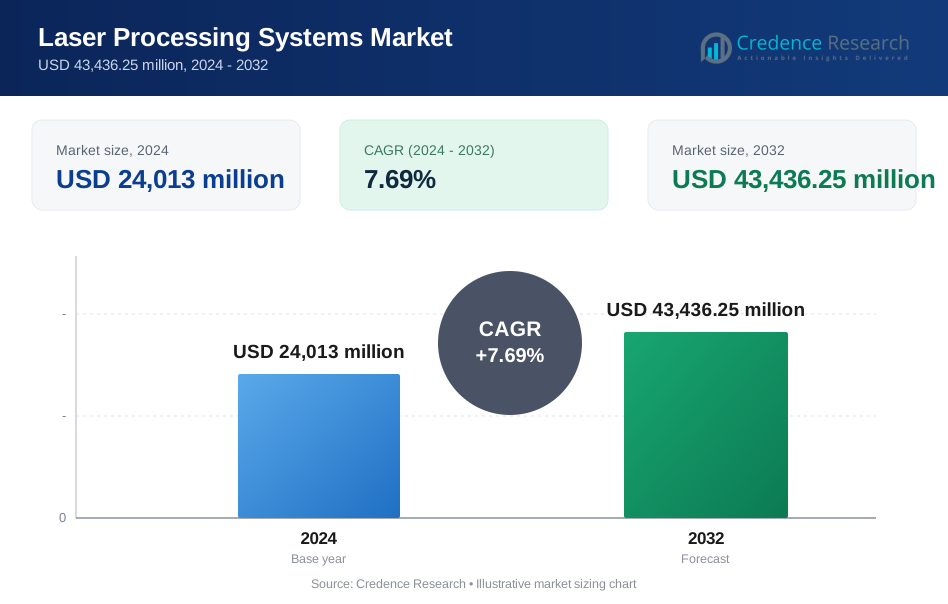
Laser Processing Systems Market size was valued USD 24013 million in 2024 and is anticipated to reach USD 43436.25 million by 2032, at a CAGR of 7.69% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Laser Processing Systems Market Size 2024 | USD 24013 Million |
| Laser Processing Systems Market, CAGR | 7.69% |
| Laser Processing Systems Market Size 2032 | USD 43436.25 Million |
The Laser Processing Systems Market is led by a group of technologically advanced manufacturers that compete on laser source innovation, system reliability, and application-specific performance. Top players focus on expanding high-power fiber and ultrafast laser portfolios while integrating automation, digital monitoring, and intelligent control features to support precision manufacturing. Competitive differentiation centers on processing speed, beam quality, lifecycle support, and the ability to address complex materials used in automotive, electronics, and industrial fabrication. Regionally, Asia-Pacific leads the market with an exact 34% share, supported by large-scale electronics, semiconductor, automotive, and battery manufacturing. Strong production volumes, rapid automation adoption, and continuous investment in advanced manufacturing infrastructure position the region as the primary growth engine for laser processing systems globally.
Market Insights
- The Laser Processing Systems Market size was valued at USD 24,013 million in 2024 and is projected to reach USD 43,436.25 million by 2032, growing at a CAGR of 7.69% during the forecast period.
- Market growth is driven by rising adoption of automation and precision manufacturing, with fiber lasers emerging as the dominant segment due to high efficiency, flexibility, and lower operating costs.
- Key trends include increased integration of laser systems with robotics, digital monitoring, and smart factory platforms, alongside growing demand for ultrafast lasers in micromachining and electronics processing.
- The competitive landscape remains intense, with leading players focusing on laser source innovation, high-power systems, application-specific solutions, and strong lifecycle service capabilities to differentiate offerings.
- Asia-Pacific leads the market with an exact 34% share, supported by large-scale electronics, semiconductor, automotive, and battery manufacturing, while capital-intensive system costs remain a key restraint for smaller manufacturers.
Market Segmentation Analysis:
By Technology Type
The Laser Processing Systems Market by technology type is led by fiber lasers, which hold the dominant share at around 46%. Fiber lasers maintain leadership due to high electrical efficiency, superior beam quality, and low maintenance requirements compared with CO₂ and solid-state systems. Their compact design and long operational lifetimes support continuous industrial use across automotive, electronics, and metal fabrication sectors. CO₂ lasers retain relevance in non-metal processing, while solid-state lasers serve precision applications. However, increasing adoption of automation and high-speed manufacturing continues to reinforce fiber lasers as the preferred industrial standard.
- For instance, Newport Corporation, under MKS Instruments, offers Spectra-Physics fiber laser platforms delivering output powers exceeding 2,000 watts with beam quality below 1.1 M² and designed operational lifetimes above 50,000 hours, supporting high-throughput cutting and welding applications in demanding production settings.
By Process Type
By process type, cutting and drilling represent the dominant sub-segment, accounting for approximately 41% of total demand. This dominance stems from widespread use in sheet metal fabrication, automotive body manufacturing, and heavy industrial components where precision and throughput are critical. Laser cutting enables high-speed processing, minimal material waste, and flexibility across thickness ranges. Welding and marking follow, supported by electronics and medical devices. Ongoing investments in smart factories and digitally controlled machining centers further strengthen cutting and drilling as the core revenue-generating process segment.
- For instance, Eurolaser GmbH develops large-format laser cutting systems with working areas up to 3,200 × 3,200 millimeters, achieving positioning accuracy of $\pm$0.1 millimeters and cutting speeds typically up to 85 meters per minute (1,414 mm/s), enabling high-volume, precision-driven industrial cutting operations.
By Metal Type
In terms of metal type, steel emerges as the leading sub-segment with an estimated 44% market share, driven by its extensive use in automotive structures, construction equipment, shipbuilding, and industrial machinery. Laser systems deliver high accuracy and repeatability when processing steel, supporting complex geometries and high-volume production. Aluminium and copper show rising adoption due to lightweighting and electrification trends, while plastics, ceramics, and composites serve specialized applications. Nevertheless, steel’s broad industrial footprint and compatibility with high-power laser systems sustain its dominant position.
Key Growth Drivers
Industrial Automation and Precision Manufacturing
Rising adoption of industrial automation drives sustained demand for laser processing systems across automotive, electronics, and general manufacturing. Manufacturers deploy fiber and solid-state lasers to achieve micron-level precision, consistent quality, and high repeatability in cutting, welding, and micromachining operations. Automated laser cells integrate seamlessly with robotics and CNC platforms, enabling lights-out manufacturing and reduced cycle times. These capabilities support mass customization, tighter tolerances, and improved yield, making laser systems a core technology for smart factories pursuing productivity gains and defect reduction.
- For instance, Han’s Laser Technology Industry Group Co., Ltd. supplies automated fiber laser cutting systems capable of positioning accuracy within ±0.03 millimeters, repeat positioning accuracy of ±0.02 millimeters, and continuous operation exceeding 20 hours per day, supporting high-throughput, fully automated manufacturing lines in automotive and electronics production.
Electrification and Lightweight Material Processing
The global shift toward electrification accelerates laser system adoption for processing advanced materials used in EVs, batteries, and power electronics. Laser cutting and welding deliver clean joints in aluminum, copper, and thin foils while minimizing heat-affected zones critical for battery safety and performance. As OEMs increase lightweighting initiatives, lasers replace mechanical tools to process high-strength alloys and composites with superior edge quality. This transition expands demand across battery module assembly, motor manufacturing, and thermal management components.
- For instance, IPG Photonics’ YLR series of ytterbium-doped fiber lasers delivers continuous output powers from 100 watts up to 4,000 watts with single-mode beam qualities suitable for precision cutting and welding, while its high-power fiber lasers can reach up to 125,000 watts output for thick metal processing, enabling manufacturers to achieve consistent, high-speed operations with reliable performance over extended duty cycles. 0search8.
Technological Advancements in Laser Sources
Continuous innovation in laser sources underpins market growth by improving efficiency, power density, and beam quality. High-power fiber lasers offer lower operating costs, longer lifetimes, and flexible beam delivery, broadening applicability across thick and thin materials. Advances in ultrafast and disk lasers enable precise micromachining with minimal thermal impact, supporting electronics and medical device manufacturing. Integrated monitoring, adaptive optics, and software control further enhance process stability, driving replacement cycles and new installations.
Key Trends & Opportunities
Adoption of Digital and Intelligent Laser Systems
Manufacturers increasingly adopt digitally enabled laser systems with real-time monitoring, closed-loop control, and data analytics. These capabilities optimize process parameters, predict maintenance needs, and reduce downtime. Integration with MES and Industry 4.0 platforms supports traceability and quality assurance across production lines. Intelligent lasers also enable rapid changeovers and remote diagnostics, creating opportunities for vendors to offer software, service contracts, and lifecycle solutions alongside hardware.
- For instance, Epilog Laser, Inc. offers Fusion Pro series laser systems equipped with Ethernet-based connectivity, onboard job memory exceeding 1,000 files, engraving speeds up to 165 inches per second, positioning resolutions of 5 microns, and CO₂ laser power options reaching 120 watts, enabling digitally controlled, high-throughput production with precise process repeatability.
Expansion into Micromachining and Electronics Manufacturing
Growing demand for miniaturized components fuels opportunities in micromachining, marking, and precision drilling. Ultrafast lasers address delicate substrates used in semiconductors, displays, and medical devices without compromising material integrity. As electronics manufacturing scales advanced packaging and flexible circuits, laser systems provide non-contact processing and high throughput. This trend opens avenues for specialized systems tailored to fine feature sizes and high-value applications.
- For instance, ALPhANOV develops ultrafast laser systems that are used in precision micromachining. The company’s product portfolio includes lasers operating with pulse durations below 10 picoseconds and repetition rates that can exceed 500 kilohertz.
Growth in Contract Manufacturing and Job Shops
Rising outsourcing of fabrication creates opportunities for laser system deployment in contract manufacturing and job shops. Flexible, multi-process laser platforms allow service providers to address diverse customer requirements efficiently. Shorter product lifecycles and variable batch sizes favor programmable laser solutions that reduce setup time and tooling costs. Vendors benefit through sales of versatile systems and aftermarket services to this expanding customer base.
Key Challenges
High Capital Investment and Cost Sensitivity
Laser processing systems require significant upfront investment, which can deter small and mid-sized manufacturers. Costs extend beyond equipment to include integration, safety infrastructure, and skilled operators. In price-sensitive markets, buyers may delay adoption or opt for lower-cost alternatives despite long-term efficiency benefits. Vendors must address this challenge through financing options, modular systems, and clear ROI justification to broaden market penetration.
Process Complexity and Skill Requirements
Advanced laser applications demand specialized process knowledge, parameter optimization, and maintenance expertise. Variability in materials and part geometries increases setup complexity and learning curves. Shortages of skilled technicians can limit effective utilization and slow adoption, particularly in emerging markets. Suppliers face pressure to simplify operation through automation, training programs, and user-friendly software while ensuring consistent performance across applications.
Regional Analysis
North America
North America holds an exact 31% market share in the Laser Processing Systems Market, driven by advanced manufacturing infrastructure and early adoption of automation technologies. The region benefits from strong demand across automotive, aerospace, electronics, and medical device manufacturing, where precision and repeatability are critical. High investment in smart factories, robotics integration, and digital manufacturing platforms supports sustained laser system adoption. The presence of leading laser technology suppliers, contract manufacturers, and system integrators further strengthens the market. Additionally, reshoring initiatives and focus on high-value manufacturing continue to stimulate demand for advanced laser processing solutions.
Europe
Europe accounts for an exact 26% market share, supported by its strong base in automotive, industrial machinery, and precision engineering. Countries such as Germany, Italy, and France emphasize high-quality manufacturing, where laser cutting, welding, and micromachining play a central role. Strict quality standards and energy-efficiency regulations encourage adoption of modern fiber and solid-state laser systems. The region also benefits from sustained investment in Industry 4.0, digitalization, and advanced materials processing. Strong collaboration between equipment manufacturers, research institutes, and end users accelerates innovation and technology upgrades across the region.
Asia-Pacific
Asia-Pacific dominates the Laser Processing Systems Market with an exact 34% market share, driven by large-scale manufacturing activity and rapid industrial expansion. China, Japan, South Korea, and Taiwan represent major demand centers due to strong electronics, semiconductor, automotive, and battery manufacturing bases. High-volume production environments favor laser systems for their speed, precision, and automation compatibility. Government initiatives supporting advanced manufacturing and domestic equipment development further strengthen regional adoption. The presence of extensive contract manufacturing and electronics assembly ecosystems positions Asia-Pacific as the fastest-growing and most competitive regional market.
Latin America
Latin America holds an exact 5% market share, reflecting gradual adoption of laser processing technologies across automotive, metal fabrication, and electronics assembly sectors. Brazil and Mexico serve as key markets due to their established automotive manufacturing bases and proximity to global supply chains. Increasing investment in industrial automation and modernization of fabrication facilities supports demand for laser cutting and welding systems. However, adoption remains selective due to capital constraints and uneven technological maturity. Growth opportunities emerge as regional manufacturers seek productivity improvements and quality enhancements to remain competitive in export-oriented industries.
Middle East & Africa
The Middle East & Africa region accounts for an exact 4% market share, supported by growing industrial diversification and infrastructure development. Demand concentrates in metal fabrication, energy equipment manufacturing, and emerging electronics assembly operations. Countries in the Gulf region invest in advanced manufacturing capabilities to reduce reliance on imports, driving adoption of laser cutting and marking systems. In Africa, gradual industrialization and foreign direct investment contribute to steady, though limited, uptake. While market penetration remains relatively low, long-term opportunities exist through industrial expansion and technology transfer initiatives.
Market Segmentations:
By Technology Type:
- Fiber lasers
- CO2
By Process Type:
- Cutting & drilling
- Welding
By Metal Type:
- Steel
- Aluminium
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Laser Processing Systems Market features a Newport Corporation (MKS Instruments, Inc.), Eurolaser GmbH, Han's Laser Technology Industry Group Co., Ltd., Altec GmbH, IPG Photonics Corporation, Epilog Laser, Inc., Alpha Nov Laser, Bystronic Laser AG, Coherent Inc., and Amada Co., Ltd. The Laser Processing Systems Market exhibits a highly competitive landscape characterized by continuous technological innovation, application-specific customization, and strong emphasis on performance reliability. Market participants compete on laser power scalability, beam quality, processing speed, and system integration capabilities to meet the evolving needs of automotive, electronics, aerospace, and precision manufacturing sectors. Vendors increasingly differentiate through advanced software, real-time monitoring, and automation-ready platforms that enhance productivity and process consistency. Strategic priorities include expanding solution portfolios for lightweight materials, batteries, and micromachining applications, while strengthening global service networks and lifecycle support. Competitive intensity remains high as companies invest in R&D, digitalization, and flexible manufacturing solutions to capture long-term contracts and maintain customer loyalty.
Key Player Analysis
- Newport Corporation (MKS Instruments, Inc.)
- Eurolaser GmbH
- Han's Laser Technology Industry Group Co., Ltd.
- Altec GmbH
- IPG Photonics Corporation
- Epilog Laser, Inc.
- Alpha Nov Laser
- Bystronic Laser AG
- Coherent Inc.
- Amada Co., Ltd.
Recent Developments
- In April 2025, AkzoNobel bonds with IPG Photonics over laser curing for powder coatings. The partnership between AkzoNobel and IPG Photonics focused on applying laser technology for curing powder coatings.
- In January 2025, Laser Photonics Corp (LPC) (LASE) announced a significant development: a novel laser cleaning-enabled robotic crawler designed to revolutionize industrial maintenance, especially for naval corrosion, in partnership with Fonon Technologies and Boston Engineering, showcasing it at the Pearl Harbor Naval Shipyard.
- In January 2024, Coherent unveiled the OBIS 640 XT, a new red laser module that offers high output power, low noise, and excellent beam quality. This module complements their existing blue and green laser offerings, collectively enhancing the performance of high-performance SRM systems. The introduction of this product signifies Coherent's commitment to advancing laser technology for various applications.
- In January 2024, Novanta Inc. acquired Motion Solutions, which is expected to facilitate the development of innovative intelligent subsystems by leveraging their combined technological capabilities. This acquisition aims to enhance their product offerings and create unique solutions tailored to customer needs.
Report Coverage
The research report offers an in-depth analysis based on Technology Type, Process Type, Metal Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Laser processing systems will see wider adoption as manufacturers prioritize precision, automation, and repeatable quality across high-volume production environments.
- Fiber and ultrafast laser technologies will continue to gain preference due to higher efficiency, longer service life, and lower operating complexity.
- Integration of laser systems with robotics, AI-driven monitoring, and digital manufacturing platforms will strengthen smart factory deployments.
- Demand for laser-based processing of lightweight and advanced materials will rise across electric vehicles, batteries, and power electronics.
- Micromachining and fine-feature processing will expand steadily with growth in electronics, medical devices, and semiconductor packaging.
- Software-enabled process optimization and predictive maintenance will become standard features in next-generation laser platforms.
- Modular and multi-process laser systems will gain traction by supporting flexible production and rapid changeovers.
- Adoption will increase among contract manufacturers and job shops seeking higher throughput and reduced tooling dependency.
- Vendors will place greater focus on service models, training, and lifecycle support to strengthen long-term customer relationships.
- Emerging economies will contribute incremental growth as industrial automation and advanced fabrication capabilities expand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Industrial Automation and Precision Manufacturing
The increasing adoption of automation and precision manufacturing in sectors like automotive, electronics, and general industry is driving demand for laser processing systems. These systems enable high-speed, repeatable, and micron-level precision operations, supporting smart factory initiatives and productivity gains.
Electrification and Lightweight Material Processing
The global shift toward electric vehicles and advanced electronics is accelerating the need for laser systems capable of processing lightweight and conductive materials such as aluminum and copper. Lasers provide clean, precise joints and minimal thermal impact, which are critical for battery and power electronics manufacturing.
Technological Advancements in Laser Sources
Continuous innovation in fiber, ultrafast, and disk laser technologies is improving efficiency, beam quality, and operational lifetimes. These advancements expand the range of applications, reduce operating costs, and drive replacement cycles and new installations across industries.
Integration with Digital and Intelligent Manufacturing
The integration of laser systems with robotics, real-time monitoring, and Industry 4.0 platforms is optimizing process control, reducing downtime, and enabling predictive maintenance. This digitalization trend is making laser processing systems more attractive for high-volume, quality-critical production environments.
Growth in Contract Manufacturing and Job Shops
The rise of contract manufacturing and job shops is fueling demand for flexible, multi-process laser platforms. These systems allow service providers to efficiently address diverse customer requirements, reduce setup times, and support variable batch sizes, expanding the market's reach.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Laser Processing Systems Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Laser Processing Systems Market projected to grow between 2024 and 2032?
Which Laser Processing Systems Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Laser Processing Systems Market?
Who are the leading companies in the Laser Processing Systems Market?
Which region commanded the largest share of the Laser Processing Systems Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Metal Type
- 1.2.1 Steel
- 1.2.2 Aluminium
- 1.2.3 Copper
- 1.2.4 Plastics & Composites
- 1.3 By Process Type
- 1.3.1 Cutting & drilling
- 1.3.2 Welding
- 1.3.3 Marking & engraving
- 1.3.4 Micromachining
- 1.4 By Technology Type
- 1.4.1 Fiber lasers
- 1.4.2 CO2 lasers
- 1.4.3 Solid-state lasers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 24,013 million → 2032: USD 43,436.25 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Laser Processing Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Laser Processing Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Laser Processing Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Laser Processing Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Laser Processing Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Laser Processing Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Laser Processing Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Laser Processing Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 24,013 million → 2032: USD 43,436.25 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Laser Processing Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Metal Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Steel
- 12.3.7.2 Aluminium
- 12.3.7.3 Copper
- 12.3.7.4 Plastics & Composites
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Process Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cutting & drilling
- 12.4.7.2 Welding
- 12.4.7.3 Marking & engraving
- 12.4.7.4 Micromachining
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fiber lasers
- 12.5.7.2 CO2 lasers
- 12.5.7.3 Solid-state lasers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Laser Processing Systems Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Laser Processing Systems Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Laser Processing Systems Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Newport Corporation (MKS Instruments, Inc.)
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Eurolaser GmbH
- 17.4 Han's Laser Technology Industry Group Co., Ltd.
- 17.5 Altec GmbH
- 17.6 IPG Photonics Corporation
- 17.7 Epilog Laser, Inc.
- 17.8 Alpha Nov Laser
- 17.9 Bystronic Laser AG
- 17.10 Coherent Inc.
- 17.11 Amada Co., Ltd.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

