
Market Overview:
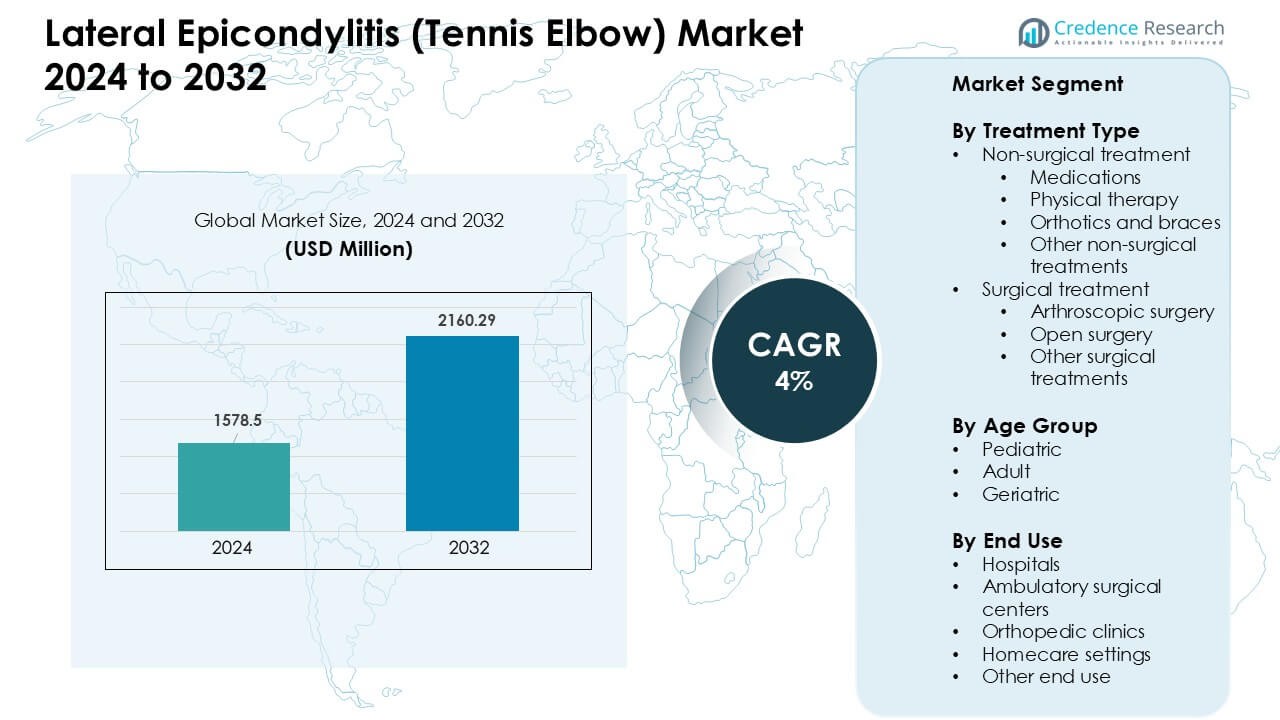
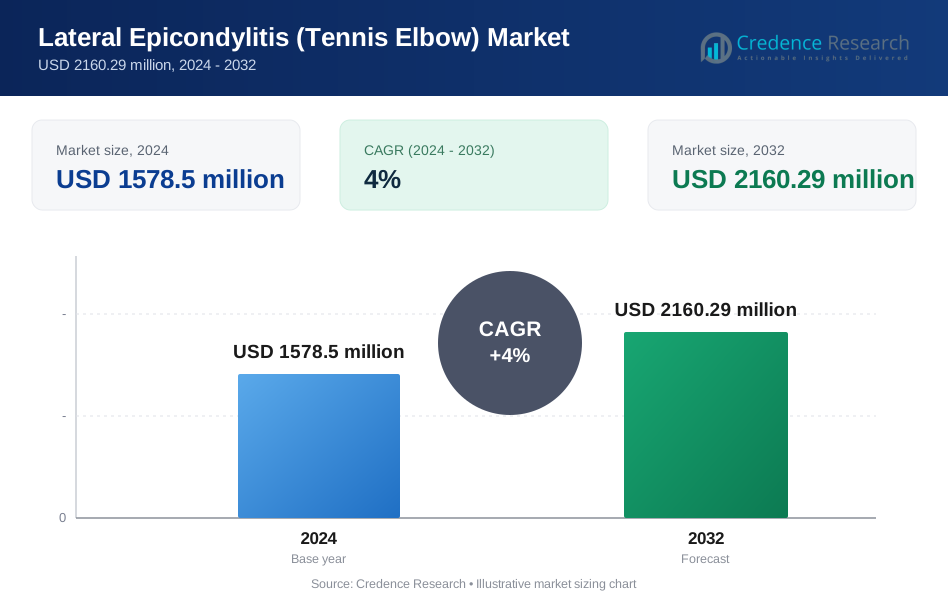
Lateral Epicondylitis (Tennis Elbow) Market was valued at USD 1578.5 million in 2024 and is anticipated to reach USD 2160.29 million by 2032, growing at a CAGR of 4 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Lateral Epicondylitis (Tennis Elbow) Market Size 2024 | USD 1578.5 Million |
| Lateral Epicondylitis (Tennis Elbow) Market, CAGR | 4% |
| Lateral Epicondylitis (Tennis Elbow) Market Size 2032 | USD 2160.29 Million |
The Lateral Epicondylitis (Tennis Elbow) Market is shaped by leading players such as Pfizer, Novartis, Merck & Co, GlaxoSmithKline, Zimmer Biomet, Ossur Corporate, Pharmascience, MedStar Health, ReLiva Physiotherapy & Rehab, and Scandinavian Physiotherapy Center. These companies strengthen their positions through advanced drug therapies, improved braces and orthopedic devices, and expanding physiotherapy networks that support long-term recovery. North America emerged as the leading region in 2024 with about 38% share, driven by strong healthcare access, high sports participation, and broad adoption of non-surgical and minimally invasive treatment approaches.
Market Insights:
- The Lateral Epicondylitis (Tennis Elbow) Market was valued at USD 5 million in 2024 and is projected to reach USD 2160.29 million by 2032, growing at a CAGR of 4%.
- Growing cases linked to repetitive strain, rising sports participation, and wider adoption of non-surgical care drive steady demand across hospitals and orthopedic clinics.
- Trends include expanding physiotherapy networks, rising use of regenerative injections, and increasing uptake of advanced braces that support faster recovery and reduce surgical dependence.
- Competitive activity is shaped by players such as Pfizer, Novartis, Merck & Co, Zimmer Biomet, and Ossur Corporate, all expanding conservative treatment support while physiotherapy centers strengthen outpatient care.
- North America held the largest share at 38%, while adults formed the dominant age segment at 71% in 2024; non-surgical treatments accounted for about 82% of total demand.
Market Segmentation Analysis:
By Treatment Type
Non-surgical treatment held the dominant share in 2024 with about 82% of the Lateral Epicondylitis (Tennis Elbow) Market. Patients favored medications, physical therapy, and braces because these options offered lower risk, quick pain relief, and strong clinical success rates. Physical therapy remained the largest sub-segment due to rising preference for targeted exercises and growing referral rates from primary care providers. Surgical procedures such as arthroscopy and open repair stayed limited to severe or chronic cases, which kept their adoption lower despite improved postoperative outcomes.
- For instance, in a large population-based study, among a sample of 576 patients with lateral elbow tendinosis, 82% received non-steroidal anti-inflammatory drugs (NSAIDs), and 77% used bracing as part of initial management; only 2% went directly to surgery.
By Age Group
Adults accounted for the largest share in 2024 with nearly 71% of the Lateral Epicondylitis (Tennis Elbow) Market. Working-age individuals faced higher repetitive-strain exposure from sports, industrial tasks, and computer-based work, which increased treatment demand. The geriatric group showed steady growth as age-related tendon degeneration raised case prevalence. Pediatric cases remained minimal due to lower participation in high-intensity repetitive activities, resulting in far fewer diagnoses and treatment interventions compared to adults.
- For instance, a population-based study found the highest annual incidence of lateral elbow tendinosis among people aged 40–49 years, at 9.0 per 1,000 persons per year overall (7.8 per 1,000 for men, 10.2 per 1,000 for women).
By End Use
Hospitals led the Lateral Epicondylitis (Tennis Elbow) Market in 2024 with about 46% share. Patients relied on hospitals for advanced diagnostics, specialist consultations, and access to both non-surgical and surgical care. Orthopedic clinics followed due to rising sports-injury consultations and faster outpatient services. Ambulatory surgical centers gained traction for minimally invasive procedures with shorter recovery time. Homecare settings grew steadily as tele-rehabilitation, home physiotherapy, and brace-based management became more accessible for mild to moderate cases.
Key Growth Drivers:
Rising Incidence Linked to Repetitive Strain Activities Growing cases of Lateral Epicondylitis stem from repetitive wrist and forearm movements across sports, industrial labor, and desk-based work. More people now engage in racquet sports, gym training, and high-intensity home workouts, which raises tendon overuse injuries. Office workers also show higher risk due to continuous typing and mouse use. This widespread strain exposure expands patient pools and drives steady demand for therapy, braces, medications, and outpatient care. As ergonomic awareness improves, early diagnosis rates rise, pushing more individuals toward formal treatment and boosting overall market growth.
- For instance, in a population of 5,036 workers across several studies, those with a Strain Index (SI) score greater than 5.1 had an increased odds ratio (~1.75) of developing Lateral Epicondylitis.
Strong Preference for Non-Surgical and Minimally Invasive Therapies The market grows as patients shift toward conservative and minimally invasive treatments that offer pain relief without long recovery periods. Physical therapy, steroid injections, shockwave therapy, and orthotic solutions see strong adoption due to their accessibility and lower complication risk. Physicians also recommend staged treatment approaches, which increases patient volume across multiple therapy cycles. Technological advances in therapy devices help clinicians improve tendon healing outcomes. The trend reduces the need for open surgery while expanding revenue across physiotherapy centers, sports clinics, and home-based rehabilitation providers.
- For instance, in a clinical series combining supervised therapeutic exercise with low-energy ESWT, patients saw significant reductions in pain intensity and improvements in grip strength and limb function by the 4th week of treatment suggesting that non-surgical therapies can restore function fairly quickly while avoiding surgical risk.
Growth of Sports Participation and Occupational Health Programs Higher global participation in recreational and professional sports increases the risk of elbow injuries, which boosts treatment demand. Sports organizations promote early injury reporting, improving diagnosis rates and expanding patient entry points. Workplace safety programs in manufacturing, logistics, and construction also encourage screening and early management of repetitive-motion injuries. Many companies now adopt ergonomic tools and wellness programs, which increase awareness and drive more individuals to seek medical care. This structured focus on injury prevention and rapid intervention amplifies the market for therapy services, braces, and specialist consultations.
Key Trends & Opportunities:
Increasing Adoption of Regenerative Therapies Regenerative options such as platelet-rich plasma (PRP) and stem-cell-based injections attract growing interest due to their potential to improve tendon healing. Clinics integrate these therapies into sports-injury care as patients seek alternatives to surgery. Research continues to validate their effectiveness, which encourages broader use in chronic cases. As providers refine protocols, treatment demand grows among athletes and active adults looking for faster recovery.
- For instance, in a 2018 retrospective study of 64 patients with chronic lateral epicondylitis resistant to standard care, 87.5% reported significant symptomatic improvement after PRP injection, showing a clear and sustained benefit for many non-responders to conventional therapy.
Expansion of Home-Based and Digital Rehabilitation Remote physiotherapy platforms, wearable devices, and app-guided exercise programs create new opportunities for patient engagement. These tools support home-based recovery, reduce clinic visits, and improve adherence to therapy plans. Advancements in telehealth make virtual assessments easier, which broadens access to care in rural and underserved regions. The shift enhances treatment convenience and stimulates long-term adoption of digital rehabilitation solutions.
- For instance, a 2022 quasi-experimental study on digital physiotherapy in patients recovering from long COVID-19 found that after a four-week app-guided home-exercise program, participants showed statistically significant improvements in functional capacity (assessed by standard tests) demonstrating feasibility, safety, and good adherence.
Innovations in Bracing and Orthotic Technologies New lightweight, adjustable, and ergonomically designed braces improve pain reduction and movement support for patients. Manufacturers introduce breathable materials, targeted compression zones, and customizable tension systems. These upgrades enhance comfort and boost daily use, driving higher adoption across both athletes and workers managing chronic strain injuries. Product innovation strengthens the competitive landscape and expands home-use applications.
Key Challenges:
Limited Long-Term Effectiveness of Certain Conservative Therapies Some widely used treatments, such as corticosteroid injections, provide short-term relief but risk limited long-term benefits. Patients may experience recurring pain, which leads to repeated treatment cycles and inconsistent outcomes. This uncertainty reduces patient confidence and forces providers to explore alternative therapy plans. The variation in results also complicates cost-effectiveness analysis for payers and slows broader adoption in insurance-driven systems.
High Variation in Treatment Access and Clinical Guidelines Access to specialized physiotherapy, regenerative treatments, and advanced diagnostics varies widely between regions. Patients in rural and low-income areas struggle to obtain consistent care, creating uneven treatment adoption. Differences in clinical guidelines across countries add further complexity and reduce standardization in care pathways. These gaps hinder uniform market growth and limit patient outcomes, especially in systems with constrained reimbursement structures.
Regional Analysis:
North America
North America led the Lateral Epicondylitis (Tennis Elbow) Market in 2024 with about 38% share. The region showed strong demand due to high participation in sports, rising overuse injuries, and broad access to orthopedic and physiotherapy services. Employers also focused on occupational health programs, which improved early diagnosis rates. Advanced treatment adoption, including PRP injections and minimally invasive procedures, grew across clinics. The strong presence of specialty orthopedic centers supported patient inflow and strengthened market leadership.
Europe
Europe held nearly 30% of the Lateral Epicondylitis (Tennis Elbow) Market in 2024. Growth came from expanding physiotherapy networks, strong sports culture, and wider acceptance of conservative treatment methods. Countries like Germany, France, and the UK showed high patient volumes driven by workplace strain injuries and active aging populations. Reimbursement support for therapy and diagnostics improved treatment access. Increasing use of ergonomic devices in industrial sectors also contributed to steady regional growth.
Asia-Pacific
Asia-Pacific captured about 24% share of the Lateral Epicondylitis (Tennis Elbow) Market in 2024. Rising sports participation, growing fitness awareness, and expanding middle-class healthcare spending pushed treatment demand. Countries such as China, Japan, and India saw more repetitive-strain cases linked to industrial and office-based work. Physiotherapy adoption increased as private clinics and urban healthcare centers expanded. The region also showed rising interest in regenerative injections and home-based therapy options, supporting its strong growth trajectory.
Latin America
Latin America accounted for nearly 5% of the Lateral Epicondylitis (Tennis Elbow) Market in 2024. The region experienced moderate demand driven by expanding physiotherapy access and higher awareness of musculoskeletal injuries. Brazil and Mexico led treatment volumes due to larger urban populations and sports activity levels. Limited reimbursement and uneven specialist availability slowed wider adoption. However, growing private healthcare investment and more orthopedic clinics supported steady improvement in patient management.
Middle East & Africa
The Middle East & Africa held about 3% share of the Lateral Epicondylitis (Tennis Elbow) Market in 2024. Market growth remained gradual due to limited specialist coverage and lower adoption of advanced therapies. Urban centers in the UAE, Saudi Arabia, and South Africa drove most of the demand, supported by better diagnostic capabilities and expanding private hospitals. Sports injuries and occupational strain cases increased as fitness participation rose. Ongoing healthcare modernization is expected to improve access and support future treatment uptake.
Market Segmentations:
By Treatment Type
- Non-surgical treatment
- Medications
- Physical Therapy
- Orthotics and Braces
- Other non- surgical Treatments
- Surgical treatment
- Arthroscopic Surgery
- Open Surgery
- Other surgical Treatments
By Age Group
- Pediatric
- Adult
- Geriatric
By End Use
- Hospitals
- Ambulatory surgical centers
- Orthopedic clinics
- Homecare settings
- Other end use
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape:
The Lateral Epicondylitis (Tennis Elbow) Market features active competition among key players such as Pfizer, Novartis, Merck & Co, GlaxoSmithKline, Zimmer Biomet, Ossur Corporate, Pharmascience, MedStar Health, ReLiva Physiotherapy & Rehab, and Scandinavian Physiotherapy Center. Companies strengthen their positions by expanding non-surgical therapies, improving targeted medications, and enhancing physical rehabilitation services. Major orthopedic manufacturers focus on advanced braces and supportive devices designed to reduce strain and improve tendon recovery. Healthcare networks and physiotherapy centers widen their treatment programs with personalized exercise protocols and tele-rehabilitation support. Drug makers invest in improved anti-inflammatory options and regenerative-care research to address chronic cases. Rising partnerships between pharmaceutical firms, orthopedic specialists, and physiotherapy groups help streamline patient pathways and increase access to combined treatment plans. The competitive environment continues to shift toward conservative care solutions, advanced rehabilitation models, and evidence-backed therapies that improve long-term outcomes.
Key Player Analysis:
- Pfizer
- ReLiva Physiotherapy & Rehab
- Novartis
- Zimmer Biomet
- Scandinavian Physiotherapy Center
- Ossur Corporate
- MedStar Health
- Pharmascience
- GlaxoSmithKline
- Merck & Co
Recent Developments:
- In 2024–2025, Novartis has been actively advancing a tendinopathy pipeline relevant to lateral-epicondylitis–type biology: their clinical-trials pages and investor materials show ongoing development of tendinopathy candidates. Specifically, a Phase 2 program for NGI226 microparticles has been ongoing in mid-portion Achilles tendinopathy since early 2023 (NCT05592990). The company also has an ongoing Phase 3 program for Cosentyx (secukinumab) in rotator cuff tendinopathy (e.g., NCT05758415), signaling increased pharma investment in biologic/minimally-invasive approaches for tendon disorders.
- In 2024–2025, ReLiva Physiotherapy & Rehab continued to expand and publish region-focused patient education and clinic guides for tennis elbow (examples: the Ultimate Guide on Where to Treat Tennis Elbow in Bangalore and several clinic pages describing physiotherapy programs, home exercises, bracing and clinic treatments). This reflects their ongoing service expansion and content updates to support conservative (physiotherapy) care for lateral epicondylitis.
- In November 2024, Pfizer published general patient-facing guidance on exercises and self-care for tennis elbow (lateral epicondylitis) as part of their standard health education content, with the article medically reviewed and published on November 14, 2024. This was routine health content publication, not a major investor event.
Report Coverage:
The research report offers an in-depth analysis based on Treatment Type, Age Group, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for non-surgical care will rise as patients prefer faster recovery options.
- Digital physiotherapy platforms will expand access to guided home-based rehabilitation.
- Regenerative treatments like PRP will gain broader clinical acceptance.
- Advanced orthopedic braces will see higher adoption due to better comfort and support.
- Early diagnosis rates will increase with improved workplace screening programs.
- Sports medicine clinics will widen treatment capacity as participation in fitness activities grows.
- Minimally invasive procedures will gain traction for chronic and severe cases.
- Partnerships between pharmaceutical companies and physiotherapy networks will strengthen care pathways.
- Aging populations will drive more cases linked to tendon degeneration.
- Emerging markets will record stronger growth as physiotherapy infrastructure improves.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Incidence Linked to Repetitive Strain Activities
Increasing participation in sports, industrial labor, and desk-based work leads to more cases of lateral epicondylitis, expanding the patient pool and driving demand for therapies, braces, and medications.
Strong Preference for Non-Surgical and Minimally Invasive Therapies
Patients and providers favor conservative treatments such as physical therapy, orthotics, and regenerative injections due to their lower risk and faster recovery, boosting market growth for non-surgical solutions.
Growth of Sports Participation and Occupational Health Programs
Higher engagement in recreational and professional sports, along with workplace ergonomic initiatives, increases early diagnosis and treatment rates, fueling demand for both preventive and therapeutic interventions.
Increasing Adoption of Regenerative Therapies
Emerging treatments like platelet-rich plasma (PRP) and stem-cell injections are gaining traction as alternatives to surgery, attracting patients seeking improved tendon healing and faster recovery.
Expansion of Home-Based and Digital Rehabilitation
The rise of tele-rehabilitation, wearable devices, and app-guided exercise programs enhances access to care, especially in underserved regions, and supports long-term adherence to therapy plans.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Lateral Epicondylitis (Tennis Elbow) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is Lateral Epicondylitis (Tennis Elbow) Market projected to grow between 2024 and 2032?
Which Lateral Epicondylitis (Tennis Elbow) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of Lateral Epicondylitis (Tennis Elbow) Market?
Who are the leading companies in Lateral Epicondylitis (Tennis Elbow) Market?
Which region commanded the largest share of Lateral Epicondylitis (Tennis Elbow) Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Hospitals
- 1.2.2 Ambulatory surgical centers
- 1.2.3 Orthopedic clinics
- 1.2.4 Homecare settings
- 1.2.5 Other end use
- 1.3 By Age Group
- 1.3.1 Pediatric
- 1.3.2 Adult
- 1.3.3 Geriatric
- 1.4 By Treatment Type
- 1.4.1 Non-surgical treatment
- 1.4.2 Medications
- 1.4.3 Physical Therapy
- 1.4.4 Orthotics and Braces
- 1.4.5 Other non-surgical Treatments
- 1.4.6 Surgical treatment
- 1.4.7 Arthroscopic Surgery
- 1.4.8 Open Surgery
- 1.4.9 Other surgical Treatments
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1578.5 million → 2032: USD 2160.29 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Lateral Epicondylitis (Tennis Elbow) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Lateral Epicondylitis (Tennis Elbow) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Lateral Epicondylitis (Tennis Elbow) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Lateral Epicondylitis (Tennis Elbow) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Lateral Epicondylitis (Tennis Elbow) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Lateral Epicondylitis (Tennis Elbow) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Lateral Epicondylitis (Tennis Elbow) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Lateral Epicondylitis (Tennis Elbow) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1578.5 million → 2032: USD 2160.29 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Lateral Epicondylitis (Tennis Elbow) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Ambulatory surgical centers
- 12.3.7.3 Orthopedic clinics
- 12.3.7.4 Homecare settings
- 12.3.7.5 Other end use
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Age Group - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pediatric
- 12.4.7.2 Adult
- 12.4.7.3 Geriatric
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Treatment Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Non-surgical treatment
- 12.5.7.2 Medications
- 12.5.7.3 Physical Therapy
- 12.5.7.4 Orthotics and Braces
- 12.5.7.5 Other non-surgical Treatments
- 12.5.7.6 Surgical treatment
- 12.5.7.7 Arthroscopic Surgery
- 12.5.7.8 Open Surgery
- 12.5.7.9 Other surgical Treatments
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Lateral Epicondylitis (Tennis Elbow) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Lateral Epicondylitis (Tennis Elbow) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Lateral Epicondylitis (Tennis Elbow) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Lateral Epicondylitis (Tennis Elbow) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Pfizer
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Novartis
- 18.4 Merck & Co
- 18.5 GlaxoSmithKline
- 18.6 Zimmer Biomet
- 18.7 Ossur Corporate
- 18.8 Pharmascience
- 18.9 MedStar Health
- 18.10 ReLiva Physiotherapy & Rehab
- 18.11 Scandinavian Physiotherapy Center
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

