
Middle East & Africa Tahini Market Overview:
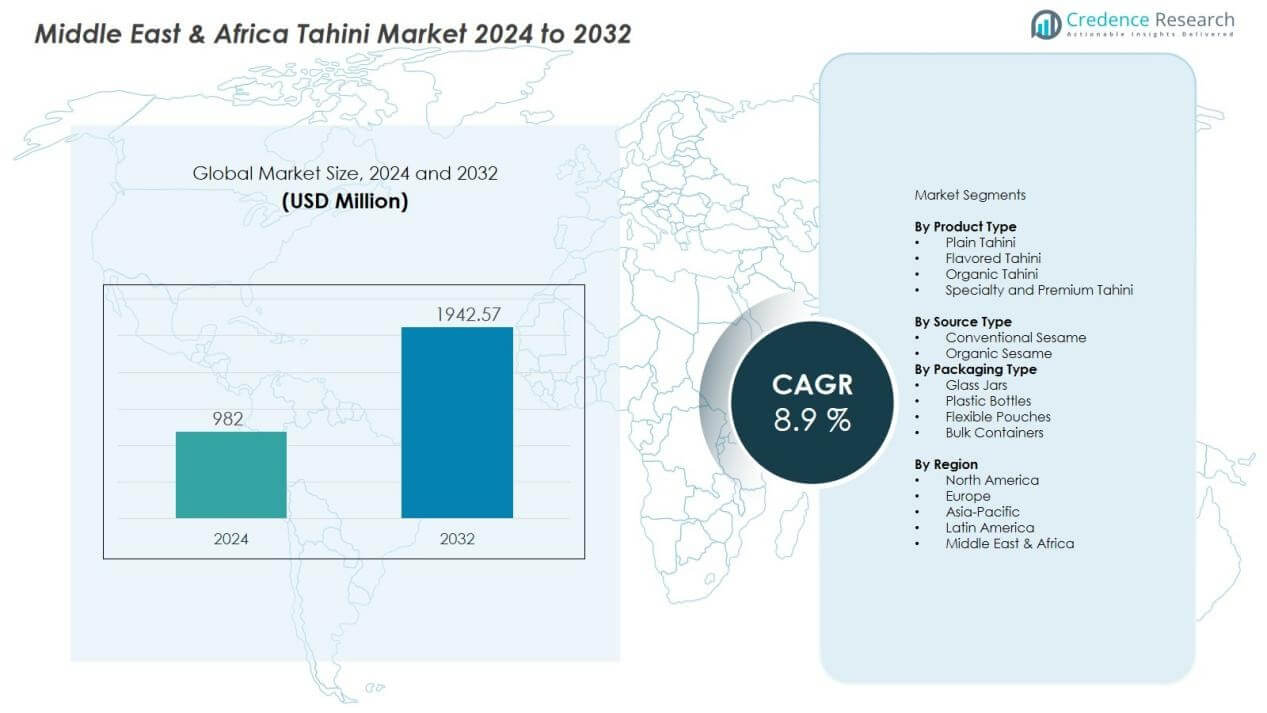
The Middle East & Africa Tahini Market size was valued at USD 982 million in 2024 and is anticipated to reach USD 1942.57 million by 2032, at a CAGR of 8.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Middle East & Africa Tahini Market Size 2024 | USD 982 million |
| Middle East & Africa Tahini Market, CAGR | 8.9% |
| Middle East & Africa Tahini Market Size 2032 | USD 1942.57 million |
Middle East & Africa Tahini Market Insights:
- The Middle East accounts for approximately 58% share, led by entrenched dietary usage and established processing capacity, North Africa holds around 27% share due to traditional cuisine and rising packaged food adoption, while Sub-Saharan Africa contributes nearly 15% share, driven by urbanization and expanding retail access.
- Sub-Saharan Africa represents the fastest-growing region with ~15% share, supported by dietary diversification, hospitality-driven cuisine exposure, modern retail expansion, and rising disposable income encouraging plant-based food adoption.
- By product type, Plain Tahini dominates with ~64% share due to widespread household and foodservice usage, while Flavored and Specialty Tahini collectively account for ~36%, supported by urban demand and premiumization trends.
- By packaging type, Glass jars hold ~52% share owing to retail preference and shelf appeal, followed by flexible pouches at ~28% for affordability, with bulk containers contributing ~20% through foodservice and institutional demand.
Middle East & Africa Tahini Market Drivers:
Strong Cultural Integration and Daily Culinary Usage
The Middle East & Africa Tahini Market benefits from deep cultural integration across traditional diets and household cooking practices. Tahini serves as a staple ingredient in widely consumed foods such as hummus, baba ghanoush, sauces, and bakery fillings. Regular household usage sustains consistent baseline demand throughout the year. Foodservice operators also rely on it for authentic menu offerings. This entrenched consumption pattern stabilizes volume growth and supports long-term demand continuity.
- For instance, Al Wadi Al Akhdar SAL, a leading Lebanese producer, employs traditional stone-grinding techniques to maintain authentic tahini flavor profiles, serving as a staple in hummus and baba ghanoush preparation.
Rising Preference for Natural and Nutrient-Dense Food Products
The Middle East & Africa Tahini Market gains momentum from growing consumer preference for clean-label and nutrient-rich food products. Tahini offers plant-based protein, healthy fats, and essential minerals, which align with dietary awareness trends. Health-focused consumers increasingly choose it over synthetic spreads and processed condiments. Retail brands emphasize purity and minimal processing to strengthen consumer trust. This shift reinforces premium positioning across modern retail formats.
- For Instance, Soom Foods produces a clean-label, single-ingredient tahini using premium White Humera sesame seeds sourced from Ethiopia, which are then processed at a specialized facility in Israel.
Expansion of Foodservice and Hospitality Infrastructure
The Middle East & Africa Tahini Market experiences demand growth from expanding foodservice, hospitality, and quick-service restaurant networks. Regional tourism growth increases exposure to traditional and fusion cuisines that rely on tahini-based formulations. Restaurants use it to maintain authenticity and consistency in high-volume operations. Centralized food preparation units also adopt it for scalable recipe execution. This channel supports bulk sales and stable institutional demand.
Regional Trade Development and Local Processing Investments
The Middle East & Africa Tahini Market benefits from investments in local sesame processing and value-added food manufacturing. Governments and private players support food security initiatives that strengthen domestic production capacity. Improved supply chains reduce dependency on imports and enhance price stability. Export-oriented producers leverage regional trade corridors to access adjacent markets. These structural improvements reinforce competitiveness and long-term market resilience.
Middle East & Africa Tahini Market Trends:
Product Premiumization Through Organic, Stone-Ground, and Specialty Variants
The Middle East & Africa Tahini Market shows a clear shift toward premium product positioning across retail and foodservice channels. Consumers favor organic, stone-ground, and single-origin sesame formulations that emphasize authenticity and quality. Brands respond by refining processing techniques to preserve flavor intensity and nutritional value. Packaging innovation supports this trend through glass jars, resealable lids, and bilingual labeling for export markets. Health-focused messaging highlights natural fats, protein content, and mineral composition. It also supports price differentiation in urban and high-income consumer segments. This trend strengthens brand loyalty and elevates category perception beyond commodity status.
- For Instance, Haitoglou Bros SA utilizes traditional stone-grinding mills to process premium Ethiopian and Sudanese sesame seeds.
Growing Penetration of Modern Retail and Digital Distribution Channels
The Middle East & Africa Tahini Market benefits from rapid expansion of supermarkets, hypermarkets, and online grocery platforms. Organized retail improves shelf visibility and encourages brand comparison across price tiers. E-commerce platforms allow manufacturers to reach diaspora communities and premium consumers with targeted offerings. Subscription-based grocery services increase repeat purchases for staple products such as tahini. It also enables direct-to-consumer branding strategies that reduce reliance on intermediaries. Data-driven promotions support demand forecasting and inventory optimization. This distribution evolution enhances accessibility and supports sustained volume growth across diverse regions.
- For Instance, Carrefour UAE, operated by Majid Al Futtaim, prioritized its core markets in Dubai and Abu Dhabi by enhancing its omnichannel presence and physical footprint.
Middle East & Africa Tahini Market Challenges Analysis:
Volatility in Sesame Seed Supply and Input Cost Pressures
The Middle East & Africa Tahini Market faces persistent challenges from fluctuations in sesame seed supply and raw material pricing. Climatic variability affects crop yields across key producing regions, which disrupts procurement planning. Import dependence in several countries exposes it to foreign exchange risk and freight cost shifts. Price instability compresses margins for small and mid-sized processors. Long-term contracts remain limited, which restricts cost predictability. It also complicates pricing strategies across retail and foodservice channels. These factors place continuous pressure on operational efficiency.
Quality Standardization and Market Fragmentation Constraints
The Middle East & Africa Tahini Market contends with inconsistent quality standards across fragmented regional supply chains. Small-scale producers often follow varied processing methods, which leads to texture and flavor variability. Regulatory enforcement differs widely across countries, creating compliance complexity for exporters. Brand trust weakens when quality inconsistency affects consumer experience. It also raises challenges for premium positioning in modern retail environments. Limited cold-chain and storage infrastructure further heightens spoilage risk. These constraints slow market consolidation and scalability.
Middle East & Africa Tahini Market Opportunities:
Expansion of Value-Added and Functional Tahini Product Lines
The Middle East & Africa Tahini Market presents strong opportunity through development of value-added and functional tahini variants. Manufacturers can introduce fortified options that support protein enrichment and micronutrient intake. Flavored formulations appeal to younger consumers and foodservice innovation. Clean-label positioning strengthens acceptance in health-focused retail segments. It allows brands to move beyond price-based competition. Premium SKUs improve margins and brand differentiation. This approach supports portfolio diversification across regional markets.
Untapped Export Potential and Regional Brand Positioning
The Middle East & Africa Tahini Market offers export opportunity through growing global demand for ethnic and plant-based foods. Producers can leverage regional authenticity to position premium brands in Europe and North America. Certification compliance enhances access to high-value markets. It also supports private-label manufacturing for international retailers. Trade agreements improve cross-border market entry efficiency. Scalable production facilities strengthen export readiness. These factors create long-term revenue expansion pathways.
Middle East & Africa Tahini Market Segmentation Analysis:
By Product Type
The Middle East & Africa Tahini Market shows clear differentiation by product type, with plain tahini holding the largest share due to its widespread use in traditional recipes and foodservice preparation. It supports consistent demand across households, restaurants, and institutional buyers. Flavored tahini variants gain traction in urban markets where consumers seek convenience and taste variety. Premium product lines focus on texture consistency and roast profile. This segmentation reflects evolving consumption preferences across income groups.
- For Instance, Al Wadi Al Akhdar SAL produces a traditional 100% plain tahini, specifically formulated as a versatile base for authentic Lebanese dishes like hummus and baba ghanoush.
By Source Type
The Middle East & Africa Tahini Market segments by source type into organic and conventional categories, with conventional tahini maintaining volume dominance due to price accessibility. It benefits from established sesame supply chains and broad retail penetration. Organic tahini records faster growth in health-conscious and export-oriented markets. Certification and traceability strengthen trust among premium buyers. This segment aligns with clean-label demand and wellness-focused purchasing behavior.
- For instance, Royal Tahini earns vegan and kosher certifications for its organic sesame paste sourced from African seeds, ensuring 100% plant-based composition with zero additives in every 200g jar.
By Packaging Type
The Middle East & Africa Tahini Market demonstrates varied demand across packaging formats such as jars, bottles, pouches, and bulk containers. It relies on jars for retail sales due to shelf appeal and product protection. Flexible pouches gain interest for affordability and portability. Bulk packaging supports foodservice and industrial users with cost efficiency. Packaging choice influences shelf life, logistics efficiency, and brand positioning across channels.
Segmentations:
By Product Type
- Plain Tahini
- Flavored Tahini
- Organic Tahini
- Specialty and Premium Tahini
By Source Type
- Conventional Sesame
- Organic Sesame
By Packaging Type
- Glass Jars
- Plastic Bottles
- Flexible Pouches
- Bulk Containers
By Region
- Middle East
- North Africa
- Sub-Saharan Africa
Regional Analysis:
Strong Consumption Base and Processing Capabilities Across the Middle East
The Middle East & Africa Tahini Market maintains a dominant share within the Middle East due to long-standing dietary integration and large-scale commercial usage. Countries such as Saudi Arabia, the United Arab Emirates, Israel, and Turkey sustain high per capita consumption through household cooking and foodservice demand. It benefits from established sesame processing infrastructure and experienced manufacturers. Modern retail penetration supports branded product visibility across urban centers. Export-oriented producers also leverage proximity to European and Asian trade routes. Demand stability supports both premium and mass-market segments. Cultural familiarity continues to anchor regional volume growth.
Expanding Demand and Local Production Strength in North Africa
The Middle East & Africa Tahini Market shows steady expansion across North African countries including Egypt, Morocco, and Tunisia. Traditional cuisine sustains baseline demand, while urbanization influences packaged and branded product adoption. It gains support from domestic sesame processing and growing food manufacturing capacity. Retail modernization enhances product accessibility beyond informal channels. Price sensitivity shapes purchasing behavior, which favors value-focused packaging formats. Public and private investment in agri-processing strengthens supply continuity. These factors support gradual yet consistent regional growth.
Emerging Consumption Patterns and Untapped Potential in Sub-Saharan Africa
The Middle East & Africa Tahini Market presents emerging opportunities across Sub-Saharan Africa driven by dietary diversification and urban population growth. Middle Eastern cuisine exposure through hospitality and migration increases awareness. It relies on imports in several countries, which raises the importance of efficient distribution networks. Modern retail expansion introduces tahini to new consumer segments. Foodservice adoption supports trial and repeat usage. Rising income levels encourage experimentation with plant-based spreads. This region offers long-term growth potential with improving market fundamentals.
Key Player Analysis:
- Al Wadi Al Akhdar (Lebanon)
- Halwani Bros. (Saudi Arabia)
- Kevala Inc. (US)
- SESAJAL S.S. de C.V. (Mexico)
- Prince Tahina Ltd. (Israel)
- Dipasa (US)
- El Rashidi El Mizan (Egypt)
- Carwari International Pty Ltd. (Australia)
- Mounir Bissat (Lebanon)
- Haitoglou Family Foods (Greece)
- Sunshine Foods (US)
- Ghandour Sons S.A.L (Lebanon)
Competitive Analysis:
The Middle East & Africa Tahini Market features a competitive structure shaped by a mix of regional manufacturers, family-owned processors, and export-focused brands. It shows moderate fragmentation, with local players holding strong positions through cultural familiarity and established distribution ties. Leading companies compete on product quality, roast profile consistency, and sourcing reliability. Brand reputation plays a critical role in retail and foodservice procurement decisions. Price competitiveness remains important in value-driven markets, while premium brands focus on organic certification and packaging differentiation. It also reflects increasing private-label activity from large retailers seeking margin control. Strategic investments target processing efficiency, shelf-life improvement, and export readiness. Partnerships with foodservice operators support volume stability. Competitive intensity continues to rise as modern retail expands and consumer expectations around quality and transparency strengthen.
Recent Developments:
- In October 2025, Grupo Sesajal S.S. de C.V. (Mexico) launched NUBAC, a new corporate umbrella brand consolidating its pet food portfolio including relaunched brands Shaggy, Grateful, and Felicat.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Source Type, Packaging Type and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The Middle East & Africa Tahini Market will experience steady demand supported by strong cultural relevance and consistent household consumption across core geographies.
- Producers will focus on quality consistency and roast standardization to strengthen brand trust across modern retail and foodservice channels.
- Premium and organic tahini variants will gain wider acceptance among health-aware urban consumers and export-oriented buyers.
- Manufacturers will invest in local sesame processing to improve supply security and reduce exposure to import volatility.
- Retail expansion will improve product visibility and encourage brand differentiation through packaging and shelf placement strategies.
- Foodservice growth will support bulk demand from restaurants, catering operators, and hospitality chains seeking authentic ingredients.
- Export activity will increase as regional brands leverage heritage positioning in international ethnic and plant-based food markets.
- Digital commerce adoption will support direct-to-consumer engagement and improve repeat purchase behavior for staple products.
- Sustainability practices will gain importance through responsible sourcing and waste-efficient processing methods.
- Market participants will prioritize operational efficiency and portfolio diversification to strengthen long-term competitiveness and resilience.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Strong Cultural Integration and Daily Culinary Usage
Tahini is deeply embedded in traditional diets and daily cooking practices across the Middle East and Africa, serving as a staple in dishes like hummus and baba ghanoush. This entrenched consumption ensures consistent baseline demand from both households and foodservice operators.
Rising Preference for Natural and Nutrient-Dense Food Products
Consumers are increasingly seeking clean-label, plant-based, and nutrient-rich foods, and tahini fits these preferences with its high protein, healthy fats, and essential minerals. This trend is driving premiumization and expanding tahini’s appeal beyond traditional markets.
Expansion of Foodservice and Hospitality Infrastructure
Growth in the foodservice, hospitality, and quick-service restaurant sectors is boosting demand for tahini as an authentic ingredient in both traditional and fusion cuisines. Bulk and institutional sales are rising as restaurants and catering services expand regionally.
Regional Trade Development and Local Processing Investments
Investments in local sesame processing and value-added manufacturing are strengthening domestic supply chains, reducing import dependency, and enhancing price stability. Improved infrastructure and trade corridors are enabling producers to access new markets and support export growth.
Product Premiumization and Packaging Innovation
There is a clear shift toward organic, stone-ground, and specialty tahini variants, supported by innovative packaging such as glass jars and resealable containers. This premiumization trend is attracting health-conscious and urban consumers, supporting higher margins and brand differentiation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the Middle East & Africa Tahini Market, and what is its projected value by 2032?
At what compound annual growth rate is the Middle East & Africa Tahini Market expected to grow during the forecast period?
Which product type segment holds the largest share in the Middle East & Africa Tahini Market?
What are the key factors driving growth in the Middle East & Africa Tahini Market?
Who are the leading players operating in the Middle East & Africa Tahini Market?
Which region accounted for the largest share of the Middle East & Africa Tahini Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Source Type
- 1.2.1 Conventional Sesame
- 1.2.2 Organic Sesame
- 1.3 By Product Type
- 1.3.1 Plain Tahini
- 1.3.2 Flavored Tahini
- 1.3.3 Organic Tahini
- 1.3.4 Specialty and Premium Tahini
- 1.4 By Packaging Type
- 1.4.1 Glass Jars
- 1.4.2 Plastic Bottles
- 1.4.3 Flexible Pouches
- 1.4.4 Bulk Containers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 982 million → 2032: USD 1,942.57 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Middle East & Africa Tahini Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Middle East & Africa Tahini Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Middle East & Africa Tahini Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Middle East & Africa Tahini Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Middle East & Africa Tahini Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Middle East & Africa Tahini Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Middle East & Africa Tahini Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Middle East & Africa Tahini Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 982 million → 2032: USD 1,942.57 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Middle East & Africa Tahini Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Source Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Conventional Sesame
- 12.3.7.2 Organic Sesame
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Plain Tahini
- 12.4.7.2 Flavored Tahini
- 12.4.7.3 Organic Tahini
- 12.4.7.4 Specialty and Premium Tahini
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Packaging Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Glass Jars
- 12.5.7.2 Plastic Bottles
- 12.5.7.3 Flexible Pouches
- 12.5.7.4 Bulk Containers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Middle East & Africa Tahini Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Middle East & Africa Tahini Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Middle East & Africa Tahini Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Al Wadi Al Akhdar
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Halwani Bros.
- 17.4 El Rashidi El Mizan
- 17.5 Prince Tahina Ltd.
- 17.6 Mounir Bissat
- 17.7 Ghandour Sons S.A.L
- 17.8 Haitoglou Family Foods
- 17.9 Kevala Inc.
- 17.10 SESAJAL S.S. de C.V.
- 17.11 Dipasa
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

