
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
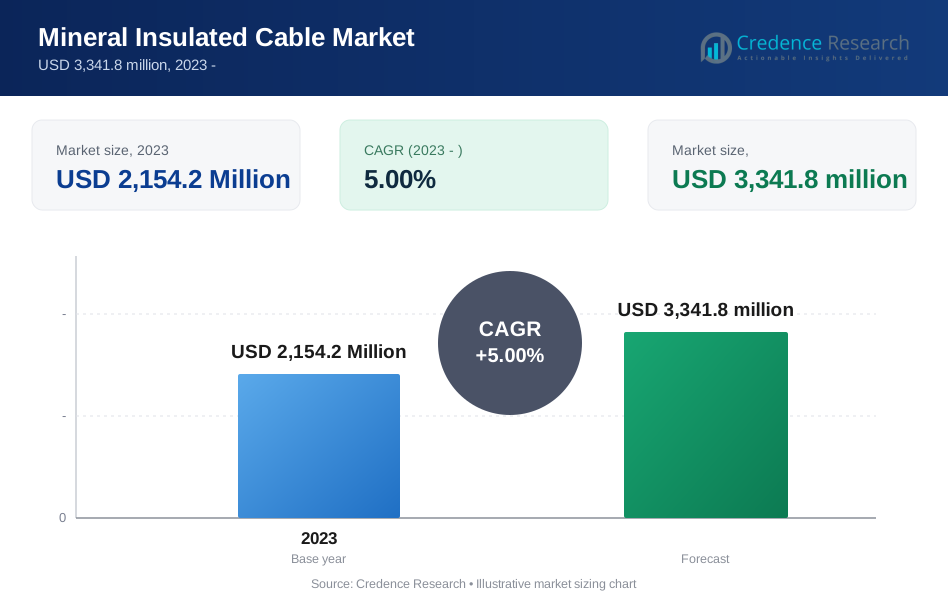
| Mineral Insulated Cables Market Size 2023 | USD 2,154.2 Million |
| Mineral Insulated Cables Market, CAGR | 5.00% |
| Mineral Insulated Cables Market Size 2032 | USD 3,341.8 Million |
Market Insights
- The global demand for Mineral Insulated Cables was valued at USD 2,154.2 Million in 2023 and is expected to reach USD 3,341.8 Million in 2032, growing at a CAGR of 5.00% between 2024 and 2032.
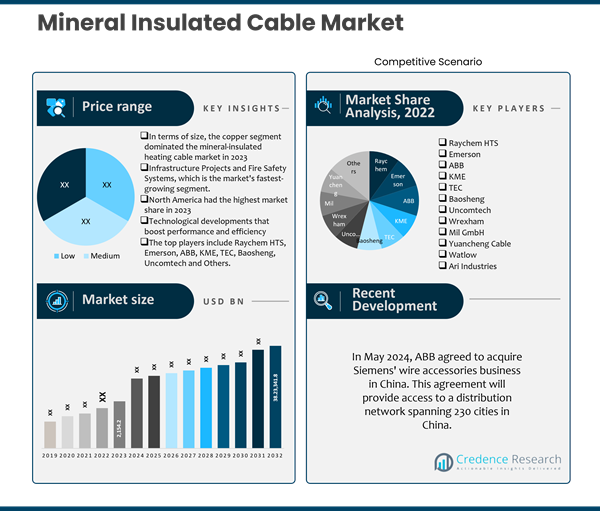
- In terms of size, the copper segment dominated the mineral-insulated heating cable market in 2023, while aluminum conductors hold the second biggest market share due to their widespread application in a range of sectors.
- Calcium silicate insulating material is the market's fastest-growing sector. Another major category is insulating materials, with magnesium oxide (MgO) being a popular choice.
- Multi-core cables are more common in the Mineral Insulated Cable Market. Another market leader is Fire Rated Cables.
- Medium Voltage (MV) Cables are the most common category in the Mineral Insulated Cable Market, while Low Voltage (LV) Cables are another important market share holder.
- The Mineral Insulated Cable Market is dominated by the Oil and Gas Industry, while Infrastructure Projects and Fire Safety Systems are the fastest-growing categories.
- The Mineral Insulated Cable Market is often dominated by utility companies, while oil and gas companies are frequently the market's fastest compound annual growth rate (CAGR) holders.
- In 2023, North America had the highest market share, accounting for 45% of total sales During the projected period, Asia-Pacific is expected to be the fastest-growing market, while Europe is another crucial area for mineral insulated heating cable market growth.
- Technological advancements fuel market expansion.
- High initial investment costs restrict market expansion.
Executive Summary
Market Definition
Mineral Insulated (MI) Cable is the most secure choice for power and heating (fire prevention and protection in industrial and civil applications), as well as electrical heat tracing (industrial and building operations). MI cable is made of copper sheath, two-conductor heating cable, and magnesium oxide insulation.
Market Overview
The global Mineral Insulated Cable market has witnessed steady growth in recent years and is expected to grow at a CAGR of 5.00% between 2024 and 2032. The market was valued at USD 2,154.2 million in 2023 and is expected to reach USD 3,341.8 million in 2032.
The Mineral Insulated Cable Market is growing due to a variety of causes. One significant driver is the growing demand for dependable and long-lasting wire solutions in industries like construction, energy, and manufacturing. Mineral insulated cables provide outstanding fire resistance, high-temperature tolerance, and excellent electrical performance, making them perfect for essential applications requiring safety and endurance. Furthermore, the increased emphasis on energy efficiency and infrastructural enhancements is accelerating the use of these cables.
However, the market confronts constraints such as higher beginning prices compared to standard cables, which may deter cost-conscious purchasers. Regulatory hurdles and a lack of awareness about the benefits of mineral-insulated cables in certain locations further impede market expansion.
Segmentation by Type of Conductor Material
- In terms of size, the copper segment dominated the mineral-insulated heating cable market in 2023. Copper-insulated heating cables have been used in a variety of applications, including commercial snow melting, commercial and residential floor heating, and electrical power generation and supply systems, among others, contributing to the expansion of the market for this category.
- Aluminum conductors have the second largest market share since they are widely used in a variety of sectors.
Segmentation by Insulation Materials
- Calcium Silicate insulating material is the market's fastest-growing sector, driven by its outstanding fire-resistant qualities and rising demand for improved safety measures in buildings and infrastructure projects.
- Another prominent category is insulating materials, with magnesium oxide (MgO) being a popular choice due to its excellent temperature resistance and longevity.
Segmentation by Cable Type
- Multi-Core Cables are more popular in the Mineral Insulated Cable Market due to their versatility and capacity to transfer numerous signals or power sources within a single cable.
- Another market leader is Fire Rated Cables, which are specifically engineered to sustain performance during fires, making them essential for safety-critical applications in buildings, transportation, and industrial environments.
Segmentation by Voltage Rating
- Medium Voltage (MV) Cables are the most popular category in the Mineral Insulated Cable Market because they are widely used in a variety of industrial applications that require moderate power transmission.
- Low Voltage (LV) Cables are another key market share holder, as they are often used in residential, commercial, and light industrial settings for low power distribution demands.
Segmentation by Application
- The Oil and Gas Industry dominates the Mineral Insulated Cable Market due to its widespread usage of cables for drilling operations, refineries, and pipelines.
- Another prominent category is Infrastructure Projects, in which mineral-insulated cables are used to power and connect diverse constructions such as buildings, bridges, and highways.
- Fire Safety Systems are the market's fastest-growing category, driven by an increased emphasis on fire prevention and safety measures in buildings and industrial facilities.
Segmentation by End User
- Utility companies typically have the largest proportion of the Mineral Insulated Cable Market. They frequently require a large number of cables for power distribution and transmission, which contributes to their huge market position.
- Oil and gas companies are often the market's fastest Compound Annual Growth Rate (CAGR) holders. This sector is expanding rapidly due to the ongoing demand for cables in numerous applications within the oil and gas industry, such as drilling operations, refineries, and pipelines.
Segmentation by Region
- In 2023, North America had the largest market share, accounting for 45% of total sales.
- During the projected period, Asia-Pacific is likely to be the fastest-growing market, while Europe is another critical sector for mineral insulated heating cable market growth.
- The rest of the world, including Latin America, the Middle East, and Africa, supplies the remaining demand for Mineral Insulated Cable.
In 2023, North America had the biggest market share, with 45% of total market revenue. It is one of the most advanced regions in terms of mineral-insulated heating cable use. Mineral insulated heating cables are becoming increasingly popular in North America because to the booming oil and gas industry and emerging power transmission projects.
Moreover, during the projected period, Asia-Pacific is expected to be the fastest-growing market for mineral-insulated heating cables. Mineral-insulated heating cables are gaining popularity in the Asia Pacific as smart grid investments, power generation capacity, and transmission and distribution infrastructure investments rise. Mineral-insulated heating cable manufacturers in the region are focused on establishing significant prospects in a wide range of industries.
During the projection period, Europe is another crucial area for mineral insulated heating cable market growth. The growing oil and gas and pharmaceutical industries in Europe are pushing rising demand for mineral-insulated cables.
Key Highlights of the Report
The global Mineral Insulated Cable market is segmented by Type of Conductor Material, Insulation Materials, Cable Type, Voltage Rating, Application, End User, price range, and region. The Oil and Gas Industry controls the Mineral Insulated Cable Market, whereas the copper segment dominated the mineral-insulated heating cable market in 2023. Furthermore, Calcium Silicate insulating material is the market's fastest-growing segment. Furthermore, oil and gas firms are frequently the market's quickest compound annual growth rate (CAGR) holders. Another market leader is Fire Rated Cables, with North America leading the market growth.
The market's primary drivers are stringent fire safety regulations, increased industrialization and infrastructure development, and a focus on safety and risk mitigation. Furthermore, the market's main restraints are the high initial cost, limited flexibility, and complex installation process. Aldo, growing demand from emerging economies, expansion in high-risk industries, and advancements in insulation materials are significant opportunities in the market.
Nonetheless, In 2023, North America had the largest market share. It is one of the most advanced places in terms of using mineral-insulated heating cables. Furthermore, during the forecast period, Asia-Pacific is likely to be the fastest-growing market for mineral-insulated heating cables. Mineral-insulated heating cables are becoming more prevalent in Asia Pacific as smart grid, power generation, and transmission and distribution infrastructure investments increase. Furthermore, Europe is a key market for mineral-insulated heating cables. The burgeoning oil, gas, and pharmaceutical industries in Europe are driving up demand for mineral-insulated cables.
What Are The Main Drivers Of The Global Mineral Insulated Cable Market?
The Mineral Insulated Cable Market is being pushed by factors such as rising demand for fire-resistant wiring solutions, a greater emphasis on energy efficiency, and the expansion of industries such as construction and manufacturing.
What Are The Major Challenges Faced By The Global Mineral Insulated Cable Market?
The market faces challenges due to higher initial costs compared to traditional cables, regulatory hurdles, and limited awareness in certain regions.
What Are The Growth Opportunities In The Global Mineral Insulated Cable Market?
Despite these limitations, there are chances for the industry to prosper, including as adoption in essential applications for safety and lifespan, infrastructure upgrades that drive cable demand, and the possibility of market expansion through focused awareness campaigns.
Market Drivers
Technological Advancements
One of the most important factors driving the growth of the Mineral Insulated Cable Market is technological advancement. Innovative cable design, material, and production processes have resulted in high-performance mineral-insulated cables with improved safety, durability, and efficiency. Mineral-insulated cables have become more widely used in a variety of industries, including power generation, oil and gas, and infrastructure building. These cables, which can withstand high temperatures and are fire resistant, enable reliable power transmission; as a result, their demand has expanded significantly in critical situations where safety and performance are paramount. The mineral-insulated cable market is expected to rise in tandem with technology, which shows no indications of slowing down due to ongoing innovation in the field of cable technology.
Market Restraints
High Initial Investment Costs
One of the primary problems limiting the mineral-insulated cable market's growth is high upfront investment expenditures. Mineral insulated cables, along with their manufacturing methods, are more expensive than traditional forms of cables accessible in the worldwide marketplace. This cost element can drive away potential consumers, particularly from companies or projects with limited budgetary resources. Furthermore, installing mineral-insulated cables necessitates the use of specialized tools and experience, raising the project's overall cost. Thus, this high barrier-to-entry expenditure, seen as the initial impediment to adopting mineral-insulated cables, allows the product to grab less market shares, particularly in businesses where every decision is based on cost.
Opportunities
Increasing Focus on Safety and Reliability
The growing focus on safety and reliability across industries is creating opportunities in the mineral-insulated cable market. Mineral insulated cables have very high fire resistance and can resist extreme conditions, thus having a major application in critical applications where safety matters the most. It is expected that demand for inherently safe and durable cables like mineral-insulated cables will rise in the future, given the tight regulations and standards that ensure tight safety in industries such as oil and gas, transportation, and infrastructure.
In addition, as companies become more concerned with uninterrupted power supply and operational continuity, the capacity of mineral-insulated cables to perform under adverse conditions is a critical solution. The market can expand in this area by meeting the growing need for high-quality and dependable cables that offer safety, dependability, and long-term cost-effectiveness for industrial applications.
Competitive Landscape
Key Players
The global Mineral Insulated Cable market is highly competitive, with several key players. Some of the major players in the market and their market share are as follows:
- Raychem HTS
- Emerson
- ABB
- KME
- TEC
- Baosheng
- Uncomtech
- Wrexham
- Mil GmbH
- Yuancheng Cable
- Watlow
- Ari Industries
- Chromalox
- MiCable Technologies
- Eltherm
- Hanhe Cable
- OMEGA
- Conax Technologies
- Others
These organizations prioritize product innovation, distribution channel expansion, and mergers and acquisitions to stay competitive.
The global Mineral Insulated Cable market's key players continually seek to stay ahead by offering new products and developments.
In April 2020, Larsen & Toubro (L&T) said that it had obtained large contracts to modernize power transmission and distribution networks in several countries, including India. The company intends to integrate additional overhead and subsurface cables to improve load bifurcation and system dependability.
In February 2019, Emerson announced to acquisition of industry major General Electric's Intelligent Platforms division. The new connection will allow the company to expand its product lines to industrial customers more effectively.
How Companies are Performing in the Mineral Insulated Cable Market?
Companies' performance in the mineral-insulated cable market is solid, with a mix of established businesses and creative start-ups entering the field. Other recent developments are improving the manufacturing process in order to attain the efficiency and quality of products that customers expect. Sustainability is quickly gaining traction, with businesses committing to minimizing their carbon footprint through eco-friendly manufacturing methods and products. Start-ups introduce new ideas and technologies into the marketplace, stimulating competency and hence innovation. To address the rising demand for trustworthy and environmentally friendly wire solutions, the wiring industry as a whole is moving toward more sustainable operations through higher technological adoption.
Summary of Key Findings
- The primary market potential is an increased focus on safety and reliability.
- Market segmented by Type of Conductor Material, Insulation Materials, Cable Type, Voltage Rating, Application, End User, and region.
- The Mineral Insulated Cable Market is dominated by Medium Voltage (MV) Cables
- Multi-core cables are more common in the Mineral Insulated Cable Market
- North America is leading market growth; the market is highly competitive with key players including Raychem HTS, Emerson, ABB, KME, TEC, Baosheng, Uncomtech and Others.
Future Outlook
- Demand for dependable and long-lasting wiring solutions continues to drive expansion.
- Technological developments that boost performance and efficiency.
- Growth into new applications and sectors.
- More emphasis on safety and fire-resistant solutions.
- Global infrastructure development is increasing market potential.
How CXOs Can Benefit from the Credence Research Mineral Insulated Cable Market Report
The Credence Research Mineral Insulated Cable Market Report provides CXOs with a comprehensive overview of the market, including:
- Market size and growth forecast:The report provides detailed estimates of the global Mineral Insulated Cable market size, segmented by Type of Conductor Material, Insulation Material, Cable Type, Voltage Rating, Application, End User, and region. It also includes forecasts for the market through 2032 based on key trends and drivers.
- Market segmentation:The report segments the Mineral Insulated Cable market by Type of Conductor Material, Insulation Material, Cable Type, Voltage Rating, Application, End User, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive Landscape:The report profiles the key players in the Mineral Insulated Cable market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers:The report identifies and analyzes the key trends and drivers that are shaping the Mineral Insulated Cable market. This information can help CXOs to make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research Mineral Insulated Cable Market Report to:
- Identify growth opportunities:The report can help CXOs identify new growth opportunities in the Mineral Insulated Cable market. For example, by highlighting the potential for market expansion in emerging industries such as renewable energy.
- Make informed investment decisions:The report can help CXOs to make informed investment decisions about Mineral Insulated Cable. For example, the report may analyze the current market demand for mineral-insulated cables in various industries and regions, offering CXOs valuable data to assess the market potential and opportunities for investment.
- Develop competitive strategies:The report can help CXOs to develop competitive strategies for their Mineral Insulated Cable businesses. For example, the report might provide a comprehensive overview of the key players in the market, their product offerings, pricing strategies, and market share
- Track market developments:The report can help CXOs track market developments and stay ahead of the curve. For example, the report provides insights into the latest trends and innovations in the Mineral Insulated Cable market.
Overall, the Credence Research Mineral Insulated Cable Market Report is a valuable resource for CXOs who are looking to gain a deeper understanding of the market and identify opportunities for growth.
Segmentation
Type of Conductor Material:
- Copper Conductors
- Aluminum Conductors
-
Insulation Material:
- Magnesium Oxide (MgO)
- Calcium Silicate
-
Cable Type:
- Single Core Cables
- Multi-Core Cables
- Fire Rated Cables
-
Voltage Rating:
- Low Voltage (LV) Cables
- Medium Voltage (MV) Cables
- High Voltage (HV) Cables
-
Application:
- Power Generation
- Oil and Gas Industry
- Chemical and Process Industries
- Fire Safety Systems
- Transportation
- Infrastructure Projects
-
End User:
- Industrial Sector
- Commercial Sector
- Utility Companies
- Oil and Gas Companies
-
By Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- North America
Adjacent Markets
In the Mineral Insulated Cable market, there are several adjacent markets which has high revenue growth opportunities. The key adjacent markets for Mineral Insulated Cable market -
Adjacent Markets |
||
| Fiber Optic Cable Market | Instrumentation Cable Market | Coaxial Cable Market |
| Power Cable Market | Heating Cable Market | Submarine Cable Market |
| Control Cable Market | Communication Cable Market | Building Wire Market |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Fire Safety Regulations
Increasingly strict fire safety codes and regulations in industrial, commercial, and infrastructure sectors are driving the adoption of mineral insulated cables due to their superior fire resistance and reliability in critical applications.
Expansion of Oil & Gas and Infrastructure Projects
The growth of oil and gas exploration, refining, and pipeline projects, along with large-scale infrastructure development, is fueling demand for mineral insulated cables, which are valued for their durability and ability to withstand harsh environments.
Technological Advancements in Cable Design
Innovations in cable materials and manufacturing processes have enhanced the performance, efficiency, and safety of mineral insulated cables, making them more attractive for high-risk and demanding applications.
Rising Focus on Operational Safety and Reliability
Industries are increasingly prioritizing uninterrupted power supply and operational continuity, leading to higher adoption of mineral insulated cables that offer exceptional reliability and longevity even under extreme conditions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global Mineral Insulated Cable market?
What is the expected growth rate of the Mineral Insulated Cable market between 2024 and 2032?
Which segment is leading the market share in terms of Type of Conductor Material?
Which Cable Type segment governs the demand for Mineral Insulated Cables in the world?
Which End User segment is expected to post the highest CAGR during the forecast period?
Which region is fueling the growth of the Mineral Insulated Cable industry?
Who are the major players in the global Mineral Insulated Cable market?
What are the major market drivers of the Mineral Insulated Cable industry?
What are the major market restraints of the Mineral Insulated Cable industry?
What are the major market opportunities of the Mineral Insulated Cable industry?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Cable Type
- 1.2.1 Single Core Cables
- 1.2.2 Multi-Core Cables
- 1.2.3 Fire Rated Cables
- 1.3 By Application
- 1.3.1 Oil and Gas Industry
- 1.3.2 Infrastructure Projects
- 1.3.3 Fire Safety Systems
- 1.3.4 Power Generation
- 1.3.5 Chemical and Process Industries
- 1.3.6 Transportation
- 1.4 By Conductor Material
- 1.4.1 Copper Conductors
- 1.4.2 Aluminum Conductors
- 1.5 By Insulation Material
- 1.5.1 Magnesium Oxide (MgO)
- 1.5.2 Calcium Silicate
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 2,154.2 Million → 2032: USD 3,341.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Mineral Insulated Cable Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Mineral Insulated Cable Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Mineral Insulated Cable Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Mineral Insulated Cable Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Mineral Insulated Cable Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Mineral Insulated Cable Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Mineral Insulated Cable Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Mineral Insulated Cable Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 2,154.2 Million → 2032: USD 3,341.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Mineral Insulated Cable Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Cable Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Single Core Cables
- 12.3.7.2 Multi-Core Cables
- 12.3.7.3 Fire Rated Cables
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oil and Gas Industry
- 12.4.7.2 Infrastructure Projects
- 12.4.7.3 Fire Safety Systems
- 12.4.7.4 Power Generation
- 12.4.7.5 Chemical and Process Industries
- 12.4.7.6 Transportation
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Conductor Material - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Copper Conductors
- 12.5.7.2 Aluminum Conductors
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Insulation Material - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Magnesium Oxide (MgO)
- 12.6.7.2 Calcium Silicate
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Mineral Insulated Cable End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Mineral Insulated Cable Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Mineral Insulated Cable Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Mineral Insulated Cable Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Raychem HTS
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Emerson
- 18.4 ABB
- 18.5 KME
- 18.6 TEC
- 18.7 Baosheng
- 18.8 Uncomtech
- 18.9 Wrexham
- 18.10 Mil GmbH
- 18.11 Chromalox
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

