
Market Overview
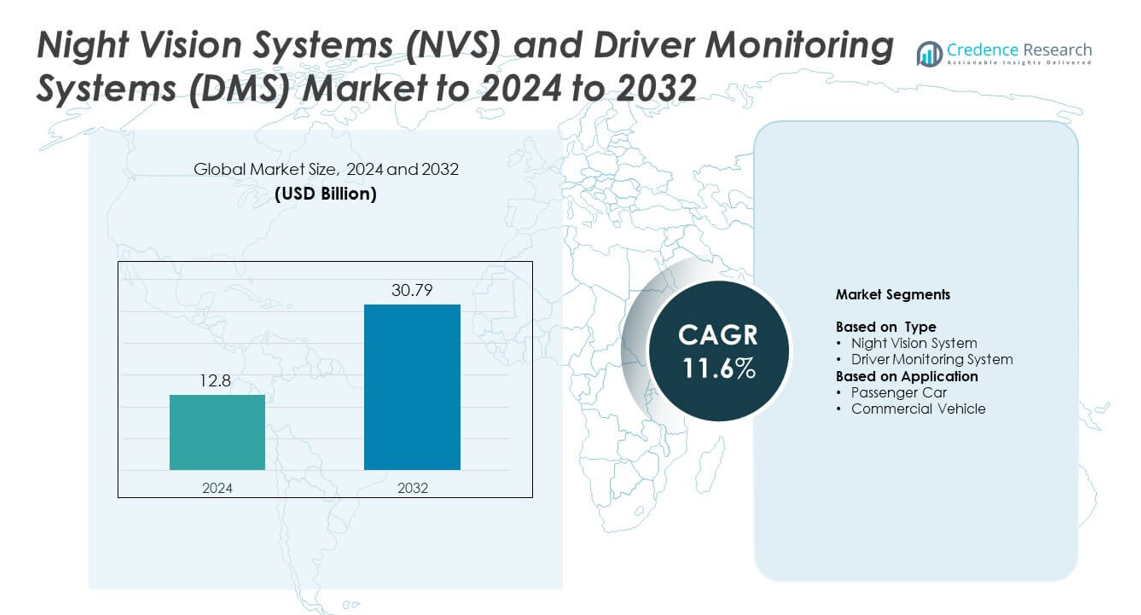
Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market size was valued at USD 12.8 billion in 2024 and is anticipated to reach USD 30.79 billion by 2032, at a CAGR of 11.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market Size 2024 | USD 12.8 billion |
| Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market, CAGR | 11.6% |
| Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market Size 2032 | USD 30.79 billion |
The Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market is shaped by major players including Aisin Seiki, Continental, OMRON, Autoliv, Magna International, Smart Eye AB, Valeo, Robert Bosch, Denso, and Delphi Automotive. These companies advance thermal imaging, infrared cameras, and AI-driven driver-attention technologies to support rising safety requirements and automation features. North America led the market in 2024 with about 36% share, driven by strong ADAS adoption and strict regulations. Europe followed with nearly 29% share, supported by NCAP mandates, while Asia Pacific held about 27% share due to rapid expansion of smart-vehicle production.
Market Insights
- The Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market was valued at USD 12.8 billion in 2024 and is projected to reach USD 30.79 billion by 2032 at a CAGR of 11.6%.
- Rising safety regulations and mandatory driver-attention features drive strong adoption across passenger cars, which held a 71% share in 2024.
- Thermal imaging, AI-driven monitoring, and sensor-fusion upgrades shape current trends as automakers enhance night-time visibility and distraction detection.
- Leading players compete through advanced infrared cameras, in-cabin sensing platforms, and ADAS integration to expand adoption in both premium and mid-range vehicles.
- North America led the market with 36% share in 2024, followed by Europe at 29% and Asia Pacific at 27%, while the driver monitoring system segment dominated by type with 58% share.
Market Segmentation Analysis:
By Type
The Driver Monitoring System segment held the dominant share in 2024 with about 58% of the Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market. Demand grew as automakers integrated real-time eye-tracking and fatigue-detection features to meet rising safety mandates in Europe, China, and North America. Carmakers used DMS to reduce distraction-related crashes and support Level-2 and Level-3 automated driving functions. Adoption increased due to regulatory pressure from NCAP programs and wider deployment in mid-range vehicles, while Night Vision Systems expanded steadily through improved infrared sensors and stronger performance in low-light driving.
- For instance, Seeing Machines reported its driver monitoring technology installed in over 2.2 million vehicles by the end of FY2024, showing growing DMS penetration in series-production cars.
By Application
Passenger cars dominated the application segment in 2024 with nearly 71% share. Growth came from rising installation of DMS and NVS in mass-market and premium models as safety standards tightened worldwide. Demand increased as buyers valued features that reduce human-error accidents and enhance night-time visibility. Carmakers introduced these systems to support ADAS upgrades and boost safety ratings, which encouraged rapid deployment across new vehicle platforms. Commercial vehicles adopted these systems at a slower pace but gained traction through fleet safety programs and regulatory focus on fatigue-related incidents.
- For instance, Smart Eye stated that its driver monitoring system software was already included in more than 3,000,000 cars on the road, backed by a total of 366 design wins from 23 global automakers, including brands like GM, BMW, Porsche, and Volvo. The company's technology is embedded in 365 production car models.
Key Growth Drivers
Rising Safety Regulations and Mandates
Global safety agencies increased pressure on automakers to adopt advanced monitoring and vision technologies. NCAP programs in Europe, China, and the U.S. pushed DMS and NVS integration to reduce distraction-related and low-visibility accidents. Carmakers responded by adding mandatory driver-attention features and nighttime detection tools across new models. These rules accelerated adoption in both premium and mid-range segments, strengthening demand throughout 2024.
- For instance, Valeo disclosed that it has produced more than 1.5 billion driving-assistance sensors over roughly 30 years, reflecting sustained investment to meet tightening active-safety and ADAS regulations.
Expansion of ADAS and Semi-Autonomous Driving
Automakers relied on NVS and DMS to support Level-2 and Level-3 automation. These systems improved lane-keeping accuracy, driver handover processes, and overall system reliability in poor lighting or complex traffic. Growing deployment of ADAS packages in mass-market vehicles encouraged higher installation rates. Strong benefits in accident prevention and smoother automation performance made this a core adoption driver across most regions.
- For instance, Mobileye reported that its solutions had been installed in approximately 190 million vehicles across roughly 1,200 vehicle models worldwide as of the end of 2024, underscoring its role in supporting ADAS and higher automation levels.
Growing Consumer Focus on Safety and Comfort
Buyers demanded vehicles with real-time fatigue alerts, distraction warnings, and better night-time visibility. Rising awareness of road fatalities increased interest in active safety technologies that detect micro-sleep or unseen hazards. Carmakers marketed these features as premium value additions, boosting adoption in luxury and mid-range cars. Expanding urban traffic density also encouraged users to choose vehicles equipped with supportive driver-assistance tools.
Key Trends & Opportunities
Integration of AI-Driven In-Cabin Monitoring
AI models enabled deeper analysis of driver behavior, including gaze direction, drowsiness patterns, and head position. Automakers used these insights to build smarter, predictive safety responses. This shift opened opportunities for software-driven upgrades and cloud-connected safety platforms. Growing interest in continuous monitoring for ridesharing and fleet services strengthened adoption across commercial use cases.
- For instance, Qualcomm stated that more than 350 million vehicles on the road use Snapdragon Digital Chassis solutions, which provide the compute platform for advanced cockpit, connectivity, and driver-assistance features.
Thermal Imaging and Sensor Fusion Expansion
Manufacturers improved NVS by combining thermal cameras with infrared and radar sensors. This fusion enhanced detection of pedestrians, animals, and obstacles in low-visibility areas, creating a strong opportunity for premium and autonomous vehicles. The trend accelerated as falling sensor costs made high-performance night-vision systems more accessible. This created new prospects for deployment in mainstream passenger cars.
- For instance, Teledyne FLIR reports that its thermal sensors for automotive night-vision systems have been deployed in more than 1.2 million vehicles, enhancing detection in dark and low-visibility conditions.
Adoption of Cabin Interaction and Personalization Features
Carmakers explored DMS as part of wider in-cabin experience design. Systems supported gesture control, mood detection, and personalized settings tied to driver identity. These upgrades created new opportunities for user-centric vehicle design and integration with infotainment systems. Growth in connected vehicles further pushed demand for multi-function camera platforms.
Key Challenges
High System Cost and Integration Complexity
NVS and DMS required advanced sensors, thermal cameras, and processing units, which raised development and installation costs. Automakers struggled to balance performance with affordability, slowing adoption in low-cost vehicles. Integration with ADAS platforms also demanded significant calibration and testing. These technical barriers limited broader penetration in emerging markets.
Privacy Concerns and Regulatory Constraints
Driver monitoring raised concerns about in-cabin data collection and facial recognition. Buyers questioned how automakers stored and used behavioral information. Inconsistent global privacy laws added compliance challenges, especially in regions with strict data-protection rules. These concerns created hesitation among some consumers and required stronger data-governance frameworks to support market expansion.
Regional Analysis
North America
North America led the Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market in 2024 with about 36% share. Strong adoption came from strict safety rules, rapid integration of ADAS, and a high share of premium vehicles that already use advanced monitoring features. Automakers deployed NVS and DMS widely to meet regulatory expectations and improve crash-prevention scores. Growth also increased as large fleets adopted monitoring tools to reduce fatigue-related incidents. Expanding autonomous driving programs in the U.S. created further demand for enhanced night-vision and in-cabin behaviour tracking technologies.
Europe
Europe held nearly 29% share in 2024, supported by strong NCAP requirements and early adoption of in-cabin monitoring systems. Countries prioritised technologies that reduce distraction, drowsiness, and nighttime collision risks. Carmakers used NVS and DMS to meet upcoming safety mandates linked to the General Safety Regulation. Premium brands expanded deployment in both combustion and EV models. Continued growth of semi-autonomous driving features and rising interest in sensor fusion supported broader integration across new vehicle platforms in key markets such as Germany, France, and the United Kingdom.
Asia Pacific
Asia Pacific accounted for about 27% share in 2024 and showed the fastest growth as China, Japan, and South Korea expanded ADAS and smart-vehicle programs. Rising production of mid-range cars boosted adoption of DMS features, driven by new safety scoring systems in China. Carmakers integrated NVS to improve low-visibility driving in dense urban and rural regions. Domestic manufacturers increased the use of AI-based monitoring to remain competitive with global brands. Strong EV production and government support for advanced safety technology helped accelerate overall market expansion in the region.
Latin America
Latin America captured nearly 5% share in 2024, with adoption growing steadily as awareness of road safety improved. Deployment remained higher in premium and imported vehicles where NVS and DMS were added as part of advanced safety packages. Fleet operators showed rising interest in monitoring systems to reduce fatigue-related accidents, especially in commercial transport. Limited affordability and lower regulatory pressure slowed wider adoption, but improving safety norms in countries such as Brazil and Mexico supported gradual market expansion across new models.
Middle East and Africa
The Middle East and Africa region held around 3% share in 2024, reflecting early-stage adoption focused mainly on luxury vehicles and high-end SUVs. Growth came from rising demand for technologies that enhance night-time visibility in low-light desert conditions. Premium car buyers valued advanced monitoring features that improve comfort and reduce driver fatigue on long routes. Broader market penetration remained slow due to high system costs and limited regulatory requirements. However, expanding vehicle imports and improving safety awareness supported steady interest in NVS and DMS technologies.
Market Segmentations:
By Type
- Night Vision System
- Driver Monitoring System
By Application
- Passenger Car
- Commercial Vehicle
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market is shaped by leading players such as Aisin Seiki, Continental, OMRON, Autoliv, Magna International, Smart Eye AB, Valeo, Robert Bosch, Denso, and Delphi Automotive. The market features strong competition driven by rapid advancements in AI-powered monitoring, thermal imaging, and multi-sensor fusion platforms. Companies focus on improving real-time driver behaviour detection, enhancing night-time visibility, and supporting Level-2 and Level-3 autonomous functions. Many manufacturers invest in software algorithms, infrared cameras, and in-cabin sensing modules to strengthen product performance. Strategic partnerships with automakers accelerate integration into new vehicle platforms, while rising regulatory pressure boosts demand for compliant safety technologies. Continuous innovation in cost-optimized sensors supports expansion into mid-range passenger cars and commercial fleets.
Key Player Analysis
- Aisin Seiki
- Continental
- OMRON
- Autoliv
- Magna International
- Smart Eye AB
- Valeo
- Robert Bosch
- Denso
- Delphi Automotive
Recent Developments
- In 2024, Robert Bosch GmbH Partnered with companies like drivebuddyAI to advance its AI-powered ADAS and DMS platforms.
- In 2024, Valeo S.A. and Teledyne FLIR announced a strategic collaboration to integrate and deliver thermal imaging technology for automotive safety systems.
- In 2023, Smart Eye AB Launched a new Driver Monitoring System (DMS) metric in June to further improve road safety and driver health.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see wider adoption as safety rules tighten across major regions.
- Automakers will integrate more AI-based driver behaviour analytics for deeper insights.
- Sensor fusion combining thermal, infrared, and radar will enhance night-time detection accuracy.
- Mass-market vehicles will increasingly adopt DMS features previously limited to premium models.
- Semi-autonomous driving growth will boost demand for reliable in-cabin monitoring systems.
- Fleet and commercial operators will expand use of monitoring tools to reduce fatigue-related risks.
- Carmakers will add multi-function in-cabin systems that support personalization and interaction.
- Falling sensor costs will make advanced NVS technology more accessible to mid-range vehicles.
- Privacy and data-governance frameworks will influence the pace of DMS adoption in key markets.
- Partnerships between automakers and AI software firms will accelerate feature development and deployment.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Safety Regulations and Mandates
Global safety agencies and NCAP programs in Europe, China, and the U.S. are enforcing stricter requirements for advanced driver monitoring and night vision systems, compelling automakers to integrate these technologies to reduce distraction-related and low-visibility accidents.
Expansion of ADAS and Semi-Autonomous Driving
Automakers are increasingly relying on NVS and DMS to support Level-2 and Level-3 automation, improving lane-keeping, driver handover, and system reliability in challenging conditions, which drives higher installation rates across new vehicle models.
Growing Consumer Focus on Safety and Comfort
Consumers are demanding vehicles equipped with real-time fatigue alerts, distraction warnings, and enhanced night-time visibility, prompting automakers to offer these features as standard or premium options to boost safety ratings and market appeal.
Integration of AI-Driven In-Cabin Monitoring
Advancements in AI enable deeper analysis of driver behavior, such as gaze direction and drowsiness, allowing automakers to deliver smarter, predictive safety responses and opening new opportunities for software-driven upgrades and connected safety platforms.
Thermal Imaging and Sensor Fusion Expansion
Manufacturers are enhancing night vision systems by combining thermal cameras with infrared and radar sensors, improving detection of pedestrians and obstacles in low-visibility conditions and making these technologies more accessible as sensor costs decline.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market projected to grow between 2025 and 2032?
Which Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market?
Who are the leading companies in the Night Vision Systems (NVS) and Driver Monitoring Systems (DMS) Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Night Vision System
- 1.2.2 Driver Monitoring System
- 1.3 By Application
- 1.3.1 Passenger Car
- 1.3.2 Commercial Vehicle
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12.8 billion → 2032: USD 30.79 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Night Vision Systems (NVS) And Driver Monitoring Systems (DMS) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Night Vision Systems (NVS) And Driver Monitoring Systems (DMS) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Night Vision Systems (NVS) And Driver Monitoring Systems (DMS) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Night Vision Systems (NVS) And Driver Monitoring Systems (DMS) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Night Vision Systems (NVS) And Driver Monitoring Systems (DMS) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Night Vision Systems (NVS) And Driver Monitoring Systems (DMS) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Night Vision Systems (NVS) And Driver Monitoring Systems (DMS) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Night Vision Systems (NVS) And Driver Monitoring Systems (DMS) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12.8 billion → 2032: USD 30.79 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Night Vision Systems (NVS) And Driver Monitoring Systems (DMS) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Night Vision System
- 12.3.7.2 Driver Monitoring System
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Passenger Car
- 12.4.7.2 Commercial Vehicle
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Night Vision Systems (NVS) And Driver Monitoring Systems (DMS) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Night Vision Systems (NVS) And Driver Monitoring Systems (DMS) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Night Vision Systems (NVS) And Driver Monitoring Systems (DMS) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Night Vision Systems (NVS) And Driver Monitoring Systems (DMS) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Aisin Seiki
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Continental
- 18.4 OMRON
- 18.5 Autoliv
- 18.6 Magna International
- 18.7 Smart Eye AB
- 18.8 Valeo
- 18.9 Robert Bosch
- 18.10 Denso
- 18.11 Delphi Automotive
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

