
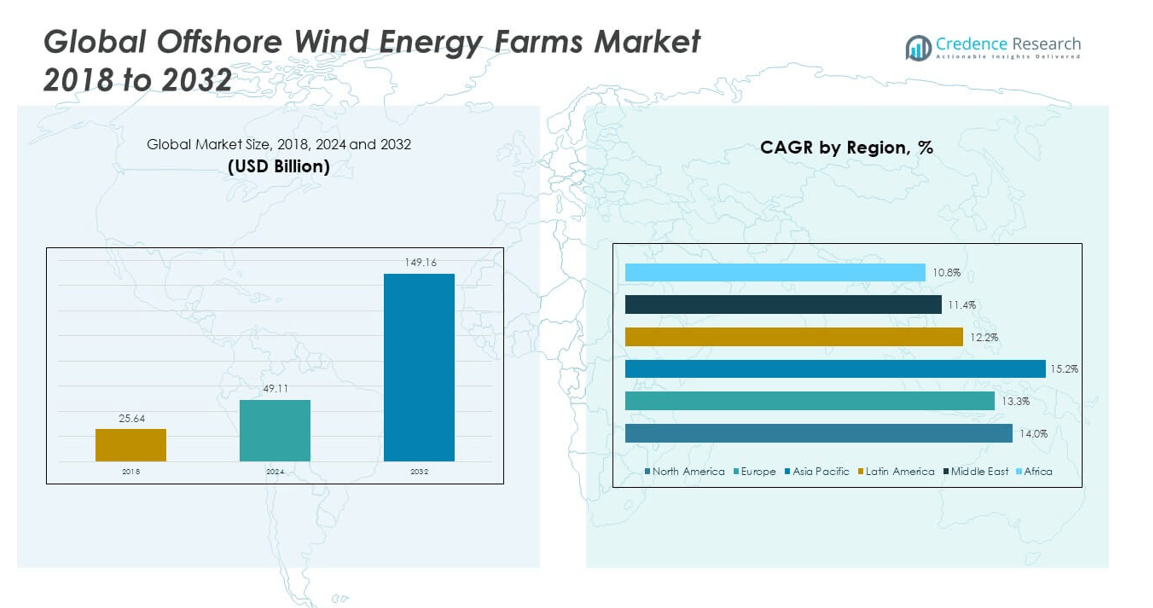
The Global Offshore Wind Energy Farms Market size was valued at USD 25.64 million in 2018 to USD 49.11 million in 2024 and is anticipated to reach USD 149.16 million by 2032, at a CAGR of 13.88% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Offshore Wind Energy Farms Market Size 2024 | USD 49.11 million |
| Offshore Wind Energy Farms Market, CAGR | 13.88% |
| Offshore Wind Energy Farms Market Size 2032 | USD 149.16 million |
The market is experiencing robust growth driven by increasing global efforts to transition toward renewable energy, rising investments in clean power infrastructure, and government incentives supporting offshore wind development. Advancements in turbine technology, floating platforms, and grid integration are further enhancing efficiency, lowering costs, and expanding deployment feasibility in deeper waters. Additionally, growing energy demand and carbon neutrality goals are accelerating offshore wind adoption as a sustainable alternative to fossil fuels.
Regionally, Europe remains the leader in offshore wind deployment due to early adoption, strong policy frameworks, and large-scale projects across the UK, Germany, and the Netherlands. Asia-Pacific is emerging rapidly, with China, South Korea, and Taiwan making significant investments to boost capacity and reduce dependence on conventional energy. North America is also gaining traction, particularly in the U.S., where favorable policies and coastal project approvals are fostering new opportunities, making the region an important contributor to the market’s future growth.
Market Insights:
- The Global Offshore Wind Energy Farms Market was valued at USD 49.11 billion in 2024 and is projected to reach USD 149.16 billion by 2032, growing at a CAGR of 13.88%.
- Europe held the largest regional share in 2024 with 40.0%, supported by advanced policy frameworks and large-scale offshore projects.
- Asia Pacific accounted for 32.2% share in 2024, led by China, Japan, and South Korea expanding offshore capacity.
- North America contributed 20.1% share in 2024, driven by strong U.S. projects and Canadian initiatives.
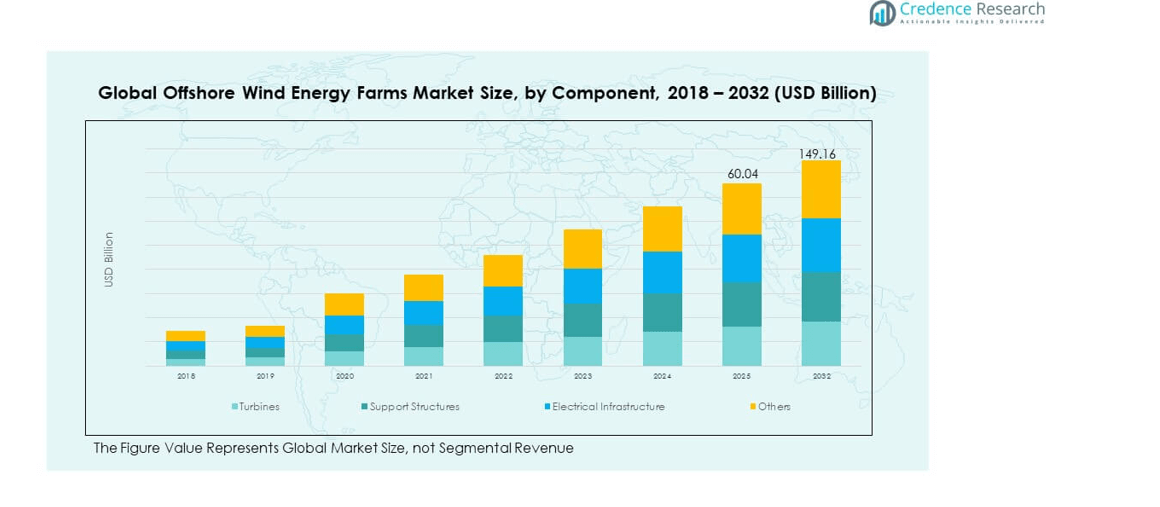
- By component, turbines dominated the market in 2024 with ~40% share, followed by support structures at ~25%, electrical infrastructure at ~20%, and others at ~15%.
Market Drivers:
Growing Energy Transition Toward Renewable Sources
The Global Offshore Wind Energy Farms Market benefits from the accelerating global shift toward renewable energy solutions. Governments in leading economies set ambitious carbon neutrality targets, pushing utilities and developers to expand offshore projects. It supports energy security by reducing reliance on fossil fuel imports and diversifying supply. Policies mandating renewable adoption strengthen investor confidence and create a stable project pipeline. Rising global demand for electricity in urbanized and industrialized regions enhances the need for offshore capacity. Technological advances improve efficiency, enabling cost-competitive electricity generation. Corporations also commit to green procurement, supporting large-scale project viability. The market leverages strong policy frameworks and sustainability commitments to ensure consistent growth.
- For instance, Ørsted commissioned the Hornsea 2 project in the UK with a capacity of 1.3 GW, making it the world’s largest operational offshore wind farm delivering power to over 1.4 million homes.
Technological Advancements Enhancing Project Viability
The Global Offshore Wind Energy Farms Market gains momentum through innovations in turbine capacity, floating platforms, and smart grid integration. Larger turbines now generate higher power output, reducing per-unit costs and lowering maintenance cycles. Floating platforms extend project feasibility into deep-water regions previously inaccessible. Grid integration solutions stabilize intermittent supply and enhance distribution efficiency. It achieves greater scalability by incorporating digital monitoring systems for predictive maintenance. Enhanced construction techniques reduce installation time, improving project economics. Research investments accelerate deployment efficiency and cost competitiveness. The market secures long-term growth by embedding innovation into every project stage.
- For example, Siemens Gamesa introduced its SG 14-236 DD offshore wind turbine with a 236-meter rotor diameter and 14 MW nominal capacity, scalable up to 15 MW with Power Boost.
Rising Public and Private Investments in Offshore Wind Projects
The Global Offshore Wind Energy Farms Market expands steadily with significant financial commitments from public authorities and private investors. Governments allocate funding for infrastructure, port facilities, and grid extensions. Private equity firms, utilities, and energy companies increase capital flow toward large-scale developments. Financial incentives, including tax credits and feed-in tariffs, improve project attractiveness. It attracts institutional investors who seek stable, long-term returns from renewable assets. Global energy companies diversify portfolios by prioritizing offshore projects. International financing institutions provide loans and grants to emerging markets, enabling broader participation. Strong investment flows accelerate construction activity and capacity expansion worldwide.
Rising Environmental Concerns and Sustainability Commitments
The Global Offshore Wind Energy Farms Market experiences strong demand due to the urgency of addressing climate change. Societal pressure and environmental policies push governments to invest heavily in low-carbon energy. Companies adopt sustainability goals, sourcing renewable electricity to reduce carbon footprints. It supports cleaner air quality and reduces greenhouse gas emissions from traditional power generation. Offshore farms deliver high energy yields without occupying land space. Environmental benefits encourage governments to fast-track project approvals. Growing public awareness drives acceptance of offshore wind as a vital energy source. The market reinforces global decarbonization strategies while expanding its role in energy transition.
Market Trends:
Expansion of Floating Offshore Wind Technologies
The Global Offshore Wind Energy Farms Market sees rapid adoption of floating platforms to unlock deep-water potential. Conventional fixed-bottom turbines limit installation to shallow regions, leaving vast offshore areas untapped. Floating systems extend feasibility to deeper waters, increasing geographic reach of projects. It enables countries with narrow continental shelves to benefit from offshore capacity. Deployment of hybrid floating solutions integrates solar arrays, strengthening overall renewable output. Floating wind farms reduce environmental impacts by minimizing seabed disturbance. Rising collaborations between technology developers and utilities accelerate commercialization. The trend expands scalability and reshapes the offshore wind project landscape.
- For instance, Equinor successfully deployed its Hywind Scotland floating wind farm with five turbines generating a total of 30 MW, demonstrating world-leading operational efficiency in over 100 meters of water depth.
Digitalization and Smart Infrastructure in Offshore Projects
The Global Offshore Wind Energy Farms Market incorporates digital platforms to optimize operations and maintenance. Artificial intelligence improves predictive maintenance by detecting early turbine faults. IoT-based systems enhance real-time monitoring and efficiency control. It supports data-driven strategies for reducing downtime and improving performance. Digital twin technology allows simulation of turbine performance under varying conditions. Integration of advanced analytics minimizes costs and improves output quality. Cloud-based management platforms simplify large-scale farm coordination. The trend demonstrates the shift toward smart, technology-driven project management in offshore wind operations.
Growing Corporate Demand for Renewable Power Procurement
The Global Offshore Wind Energy Farms Market experiences rising demand from corporate buyers seeking renewable electricity. Multinational companies commit to sustainability through power purchase agreements with offshore developers. It helps corporations meet emissions reduction targets while ensuring stable energy supply. Energy-intensive industries prioritize offshore procurement to reduce carbon dependency. Green certification programs promote renewable sourcing across corporate supply chains. Developers secure long-term contracts, strengthening financial stability of projects. Corporate procurement increases global offshore demand beyond public policy mandates. The trend underscores the growing private-sector role in advancing offshore wind adoption.
Integration of Hybrid Renewable Energy Systems
The Global Offshore Wind Energy Farms Market embraces hybrid energy projects combining offshore wind with other renewables. Integration with floating solar platforms and hydrogen production facilities enhances system value. It improves energy storage and distribution efficiency across coastal grids. Hybrid projects reduce reliance on standalone technologies by diversifying generation sources. Offshore hydrogen hubs supported by wind farms enable future clean fuel applications. Hybrid models attract investment by lowering intermittency risks. Governments promote hybrid projects to optimize renewable infrastructure usage. The trend establishes offshore wind as a cornerstone of multi-resource energy ecosystems.
- For instance, RWE launched the AquaVentus initiative at Heligoland to combine 10 GW of offshore wind with green hydrogen production by 2035, supporting large-scale hybrid energy deployment.
Market Challenges Analysis:
High Costs and Capital Intensity of Offshore Projects
The Global Offshore Wind Energy Farms Market faces persistent challenges linked to high upfront costs and capital requirements. Offshore installations demand significant investments in turbine procurement, transmission infrastructure, and specialized vessels. It increases financial risks for developers and requires long-term planning. Limited access to financing in emerging markets further slows expansion. Currency fluctuations and rising material prices create additional financial pressures. Maintenance costs escalate due to harsh offshore conditions. Delays in grid connectivity also raise project expenses. The market must address financing constraints to ensure cost efficiency and competitive growth.
Environmental Concerns and Regulatory Complexities
The Global Offshore Wind Energy Farms Market navigates environmental and regulatory challenges that influence project timelines. Concerns over marine biodiversity, fishing activities, and seabed disruption complicate approval processes. It requires extensive environmental impact assessments before project execution. Regulatory differences across countries delay cross-border developments. Public opposition occasionally hinders coastal project acceptance. Grid integration faces bureaucratic hurdles, leading to extended lead times. Marine spatial planning further complicates siting decisions. Developers must balance environmental responsibilities with energy demand. The market needs clearer regulations to streamline offshore wind expansion.
Market Opportunities:
Expanding Potential in Emerging Offshore Wind Regions
The Global Offshore Wind Energy Farms Market holds promising opportunities in emerging economies across Asia-Pacific, Latin America, and Africa. Governments in these regions introduce favorable policies to diversify energy supply. It attracts global developers and technology providers to invest in coastal projects. Growing industrial demand drives interest in renewable electricity generation. International collaborations enhance financing availability and knowledge transfer. Offshore farms in these markets expand energy access while reducing dependency on fossil fuels. The market leverages supportive reforms to unlock new growth corridors.
Rising Role of Offshore Wind in Green Hydrogen Production
The Global Offshore Wind Energy Farms Market creates opportunities through integration with green hydrogen initiatives. Offshore farms provide renewable electricity for electrolyzers, enabling large-scale hydrogen output. It positions offshore wind as a vital enabler of future clean fuel supply chains. Hydrogen production diversifies revenue streams for offshore developers. Governments support hydrogen hubs near coastal regions to accelerate adoption. Growing global demand for hydrogen in transport and industry enhances offshore project importance. The market develops synergies that extend its role beyond power generation.
Market Segmentation Analysis:
The Global Offshore Wind Energy Farms Market demonstrates strong diversification across components, applications, and end users.
By component, turbines hold the dominant share, driven by rapid advancements in blade design and capacity expansion. Support structures play a crucial role in ensuring stability and are gaining demand with the rise of floating offshore platforms. Electrical infrastructure, including cables and substations, enables seamless grid integration and is essential for scaling capacity. The category of others, which includes monitoring systems and auxiliary equipment, provides complementary value by improving operational efficiency and reliability.
- For example, GE Vernova’s Haliade-X offshore wind turbine, featuring 107-meter blades, was first deployed in pilot operations in the Netherlands. The 12 MW variant of the Haliade-X is capable of generating enough renewable electricity to power around 16,000 European households annually, setting a benchmark in offshore wind technology.
By application, utility-scale power generation accounts for the largest market share, reflecting global demand for large offshore projects that deliver significant capacity to national grids. Hybrid projects are gaining momentum, integrating offshore wind with solar and storage solutions to stabilize supply. Offshore hydrogen production emerges as a high-potential segment, leveraging renewable electricity for green hydrogen generation to support future clean fuel ecosystems.
- For instance, China’s State Power Investment Corporation (SPIC) launched the world’s first commercial pilot integrating offshore wind with floating solar in Haiyang, Shandong Province. The project combines a wind turbine with two floating solar arrays totaling 0.5 MWp, showcasing hybrid offshore renewable generation on a pilot scale.
By end user, independent power producers dominate project development, supported by strong private investment and partnerships. Utility companies remain key adopters, expanding renewable portfolios to meet regulatory mandates and consumer demand. Government and public sector utilities contribute significantly in regions with state-driven initiatives, ensuring reliable energy transition pathways. Together, these segments highlight the diverse and evolving landscape of offshore wind.
Segmentation:
By Component
- Turbines
- Support Structures
- Electrical Infrastructure
- Others
By Application
- Utility-scale Power Generation
- Hybrid Projects
- Offshore Hydrogen Production
By End User
- Independent Power Producers
- Utility Companies
- Government and Public Sector Utilities
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Offshore Wind Energy Farms Market size was valued at USD 5.24 million in 2018 to USD 9.81 million in 2024 and is anticipated to reach USD 29.96 million by 2032, at a CAGR of 14.0% during the forecast period. North America accounts for 20.1% share of the global market. The Global Offshore Wind Energy Farms Market in this region benefits from favorable policies in the United States and Canada. It gains momentum through government-backed auctions, tax credits, and infrastructure investments. The U.S. leads regional development with projects concentrated along the Atlantic coast, while offshore initiatives in the Great Lakes and Pacific coastlines are expanding. It strengthens its supply chain with increased domestic manufacturing and specialized vessels. Developers form alliances with global players to accelerate project timelines. Canadian coastal regions invest in offshore projects to diversify energy supply. Mexico shows emerging interest, supported by renewable integration policies. The region enhances its renewable profile with strong regulatory and financial frameworks.
Europe
The Europe Global Offshore Wind Energy Farms Market size was valued at USD 10.90 million in 2018 to USD 20.38 million in 2024 and is anticipated to reach USD 59.51 million by 2032, at a CAGR of 13.3% during the forecast period. Europe holds 40.0% share of the global market. The Global Offshore Wind Energy Farms Market in this region is the global leader, driven by advanced policy frameworks and large-scale capacity expansion. It is anchored by the U.K., Germany, and the Netherlands, which account for a majority of installed offshore capacity. France, Spain, and Italy are scaling up projects, leveraging strong coastal resources. It benefits from EU-wide commitments toward net-zero targets, ensuring long-term policy support. Technological innovation in floating wind strengthens feasibility in deep-water zones. Regional supply chains are mature, with leading OEMs headquartered in Europe. Investment from both public and private sectors supports continuous growth. The region remains the innovation hub for offshore wind globally.
Asia Pacific
The Asia Pacific Global Offshore Wind Energy Farms Market size was valued at USD 7.14 million in 2018 to USD 14.47 million in 2024 and is anticipated to reach USD 48.06 million by 2032, at a CAGR of 15.2% during the forecast period. Asia Pacific contributes 32.2% share of the global market. The Global Offshore Wind Energy Farms Market in this region expands rapidly with China leading global capacity additions. It witnesses large-scale installations supported by state policies and investments in technology. Japan and South Korea develop offshore wind to reduce dependency on imported fuels. India is entering the sector with ambitious capacity targets along coastal states. It benefits from strong industrial bases, lowering equipment costs. Taiwan becomes a regional hotspot for international developers. Australia and Southeast Asia explore offshore opportunities to meet clean energy targets. Regional expansion is driven by supportive reforms, growing demand, and accelerating industrialization.
Latin America
The Latin America Global Offshore Wind Energy Farms Market size was valued at USD 1.24 million in 2018 to USD 2.35 million in 2024 and is anticipated to reach USD 6.32 million by 2032, at a CAGR of 12.2% during the forecast period. Latin America represents 4.2% share of the global market. The Global Offshore Wind Energy Farms Market in this region remains nascent but shows significant promise. Brazil leads development with favorable offshore wind policies and abundant coastal resources. Argentina explores pilot projects to diversify renewable energy portfolios. It gains traction as governments attract foreign investors through reforms. Limited infrastructure and financing challenges slow large-scale deployment. Regional collaboration with international developers strengthens technical expertise. Mexico and Chile evaluate opportunities for offshore integration into national grids. The region demonstrates long-term potential for clean energy transformation.
Middle East
The Middle East Global Offshore Wind Energy Farms Market size was valued at USD 0.70 million in 2018 to USD 1.22 million in 2024 and is anticipated to reach USD 3.12 million by 2032, at a CAGR of 11.4% during the forecast period. The Middle East holds 2.1% share of the global market. The Global Offshore Wind Energy Farms Market in this region is still at an early stage of development. It benefits from ambitious diversification plans by Gulf countries seeking to reduce reliance on hydrocarbons. Coastal regions of Saudi Arabia and the UAE explore offshore projects to supplement solar investments. Israel invests in renewable diversification strategies. It faces challenges due to high capital requirements and limited regional expertise. Turkey demonstrates stronger progress with offshore feasibility studies. Governments attract foreign partnerships to accelerate project development. The region builds momentum through policy reforms supporting clean energy transition.
Africa
The Africa Global Offshore Wind Energy Farms Market size was valued at USD 0.42 million in 2018 to USD 0.88 million in 2024 and is anticipated to reach USD 2.17 million by 2032, at a CAGR of 10.8% during the forecast period. Africa accounts for 1.5% share of the global market. The Global Offshore Wind Energy Farms Market in this region develops gradually with South Africa and Egypt as key frontrunners. It leverages vast coastal resources to strengthen energy security and reduce dependence on fossil fuels. Limited infrastructure and financing options hinder immediate large-scale expansion. International partnerships bring technical expertise and financial support to local markets. Governments launch initiatives to attract foreign investment in renewable energy. Coastal nations such as Morocco and Kenya evaluate offshore wind feasibility. It gains importance in regional electrification strategies. Africa demonstrates untapped long-term potential in global offshore wind expansion.
Key Player Analysis:
- Siemens Gamesa Renewable Energy
- Vestas Wind Systems
- General Electric (GE Renewable Energy)
- Nordex SE
- Goldwind
- ENESSERE
- IMPSA
- Furukawa Electric
- LS Cable & System
- Nexans
Competitive Analysis:
The Global Offshore Wind Energy Farms Market is characterized by intense competition among leading players such as Siemens Gamesa Renewable Energy, Vestas Wind Systems, GE Renewable Energy, Nordex SE, and Goldwind. It is shaped by continuous innovation in turbine capacity, floating platform development, and grid integration technologies. Companies expand their global presence through partnerships, mergers, and acquisitions to secure long-term contracts and enhance market share. European players dominate, supported by advanced supply chains and established regulatory frameworks, while Asian companies strengthen competitiveness with large-scale domestic projects. Investment in digital solutions and predictive maintenance improves efficiency and reduces operational costs. Firms also pursue sustainability initiatives to align with global decarbonization goals. The competitive landscape reflects strong commitments to research, infrastructure development, and regional expansion strategies
Recent Developments:
- In July 2025, Vestas Wind Systems secured a 527 MW order in the USA, including turbine delivery and a 5-year service agreement with commissioning scheduled for the fourth quarter of 2026. This contract represents a substantial expansion in Vestas' presence in the American wind energy market, supporting sustainable energy growth.
- In December 2024, bp and JERA Co., Inc. announced a partnership to combine their offshore wind businesses into a new standalone, equally-owned joint venture. This strategic alliance aims to create a top-tier global offshore wind company focused on growth in Europe, Japan, and other markets.
Market Concentration & Characteristics:
The Global Offshore Wind Energy Farms Market displays moderate to high concentration, with a few multinational companies holding significant shares in turbine manufacturing and project development. It is defined by high capital intensity, long project lifecycles, and reliance on regulatory support. Regional dominance is evident in Europe and Asia Pacific, where established supply chains and policy frameworks drive large-scale deployments. Smaller regional firms contribute through niche solutions in support structures, cabling, and engineering services. The market emphasizes innovation, collaboration, and sustainability to maintain competitiveness. It continues to attract new entrants through joint ventures and technology-driven partnerships. Strong government incentives and international financing support reinforce stability and long-term growth.
Report Coverage:
The research report offers an in-depth analysis based on Component, Application and End User, It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Offshore wind farms will expand into deeper waters with wider adoption of floating platforms.
- Turbine technology will advance with larger capacity models improving efficiency and reducing costs.
- Digitalization will drive predictive maintenance, lowering downtime and operational risks.
- Hybrid renewable projects will gain traction by integrating offshore wind with solar and hydrogen production.
- Policy support and government incentives will remain central to accelerating new project approvals.
- Supply chain localization will strengthen regional competitiveness and reduce reliance on imports.
- Corporate procurement agreements will increase, supporting long-term power purchase commitments.
- Investment flows from institutional and private players will intensify, ensuring financial stability for large projects.
- Emerging economies will accelerate offshore installations to diversify energy portfolios and reduce fossil fuel dependence.
- Sustainability targets and climate goals will reinforce offshore wind as a cornerstone of the global energy transition.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Energy Transition and Carbon Neutrality Goals
Ambitious government targets for carbon neutrality and renewable energy adoption are driving utilities and developers to invest heavily in offshore wind projects, supporting energy security and reducing reliance on fossil fuels.
Technological Advancements in Turbines and Floating Platforms
Innovations such as larger, more efficient turbines and the development of floating platforms are expanding the feasibility of offshore wind farms into deeper waters, lowering costs and improving project viability.
Rising Public and Private Investments
Significant financial commitments from governments, utilities, and private investors, including incentives like tax credits and feed-in tariffs, are accelerating the construction and expansion of offshore wind capacity worldwide.
Supportive Policy Frameworks and Regulatory Incentives
Strong policy support, including government-backed auctions, long-term power purchase agreements, and streamlined permitting processes, is fostering a stable pipeline of offshore wind projects, particularly in Europe and Asia Pacific.
Integration with Hybrid and Green Hydrogen Projects
The growing trend of integrating offshore wind with other renewables and green hydrogen production is diversifying revenue streams and enhancing the value proposition of offshore wind farms, attracting further investment and innovation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Offshore Wind Energy Farms Market, and what is its projected size in 2032?
Which Global Offshore Wind Energy Farms Market segment held the largest share in 2024?
Who are the leading companies in the Global Offshore Wind Energy Farms Market?
Which region commanded the largest share of the Global Offshore Wind Energy Farms Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Independent Power Producers
- 1.2.2 Utility Companies
- 1.2.3 Government and Public Sector Utilities
- 1.3 By Component
- 1.3.1 Turbines
- 1.3.2 Support Structures
- 1.3.3 Electrical Infrastructure
- 1.3.4 Others
- 1.4 By Application
- 1.4.1 Utility-scale Power Generation
- 1.4.2 Hybrid Projects
- 1.4.3 Offshore Hydrogen Production
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 49.11 million → 2032: USD 149.16 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Offshore Wind Energy Farms Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Offshore Wind Energy Farms Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Offshore Wind Energy Farms Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Offshore Wind Energy Farms Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Offshore Wind Energy Farms Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Offshore Wind Energy Farms Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Offshore Wind Energy Farms Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Offshore Wind Energy Farms Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 49.11 million → 2032: USD 149.16 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Offshore Wind Energy Farms Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Independent Power Producers
- 12.3.7.2 Utility Companies
- 12.3.7.3 Government and Public Sector Utilities
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Turbines
- 12.4.7.2 Support Structures
- 12.4.7.3 Electrical Infrastructure
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Utility-scale Power Generation
- 12.5.7.2 Hybrid Projects
- 12.5.7.3 Offshore Hydrogen Production
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Offshore Wind Energy Farms End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Offshore Wind Energy Farms Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Offshore Wind Energy Farms Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Offshore Wind Energy Farms Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Siemens Gamesa Renewable Energy
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Vestas Wind Systems
- 18.4 General Electric (GE Renewable Energy)
- 18.5 Nordex SE
- 18.6 Goldwind
- 18.7 ENESSERE
- 18.8 IMPSA
- 18.9 Furukawa Electric
- 18.10 LS Cable & System
- 18.11 Nexans
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

