
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Sulphur Recovery Technology Market Size 2023 | USD 1621.2 Million |
| Sulphur Recovery Technology Market, CAGR | 11.50% |
| Sulphur Recovery Technology Market Size 2032 | USD 4318.2 Million |
Market Insights
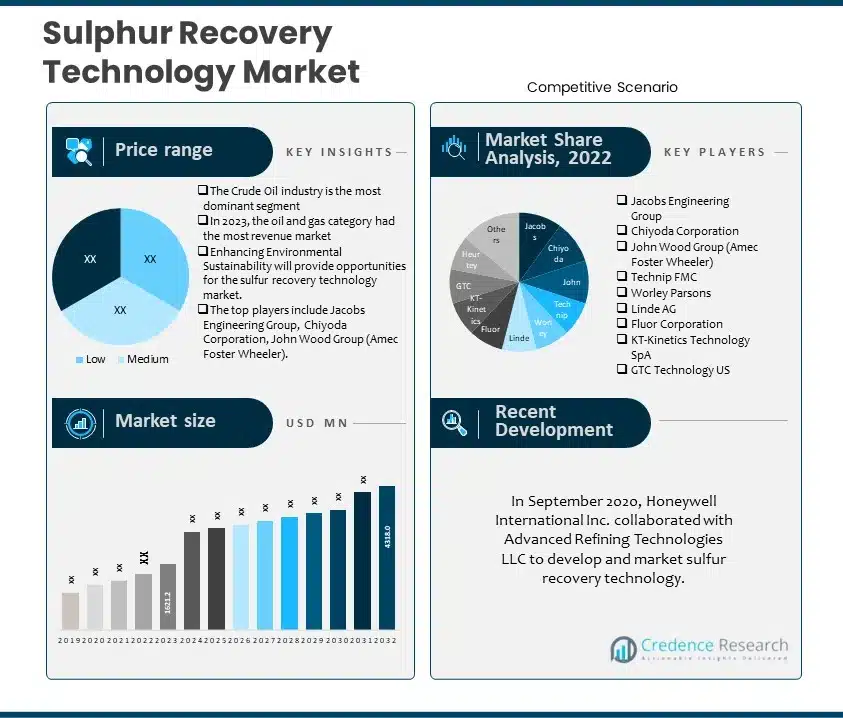
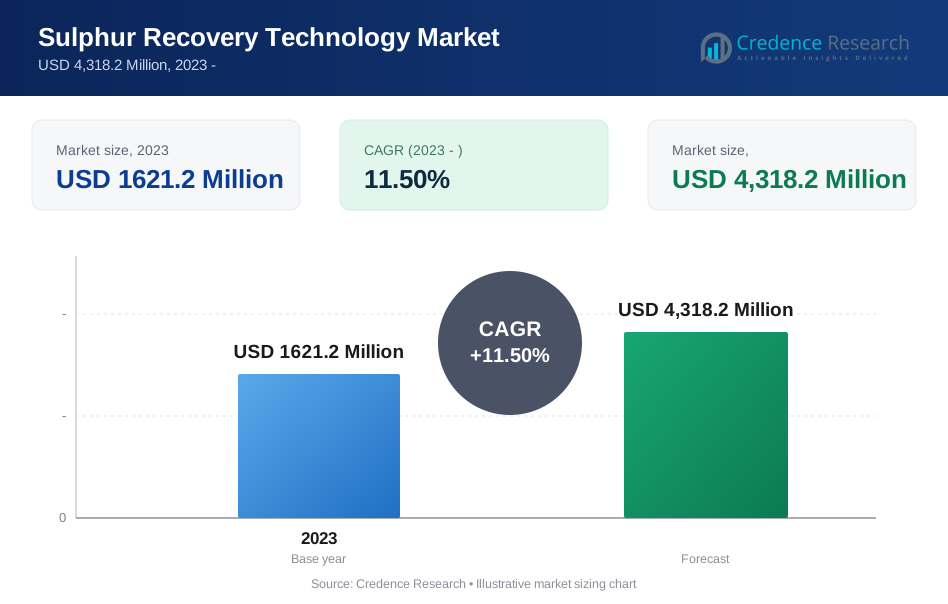
- The global demand for Sulphur Recovery Technology market was valued at USD 1621.2 Million in 2023 and is expected to reach USD 4318.2 Million in 2032, growing at a CAGR of 11.50% between 2024 and 2032.
- The Claus technology category is projected to dominate the market over the projection period, and the tail gas treatment sector is predicted to rise significantly throughout that time.
- In 2023, the oil and gas category had the largest revenue market share of all of these, and the Chemicals and Petrochemicals section is expected to rise significantly throughout the projected period.
- Crude oil is the most dominant segment of the sulfur recovery technology industry, while shale gas is the fastest-growing category.
- The market for sulfur recovery technology in the Asia Pacific area is expected to have the highest revenue share, while the markets in North America and Europe are expected to grow rapidly.
- The growing use of sulfur recovery technologies in emerging economies propels market expansion.
- High initial expenditures associated with the implementation of sulfur recovery plants impede industry growth.
Executive Summary
Market Definition
The Sulphur Recovery Technology Market is the industry that develops, manufactures, and implements technology for recovering sulfur from diverse sources, including natural gas processing, oil refining, and other industrial processes. These methods seek to reduce sulphur dioxide emissions, adhere to environmental standards, and maximize the recovery of valuable sulphur compounds.
Market Overview
The global Sulphur Recovery Technology Market has witnessed steady growth in recent years and is expected to grow at a CAGR of 11.50% between 2024 and 2032. The market was valued at USD 1621.2 million in 2023 and is expected to reach USD 4318.2 million in 2032.
The Sulphur Recovery Technology Market is expanding rapidly worldwide. With rising environmental laws and the need to reduce sulphur emissions, demand for sulphur recovery technologies is increasing. These technologies are critical in the oil and gas industry, as well as other industries that generate sulphur as a byproduct.
The market is being pushed by reasons such as increased demand for cleaner fuels, the need for effective sulphur recovery methods, and a growing awareness of environmental sustainability. The market provides a diverse range of technologies, including the Claus process, tail gas treatment units, and amine-based scrubbing systems, among others.
Segmentation by Technology Type
- The Claus technology category is likely to dominate the market over the forecast period. Claus technology converts hydrogen sulphide (H2S) to sulfur, a tried-and-true sulfur recovery method. Industries have paid particular attention to this technology because it can recover significant amounts of sulfur while reducing environmental pollution.
- The tail gas treatment sector is predicted to grow significantly throughout the forecast period. Sulfur from Claus plant tail gas that cannot be collected using the usual Claus process is recovered via tail gas treatment technology.
Segmentation by End User Industry
- In 2023, the oil and gas category had the most revenue market share of all of these. Sulfur recovery is an important stage in oil and gas refineries because it helps to eliminate potentially hazardous sulfur compounds from finished goods such as gasoline, diesel, and jet fuel.
- The Chemicals and Petrochemicals segment is predicted to grow significantly during the forecast period as demand for Sulfuric Acid rises in various industrial applications. Sulfuric acid is used to manufacture various chemicals, including pharmaceuticals, detergents, and fertilizers.
- During the projected period, the others section, which includes businesses such as mining and metal processing, is also likely to grow significantly.
Segmentation by Type of Feedstock
- The Crude Oil industry is the most dominant segment. Crude oil refining operations produce considerable amounts of sulfur-containing chemicals, hence sulfur recovery is critical in this business.
- Conversely, the Shale Gas sector is the fastest-growing category in the sulfur recovery technology industry.
Segmentation by Region
- The Asia Pacific region's sulfur recovery technology market is predicted to earn the most revenue share throughout the forecast period, accounting for 35.20% of the market.
- The market in North America and Europe is predicted to increase rapidly.
- The rest of the world, including Latin America, the Middle East, and Africa, supplies the remaining demand for Sulphur Recovery Technology.
The Asia Pacific region's sulfur recovery technology market is expected to earn the largest revenue share throughout the forecast period. The region's growing need for sulfur recovery technology is being driven mostly by expanding economies like as China and India, which are quickly industrializing and urbanizing. The presence of major oil and gas refineries in the area is also expected to stimulate demand for sulfur recovery technology. Furthermore, the region's implementation of stringent government regulations governing sulfur dioxide emissions, as well as an increased emphasis on sustainable development, are expected to promote market growth.
The North America market is expected to grow at a significant rate due to increased demand for sulfur recovery technologies in the oil and gas industry throughout the forecast period. The increasing shale gas production and refining activities in the United States, which is a major contributor to the market's rise in this region, are driving the demand for sulfur recovery technology. The region's plethora of producers of sulfur recovery technologies is also expected to drive market growth.
Moreover, the Europe market is expected to grow at a moderate rate during the forecast period due to the region's increasing emphasis on sustainable development and the implementation of rigorous government policies addressing sulfur dioxide emissions. The presence of big oil and gas refineries in the area is expected to stimulate demand for sulfur recovery technology. In addition, the demand for natural gas is rising.
Key Highlights of the Report
The global Sulphur Recovery Technology Market is segmented by Technology Type, End User Industry, Type of Feedstock, and region. In 2023, the oil and gas category had the largest revenue market share, while the Claus technology category and the crude oil industry are expected to lead the market. In addition, the tail gas treatment sector is expected to increase rapidly, while the Shale Gas sector is the fastest-growing segment in the sulfur recovery technology market, with Asia Pacific leading the market growth
The market's key drivers include increasing environmental regulations, rising demand for cleaner fuels, and growing awareness of environmental sustainability. Also, the industry's main challenges are high initial investment prices, the complexity of retrofitting existing facilities, and potential market saturation in industrialized countries. Additionally, the industry's important potential include expanding into new markets, technological advancements and innovation, and collaboration and partnerships for market growth..
The Asia Pacific region's sulfur recovery technology market is predicted to have the highest revenue share over the forecast period. The region's growing need for sulfur recovery technologies is fueled mostly by expanding economies like as China and India, which are rapidly industrializing and urbanizing. The presence of big oil and gas refineries in the vicinity is projected to drive up demand for sulfur recovery technology. Furthermore, the North American market is predicted to rise rapidly due to increased demand for sulfur recovery technologies in the oil and gas industry over the forecast period. Furthermore, the Europe market is predicted to increase at a moderate rate throughout the forecast period.
What Are The Main Drivers Of The Global Sulphur Recovery Technology Market?
Several factors drive the sulfur recovery technology market. There is a growing emphasis on environmental regulations that compel industry to limit sulfur emissions. Furthermore, there is an increasing demand for greener fuels, necessitating the use of effective sulphur recovery technologies. Furthermore, there is a growing awareness of environmental sustainability, leading firms to embrace technology that reduce their environmental impact.
What Are The Major Challenges Faced By The Global Sulphur Recovery Technology Market?
However, the market faces certain restraints. One of the main challenges is the high initial investment costs associated with implementing sulphur recovery technologies. Additionally, retrofitting existing facilities with these technologies can be complex and time-consuming.
What Are The Growth Opportunities In The Global Sulphur Recovery Technology Market?
Despite the restraints, the Sulphur Recovery Technology Market offers several opportunities. Emerging economies present a significant growth potential, as they undergo industrialization and increase their focus on environmental regulations. Technological advancements and innovation also open doors for more efficient and cost-effective sulphur recovery solutions. Moreover, collaboration and partnerships among industry players can drive market growth by fostering innovation and expanding the reach of these technologies.
Market Drivers
Several factors drive the global Sulphur Recovery Technology Market. The following are the key drivers of the global Sulphur Recovery Technology Market:
Rising Usage Of Sulfur Recovery Technology In Emerging Economies
The expanding adoption of technologies in emerging countries is a prominent trend driven by the region's industrialization and economic progress. Furthermore, when rising economies grow their industrial activity, there is an increase in the use of oil, natural gas, and other sulfur-containing commodities. Furthermore, the increase in industrial output demands sophisticated sulfur removal techniques in order to comply with severe environmental requirements and address growing concerns about air quality.
For instance, countries in the Asia-Pacific area, such as China and India, are experiencing fast industrial expansion, which is accompanied by an increase in energy demand. Furthermore, as these countries expand their oil refining and natural gas processing facilities, the demand for efficient sulfur recovery methods grows. Furthermore, the adoption of these technologies is motivated not just by regulatory requirements, but also by a proactive effort to reducing environmental effect and encouraging sustainable industrial practices. As a result, it is increasing the demand for sulfur recovery technologies. As a result, such factors are driving market expansion over the predicted period.
Market Restraints
The global Sulphur Recovery Technology Market faces some challenges that may hinder its growth. These include the following:
High Initial Costs Involved With The Deployment Of Sulfur Recovery Plants
Implementing sulfur recovery units and technologies requires significant upfront investments in equipment, engineering, and installation, making it a capital-intensive project. For instance, the cost of installing this unit in a refinery might range from several million to tens of millions of dollars, depending on the facility's size and complexity.
Furthermore, the installation of a new 100-ton-per-day sulfur recovery unit (SRU) with a sulfur recovery rate of 98.5% can cost between USD25 million and USD30 million. Additionally, the high initial expenditures are mostly due to the advanced equipment necessary for effective sulfur recovery, such as amine treating units, Claus units, and tail gas treatment units. Furthermore, the necessity for specialist technical skills to design and integrate these units into current industrial processes increases the overall cost. As a result, such factors impede market expansion throughout the predicted period.
Opportunities
The global Sulphur Recovery Technology Market offers significant growth opportunities. These include the following:
Enhancing Environmental Sustainability
In today's world, there is an increasing emphasis on environmental sustainability, and the Sulphur Recovery Technology Market offers a substantial chance to help achieve this goal. With growing worries about air pollution and the negative effects of sulphur emissions, there is a greater demand for effective sulphur recovery methods.
One significant opportunity in the Sulphur Recovery Technology Market is the ability to develop and execute improved technologies capable of efficiently capturing and converting sulphur emissions into valuable goods. This not only helps enterprises comply with severe environmental requirements, but it also provides an opportunity to turn a waste product into a valuable resource.
Companies that invest in research & development can innovate and develop more efficient and cost-effective sulfur recovery solutions. This can result in increased process efficiencies, lower energy usage, and less environmental impact. Furthermore, organizations that capitalize on this opportunity can gain a competitive advantage by providing sustainable solutions to sectors looking to lessen their environmental imprint.
Competitive Landscape
Key Players
The global Sulphur Recovery Technology Market is highly competitive, with several key players. Some of the major players in the market and their market share are as follows:
- Jacobs Engineering Group
- Chiyoda Corporation
- John Wood Group (Amec Foster Wheeler)
- Technip FMC
- Worley Parsons
- Linde AG
- Fluor Corporation
- KT-Kinetics Technology SpA
- GTC Technology US
- Heurtey Petrochem
- McDermott
- Sunway Petrochemical Engineering
These organizations prioritize product innovation, distribution channel expansion, and mergers and acquisitions to stay competitive.
The global Sulphur Recovery Technology Market's key players continually seek to stay ahead by offering new products and developments.
In June 2020, Shell and Saudi Aramco formed a joint venture to research and commercialize innovative sulfur recovery technology.
In August 2020, Honeywell International Inc. purchased Advanced Refining Solutions LLC, a producer of sulfur recovery solutions.
In July 2020, Shell and Saudi Aramco formed a cooperation to develop and market innovative sulfur recovery technology.
Summary of Key Findings
- The high initial costs associated with the development of sulfur recovery plants limit industry expansion.
- Market segmented by Technology Type, End User Industry, Type of Feedstock, and region.
- During the projected period, the Claus technology category is expected to dominate the market.
- The most prominent segment in the sulfur recovery technology industry is crude oil.
- Asia Pacific is leading market growth; the market is highly competitive with key players including Jacobs Engineering Group, Chiyoda Corporation, John Wood Group (Amec Foster Wheeler), Technip FMC, Worley Parsons, Linde AG, Fluor Corporation. and Others.
Future Outlook
- Increasing adoption of advanced sulfur recovery technologies.
- Growing demand for cleaner fuels and stricter environmental regulations.
- Technological advancements leading to more efficient and cost-effective solutions.
- Expansion of the market in emerging economies.
- Rising awareness about the importance of sulfur recovery and environmental sustainability.
- Collaborations and partnerships among industry players for innovation and market expansion.
How CXOs Can Benefit from the Credence Research Sulphur recovery technology market Report
The Credence Research Sulphur recovery technology market Report provides CXOs with a comprehensive overview of the market, including:
- Market size and growth forecast: The report provides detailed estimates of the global sulphur recovery technology market size, segmented by Technology Type, End User Industry, Type of Feedstock, and region. It also includes forecasts for the market through 2032, based on key trends and drivers.
- Market segmentation: The report segments the sulphur recovery technology market by Technology Type, End User Industry, Type of Feedstock, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape: The report profiles the key players in the sulphur recovery technology market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers: The report identifies and analyzes the key trends and drivers that are shaping the sulphur recovery technology market . This information can help CXOs to make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research Sulphur recovery technology market Report to:
- Identify growth opportunities: The report can help CXOs to identify new growth opportunities in the sulphur recovery technology market. For example, it may highlight the increasing demand for sulfur recovery technologies in emerging markets like India, where environmental regulations are becoming more stringent. This presents an opportunity for companies to expand their operations and offer innovative solutions in these regions.
- Make informed investment decisions: The report can help CXOs to make informed investment decisions about sulphur recovery technology. For example, it may provide valuable insights into the current market size, growth potential, and key players in the industry. This information can help CXOs evaluate the viability of investing in sulfur recovery technology and determine the potential return on investment.
- Develop competitive strategies: The report can help CXOs to develop competitive strategies for their sulphur recovery technology businesses. For example, it may provide insights into the latest technological advancements in sulfur recovery, enabling CXOs to stay ahead of the competition by implementing innovative solutions.
- Track market developments: The report can help CXOs to track market developments and stay ahead of the curve. For example, the report provides insights into the latest trends and innovations in the sulphur recovery technology market .
Overall, the Credence Research Sulphur recovery technology market Report is a valuable resource for CXOs who are looking to gain a deeper understanding of the market and identify opportunities for growth.
Segmentation
- Technology Type:
- Claus Process
- Tail Gas Treatment
- Other Advanced Technologies
- End User Industry:
- Oil and Gas
- Chemicals and Petrochemicals
- Others
- Type of Feedstock:
- Crude Oil
- Natural Gas
- Oil Sands
- Shale Gas
- Coal
- Others
- By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- North America
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Environmental Regulations
Increasingly strict global and regional regulations on sulfur dioxide emissions are compelling refineries and processing plants to adopt advanced sulfur recovery technologies to remain compliant and avoid penalties.
Growth of Oil & Gas and Petrochemical Industries
Expansion of oil refining and petrochemical operations, especially in emerging economies, is driving demand for sulfur recovery solutions to manage byproduct sulfur and meet product quality standards.
Rising Demand for Cleaner Fuels
The global shift toward cleaner fuels with lower sulfur content is pushing refineries to invest in efficient sulfur recovery technologies to meet fuel specifications and environmental mandates.
Industrialization in Emerging Markets
Rapid industrialization in countries such as China and India is increasing the volume of sulfur-containing feedstocks processed, thereby boosting the need for sulfur recovery technologies to manage emissions and recover valuable sulfur.
Technological Advancements and Process Efficiency
Ongoing innovation in sulfur recovery processes, such as improvements in Claus and tail gas treatment technologies, is enabling higher recovery rates and lower operational costs, making adoption more attractive for industry players.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global Sulphur Recovery Technology Market?
What is the expected growth rate of the Sulphur Recovery Technology Market between 2024 and 2032?
Which segment is leading the market share in terms of Technology Type?
Which Type of Feedstock segment is expected to post the fastest growth rate during the forecast period?
Who are the major players in the global Sulphur Recovery Technology Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology Type
- 1.2.1 Claus Process
- 1.2.2 Tail Gas Treatment
- 1.2.3 Other Advanced Technologies
- 1.3 By End User Industry
- 1.3.1 Oil and Gas
- 1.3.2 Chemicals and Petrochemicals
- 1.3.3 Others
- 1.4 By Type of Feedstock
- 1.4.1 Crude Oil
- 1.4.2 Natural Gas
- 1.4.3 Oil Sands
- 1.4.4 Shale Gas
- 1.4.5 Coal
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1621.2 Million → 2032: USD 4,318.2 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sulphur Recovery Technology Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sulphur Recovery Technology Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sulphur Recovery Technology Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sulphur Recovery Technology Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sulphur Recovery Technology Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sulphur Recovery Technology Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sulphur Recovery Technology Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sulphur Recovery Technology Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1621.2 Million → 2032: USD 4,318.2 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sulphur Recovery Technology Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Claus Process
- 12.3.7.2 Tail Gas Treatment
- 12.3.7.3 Other Advanced Technologies
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User Industry - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oil and Gas
- 12.4.7.2 Chemicals and Petrochemicals
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Feedstock - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Crude Oil
- 12.5.7.2 Natural Gas
- 12.5.7.3 Oil Sands
- 12.5.7.4 Shale Gas
- 12.5.7.5 Coal
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sulphur Recovery Technology End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Sulphur Recovery Technology Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Sulphur Recovery Technology Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Sulphur Recovery Technology Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Jacobs Engineering Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Chiyoda Corporation
- 18.4 John Wood Group (Amec Foster Wheeler)
- 18.5 Technip FMC
- 18.6 Worley Parsons
- 18.7 Linde AG
- 18.8 Fluor Corporation
- 18.9 KT-Kinetics Technology SpA
- 18.10 GTC Technology US
- 18.11 McDermott
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

