
Market Overview:
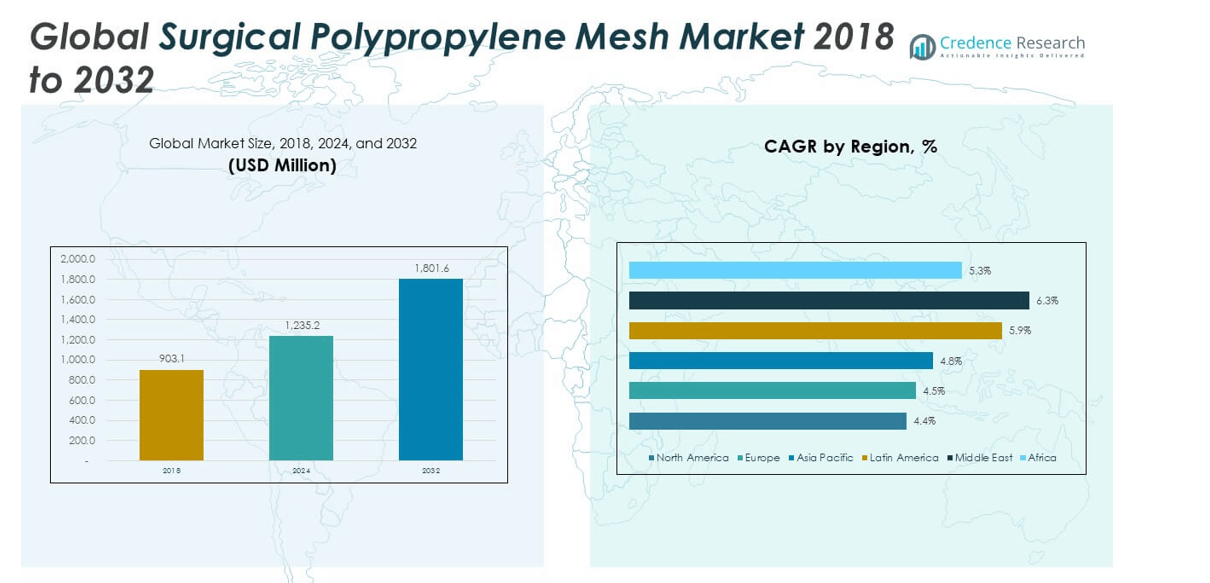
The Global Surgical Polypropylene Mesh Market size was valued at USD 903.1 million in 2018 to USD 1,235.2 million in 2024 and is anticipated to reach USD 1,801.6 million by 2032, at a CAGR of 4.81% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Surgical Polypropylene Mesh Market Size 2024 | USD 1,235.2 million |
| Surgical Polypropylene Mesh Market, CAGR | 4.81% |
| Surgical Polypropylene Mesh Market Size 2032 | USD 1,801.6 million |
The market is driven by the rising prevalence of hernia cases, increasing demand for minimally invasive surgeries, and growing awareness about advanced surgical materials. Hospitals and surgical centers are adopting polypropylene mesh for its durability, flexibility, and reduced recurrence rates in hernia repair procedures. Continuous improvements in surgical techniques and the introduction of lightweight, patient-friendly mesh products are further supporting market expansion. In addition, the rise in aging populations and lifestyle-related health issues contribute to sustained growth.
Geographically, North America leads the market due to advanced healthcare infrastructure and high adoption of surgical innovations. Europe follows with strong demand supported by aging demographics and healthcare reforms. Asia-Pacific is emerging as a high-growth region, driven by increasing healthcare investments, rising surgical procedures, and expanding medical tourism. Meanwhile, Latin America and the Middle East & Africa are witnessing gradual adoption, supported by growing awareness and improving healthcare facilities.
Market Insights:
- The Global Surgical Polypropylene Mesh Market was valued at USD 903.1 million in 2018, reached USD 1,235.2 million in 2024, and is projected to hit USD 1,801.6 million by 2032, expanding at a CAGR of 4.81%.
- Asia Pacific leads with 35.9% share in 2024, driven by large surgical volumes, expanding healthcare infrastructure, and strong demand in China and India.
- Europe holds 29.4% share, supported by advanced clinical practices and aging demographics, while North America follows with 19.3%, driven by reimbursement policies and higher procedure rates.
- Latin America, with 7.4% share, is the fastest-growing region, fueled by medical tourism, rising healthcare spending, and increasing accessibility of advanced surgical solutions.
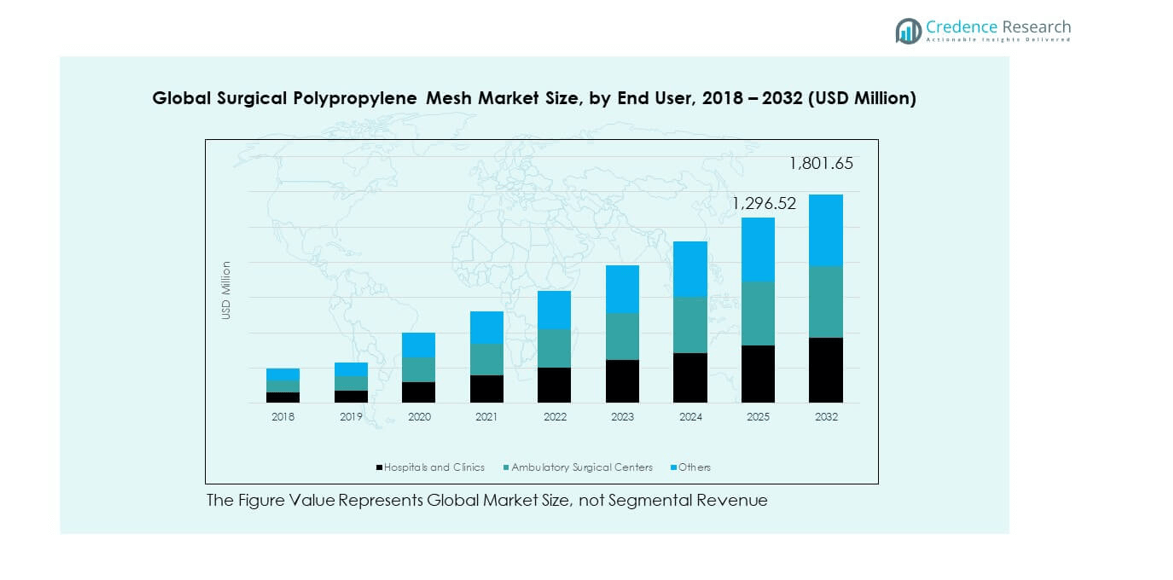
- Hospitals and clinics dominate with about 43% share in 2024, followed by ambulatory surgical centers at 36%, while the remaining 21% is captured by other end users.
Market Drivers:
Rising Prevalence of Hernia and Surgical Cases:
The Global Surgical Polypropylene Mesh Market is strongly driven by the growing incidence of hernia cases worldwide. Hernia repair remains one of the most common surgical procedures, creating consistent demand for surgical mesh solutions. Polypropylene mesh is widely used because of its proven effectiveness in reducing recurrence and improving patient outcomes. Surgeons prefer it for its strength, adaptability, and relatively low cost. Rising awareness among patients about treatment options is further encouraging procedure adoption. The expanding elderly population, often at higher risk of hernia, contributes to growing demand. Increased surgical volume in hospitals and specialty clinics strengthens the market outlook. It is expected to remain a primary driver for polypropylene mesh adoption.
- For instance, studies show that using polypropylene mesh for inguinal hernia repair has significantly reduced recurrence rates compared to suture-only techniques. For example, one study found a 6.8% recurrence rate with mesh versus a 22.3% rate with suture repair. Surgeons prefer mesh for its strength, adaptability, and relatively low cost. Additionally, rising patient awareness about advanced and minimally invasive treatment options is further encouraging procedure adoption.
Growing Shift Toward Minimally Invasive Procedures:
The adoption of minimally invasive surgery is accelerating demand in the market. Polypropylene mesh is compatible with laparoscopic techniques, offering shorter recovery times and fewer complications. Surgeons prefer these procedures to reduce patient discomfort and hospital stay. Advancements in surgical devices are making such approaches safer and more accessible. Patients are increasingly seeking minimally invasive options due to lower risk and improved outcomes. Insurance coverage for laparoscopic hernia repair is expanding access in many regions. Rising healthcare expenditure in developed and developing economies supports wider adoption. It is becoming a key factor in strengthening polypropylene mesh demand.
- For instance, Medtronic's laparoscopic mesh implantation systems have enabled hernia repair procedures with average patient recovery times reduced by 30% compared to open surgeries, based on hospital records from 2024. Surgeons prefer these procedures to reduce patient discomfort and hospital stay. Advancements in surgical devices are making such approaches safer and more accessible. Patients are increasingly seeking minimally invasive options due to lower risk and improved outcomes.
Technological Advancements in Mesh Design and Materials:
Innovation in mesh materials is significantly boosting the market. Manufacturers are focusing on lightweight, flexible, and biocompatible polypropylene mesh products. These designs minimize patient discomfort while maintaining surgical effectiveness. Advances in antimicrobial coatings and absorbable composites are expanding product use. Healthcare providers are adopting advanced mesh solutions to lower the risk of infection. Surgeons are also choosing meshes that adapt better to complex anatomical structures. Continuous R&D investments from major players drive product differentiation. The Global Surgical Polypropylene Mesh Market benefits from the introduction of premium solutions addressing surgeon and patient needs.
Supportive Healthcare Policies and Reimbursement Structure:
Government initiatives and reimbursement policies support wider access to hernia repair procedures. Favorable reimbursement frameworks in developed markets encourage adoption of surgical polypropylene mesh. Public healthcare systems are investing in expanding surgical infrastructure, particularly in emerging economies. Hospitals are increasing procurement of mesh products to meet rising procedure volumes. Awareness campaigns by medical associations highlight the importance of early treatment. Training programs for surgeons improve confidence in using polypropylene mesh solutions. Regulatory approvals for new product designs are enhancing market confidence. It is expected that these supportive policies will sustain long-term growth.
Market Trends:
Increased Focus on Patient-Centric Mesh Designs:
Manufacturers are prioritizing the development of patient-friendly mesh products. The Global Surgical Polypropylene Mesh Market is experiencing growth from demand for meshes that reduce postoperative pain and complications. Companies are introducing ultra-lightweight meshes that enhance comfort and recovery. Patients are increasingly influencing product choices through awareness and education. Hospitals are responding by sourcing products with proven patient benefits. Clinical studies continue to validate the advantages of these new designs. Surgeons are recommending advanced meshes for complex cases requiring tailored solutions. It is shaping the evolution of product portfolios across the industry.
- For instance, B. Braun manufactures super-lightweight polypropylene meshes, like Optilene® Mesh LP, which feature large pores for high biocompatibility and to help reduce the body's foreign body reaction.
Rising Integration of Digital Tools in Surgical Practices:
Digital technologies are increasingly used to improve surgical planning and outcomes. Surgeons are adopting simulation and imaging systems to optimize mesh placement. Hospitals are investing in advanced operating room technologies to support precision surgery. The Global Surgical Polypropylene Mesh Market benefits from these innovations as they enhance success rates. Training programs using virtual and augmented reality are gaining traction. This approach improves surgeon confidence and skills in mesh-related procedures. Medical device companies are also collaborating with digital health firms to integrate solutions. It is leading to greater efficiency and consistency in surgical performance.
Expanding Use of Biodegradable and Hybrid Mesh Solutions:
Biodegradable meshes are gaining market attention as an alternative to permanent implants. While polypropylene remains dominant, hybrid solutions combining absorbable components are emerging. These innovations reduce long-term complications in some patients. The Global Surgical Polypropylene Mesh Market is witnessing diversification as providers expand their portfolios. Hospitals are evaluating hybrid solutions for specific patient groups. Surgeons are increasingly open to using bio-integrated products when clinically appropriate. Ongoing clinical trials are reinforcing confidence in biodegradable mesh designs. It is expected to expand product choices and shape future demand.
Growing Emphasis on Sustainable Manufacturing Practices:
Sustainability is becoming a priority in medical device manufacturing. Companies are adopting eco-friendly processes in polypropylene mesh production. Hospitals and healthcare systems are emphasizing sustainable procurement policies. The Global Surgical Polypropylene Mesh Market is aligning with this shift by promoting recyclable packaging and reduced waste. Manufacturers are investing in energy-efficient facilities to meet regulatory standards. Awareness among stakeholders about environmental impact drives transparency in supply chains. Green certifications are becoming an advantage in competitive tendering processes. It is fostering innovation in sustainable production techniques across the industry.
Market Challenges Analysis:
Concerns About Post-Surgical Complications and Recalls:
The Global Surgical Polypropylene Mesh Market faces scrutiny due to reported complications associated with mesh implants. Some patients experience chronic pain, infections, or mesh rejection, raising concerns about safety. Product recalls in past years have created hesitation among both surgeons and patients. Negative media coverage has also affected public perception of polypropylene mesh. Regulatory agencies are enforcing stricter guidelines to ensure product safety. Surgeons must carefully evaluate patients before recommending mesh implants. Hospitals face reputational risks if adverse events rise. It is a significant challenge that continues to pressure manufacturers to improve design and testing standards.
Price Sensitivity and Availability of Alternatives:
Cost remains a challenge in emerging economies where healthcare budgets are limited. Patients in low-income regions often face barriers to accessing polypropylene mesh surgeries. Alternative surgical techniques without mesh remain in use, reducing adoption rates. Local manufacturers in developing countries sometimes offer low-cost solutions that intensify competition. Hospitals evaluate procurement decisions based on cost rather than advanced features. The Global Surgical Polypropylene Mesh Market must balance innovation with affordability. Supply chain disruptions also affect product availability in some regions. It is a barrier that impacts consistent adoption across diverse markets.
Market Opportunities:
Emerging Demand in Developing Economies:
The Global Surgical Polypropylene Mesh Market has promising opportunities in developing regions. Rapid growth in healthcare infrastructure is supporting adoption of advanced surgical products. Rising disposable income and expanding insurance coverage are enabling access to treatment. Governments are investing in hospitals and surgical centers, boosting demand. Medical tourism in countries like India and Thailand also supports growth. Surgeons in emerging economies are increasingly trained in advanced procedures. Local distribution networks are improving product availability across remote areas. It is creating strong opportunities for manufacturers to expand their presence.
Collaborations and Product Innovation Strategies:
Collaborations between medical device companies and research institutions are driving innovation. The Global Surgical Polypropylene Mesh Market is benefiting from the launch of advanced products addressing unmet needs. Strategic partnerships with hospitals are supporting product trials and adoption. Companies are investing in next-generation meshes with antimicrobial properties and enhanced biocompatibility. Expanding R&D pipelines highlight the commitment to safer and more effective solutions. Marketing alliances are helping manufacturers reach broader audiences. Hospitals are more willing to adopt new products when supported by clinical evidence. It is opening opportunities for long-term growth through innovation.
Market Segmentation Analysis:
By Product
The Global Surgical Polypropylene Mesh Market is divided into absorbable and non-absorbable types. Absorbable meshes are gaining traction for patients requiring temporary reinforcement, particularly in cases where long-term foreign body presence is undesirable. Non-absorbable meshes remain the dominant choice due to their durability, strength, and wide adoption in hernia repair. Hospitals and surgeons continue to prefer non-absorbable options for their reliability in complex and recurrent cases. It is expected that product diversification will continue, supported by innovation in hybrid and patient-friendly solutions.
- For instance, Lotus Surgicals, a leading medical device company known for manufacturing sterile medical devices, offers absorbable meshes like the Pro-AB™, which are used in many hospitals in over 60 countries..
By Application
Hernia repair represents the largest application segment due to the high global incidence of hernia surgeries. Surgical polypropylene mesh ensures reduced recurrence rates, faster recovery, and higher success outcomes. Traumatic or surgical wounds also drive demand, where mesh is used for reinforcement and tissue stabilization. The “others” category includes reconstructive and specialty surgeries, which are expanding as surgical techniques advance. It is anticipated that hernia repair will remain the key driver, while wound-related applications gradually gain share.
- For instance, though some studies show low short-term recurrence rates, numerous long-term studies have identified significant and serious complications in many patients, such as chronic pain, mesh migration, and adhesions. The sheer volume of procedures performed, as mentioned, does not inherently confirm positive patient outcomes; rather, it reflects a history of use that is now understood to carry substantial risks in certain cases.
By End User
Hospitals and clinics lead the market due to high surgical volumes, advanced infrastructure, and wider patient reach. Ambulatory surgical centers are emerging as a strong growth segment, driven by rising demand for minimally invasive outpatient procedures. The “others” category, including specialty surgical centers, contributes to niche demand. It is expected that hospitals will maintain dominance, while ambulatory centers expand faster with the shift toward cost-effective and convenient surgical care.
Segmentation:
By Product
- Absorbable
- Non-Absorbable
By Application
- Hernia Repair
- Traumatic or Surgical Wound
- Others
By End User
- Hospitals and Clinics
- Ambulatory Surgical Centers
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
The North America Surgical Polypropylene Mesh Market size was valued at USD 178.64 million in 2018 to USD 238.45 million in 2024 and is anticipated to reach USD 336.37 million by 2032, at a CAGR of 4.4% during the forecast period. North America accounts for nearly 19.3% of the global market in 2024, supported by advanced healthcare infrastructure and high adoption of innovative surgical products. Strong reimbursement policies encourage hospitals and clinics to adopt polypropylene mesh for hernia repair and wound management. The U.S. leads demand due to a higher prevalence of lifestyle-related hernias and a large aging population. Canada and Mexico are witnessing rising adoption through government healthcare investments. It is expected that the presence of key global players and ongoing clinical advancements will sustain growth in this region.
Europe
The Europe Surgical Polypropylene Mesh Market size was valued at USD 270.21 million in 2018 to USD 363.44 million in 2024 and is anticipated to reach USD 518.15 million by 2032, at a CAGR of 4.5% during the forecast period. Europe represents around 29.4% of the global share in 2024, making it a significant contributor. Demand is fueled by aging demographics, high surgical volumes, and supportive public healthcare systems. Germany, France, and the UK dominate due to advanced clinical practices and high patient awareness. Southern and Eastern European countries are gradually increasing adoption with rising healthcare spending. It is anticipated that ongoing medical research and regional regulatory support will further strengthen market penetration.
Asia Pacific
The Asia Pacific Surgical Polypropylene Mesh Market size was valued at USD 325.12 million in 2018 to USD 444.15 million in 2024 and is anticipated to reach USD 646.79 million by 2032, at a CAGR of 4.8% during the forecast period. Asia Pacific holds the largest share of about 35.9% in 2024, driven by high surgical volumes, large populations, and rapid healthcare infrastructure development. China and India represent the bulk of regional demand with rising incidence of hernia cases and expanding surgical capacity. Japan and South Korea contribute with advanced technology adoption, while Southeast Asia benefits from medical tourism. It is expected that rapid urbanization and improved insurance coverage will make Asia Pacific the fastest-growing market.
Latin America
The Latin America Surgical Polypropylene Mesh Market size was valued at USD 62.31 million in 2018 to USD 91.05 million in 2024 and is anticipated to reach USD 144.13 million by 2032, at a CAGR of 5.9% during the forecast period. Latin America contributes about 7.4% of the global share in 2024, reflecting moderate but growing demand. Brazil leads the region with high surgical capacity and rising private healthcare investments. Argentina and Mexico are also contributing through gradual improvements in healthcare accessibility. The region faces challenges such as unequal access to advanced surgical techniques, but rising middle-class income and medical tourism are creating opportunities. It is anticipated that government focus on expanding healthcare coverage will support stronger adoption.
Middle East
The Middle East Surgical Polypropylene Mesh Market size was valued at USD 43.17 million in 2018 to USD 64.92 million in 2024 and is anticipated to reach USD 106.12 million by 2032, at a CAGR of 6.3% during the forecast period. The Middle East accounts for nearly 5.2% of the global market in 2024, driven by investments in healthcare modernization and surgical infrastructure. GCC countries dominate regional demand due to advanced facilities and growing focus on minimally invasive procedures. Israel and Turkey are expanding their market presence through medical technology advancements and specialist clinics. Rising lifestyle-related hernia cases are supporting consistent adoption. It is expected that favorable government initiatives and private investments will accelerate growth in this region.
Africa
The Africa Surgical Polypropylene Mesh Market size was valued at USD 23.66 million in 2018 to USD 33.21 million in 2024 and is anticipated to reach USD 50.09 million by 2032, at a CAGR of 5.3% during the forecast period. Africa represents around 3.3% of the global share in 2024, reflecting early adoption compared to other regions. South Africa leads the regional market due to better healthcare infrastructure and higher surgical capacity. Egypt is also emerging with improvements in surgical procedures and government healthcare initiatives. Limited awareness, infrastructure gaps, and affordability issues restrict wider adoption in other parts of Africa. It is expected that international collaborations and rising private healthcare investments will gradually boost market penetration.
Key Player Analysis:
- Pierson Surgical Ltd
- Becton, Dickinson and Company
- Medtronic
- Johnson & Johnson Services Inc.
- Bristol-Myers Squibb and Company
- Lotus Surgicals
- Vital Sutures
- Altaylar Medical Ltd.
- Braun
- Atrium Inc.
- Other Key Players
Competitive Analysis:
The Global Surgical Polypropylene Mesh Market is competitive with both multinational corporations and regional players contributing to supply. Key companies such as Becton, Dickinson and Company, Medtronic, Johnson & Johnson Services Inc., B. Braun, and Atrium Inc. dominate through strong product portfolios and established distribution networks. Emerging firms like Lotus Surgicals and Vital Sutures strengthen their positions through cost-effective solutions tailored for developing markets. Competition is driven by continuous product innovation, regulatory approvals, and surgeon adoption of advanced mesh technologies. It is also shaped by mergers, acquisitions, and strategic partnerships designed to expand global presence. The emphasis on absorbable and hybrid mesh solutions is expected to intensify competition.
Recent Developments:
- In July 2025, Becton, Dickinson and Company announced that Waters Corp would acquire its bioscience and diagnostics division in a stock-and-cash transaction valued at $17.5 billion. This move allows Becton Dickinson to focus more on its core medtech operations while Waters expands its presence in clinical and diagnostic applications.
- In June 2025, Medtronic entered a significant multi-year strategic partnership with Philips aimed at expanding access to patient monitoring technology. The agreement includes integrating Medtronic’s advanced monitoring technologies into Philips' solutions and bundling essential supplies with these systems, initially focusing on the North American market.
- In March 2025, Johnson & Johnson Services Inc. showcased advancements in digital orthopedics at the AAOS 2025 meeting, highlighting new implants, advanced techniques, and data-driven technologies aimed at improving patient outcomes in joint reconstruction, trauma, and spine care.
Report Coverage:
The research report offers an in-depth analysis based on product, application, and end-user segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for hernia repair procedures will sustain polypropylene mesh adoption.
- Hospitals will remain the largest end user due to high surgical capacity.
- Ambulatory surgical centers are expected to record faster growth with outpatient procedures.
- Innovation in lightweight and absorbable meshes will expand product diversity.
- Asia Pacific will maintain its position as the fastest-growing region.
- Strategic partnerships and collaborations will enhance global market penetration.
- Regulatory approvals for advanced designs will boost surgeon and patient confidence.
- Growing healthcare investments in emerging economies will create new opportunities.
- Adoption of minimally invasive surgical techniques will drive polypropylene mesh demand.
- Competition will intensify as global and regional players expand portfolios.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Hernia and Surgical Cases
The increasing global incidence of hernia and related surgical cases is driving demand for polypropylene mesh, as hernia repair remains one of the most common surgical procedures. Polypropylene mesh is preferred for its effectiveness in reducing recurrence rates and improving patient outcomes, especially among the aging population.
Shift Toward Minimally Invasive Procedures
Growing adoption of minimally invasive and laparoscopic surgeries is boosting the use of polypropylene mesh, which is compatible with these techniques. These procedures offer shorter recovery times and fewer complications, making them attractive to both patients and healthcare providers.
Technological Advancements in Mesh Design
Continuous innovation in mesh materials, such as lightweight, flexible, and biocompatible polypropylene meshes, is enhancing patient comfort and surgical outcomes. Advances like antimicrobial coatings and hybrid absorbable meshes are expanding the range of clinical applications and reducing post-surgical complications.
Supportive Healthcare Policies and Reimbursement
Favorable reimbursement structures and government initiatives in developed and emerging markets are increasing access to hernia repair procedures using polypropylene mesh. Investments in surgical infrastructure and awareness campaigns further support market growth.
Emerging Demand in Developing Economies
Rapid healthcare infrastructure development, rising disposable incomes, and expanding insurance coverage in developing regions are creating new opportunities for polypropylene mesh adoption. Medical tourism and improved training for surgeons are also contributing to increased market penetration.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Surgical Polypropylene Mesh Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Surgical Polypropylene Mesh Market projected to grow between 2025 and 2032?
Which Global Surgical Polypropylene Mesh Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Surgical Polypropylene Mesh Market?
Who are the leading companies in the Global Surgical Polypropylene Mesh Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Absorbable
- 1.2.2 Non-Absorbable
- 1.3 By End User
- 1.3.1 Hospitals and Clinics
- 1.3.2 Ambulatory Surgical Centers
- 1.3.3 Others
- 1.4 By Application
- 1.4.1 Hernia Repair
- 1.4.2 Traumatic or Surgical Wound
- 1.4.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 903.1 million → 2032: USD 1,801.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Surgical Polypropylene Mesh Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Surgical Polypropylene Mesh Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Surgical Polypropylene Mesh Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Surgical Polypropylene Mesh Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Surgical Polypropylene Mesh Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Surgical Polypropylene Mesh Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Surgical Polypropylene Mesh Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Surgical Polypropylene Mesh Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 903.1 million → 2032: USD 1,801.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Surgical Polypropylene Mesh Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Absorbable
- 12.3.7.2 Non-Absorbable
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals and Clinics
- 12.4.7.2 Ambulatory Surgical Centers
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hernia Repair
- 12.5.7.2 Traumatic or Surgical Wound
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Surgical Polypropylene Mesh End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Surgical Polypropylene Mesh Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Surgical Polypropylene Mesh Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Surgical Polypropylene Mesh Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Becton, Dickinson and Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Medtronic
- 18.4 Johnson & Johnson Services Inc.
- 18.5 B. Braun
- 18.6 Atrium Inc.
- 18.7 Lotus Surgicals
- 18.8 Vital Sutures
- 18.9 Pierson Surgical Ltd
- 18.10 Altaylar Medical Ltd.
- 18.11 Bristol-Myers Squibb and Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

