
Market Overview
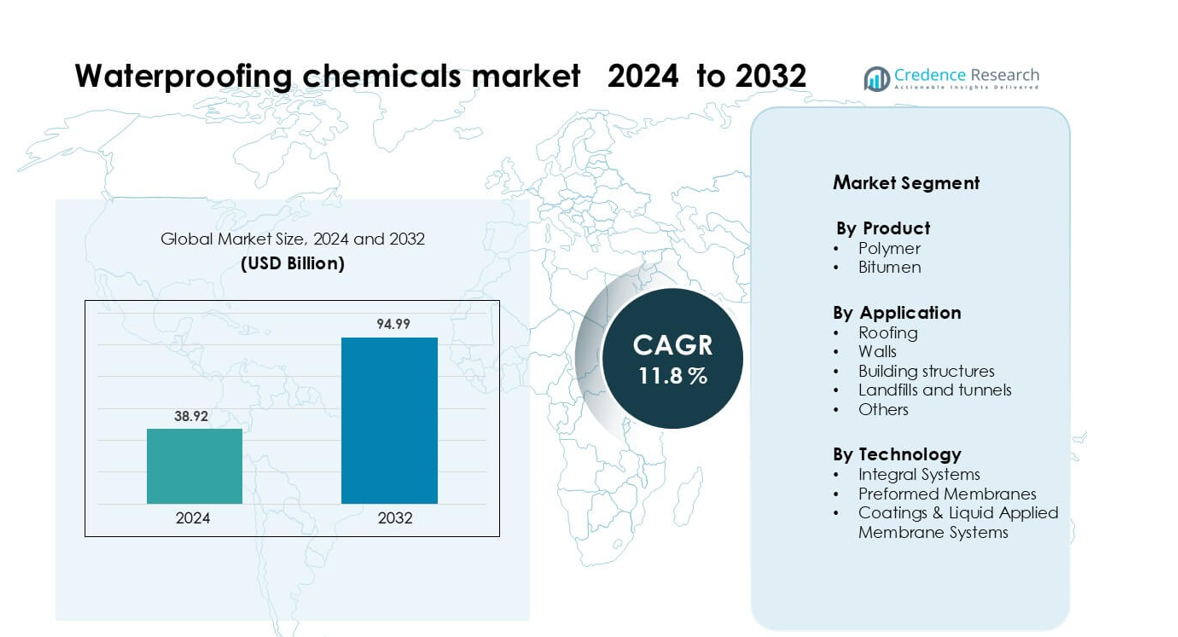
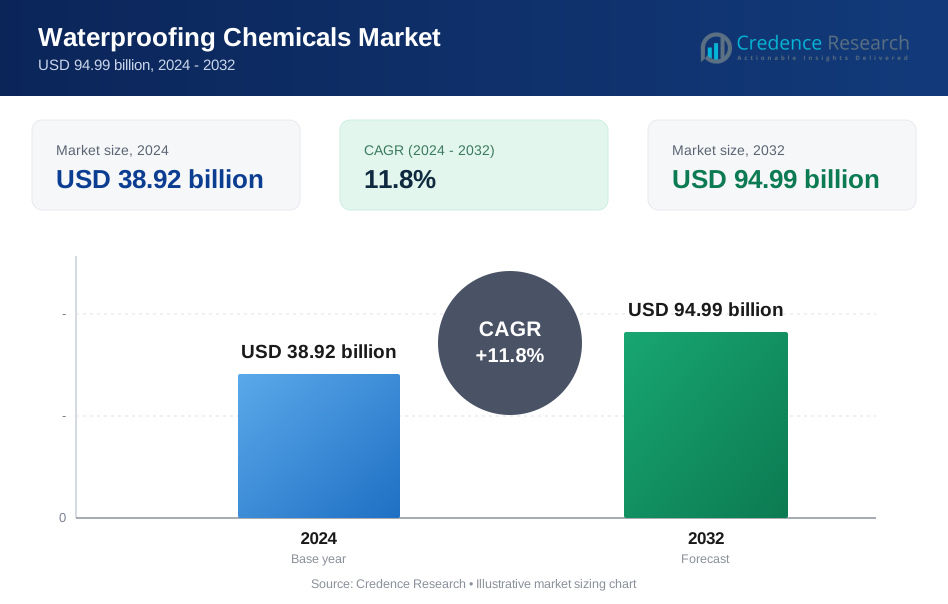
Waterproofing chemicals market was valued at USD 38.92 billion in 2024 and is anticipated to reach USD 94.99 billion by 2032, growing at a CAGR of 11.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Waterproofing Chemicals Market Size 2024 | USD 38.92 billion |
| Waterproofing Chemicals Market, CAGR | 11.8% |
| Waterproofing Chemicals Market Size 2032 | USD 94.99 billion |
Top players in the waterproofing chemicals market include BASF SE, Johns Manville, SOPREMA Group, Sika AG, DOW, Minerals Technologies Inc., MBCC Group, Firestone Building Products Company, EverGuard TPO Walkway Roll, and Carlisle Companies Inc. These companies strengthen their position through advanced polymer membranes, liquid-applied coatings, and durable bitumen systems used across large construction projects. Continuous product innovation, regional capacity expansion, and strong contractor partnerships help these firms maintain competitiveness in rapidly growing markets. Asia Pacific remained the leading region in 2024 with about 41% share, driven by large-scale infrastructure spending, urban housing demand, and rising adoption of high-performance waterproofing solutions.
Market Insights
- Waterproofing chemicals market was valued at USD 38.92 billion in 2024 and is anticipated to reach USD 94.99 billion by 2032, growing at a CAGR of 11.8% during the forecast period.
- Growth drivers include rapid urbanisation, expanded infrastructure development, and increasing demand for durable buildings, which push segment share for polymer-based products higher.
- Key trends highlight a shift toward sustainable, low-VOC waterproofing solutions and wider adoption of liquid-applied membranes, especially in the roofing and building-structures applications.
- Competitive analysis shows major chemical and construction companies leveraging innovations, geographic expansions and strategic partnerships to secure stronger positions, though high raw material costs act as a market restraint.
- Regionally, Asia Pacific dominated the market with a share of approximately 41 % in 2023; product segments such as roofing accounted for leading application shares.
Market Segmentation Analysis:
By Product
Polymer products dominated the waterproofing chemicals market in 2024 with about 46% share. Strong demand came from construction firms that favored acrylic, polyurethane, and EPDM solutions for flexibility and long service life. Builders used polymer barriers in large projects due to fast curing and strong UV resistance. Bitumen stayed important in mass roofing and roadwork, but rising need for lighter and more durable materials helped polymer systems grow faster across both residential and commercial sites.
- For instance, Sika AG applied 3.3 million m² of its Sikaplan® polymer‑based waterproofing membrane in the Gotthard Base Tunnel project, demonstrating both excellent flexibility and long-term durability.
By Application
Roofing remained the dominant application in 2024 with nearly 42% share. Contractors chose roofing systems because they offered strong leak protection, easy installation, and wide compatibility with modern membranes. Market growth also came from urban housing upgrades and warehouse expansion. Walls and building structures showed steady demand as high-rise projects increased, while landfills and tunnels used advanced barriers for chemical resistance and long-term moisture control in regulated environments.
- For instance, Sika deployed its Sikalastic‑833 R pure polyurea membrane at a large exposed roof project with a coverage rate of ~2.0–2.4 kg/m², delivering a dry film thickness of 2.0–2.4 mm and a tensile strength of ~16 MPa, which provided excellent crack bridging and UV resistance.
By Technology
Coatings & liquid applied membrane systems led the market in 2024 with around 49% share. These systems gained traction due to seamless coverage, easy handling, and strong adhesion on complex surfaces. Construction firms preferred liquid membranes for large roofs, podium slabs, and refurbishment jobs. Preformed membranes stayed relevant in tunnels and basements, while integral systems expanded as developers added admixtures during concrete mixing to improve long-term structural durability across new infrastructure projects.
Key Growth Drivers
Rising Construction and Infrastructure Investment
Global construction growth acts as a major catalyst for the waterproofing chemicals market. Urban housing demand continues to rise, while governments invest in transportation networks, smart cities, and industrial corridors. These projects require long-lasting moisture barriers to protect foundations, roofs, and structural components from water damage. Builders now follow stricter quality norms, which boosts the use of advanced membranes and polymer-based coatings. Climate variation also increases the need for strong waterproofing solutions in flood-prone and high-rainfall areas. Together, these factors push steady adoption across residential, commercial, and public infrastructure developments worldwide.
- For instance, Sika supplied approximately 3.3 million m² of its Sikaplan® waterproofing membrane for the Gotthard Base Tunnel in Switzerland, leveraging its long-term durability for high stress, water-bearing underground infrastructure.
Increasing Focus on Durability and Building Safety
Developers now prioritize structural safety as building failures linked to water seepage become more common. Moisture intrusion accelerates corrosion, weakens concrete, and raises repair costs for large assets. Waterproofing chemicals help extend service life, reduce lifecycle spending, and improve overall building durability. Commercial complexes, warehouses, and industrial units use liquid membranes and integral systems to protect heavy-use areas. Better awareness among builders and facility managers drives wider compliance with safety codes. This shift supports strong growth for high-performance coatings, modified bitumen sheets, and polymer membranes across key global markets.
- For instance, Sika’s Sikagard® M 790 crack-bridging membrane provides high resistance to carbon dioxide diffusion, thereby protecting embedded rebar in concrete from corrosion
Growth in Industrial and Waste Management Projects
Demand rises as industries expand storage units, processing plants, and utility buildings that require strong waterproofing barriers. Chemical plants, warehouses, water-treatment projects, and power facilities use membranes to prevent leaks that may affect operations or safety. Landfill sites and tunnels also need specialized waterproofing layers to block hazardous runoffs and groundwater intrusion. Regulations encourage the use of protective coatings in waste containment zones, pushing wider adoption. These needs make waterproofing chemicals essential for long-term protection in sectors where exposure risks remain high and maintenance windows stay limited.
Key Trend & Opportunity
Shift Toward Polymer and Liquid Membrane Technologies
The market shows a clear shift toward flexible, seamless polymer coatings and liquid-applied membranes. Builders value these technologies for their ease of application, faster installation, and strong adhesion to complex surfaces. Urban redevelopment, green buildings, and lightweight construction materials further support this shift. Companies now innovate with elastomeric acrylics, polyurethanes, and hybrid membranes that offer longer durability and UV resistance. This trend opens opportunities for manufacturers to introduce low-VOC, fast-curing, and energy-efficient solutions aligned with modern architectural needs.
- For instance, Sika’s Sikalastic®‑560 (a one-component, waterborne polyurethane‑acrylic dispersion) cures to rain resistance in about 8 hours and reaches full cure in 4 days at 20 °C, with a dry film thickness of 0.3–0.5 mm when applied at 0.9–1.4 kg/m².
Adoption of Sustainable and Low-Emission Waterproofing Solutions
Sustainability creates new opportunities as buyers prefer materials with reduced environmental impact. Regulations encourage lower solvent use, recyclable membranes, and products that reduce VOC emissions. Leading brands now develop bio-based polymers and water-borne coatings that meet green-building certifications. Roofing and facade systems adopt reflective and heat-resistant coatings, helping reduce energy use in high-temperature regions. This shift enables companies to expand their portfolios with eco-friendly options while capturing demand from developers aiming for LEED, BREEAM, and similar ratings.
- For instance, GCP Applied Technologies offers its SILCOR® 560 LVOC, a one-part, fast-curing polyurethane elastomer with a VOC content low enough to qualify as low odor/low VOC.
Technological Integration in Application and Monitoring
Automation and digital tools now support waterproofing work through improved accuracy and quality control. Spray-applied robotics, moisture sensors, and advanced curing monitors help contractors achieve consistent membrane thickness and long-term reliability. Smart infrastructure projects integrate waterproofing with real-time monitoring systems that detect leaks early. This trend opens opportunities for suppliers to partner with construction-tech firms and deliver value-added, technology-enabled solutions. Adoption rises in commercial complexes, tunnels, and high-risk industrial facilities where downtime due to failures is costly.
Key Challenge
Price Sensitivity and High Installation Costs
Cost remains one of the biggest challenges in the waterproofing chemicals market. Advanced polymer membranes and liquid systems cost more than traditional options, which reduces adoption among small contractors and low-budget projects. Skilled labor is required for proper installation, especially for spray-based and multi-layer membrane systems, raising service charges. In developing regions, many buyers choose lower-grade materials that compromise long-term performance. These factors slow premium-product penetration, despite strong awareness of lifecycle benefits.
Lack of Standardization and Quality Compliance
The market faces gaps in regulatory enforcement, especially across emerging economies. Many projects use non-certified materials that fail to meet performance standards, leading to leakage issues and premature repairs. Inconsistent installation practices also reduce membrane effectiveness, as contractors may skip curing steps or apply uneven thickness. Limited training and fragmented supply chains add to the problem. These issues hinder uniform adoption of advanced systems and create challenges for manufacturers aiming to maintain consistent quality across large construction markets.
Regional Analysis
North America
North America held about 28% share of the waterproofing chemicals market in 2024. Strong residential repair activity and large commercial upgrades supported steady demand across the United States and Canada. Builders used polymer coatings and liquid membranes to meet strict moisture-control and energy-efficiency codes. Infrastructure spending on bridges, tunnels, and public utilities further increased adoption. Roofing refurbishment dominated applications, while green-building programs encouraged low-VOC and durable solutions. Industrial facilities and warehouses expanded their use of waterproofing systems to protect slabs and containment areas from long-term water exposure and operational risks.
Europe
Europe accounted for nearly 25% share in 2024, driven by stringent environmental rules and strong focus on sustainable construction. Western Europe adopted advanced polymer membranes and low-emission coatings for housing retrofits and commercial structures. Eastern Europe expanded infrastructure work, pushing demand for preformed sheets in tunnels, rail corridors, and wastewater facilities. Energy-efficient building standards boosted interest in reflective coatings and water-borne systems. Growing renovation cycles across Germany, France, and the UK supported steady use of liquid-applied membranes, while industrial upgrades increased adoption of integral systems in long-life concrete projects.
Asia Pacific
Asia Pacific dominated the global market with around 41% share in 2024. Massive investments in housing, transport networks, and industrial facilities drove strong growth across China, India, Indonesia, and Vietnam. Contractors preferred cost-effective polymer membranes and bitumen systems for large-scale roofing and foundation work. Rising urban flooding and extreme rainfall pushed developers to adopt stronger waterproofing layers in high-rise construction. Expanding manufacturing zones and logistics parks increased the use of coatings in warehouses and utility structures. Government-backed smart-city projects further boosted demand for advanced sealing systems and durable liquid membranes.
Latin America
Latin America captured about 4% share in 2024, supported by infrastructure recovery and housing upgrades. Brazil and Mexico led consumption as public-sector spending focused on transport, water management, and urban renewal. Builders favored liquid-applied membranes for refurbishment due to simple installation and lower labor cost. Industrial plants, especially in mining and agro-processing, used reinforced membranes to protect storage units and containment basins. Uneven economic growth limited premium adoption, but rising awareness of moisture-related structural failures encouraged broader use of high-performance waterproofing products across commercial and residential projects.
Middle East & Africa
The Middle East & Africa region held nearly 6% share in 2024, driven by large construction pipelines across the Gulf and rising urban development in African economies. Harsh climatic conditions increased demand for heat-resistant polymer coatings and long-life membranes. Mega-projects in Saudi Arabia and the UAE used advanced waterproofing systems for tunnels, basements, and transport corridors. Africa showed growing use of bitumen and liquid membranes in housing and public infrastructure. Water scarcity concerns also encouraged adoption of protective coatings in desalination plants, utility structures, and wastewater treatment facilities.
Market Segmentations:
By Product
- Polymer
- Bitumen
By Application
- Roofing
- Walls
- Building structures
- Landfills and tunnels
- Others
By Technology
- Integral Systems
- Preformed Membranes
- Coatings & Liquid Applied Membrane Systems
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The waterproofing chemicals market features strong competition among global manufacturers that focus on durable membranes, advanced polymer solutions, and liquid-applied coatings for large construction needs. BASF SE, Johns Manville, SOPREMA Group, Sika AG, DOW, Minerals Technologies Inc., MBCC Group, Firestone Building Products Company, EverGuard TPO Walkway Roll, and Carlisle Companies Inc. lead the landscape with broad product portfolios and strong project networks. These companies invest in improved elastomeric coatings, hybrid membranes, and low-VOC systems to meet rising sustainability goals. Partnerships with contractors, quick-installation technologies, and region-specific product lines help expand market presence. Companies also strengthen their positions by expanding production capacity and enhancing distribution networks in fast-growing regions.
Key Player Analysis
- BASF SE (Germany)
- Johns Manville (U.S.)
- SOPREMA Group (France)
- Sika AG (Switzerland)
- DOW (U.S.)
- Minerals Technologies Inc. (U.S.)
- MBCC Group (Germany)
- Firestone Building Products Company (U.S.)
- EverGuard TPO Walkway Roll (U.S.)
- Carlisle Companies Inc. (U.S.)
Recent Developments
- In October 2025, SOPREMA Group (France) SOPREMA US announced the full transition of Tropical Roofing Products to the SOPREMA brand, consolidating TRP’s roof coatings and maintenance products under a unified waterproofing portfolio while keeping product performance unchanged for contractors and building owners.
- In October 2024, Johns Manville (U.S.) Johns Manville launched its JM EPDM FIT SA self-adhered EPDM roofing membrane, designed to install up to three times faster than traditionally adhered membranes and to be applied in temperatures as low as 20°F, while eliminating separate adhesives and associated VOC emissions.
- In April 2024, BASF SE (Germany) BASF signed a memorandum of understanding with Oriental Yuhong to expand joint development of solutions for the construction sector, including new technologies in waterproof materials, architectural coatings, and insulation systems for sustainable building projects
Report Coverage
The research report offers an in-depth analysis based on Product, Application, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise as cities expand housing, transport links, and commercial sites.
- Builders will adopt more polymer membranes for long service life and flexibility.
- Liquid-applied coatings will gain wider use due to faster installation needs.
- Green construction rules will push producers to develop low-VOC and eco-safe products.
- Smart application tools and sensors will improve accuracy and reduce project failures.
- Industrial zones will increase use of waterproofing for storage, utilities, and process units.
- Renovation work in aging buildings will boost demand for high-performance membranes.
- Companies will expand regional production to cut lead times and serve fast-growing markets.
- Rising climate risks will increase adoption in flood-prone and high-rainfall regions.
- New product blends combining polymers and hybrid materials will take larger market share.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Construction and Infrastructure Investment
Global construction growth, including urban housing, transportation networks, and industrial corridors, is driving demand for waterproofing chemicals to protect new and existing structures from water damage. Stricter quality norms and climate variability further increase the need for advanced waterproofing solutions.
Increasing Focus on Durability and Building Safety
Developers and facility managers are prioritizing long-term structural safety and lifecycle cost reduction, leading to greater adoption of high-performance membranes and coatings that prevent moisture intrusion, corrosion, and concrete degradation.
Growth in Industrial and Waste Management Projects
Expansion of industrial facilities, warehouses, and utility buildings, as well as stricter regulations for landfills and tunnels, are boosting demand for specialized waterproofing chemicals that ensure operational safety and environmental compliance.
Shift Toward Polymer and Liquid Membrane Technologies
The market is experiencing a shift toward flexible, seamless polymer coatings and liquid-applied membranes due to their ease of application, fast installation, and superior durability, especially in large-scale and complex construction projects.
Adoption of Sustainable and Low-Emission Waterproofing Solutions
Environmental regulations and green building certifications are encouraging the use of low-VOC, recyclable, and bio-based waterproofing chemicals, prompting manufacturers to innovate and expand their eco-friendly product portfolios.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Waterproofing chemicals market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is Waterproofing chemicals market projected to grow between 2025 and 2032?
What are the key drivers for the growth of the Waterproofing Chemicals Market?
Which is the major segment in Waterproofing Chemicals Market by Chemistry?
Which is the major segment in Waterproofing Chemicals Market by System/Technology?
Who are the leading companies in Waterproofing chemicals market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Polymer
- 1.2.2 Bitumen
- 1.3 By Technology
- 1.3.1 Integral Systems
- 1.3.2 Preformed Membranes
- 1.3.3 Coatings & Liquid Applied Membrane Systems
- 1.4 By Application
- 1.4.1 Roofing
- 1.4.2 Walls
- 1.4.3 Building structures
- 1.4.4 Landfills and tunnels
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 38.92 billion → 2032: USD 94.99 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Waterproofing Chemicals Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Waterproofing Chemicals Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Waterproofing Chemicals Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Waterproofing Chemicals Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Waterproofing Chemicals Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Waterproofing Chemicals Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Waterproofing Chemicals Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Waterproofing Chemicals Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 38.92 billion → 2032: USD 94.99 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Waterproofing Chemicals Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Polymer
- 12.3.7.2 Bitumen
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Integral Systems
- 12.4.7.2 Preformed Membranes
- 12.4.7.3 Coatings & Liquid Applied Membrane Systems
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Roofing
- 12.5.7.2 Walls
- 12.5.7.3 Building structures
- 12.5.7.4 Landfills and tunnels
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Waterproofing Chemicals End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Waterproofing Chemicals Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Waterproofing Chemicals Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Waterproofing Chemicals Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Johns Manville
- 18.4 SOPREMA Group
- 18.5 Sika AG
- 18.6 DOW
- 18.7 Minerals Technologies Inc.
- 18.8 MBCC Group
- 18.9 Firestone Building Products Company
- 18.10 Carlisle Companies Inc.
- 18.11 EverGuard TPO Walkway Roll
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

