
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Emulsifiers Market Size 2024 | USD 9,579.5 million |
| Emulsifiers Market, CAGR | 3.70% |
| Emulsifiers Market Size 2032 | USD 12,810.7 million |
Market Overview
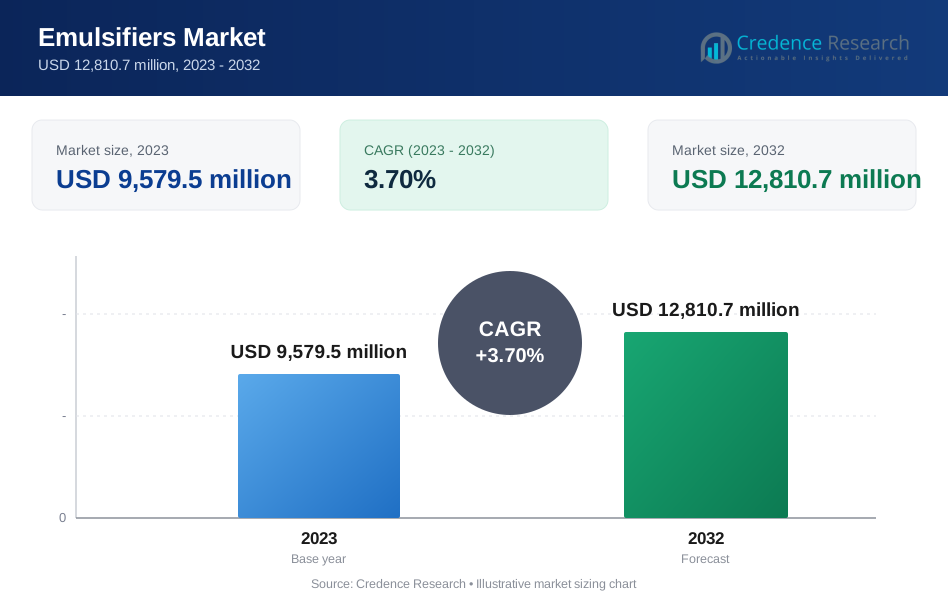
The Emulsifiers Market is projected to grow from USD 9,579.5 million in 2023 to an estimated USD 12,810.7 million by 2032, with a compound annual growth rate (CAGR) of 3.70% from 2024 to 2032. This growth trajectory highlights the increasing demand for emulsifiers across various industries, including food and beverages, personal care, pharmaceuticals, and agrochemicals.
Several key drivers propel the emulsifiers market forward. The growing demand for processed and convenience foods is a major factor, as emulsifiers improve the texture, consistency, and taste of these products. Additionally, the personal care and cosmetics sector leverages emulsifiers in lotions, creams, and other formulations for their stabilizing properties. Emerging trends such as the shift towards natural and bio-based emulsifiers, driven by consumer preference for clean-label ingredients, further bolster market growth. These drivers, coupled with increasing R&D in emulsifier formulations, shape the evolving landscape of the emulsifiers market.
Geographically, North America and Europe lead the emulsifiers market due to the high demand in food processing and personal care industries. The Asia-Pacific region is expected to witness significant growth, supported by the expanding food and beverage sector and rising disposable incomes in countries like China and India. Key players in the global emulsifiers market include Archer Daniels Midland Company, Cargill, BASF SE, DuPont, and Kerry Group, among others, who focus on innovation and strategic partnerships to maintain their competitive edge and cater to diverse industry needs.
Market Drivers
Rising Demand for Processed and Convenience Foods
The emulsifiers market experiences robust growth due to the increasing consumption of processed and convenience foods. As consumer lifestyles become more fast-paced, there is a growing preference for ready-to-eat and packaged foods. For instance, emulsifiers are crucial in products like mayonnaise and ice cream, where they enhance texture and prevent separation of ingredients, ensuring a stable and appealing final product. The use of emulsifiers like lecithin and mono- and diglycerides is prevalent in these applications, allowing manufacturers to create high-quality items that meet consumer expectations for convenience and taste. Emulsifiers play a critical role in enhancing the texture, stability, and overall sensory appeal of these products. They prevent the separation of ingredients, allowing manufacturers to produce high-quality, long-lasting products that meet consumer expectations. In addition, food companies are continually seeking ingredients that improve food consistency and mouthfeel, making emulsifiers essential in product formulation. This trend is particularly strong in urbanized areas and developed markets, but it is also expanding rapidly in emerging economies as they adopt more Western-style food consumption patterns.
Increasing Application in Personal Care and Cosmetics
Another significant driver for the emulsifiers market is the personal care and cosmetics industry, which uses emulsifiers extensively in products such as lotions, creams, and shampoos. For instance, in lotions and creams, emulsifiers facilitate the blending of oil and water components, leading to stable formulations that maintain their effectiveness over time. This is particularly important as consumers increasingly seek products that deliver both quality and performance, driving the demand for emulsifiers that can support these requirements.Emulsifiers allow for the smooth blending of water and oil-based ingredients, creating formulations that are stable and effective over extended periods. As consumer awareness grows around self-care and grooming, the demand for high-quality skincare and beauty products is rising. Additionally, trends toward clean beauty and natural ingredients are pushing cosmetic manufacturers to explore bio-based emulsifiers, which are perceived as safer and more environmentally friendly. This shift not only drives innovation but also increases the overall demand for emulsifiers as companies strive to meet consumer expectations for safe, effective, and eco-conscious products.
Shift Toward Natural and Bio-based Emulsifiers
There is a noticeable shift in the emulsifiers market towards natural and bio-based products, driven by the increasing consumer preference for clean-label and environmentally sustainable ingredients. For instance, many cosmetic brands are now exploring plant-derived emulsifiers as alternatives to synthetic options, which aligns with the growing trend towards sustainability and transparency in ingredient sourcing. This change is fueled by both regulatory pressures and consumer demand for transparency in product sourcing and production.The food and beverage industry, in particular, is moving towards natural emulsifiers as health-conscious consumers seek products free from artificial additives. Similarly, the cosmetics industry is adopting bio-based emulsifiers to cater to the demand for organic and natural products. This trend toward natural emulsifiers is opening new avenues for manufacturers and creating opportunities for companies that prioritize sustainability and natural product lines
Expansion of Emulsifier Applications Across Diverse Industries
Emulsifiers are becoming increasingly important in a wide range of industries beyond food and personal care, including pharmaceuticals, agrochemicals, and industrial applications. In the pharmaceutical industry, emulsifiers are used in drug formulations to enhance the stability and bioavailability of active ingredients. They also play a crucial role in controlled-release drug delivery systems, which is an area of significant research and development. Similarly, the agrochemical industry utilizes emulsifiers in pesticides and herbicides to improve the dispersion and effectiveness of active compounds. Additionally, the industrial sector employs emulsifiers in applications such as lubricants and coatings, where they enhance the performance and longevity of products. The broadening scope of emulsifier applications across these diverse sectors underscores their versatility and drives sustained growth in the market.
Market Trends
Surge in Demand for Clean-Label and Natural Emulsifiers
A major trend driving the emulsifiers market is the increasing demand for clean-label and natural ingredients. As consumers become more health-conscious and environmentally aware, they seek transparency in the products they purchase, particularly in food, beverages, and personal care items. Clean-label emulsifiers, which are free from artificial additives, preservatives, and chemical stabilizers, align with this shift in consumer preference. For instance, a recent product launch by InnovoPro introduced a clean-label chickpea protein concentrate, CP-Pro 70, designed to be nutrient-dense and versatile while maintaining stability on the shelf. This trend is particularly evident in the food and beverage sector, where manufacturers face pressure to reformulate their products to cater to consumers looking for simple, recognizable ingredients. In response, companies are investing in research and development to create bio-based and sustainable emulsifiers that meet these expectations while maintaining the stability and functionality of their products. This trend is also influencing the cosmetics industry, where brands are increasingly emphasizing the use of natural emulsifiers to appeal to customers who prioritize organic and environmentally friendly ingredients.
Technological Advancements and Innovation in Emulsifier Formulations
Another prominent trend in the emulsifiers market is the continuous technological advancements and innovation in product formulations. Companies are actively exploring new emulsification technologies to improve the efficiency, performance, and versatility of emulsifiers across various applications. For example, there is a growing interest in nanoemulsions, which utilize emulsifiers to create fine, stable emulsions at the nanoscale level. These innovations enhance the bioavailability of active ingredients in pharmaceuticals and nutraceuticals, making them more effective.In the food industry, advancements like cold emulsification processes have emerged, allowing manufacturers to produce high-quality products while reducing energy consumption-aligning with sustainability goals. Additionally, companies are experimenting with encapsulation techniques and multi-functional emulsifiers that can offer enhanced stability, extended shelf life, and even improved flavor and texture in food products. Such innovations not only meet the evolving demands of end-users but also open new avenues for product differentiation in an increasingly competitive market.
Market Restraints and Challenges
Stringent Regulatory Requirements and Compliance Costs
One of the most significant challenges facing the emulsifiers market is the stringent regulatory landscape governing food additives and cosmetic ingredients. Regulatory bodies such as the U.S. Food and Drug Administration (FDA), the European Food Safety Authority (EFSA), and others have strict guidelines regarding the use of emulsifiers, especially synthetic and chemical-based types, due to potential health and environmental concerns. Compliance with these regulations often requires extensive testing, which can be costly and time-consuming for manufacturers. As regulations evolve, companies must invest in ongoing research and development to ensure their emulsifiers meet safety and labeling requirements. This can be particularly challenging for smaller companies with limited resources. Furthermore, as consumers increasingly seek products with natural and organic ingredients, the pressure to reformulate or develop bio-based emulsifiers that comply with regulatory standards while delivering effective performance adds another layer of complexity. These regulatory hurdles can hinder market growth by slowing down the introduction of new products and increasing the overall costs for manufacturers.
Fluctuations in Raw Material Availability and Costs
The emulsifiers market is also impacted by the fluctuating availability and rising costs of raw materials, particularly those derived from natural sources. Emulsifiers are often produced from plant-based oils such as palm, soy, and sunflower, and the supply of these raw materials can be affected by factors such as climate change, agricultural practices, and geopolitical instability. For instance, the palm oil industry faces scrutiny due to environmental concerns, which has led to regulatory restrictions and increased costs. As a result, manufacturers may face challenges in securing a consistent supply of high-quality raw materials at competitive prices, which can directly impact production costs and profit margins. Additionally, the shift towards sustainable and bio-based emulsifiers intensifies the demand for certain raw materials, further straining supply chains. These cost and availability issues can limit the market’s growth potential, as manufacturers may need to pass on higher costs to consumers, potentially reducing demand for products containing emulsifiers.
Market Segmentation Analysis
By Product
The emulsifiers market encompasses a variety of product types, each serving distinct roles across industries. Lactic esters of fatty acids are popular in food for enhancing texture and shelf life and are also used in personal care products due to their skin-friendly properties. Lecithin, derived from sources like soybeans and sunflower seeds, is versatile and widely used in both food and non-food products, especially in chocolate, bakery, and confectionery applications. Mono and di-glycerides of fatty acids improve dough stability and product texture in bakery items and are also found in margarine, processed foods, and frozen desserts. Esters of monoglycerides contribute stability and texture, commonly seen in dairy, meat, and processed foods. Polysorbates are valuable in pharmaceuticals, cosmetics, and foods, enhancing consistency and bioavailability. Polyglycerol esters are efficient for oil-in-water emulsions, ideal for baked goods, sauces, and spreads, while polyglycerol polyricinoleate (PGPR) is used mainly in chocolate production for reducing viscosity and improving flow. Lastly, the “Others” category includes emulsifiers like stearoyl lactylates and sorbitan esters, which have specialized uses across food, cosmetics, and pharmaceuticals.
By Source
The emulsifiers market is segmented by source into bio-based and synthetic categories, reflecting a growing trend toward sustainability and a preference for natural ingredients. Bio-based emulsifiers, derived from plants and animals, align with clean-label demands and are especially popular in food and cosmetics, as they are viewed as more environmentally sustainable and appeal to consumers seeking organic and non-GMO options. In contrast, synthetic emulsifiers, produced through chemical processes, remain widely used across industries for their cost-effectiveness and consistent quality. However, as regulatory pressures and consumer preferences shift towards natural ingredients, many companies are exploring bio-based alternatives, although synthetic emulsifiers still dominate in applications requiring higher stability or functionality.
Segments
Based on Product Type
- Lactic Esters of Fatty Acids
- Lecithin
- Mono & Di-glycerides of Fatty Acid
- Esters of Monoglycerides of Fatty Acid
- Polysorbates
- Polyglycerol Esters
- Polyglycerol Polyricinoleate
- Others
Based on Source
- Bio-Based
- Synthetic
Based on Application
- Food and Beverages
- Cosmetics and Personal Care Products
- Oilfield Chemicals
- Pharmaceuticals
- Others
Based on Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis
North America (30%):
North America is a leading region in the emulsifiers market, holding approximately 30% of the global market share. The region’s demand for emulsifiers is driven primarily by the well-established food and beverage industry, which extensively utilizes emulsifiers to enhance product quality and shelf life. Additionally, the personal care and cosmetics sectors in North America heavily rely on emulsifiers for product formulations, as consumer preferences shift towards natural and bio-based ingredients. The region also witnesses strong regulatory oversight, with agencies such as the FDA setting stringent guidelines, which encourage innovation and higher-quality product development. Moreover, the growing popularity of clean-label products has led to an increased demand for natural emulsifiers, particularly in the U.S. and Canada.
Europe (25%):
Europe accounts for roughly 25% of the global emulsifiers market, with countries like Germany, the United Kingdom, and France being key contributors. The demand in Europe is primarily driven by the food and personal care sectors, where emulsifiers are used to enhance the stability and texture of products. Additionally, Europe’s stringent regulations concerning food safety and environmental sustainability push manufacturers to adopt bio-based emulsifiers, especially in response to the region’s heightened focus on eco-friendly and organic ingredients. The region’s emphasis on clean-label and non-GMO products further fuels demand for natural emulsifiers, while companies in Europe actively invest in R&D to develop sustainable and high-performance emulsifiers to meet these consumer expectations.
Key players
- Archer Daniels Midland Company
- BASF SE
- Cargill Incorporated
- Koninklijke DSM N.V.
- Evonik Industries AG
- Kerry Group plc
- Palsgaard A/S
- Puratos Group
- Spartan Chemical Company Inc.
- Stepan Company
- The Dow Chemical Company
- The Lubrizol Corporation
Competitive Analysis
The emulsifiers market is highly competitive, with key players focusing on innovation, strategic partnerships, and sustainable practices to gain a competitive edge. Companies such as Archer Daniels Midland, Cargill, and BASF SE leverage their extensive portfolios and global reach to cater to various industries, including food and beverage, personal care, and pharmaceuticals. Market leaders are increasingly investing in research and development to create bio-based and clean-label emulsifiers in response to rising consumer demand for natural ingredients. Additionally, partnerships and acquisitions are prevalent strategies, enabling companies like Kerry Group and Palsgaard A/S to expand their product lines and market presence. Regulatory compliance also plays a significant role, with players ensuring that their products meet stringent safety and environmental standards. This competitive landscape drives innovation and sustainability, as companies strive to differentiate themselves in a growing, diverse market.
Recent Developments
- In September 2023, Evonik launched a new line of plantInbased emulsifiers designed to meet the increasing consumer demand for natural ingredients in food products.
- In February 2024, Palsgaard introduced a new range of emulsifiers specifically designed for plantInbased products, responding to the rising trend of vegan dietary preferences
- In March 2023, Puratos launched a new range of cleanInlabel emulsifiers aimed at enhancing texture and stability in bakery products while meeting consumer demands for transparency.
- In November 2023, Spartan Chemical announced the expansion of its product line to include new emulsifiers suitable for industrial applications, focusing on sustainability and performance.
- In January 2023, Stepan Company unveiled a new series of bioInbased emulsifiers aimed at improving product performance while reducing environmental impact.
- In April 2023, Lubrizol launched a new range of emulsifiers that enhance formulation stability in both food and personal care applications, emphasizing their commitment to innovation.
Market Concentration and Characteristics
The emulsifiers market is moderately concentrated, with a mix of large multinational corporations and smaller regional players contributing to its dynamic landscape. Key players such as Archer Daniels Midland, Cargill, BASF SE, and Kerry Group hold significant market shares due to their extensive portfolios, global presence, and strong customer networks. These companies focus on continuous innovation, particularly in developing bioInbased and cleanInlabel emulsifiers, to cater to growing consumer demand for sustainable and natural ingredients. Smaller players, meanwhile, capitalize on niche segments and regional demand, especially in emerging markets. The market is characterized by high regulatory scrutiny, a strong emphasis on sustainability, and evolving consumer preferences, which drive ongoing research and development efforts and strategic partnerships within the industry.
Report Coverage
The research report offers an inIndepth analysis based on Product Type, Source, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to shift towards bio-based emulsifiers, as consumer demand for natural and clean-label products grows, particularly in the food and cosmetics industries.
- Rapid urbanization and rising disposable incomes in emerging regions, such as Asia-Pacific and Latin America, will drive demand for emulsifiers across diverse applications, including food processing and personal care.
- Innovations in nanoemulsion technology and advanced encapsulation methods will enhance the effectiveness and versatility of emulsifiers, expanding their applications in pharmaceuticals and nutraceuticals.
- As regulatory bodies enforce stricter guidelines on food and cosmetic additives, companies will need to invest in research and development to ensure compliance while meeting performance standards.
- With a global push towards sustainability, manufacturers are expected to explore environmentally friendly production processes and renewable raw materials, aligning with eco-conscious consumer preferences.
- As the demand for functional foods with health benefits rises, emulsifiers will play a critical role in improving the stability and texture of products, such as fortified beverages and dietary supplements.
- The personal care industry’s demand for emulsifiers is projected to grow steadily, driven by an increasing focus on natural skincare and personal grooming products globally.
- Companies will prioritize innovation and product differentiation by developing multi-functional emulsifiers that offer added benefits, such as enhanced shelf life, improved texture, and increased nutritional value.
- Transparency in ingredient sourcing and production processes will become a key factor, pushing companies to label emulsifiers clearly and emphasize their natural or sustainable origins.
- The market is likely to see increased collaborations between manufacturers, research institutions, and technology providers, fostering innovation and enabling companies to expand their global reach and market share.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Processed and Convenience Foods
The increasing consumption of processed and convenience foods, especially in urbanized and emerging markets, is driving demand for emulsifiers that enhance texture, stability, and shelf life in products like bakery goods, sauces, and ice cream.
Expansion in Personal Care and Cosmetics
Emulsifiers are essential in personal care and cosmetic formulations such as lotions, creams, and shampoos, where they enable stable blends of oil and water. Rising consumer focus on self-care and natural ingredients is boosting demand for advanced and bio-based emulsifiers in this sector.
Shift Toward Natural and Bio-Based Ingredients
Consumer preference for clean-label, sustainable, and non-GMO products is accelerating the adoption of bio-based emulsifiers in both food and cosmetics, prompting manufacturers to innovate and reformulate products to meet these expectations.
Technological Advancements in Emulsifier Formulations
Innovations such as nanoemulsions and advanced encapsulation techniques are expanding the functional applications of emulsifiers in pharmaceuticals, nutraceuticals, and specialty foods, improving ingredient bioavailability and product performance.
Broadened Industrial Applications
Beyond food and personal care, emulsifiers are increasingly used in pharmaceuticals, agrochemicals, and industrial products, where they improve dispersion, stability, and effectiveness, supporting market growth across diverse end-use sectors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Emulsifiers Market?
What factors are driving the growth of the Emulsifiers Market?
Which regions are leading the Emulsifiers Market?
How are consumer preferences impacting the Emulsifiers Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Source
- 1.2.1 Bio-Based
- 1.2.2 Synthetic
- 1.3 By Application
- 1.3.1 Food and Beverages
- 1.3.2 Cosmetics and Personal Care Products
- 1.3.3 Oilfield Chemicals
- 1.3.4 Pharmaceuticals
- 1.3.5 Others
- 1.4 By Product Type
- 1.4.1 Lactic Esters of Fatty Acids
- 1.4.2 Lecithin
- 1.4.3 Mono & Di-glycerides of Fatty Acid
- 1.4.4 Esters of Monoglycerides of Fatty Acid
- 1.4.5 Polysorbates
- 1.4.6 Polyglycerol Esters
- 1.4.7 Polyglycerol Polyricinoleate
- 1.4.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 9,579.5 million → 2032: USD 12,810.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Emulsifiers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Emulsifiers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Emulsifiers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Emulsifiers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Emulsifiers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Emulsifiers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Emulsifiers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Emulsifiers Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 9,579.5 million → 2032: USD 12,810.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Emulsifiers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Source - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bio-Based
- 12.3.7.2 Synthetic
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Food and Beverages
- 12.4.7.2 Cosmetics and Personal Care Products
- 12.4.7.3 Oilfield Chemicals
- 12.4.7.4 Pharmaceuticals
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Lactic Esters of Fatty Acids
- 12.5.7.2 Lecithin
- 12.5.7.3 Mono & Di-glycerides of Fatty Acid
- 12.5.7.4 Esters of Monoglycerides of Fatty Acid
- 12.5.7.5 Polysorbates
- 12.5.7.6 Polyglycerol Esters
- 12.5.7.7 Polyglycerol Polyricinoleate
- 12.5.7.8 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Emulsifiers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Emulsifiers Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Emulsifiers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Emulsifiers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Archer Daniels Midland Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BASF SE
- 18.4 Cargill Incorporated
- 18.5 Kerry Group plc
- 18.6 Evonik Industries AG
- 18.7 Palsgaard A/S
- 18.8 Puratos Group
- 18.9 Stepan Company
- 18.10 The Dow Chemical Company
- 18.11 The Lubrizol Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

