
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Cable Management Systems Market Size 2023 | USD 17512.8 Million |
| Cable Management Systems Market, CAGR | 12.50% |
| Cable Management Systems Market Size 2032 | USD 50550.8 Million |
Market Insights
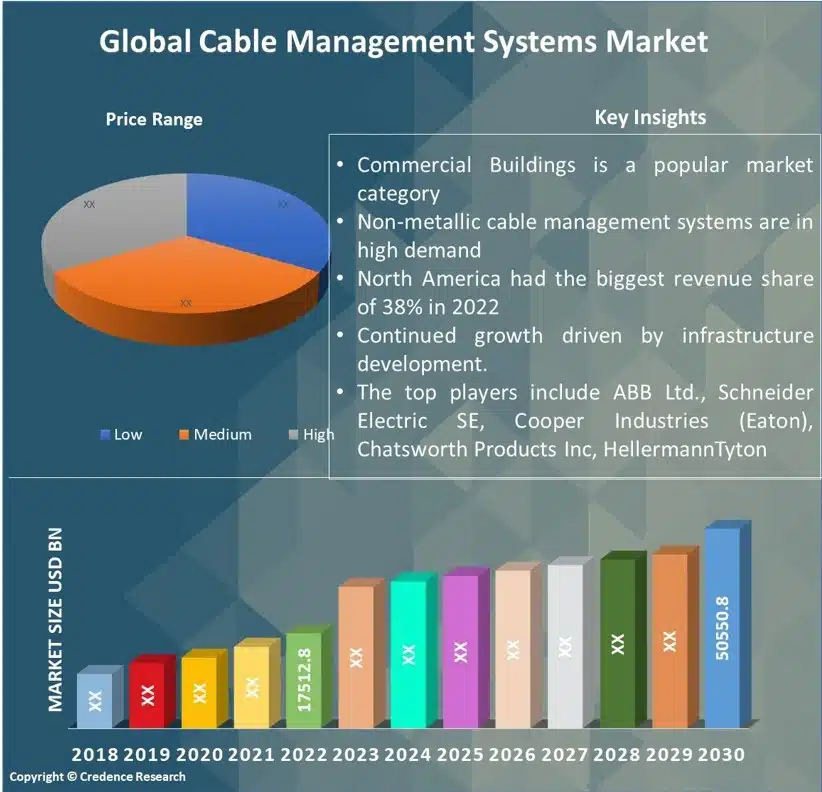
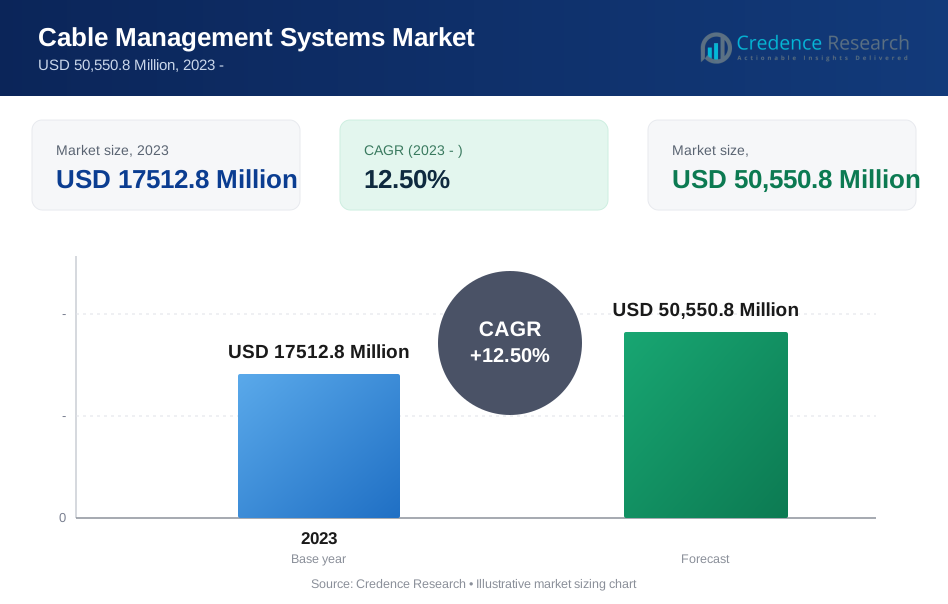
- The global demand for Cable Management Systems was valued at USD 17512.8 Million in 2023 and is expected to reach USD 50550.8 Million in 2032, growing at a CAGR of 12.50% between 2024 and 2032.
- Cable conduits are the market's largest contribution, with cable trays coming in second.
- Non-metallic cable management systems are in great demand in the business, and steel is a major component in the Cable Management Systems Market.
- Commercial Buildings is a popular market category, with Data Centres being the fastest expanding segment.
- IT and Telecom Spiralling need for data communication
- Spiralling demand for data connectivity, and another key sector, Support and Protection.
- Surface-Mounted Cable Management Systems have the most market share. Another popular market segment is Underfloor Cable Management Systems.
- Direct/Manufacturer Sales is the market's largest distributor, and it gives producers more control over the distribution process.
- The most prominent market segment is Fire-Resistant Cable Management Systems.
- North America had the largest revenue share of 38% in 2022, while Europe is predicted to have the highest CAGR over the projection period.
- Rising demand as a result of evolving technology promotes market expansion.
- Inconsistent raw material costs impedes market expansion.
Executive Summary
Market Definition
The Cable Management Systems Market includes goods and solutions for organizing, securing, and protecting cables in a variety of Materials. It covers a diverse range of devices such as cable trays, cable raceways, cable ties, cable clips, and other accessories that aid in cable routing and management. The market serves a variety of sectors, including residential, commercial, industrial, and data centres, where efficient cable management is critical for the safety, organization, and optimal performance of electrical and communication equipment.
Market Overview
The global Cable Management Systems Market has witnessed steady growth in recent years and is expected to grow at a CAGR of 12.50% between 2024 and 2032. The market was valued at USD 17512.8 million in 2023 and is expected to reach USD 50550.8 million in 2032.
The Cable Management Systems Market is seeing rapid expansion and is projected to continue in the coming years. The growing demand for efficient cable organization and management solutions across various sectors is propelling the market forward. Factors such as increased infrastructure development, the necessity for effective cable protection, and the growing usage of new technologies all help to drive market growth. Furthermore, the emphasis on workplace safety standards, combined with the rising complexity of cable networks, is driving demand for novel cable management solutions. The market provides a diverse selection of products and solutions adapted to specific installation requirements, resulting in a vibrant and competitive industry.
Segmentation by Type of Cable Management Systems
- The cable conduits segment is the market's largest contributor and is predicted to increase at a CAGR of 5.5% throughout the forecast period. A conduit system is a series of tubes that protect and route electrical cables in buildings and other structures.
- Cable trays can hold shielded electrical wiring for power distribution and communication. Because of its adaptability and flexibility, the cable tray industry has risen tremendously with increased technical awareness and innovation.
Segmentation by Material
- Non-metallic cable management systems are in high demand in the industry. These systems, such as PVC (Polyvinyl Chloride) and HDPE (High-Density Polyethylene), are widely used due to their versatility, low cost, and ease of installation.
- Steel is a prominent element in the Cable Management Systems Market. Steel cable management systems are renowned for their toughness and longevity. They are often utilized in heavy-duty applications where strength and load-bearing capabilities are required.
Segmentation by Application
- Commercial Buildings is a popular market category. Cable management systems are frequently employed in commercial buildings to organize and secure cables, resulting in more efficient and safe electrical installations.
- Data Centres are the fastest growing segment. With the growing demand for data storage and processing, data centres require reliable cable management solutions to manage the complicated network infrastructure and assure peak performance.
Segmentation by End-User Industry
- Spiralling demand for data communications and a growing need for high-performance data cabling in the IT and telecom industries are expected to drive market growth during the forecast period. The main segment of the telecommunications industry is made up of wired telecommunications carriers, who use management systems when establishing cable networks.
Segmentation by Product Function
- Routing and Securing is the dominant segment. This part focuses on correct cable routing and securing to enable efficient and orderly cable management across a variety of applications.
- Another significant sector is Support and Protection. This segment entails providing support structures and protective measures to avoid damage and extend the life of cables in various conditions.
Segmentation by Installation Type
- Surface-Mounted Cable Management Systems account for the greatest market share. These systems are commonly utilized in a variety of environments, including offices, residential complexes, and commercial spaces, where wires are organized and maintained on the surface of walls or ceilings.
- Another popular market sector is Underfloor Cable Management Systems.
Segmentation by Distribution Channel
- Direct/Manufacturer Sales is the market's major distributor. Manufacturers use this distribution channel to offer their products directly to customers, eliminating the need for intermediaries.
- Direct sales provide producers more control over the distribution process, allowing them to build direct ties with clients and offer specialized services.
Segmentation by Fire Rating
- The most popular market sector is Fire-Retardant Cable Management Systems. These systems are intended to inhibit the spread of fire by utilizing flame-resistant materials capable of withstanding high temperatures.
Segmentation by Region
- North America had the biggest revenue share of 38% in 2022.
- Europe is expected to have the highest CAGR over the forecast period.
- The rest of the world, including Latin America, the Middle East, and Africa, supplies the remaining demand for Cable Management Systems.
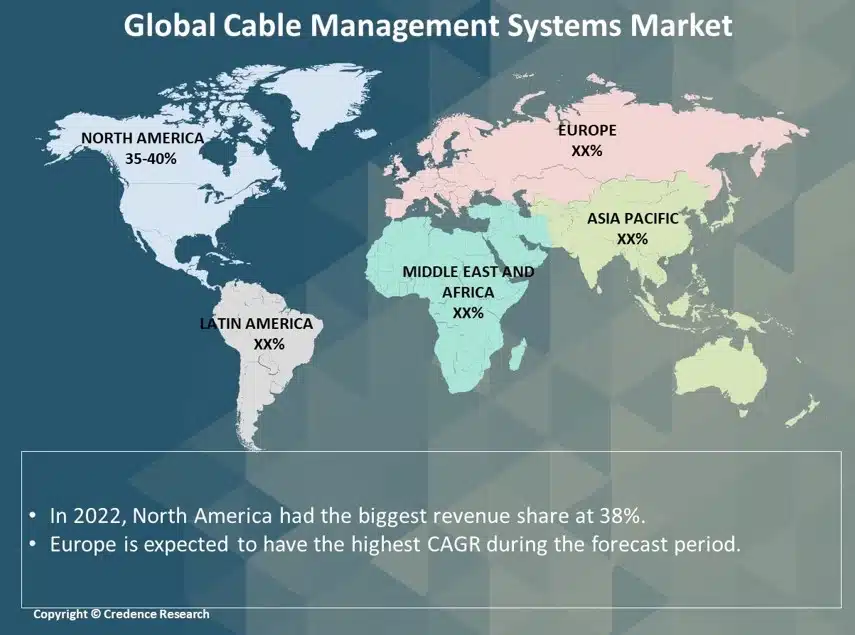
North America is the largest global market shareholder in 2022. Cable management devices have a large growth potential in North America in industries such as IT, construction, manufacturing, healthcare, and others. North America's lifestyle and living standards have also progressed, emphasizing the importance of proper cable management in the residential and commercial sectors, corporate offices, and other settings to ensure safety and minimal maintenance. The area's GDP growth rate contributes to the sluggish adoption of cable management technologies. North America is a major aerospace and space program region, which includes NASA and the USSR. Spiral wraps, lacing tapes, heat shrink tubes, and cable tie wraps are all essential components in the aerospace sector. High Voltage Direct Current (HVDC), HVAC (Heat, Ventilation, and Air Conditioning), MV (Medium Voltage), and other cable systems in submarines provide efficient power transfer between networks with wide coverage.
Europe is predicted to see the highest CAGR during the projection period. The European economy has been recovering since 2012, following the 2009 financial crisis, which hurt countries such as Germany, the United Kingdom, the Netherlands, Russia, and France. The headquarters of 195 of the 500 manufacturing companies on the Fortune Global 500 list are in Europe. Leading European cable management product providers such as Prysmian, Nexans, Legrand, and others operate on a global scale and offer a wide range of products to fulfill customer requirements. Leading economies from around the world, including Greece, Luxembourg, the Netherlands, France, Russia, and others, are helping to drive economic growth in Europe. Cable management products are popular in Europe for the home appliance, infrastructure, information End-User Industry, construction, and industrial industries.
Key Highlights of the Report
The global Cable Management Systems Market is segmented by Type of Cable Management Systems, Material, Applications, End-User Industry, Product Function, Installation Type, Distribution Channel, Fire Rating and region. In 2022, Surface-Mounted Cable Management Systems have the largest market share, and the most popular market segment is Fire-Retardant Cable Management Systems. Furthermore, Data Centres are the fastest growing area, and nonmetallic cable management systems are in high demand in the industry. Additionally, Direct/Manufacturer Sales is the market's primary distributor, with North America leading the market growth.
The market's primary drivers are increasing demand for efficient cable organization and management solutions across sectors, an emphasis on workplace safety laws and compliance, and the growing adoption of new technologies and infrastructure development. Furthermore, high initial installation and maintenance costs, limited knowledge and understanding of the need of appropriate cable management, and difficulties in retrofitting existing infrastructure with cable management systems are the significant limitations of the market.
Nonetheless, In 2022, North America will be the world's largest market shareholder. Cable management devices have a high growth potential in North American industries such as information technology, construction, manufacturing, and healthcare, among others. Furthermore, Europe is expected to have the greatest CAGR during the projection period.
What Are The Main Drivers Of The Global Cable Management Systems Market?
Several main factors are driving the cable management systems market. There is an increasing demand for effective cable organizing and management solutions across sectors. As technology advances, appropriate cable management becomes increasingly critical to guarantee that electrical and communication equipment work optimally and safely. Furthermore, there is a focus on workplace safety rules and compliance, which increases demand for effective cable management systems.
What Are The Major Challenges Faced By The Global Cable Management Systems Market?
While the Cable Management Systems Market is showing promising growth, there are a few factors to consider. One of the most significant problems is the high initial installation and maintenance expenses associated with deploying cable management systems. This may discourage some businesses from investing in these solutions, particularly smaller organizations with limited resources. Furthermore, there is a lack of awareness and understanding of the need of efficient cable management, which may impede market growth.
What Are The Growth Opportunities In The Global Cable Management Systems Market?
The Cable Management Systems Market provides numerous chances for growth and innovation. One of the significant prospects is the growing need for smart and automated cable management systems. As technology advances, including smart features into cable management systems can improve productivity and provide real-time monitoring and control. Another possibility is to expand into emerging areas and increase construction activity. As these markets expand, the demand for dependable and well-organized cable management systems will increase.
Market Drivers
The global Cable Management Systems Market is driven by several factors. The following are the key drivers of the global Cable Management Systems Market:
Rising Demand As A Result Of Advancing Technologies
Technological advancements have raised global demand for energy, high-speed connectivity, massive amounts of bandwidth, and data centralization. The demand for new HVDC cables and cable overheads has also surged dramatically. Effective cable management is critical for safe and efficient resource utilization. The growing public awareness of End-User Industry and its widespread use has pushed the cable management business forward.
Numerous Industrial Verticals
The cable management industry has grown significantly over time due to a growth in the number of Materials in Application sectors. Cable management products are used in a wide range of industries, including information End-User Industry, telecommunications, construction, infrastructure, healthcare, transportation, aerospace, maritime, and others. Cable trays, conduits, raceways, cable chains and reels, and other devices have a high market demand due to their distinct characteristics and functions.
Market Restraints
The global Cable Management Systems Market faces some challenges that may hinder its growth. These include the following:
Inconsistent Raw Material Costs
The market for cables and wires is quite large and diverse. The cable management market's direct end users include the IT, electricity, construction, and telecommunications industries. Copper, rubber, thermoplastics, aluminium, and other materials are common raw materials. Prices fluctuate due to the diverse distribution of raw material suppliers across areas. Changes in raw material prices lead to market instability, and some function as barriers in the worldwide cable management industry.
Opportunities
The global Cable Management Systems Market offers significant growth opportunities. These include the following:
Expansion Of The IT And Telecom Sector
The IT and telecoms industry remains dominant and will continue to grow, creating prospects for the cable management market. One of the world's leading sectors, they have a significant demand for cable management. Cable management products are widely utilized in the communication networks that connect two-thirds of the world's population. Cable trays, rack systems, IT infrastructure, data transmission, and other associated Materials are all experiencing growth in demand.
Competitive Landscape
Key Players
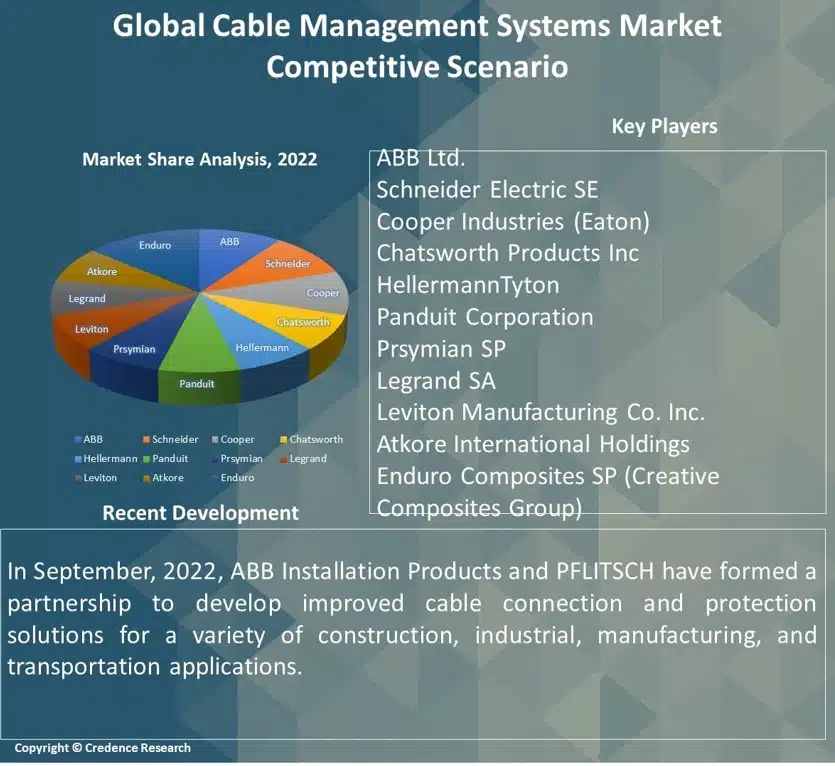
The global Cable Management Systems Market is highly competitive, with several key players. Some of the major players in the market and their market share are as follows:
- ABB Ltd.
- Schneider Electric SE
- Cooper Industries (Eaton)
- Chatsworth Products Inc
- HellermannTyton
- Panduit Corporation
- Prsymian SP
- Legrand SA
- Leviton Manufacturing Co. Inc.
- Atkore International Holdings
- Enduro Composites SP (Creative Composites Group)
These organizations prioritize product innovation, Cable Management Systems Centers expansion, and mergers and acquisitions to stay competitive.
The global Cable Management Systems Market's key players continually seek to stay ahead by offering new products and developments.
In January 2023, The Houdson Group has formed a new cooperation with Wibe Group to deliver specialized cable management solutions for corrosive and hazardous situations. This agreement is intended to see Wibe cable ladders and Mita Glass Reinforced Polymer (GRP) containment products supplied in the UK under 'Milton,' a new division of the Hudson Group.
In September 2022, ABB Ltd. announced that it would invest USD 13 million in its Installation Products Division's Iberville manufacturing plant in Saint-Jean-sur-Richelieu, Quebec, to increase production capacity and establish a research and development facility at its cable tray manufacturing centre.
Summary of Key Findings
- Growth of the IT and telecom sectors
- Market segmented by Type of Cable Management Systems, Material, Applications, End-User Industry, Product Function, Installation Type, Distribution Channel, Fire Rating and region.
- Surface-Mounted Cable Management Systems account for the largest market shar
- The most popular market sector is Fire-Retardant Cable Management Systems
- North America is leading market growth; the market is highly competitive with key players including ABB Ltd., Schneider Electric SE, Cooper Industries (Eaton), Chatsworth Products Inc, HellermannTyton, Panduit Corporation and Others.
Future Outlook
- Continued growth driven by infrastructure development.
- Increasing demand for advanced cable protection solutions.
- Adoption of innovative technologies for efficient cable management.
- Emphasis on workplace safety regulations driving market expansion.
- Growing complexity of cable networks boosting the need for organized solutions.
How CXOs Can Benefit from the Credence Research Cable Management Systems Market Report
The Credence Research Cable Management Systems Market Report provides CXOs with a comprehensive overview of the market, including:
- Market size and growth forecast: The report provides detailed estimates of the global Cable Management Systems Market size, segmented by Type of Cable Management Systems, Material, Applications, End-User Industry, Product Function, Installation Type, Distribution Channel, Fire Rating and region. It also includes forecasts for the market through 2032, based on key trends and drivers.
- Market segmentation: The report segments the Cable Management Systems Market by Type of Cable Management Systems, Material, Applications, End-User Industry, Product Function, Installation Type, Distribution Channel, Fire Rating and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape: The report profiles the key players in the Cable Management Systems Market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers: The report identifies and analyzes the key trends and drivers that are shaping the Cable Management Systems Market. This information can help CXOs to make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research Cable Management Systems Market Report to:
- Identify growth opportunities: The report can help CXOs to identify new growth opportunities in the Cable Management Systems Market. For example, it can provide insights into emerging technologies, market trends, and customer demands. This information can guide CXOs in identifying untapped market segments and developing strategies to capitalize on these opportunities.
- Make informed investment decisions: The report can help CXOs to make informed investment decisions about Cable Management Systems. For example, it provides valuable market insights, including market size, growth rate, competitive landscape, and key trends. This information can guide CXOs in evaluating investment opportunities and developing effective strategies for their businesses in the Cable Management Systems market.
- Develop competitive strategies: The report can help CXOs to develop competitive strategies for their Cable Management Systems businesses. For example, it provides in-depth analysis of market dynamics, including key players, market share, and competitive landscape. With this valuable information, CXOs can identify their strengths, weaknesses, and opportunities, allowing them to develop effective strategies to stay ahead in the Cable Management Systems market.
- Track market developments: The report can help CXOs to track market developments and stay ahead of the curve. For example, the report provides insights into the latest trends and innovations in the Cable Management Systems Market.
Overall, the Credence Research Cable Management Systems Market Report is a valuable resource for CXOs who are looking to gain a deeper understanding of the market and identify opportunities for growth.
Segmentation
By Type of Cable Management Systems:
- Cable Trays:
- Ladder Trays
- Wire Mesh Trays
- Solid Bottom Trays
- Channel Trays
- Cable Conduits
- Raceways:
- Surface-Mounted Raceways
- Flush-Mounted Raceways
- Cable Glands and Connectors
- Cable Lugs and Tools
- Cable Markers and Labels
- Cable Ties and Clips
- Cable Sleeves and Wraps
By Material:
- Metal Cable Management Systems
- Steel
- Aluminum
- Stainless Steel
- Non-Metallic Cable Management Systems
- PVC (Polyvinyl Chloride)
- HDPE (High-Density Polyethylene)
- Others
By Application:
- Commercial Buildings
- Data Centers
- Industrial Facilities
- Residential Buildings
- Others
By End-User Industry:
- IT and Telecom
- Manufacturing
- Energy and Utility
- Healthcare
- Mining
- Oil and Gas
- Transportation
- Others
By Product Function:
- Organizing and Sorting
- Support and Protection
- Routing and Securing
- Connection and Termination
By Installation Type:
- Surface-Mounted Cable Management Systems
- Underfloor Cable Management Systems
- Flush-Mounted Cable Management Systems
By Distribution Channel:
- Direct Sales/Manufacturer Sales
- Distributors
- E-commerce Platforms
By Fire Rating:
- Fire-Retardant Cable Management Systems
- Non-Fire-Retardant Cable Management Systems
By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancing Technology and Data Connectivity
The rapid adoption of new technologies and the spiraling need for high-speed data communication in sectors like IT, telecom, and data centers are driving demand for advanced cable management systems to ensure reliable and organized network infrastructure.
Infrastructure Development and Urbanization
Ongoing infrastructure projects and increased construction activity in commercial, industrial, and residential sectors are fueling the need for efficient cable management solutions to support complex electrical and communication networks.
Workplace Safety and Regulatory Compliance
Stricter workplace safety standards and regulations are compelling organizations to invest in cable management systems that reduce hazards, prevent accidents, and ensure compliance with fire and electrical safety codes.
Growth of Data Centers and Cloud Computing
The expansion of data centers, driven by the surge in cloud computing and digital services, is creating significant demand for robust cable management systems to handle dense cabling and maintain optimal performance and uptime.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global Cable Management Systems Market?
What is the expected growth rate of the Cable Management Systems Market between 2024 and 2032?
Which segment is leading the market share in terms of Type of Cable Management Systems?
Which Material segment governs the demand for Product Function?
Who are the major players in the global Cable Management Systems Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Steel
- 1.2.2 Aluminum
- 1.2.3 PVC (Polyvinyl Chloride)
- 1.2.4 HDPE (High-Density Polyethylene)
- 1.2.5 Stainless Steel
- 1.3 By Application
- 1.3.1 Commercial Buildings
- 1.3.2 Data Centers
- 1.3.3 Industrial Facilities
- 1.3.4 Residential Buildings
- 1.4 By Installation Type
- 1.4.1 Surface-Mounted Cable Management Systems
- 1.4.2 Underfloor Cable Management Systems
- 1.4.3 Flush-Mounted Cable Management Systems
- 1.5 By Type of Cable Management Systems
- 1.5.1 Cable Trays
- 1.5.2 Cable Conduits
- 1.5.3 Raceways
- 1.5.4 Cable Ties and Clips
- 1.5.5 Cable Sleeves and Wraps
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 17512.8 Million → 2032: USD 50,550.8 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cable Management Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cable Management Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cable Management Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cable Management Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cable Management Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cable Management Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cable Management Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cable Management Systems Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 17512.8 Million → 2032: USD 50,550.8 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cable Management Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Steel
- 12.3.7.2 Aluminum
- 12.3.7.3 PVC (Polyvinyl Chloride)
- 12.3.7.4 HDPE (High-Density Polyethylene)
- 12.3.7.5 Stainless Steel
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Commercial Buildings
- 12.4.7.2 Data Centers
- 12.4.7.3 Industrial Facilities
- 12.4.7.4 Residential Buildings
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Installation Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Surface-Mounted Cable Management Systems
- 12.5.7.2 Underfloor Cable Management Systems
- 12.5.7.3 Flush-Mounted Cable Management Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Type of Cable Management Systems - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Cable Trays
- 12.6.7.2 Cable Conduits
- 12.6.7.3 Raceways
- 12.6.7.4 Cable Ties and Clips
- 12.6.7.5 Cable Sleeves and Wraps
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cable Management Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cable Management Systems Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cable Management Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cable Management Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ABB Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Schneider Electric SE
- 18.4 Eaton (Cooper Industries)
- 18.5 Legrand SA
- 18.6 Panduit Corporation
- 18.7 HellermannTyton
- 18.8 Chatsworth Products Inc.
- 18.9 Atkore International Holdings
- 18.10 Leviton Manufacturing Co. Inc.
- 18.11 Prysmian Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

