
Market Overview:
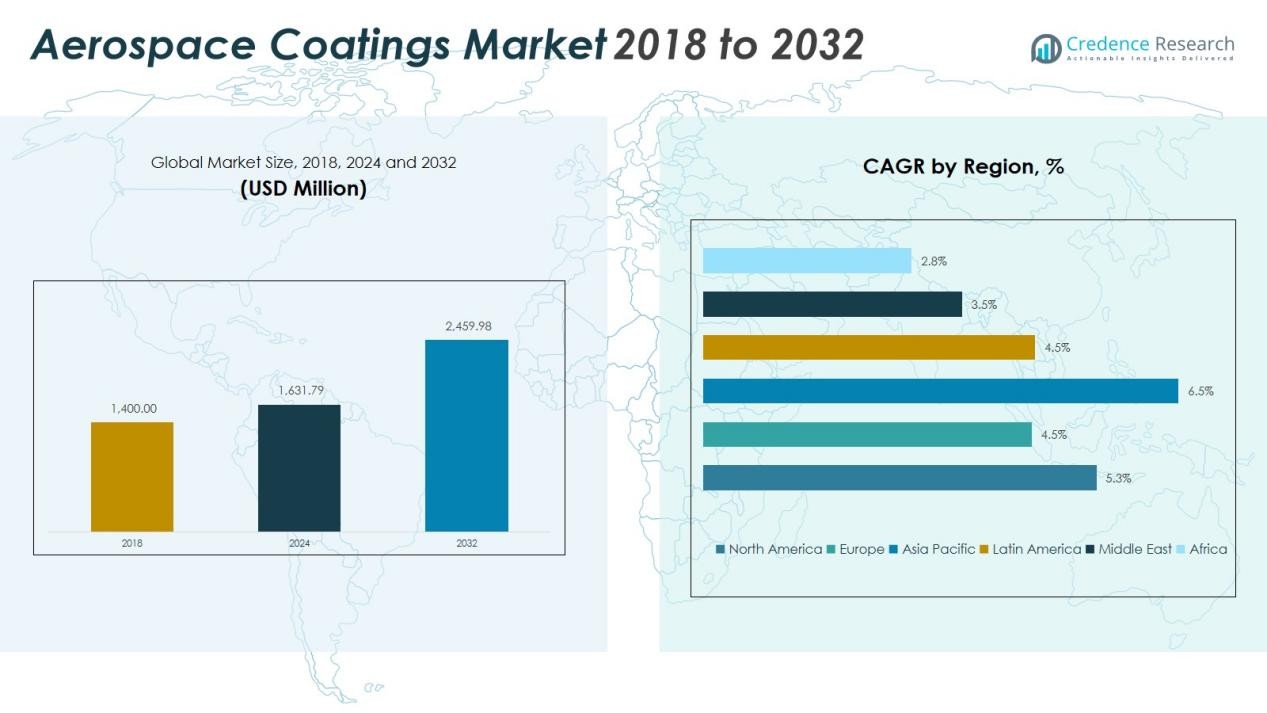
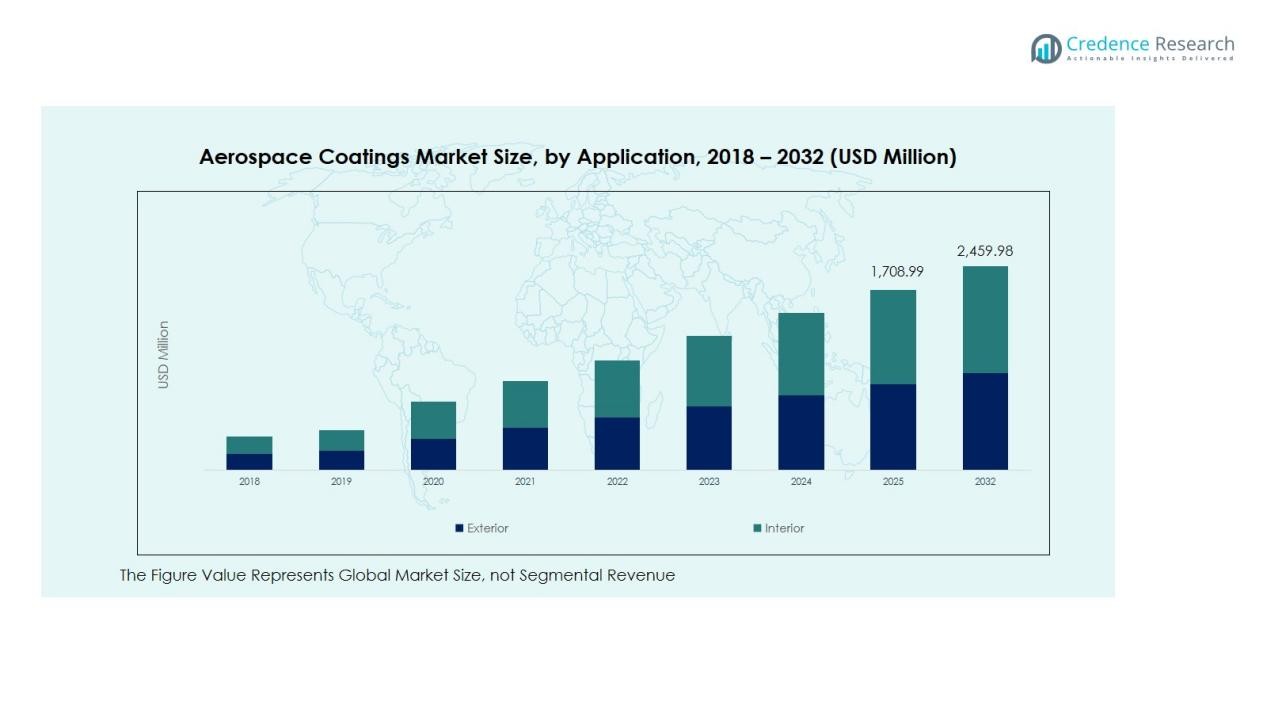
The Global Aerospace Coatings Market size was valued at USD 1,400 million in 2018 to USD 1,631.79 million in 2024 and is anticipated to reach USD 2,459.98 million by 2032, at a CAGR of 5.34% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aerospace Coatings Market Size 2024 | USD 1,631.79 Million |
| Aerospace Coatings Market, CAGR | 5.34% |
| Aerospace Coatings Market Size 2032 | USD 2,459.98 Million |
Growth is driven by increased production of commercial aircraft and expanding global air travel, which raise demand for coatings in both original equipment and maintenance sectors. Advancements in lightweight and eco-friendly coatings, coupled with stricter environmental regulations, are supporting product innovation. Rising military and space-craft applications are further driving adoption of coatings that provide superior corrosion resistance, durability, and thermal protection.
North America holds the largest share of the aerospace coatings market due to its strong aircraft manufacturing base and extensive maintenance, repair, and overhaul (MRO) operations. Europe follows, supported by technological innovation and regulatory emphasis on sustainable aviation materials. The Asia-Pacific region is expected to record the fastest growth, driven by expanding commercial aviation fleets in China and India and increasing regional MRO infrastructure.
Market Insights:
- The Global Aerospace Coatings Market was valued at USD 1,400 million in 2018, reached USD 1,631.79 million in 2024, and is projected to attain USD 2,459.98 million by 2032, expanding at a CAGR of 5.34% during the forecast period.
- North America holds 35% of the market share, driven by strong aircraft manufacturing, defense investments, and large MRO infrastructure led by Boeing and Lockheed Martin.
- Europe accounts for 25% of the share, supported by Airbus-led aerospace production, strict environmental compliance, and advanced coating technologies developed by AkzoNobel and Mankiewicz.
- Asia Pacific represents 28% of the share and remains the fastest-growing region due to expanding commercial aviation fleets, rising passenger traffic, and government-backed aircraft manufacturing initiatives in China and India.
- By segment, liquid coatings dominate with 40% share owing to their superior finish and widespread use in OEM applications, while the OEM category leads with 55% share driven by increasing aircraft deliveries and fleet modernization.
Market Drivers:
Rising Aircraft Production and Fleet Expansion Accelerating Coating Demand
The Global Aerospace Coatings Market benefits from growing aircraft production and fleet modernization across commercial and defense sectors. Increasing passenger traffic and new aircraft orders from major manufacturers such as Boeing and Airbus strengthen coating requirements for protection and performance. Airlines are investing in repainting and maintenance programs to improve fuel efficiency and visual appeal. It continues to gain traction as lightweight, high-durability coatings reduce maintenance costs and extend aircraft lifespan.
- For instance, Boeing reported a firm order backlog of over 5,500 commercial airplanes, specifically 5,595 at year-end 2024 [2, 3].
Technological Advancements in High-Performance and Eco-Friendly Coatings
Continuous innovation in coating formulations is a major growth driver. The market is witnessing increased adoption of nanotechnology-based coatings and advanced polyurethane systems that enhance corrosion and UV resistance. Demand for low-VOC, chrome-free, and waterborne coatings is rising due to stricter environmental standards. It supports aircraft manufacturers in meeting sustainability goals while maintaining high surface protection standards.
- For instance, PPG's PR-2940 epoxy syntactic paste adhesive (ESPA) for aircraft internal structures combines exceptional mechanical strength with flexibility and microcracking resistance across operating temperature ranges, enabling lightweight potency through honeycomb structure reinforcement in aircraft wings, galleys, and flooring-delivering significant performance and sustainability advantages through structural lightweighting.
Growing Maintenance, Repair, and Overhaul (MRO) Activities Enhancing Market Growth
Expanding MRO operations worldwide create strong opportunities for aerospace coating suppliers. Airlines and defense forces are extending aircraft service life through regular repainting and refurbishing. Increased air traffic drives faster turnaround needs for repainting operations. It helps MRO service providers use advanced coatings that ensure quicker application, reduced drying time, and long-lasting finishes.
Rising Defense Expenditure and Space Exploration Programs Fueling Demand
The defense and space sectors significantly influence market expansion. Growing investments in military aircraft, satellites, and spacecraft require specialized coatings for thermal stability and radiation resistance. Countries such as the U.S., China, and India are accelerating aerospace projects that demand high-performance coatings. It positions aerospace coatings as critical for mission safety, durability, and operational performance.
Market Trends:
Shift Toward Sustainable and High-Performance Coating Technologies
The Global Aerospace Coatings Market is witnessing a clear shift toward sustainable and high-performance formulations driven by stricter environmental regulations and operational efficiency goals. Manufacturers are developing chrome-free primers, waterborne systems, and eco-friendly polyurethane coatings that reduce VOC emissions while maintaining durability. The demand for lightweight coatings that enhance fuel efficiency and resist corrosion is increasing among aircraft manufacturers and MRO operators. It is also experiencing adoption of smart coatings capable of self-healing and detecting surface damage, which improves safety and maintenance efficiency. Nanotechnology-based coatings are gaining prominence due to their superior UV, abrasion, and temperature resistance properties. Sustainability commitments by major players, including PPG Industries and AkzoNobel, are encouraging industry-wide transitions toward greener production and lifecycle practices.
- For instance, AkzoNobel’s new generation waterborne basecoat technology introduced in early 2025, while marketed for car refinishes rather than aerospace applications, can achieve material savings of around 15% on average due to its high pigmentation and coverage in 1.5 layers.
Rising Adoption of Advanced Coating Application and Digital Technologies
Digital transformation and process automation are emerging as key trends in aerospace coating applications. Robotic and automated spray systems are reducing application time, improving uniformity, and lowering operational costs for aircraft manufacturers. It is also integrating digital monitoring tools that ensure consistency in coating thickness and quality during production and maintenance stages. Data-driven quality control methods enhance precision while minimizing waste and rework rates. Increasing use of 3D printing for aircraft components is prompting the development of specialized coatings tailored for additive manufacturing materials. Global collaborations among OEMs, coating suppliers, and aerospace research institutions are accelerating advancements in efficiency, performance, and sustainability. These developments position advanced coating and digital application technologies at the center of the industry’s modernization strategy.
- For instance, Aerobotix's robotic coating system for F-22 aircraft inlet duct maintenance achieved a 50% increase in first-pass yield and quality while reducing rework per aircraft, with the system's precision application enabling savings of approximately $40,000 per aircraft through reduced coating waste at $1,000 per gallon.
Market Challenges Analysis:
Stringent Environmental Regulations and High Compliance Costs
The Global Aerospace Coatings Market faces major challenges due to strict environmental and safety regulations governing VOC emissions and hazardous chemical use. Manufacturers must comply with evolving international standards such as REACH and EPA regulations, which restrict the use of heavy metals and solvent-based compounds. Meeting these norms demands investment in R&D and reformulation of existing products, increasing operational costs. It must balance performance expectations with compliance requirements without compromising coating durability. The need for advanced, eco-friendly alternatives also slows product approvals and extends development timelines. These factors create financial pressure on small and mid-sized manufacturers seeking to maintain competitiveness.
Complex Application Processes and High Production Costs
Applying aerospace coatings involves precision, skilled labor, and advanced equipment, which elevate production and maintenance costs. The multi-layer coating systems require controlled environments and strict adherence to temperature and humidity standards. It faces challenges in reducing downtime and achieving consistent quality during large-scale or MRO operations. High raw material costs, especially for specialty resins and pigments, further affect profitability. The shortage of trained applicators and technical experts limits efficiency in emerging regions. These complexities continue to challenge manufacturers and service providers striving for cost-effective and reliable coating performance.
Market Opportunities:
Expansion of Commercial Aviation and MRO Infrastructure in Emerging Economies
The Global Aerospace Coatings Market holds strong opportunities in emerging economies with expanding commercial aviation fleets. Rapid air traffic growth in Asia-Pacific, the Middle East, and Latin America is creating demand for new aircraft and maintenance services. Governments are investing in aviation infrastructure and MRO facilities to support fleet modernization and safety compliance. It benefits from this trend through increased requirements for corrosion-resistant, fuel-efficient, and aesthetically advanced coatings. Local manufacturing partnerships and technology transfers further enhance supply chain efficiency. Growing regional airline competition is also pushing carriers to adopt premium coatings that improve performance and reduce operational costs.
Rising Demand for Smart and Functional Coating Technologies
The market is moving toward functional coatings that extend beyond surface protection. Smart coatings with anti-icing, self-healing, and temperature-sensing properties offer significant innovation potential. It creates new opportunities for suppliers specializing in nanotechnology and advanced materials. Defense and space programs are adopting multifunctional coatings to enhance stealth, thermal resistance, and radiation protection. Demand for digitalized coating processes that integrate predictive maintenance tools is also growing. These advancements position high-performance and intelligent coatings as a key revenue growth frontier for the industry.
Market Segmentation Analysis:
By Product Type
The Global Aerospace Coatings Market is segmented into liquid, solvent-based, water-based, and powder coatings. Liquid coatings hold a dominant share due to their superior finish quality and ease of application across aircraft surfaces. Solvent-based variants remain preferred in heavy-duty aerospace maintenance for their durability and weather resistance. Water-based coatings are gaining traction with stricter VOC regulations and sustainability goals. It benefits from the shift toward powder coatings, which provide efficient coverage, minimal waste, and enhanced corrosion protection.
- For instance, PPG's Deft 03-GY-444 polyurethane topcoat, a MIL-PRF-85285E-compliant aerospace liquid coating system, provides exceptional corrosion protection and is capable of achieving performance that can exceed 1000 hours of salt spray exposure in specific test conditions, all while maintaining superior gloss retention and dimensional stability on aircraft exteriors.
By Application
The market is divided into exterior and interior applications. Exterior coatings lead the segment due to their critical role in protection against UV radiation, temperature extremes, and corrosion. They are widely used to maintain aerodynamic efficiency and improve fuel performance. Interior coatings focus on aesthetics, wear resistance, and fire safety in cabin components. It continues to see innovation in lightweight coatings that extend surface life while reducing maintenance downtime.
- For instance, Japan Airlines (JAL) applied O-Well Corporation's riblet-shaped coating to a Boeing 787-9 aircraft in January 2025, achieving a 0.24% drag reduction during cruising, which translates to annual fuel savings of 119 tons and CO2 emission reductions of 381 tons per aircraft.
By Industry Category
Based on industry category, the market is classified into OEM and MRO. The OEM segment dominates due to rising aircraft deliveries and production expansion by major manufacturers. The MRO segment shows strong growth driven by fleet modernization and refurbishing programs. It gains further momentum from the increasing lifespan of aircraft, fueling steady coating replacement demand.
Segmentations:
By Product Type
- Liquid
- Solvent-based
- Water-based
- Powder
By Application
- Exterior
- Interior
By Industry Category
- OEM
- MRO
By Resin Type
- Epoxy
- Polyurethane
- Others
By End User
- Commercial
- Military
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Aerospace Coatings Market size was valued at USD 516.46 million in 2018 to USD 594.78 million in 2024 and is anticipated to reach USD 895.44 million by 2032, at a CAGR of 5.3% during the forecast period. North America holds 35% of the total share of the Global Aerospace Coatings Market. The United States drives regional dominance through high aircraft production, robust MRO infrastructure, and strong defense spending. Leading manufacturers such as Boeing and Lockheed Martin create consistent demand for advanced coating systems. It benefits from the presence of key players including PPG Industries and Sherwin-Williams, which invest heavily in R&D for sustainable coatings. The region’s focus on eco-friendly technologies and digital maintenance solutions continues to accelerate market expansion.
Europe
The Europe Aerospace Coatings Market size was valued at USD 314.30 million in 2018 to USD 349.65 million in 2024 and is anticipated to reach USD 492.62 million by 2032, at a CAGR of 4.5% during the forecast period. Europe holds 25% of the global market share, led by countries such as Germany, France, and the UK. The region benefits from strong aerospace manufacturing supported by Airbus and other OEMs. Stringent environmental policies are driving adoption of waterborne and chrome-free coatings. It also witnesses steady demand from defense aviation modernization programs across NATO nations. Advanced coating technologies from AkzoNobel and Mankiewicz strengthen Europe’s position as a hub for sustainable aerospace coating innovation.
Asia Pacific
The Asia Pacific Aerospace Coatings Market size was valued at USD 398.30 million in 2018 to USD 481.94 million in 2024 and is anticipated to reach USD 791.62 million by 2032, at a CAGR of 6.5% during the forecast period. Asia Pacific holds 28% of the Global Aerospace Coatings Market share and is the fastest-growing region. Rising air passenger traffic in China, India, and Southeast Asia fuels demand for new aircraft and MRO services. It gains traction from expanding commercial aviation fleets and infrastructure investments. Regional governments are promoting domestic aircraft production, supporting long-term coating demand. Increasing partnerships between local and global manufacturers drive technology transfer and capacity expansion across the region.
Latin America
The Latin America Aerospace Coatings Market size was valued at USD 102.20 million in 2018 to USD 118.13 million in 2024 and is anticipated to reach USD 166.96 million by 2032, at a CAGR of 4.5% during the forecast period. Latin America holds 7% of the global market share, supported by growing MRO activities and airline modernization efforts. Brazil remains the primary hub, driven by Embraer’s operations and regional air transport expansion. It experiences increasing adoption of durable and cost-effective coatings that extend aircraft service life. Economic recovery and regional airline growth encourage maintenance investments. The demand for eco-compliant and high-performance coatings continues to rise across civil and defense aviation sectors.
Middle East
The Middle East Aerospace Coatings Market size was valued at USD 40.46 million in 2018 to USD 43.23 million in 2024 and is anticipated to reach USD 56.59 million by 2032, at a CAGR of 3.5% during the forecast period. The Middle East holds 3% of the global market share, anchored by strong airline operators such as Emirates and Qatar Airways. The region’s MRO facilities in the UAE and Saudi Arabia support consistent coating demand for large commercial fleets. It benefits from continued investments in aviation infrastructure and fleet expansion. The defense sector also contributes through modernization of aircraft and helicopters. Coating manufacturers are focusing on weather-resistant and high-gloss finishes suited to desert environments.
Africa
The Africa Aerospace Coatings Market size was valued at USD 28.28 million in 2018 to USD 44.06 million in 2024 and is anticipated to reach USD 56.75 million by 2032, at a CAGR of 2.8% during the forecast period. Africa holds 2% of the Global Aerospace Coatings Market share and is gradually emerging with increasing investments in aviation. South Africa and Egypt are leading contributors with expanding commercial and maintenance operations. It faces challenges of limited local manufacturing and higher import dependency for coating materials. Growing regional connectivity and airport modernization projects support gradual market expansion. Partnerships with global suppliers are improving product access and technical expertise across the continent.
Key Player Analysis:
- AkzoNobel N.V.
- PPG Industries, Inc.
- Sherwin-Williams
- Hentzen Coatings, Inc.
- Mankiewicz Gebr. & Co
- Axalta Coating Systems Ltd
- Saint-Gobain S.A.
- Henkel Corporation
- IHI Ionbond AG
- Zircotec Ltd
- LORD Corporation
- AHC Oberflächentechnik
- BryCoat Inc.
- NV Specialty Coatings
Competitive Analysis:
The Global Aerospace Coatings Market is characterized by strong competition among leading multinational and specialized coating manufacturers. Key participants include AkzoNobel N.V., PPG Industries, Inc., Sherwin-Williams, Hentzen Coatings, Inc., Mankiewicz Gebr. & Co, Axalta Coating Systems Ltd, Saint-Gobain S.A., Henkel Corporation, and IHI Ionbond AG. It is driven by innovation, quality, and compliance with stringent aerospace standards. Companies focus on developing eco-friendly, high-durability coatings that meet VOC and REACH regulations. Strategic alliances with aircraft OEMs and MRO providers enhance brand positioning and long-term contracts. Continuous investment in R&D, automation, and nanotechnology-based coatings supports product differentiation. Competition remains intense, with players emphasizing sustainability, performance, and customer service to maintain global market leadership.
Recent Developments:
- In June 2025, AkzoNobel signs an agreement to sell Akzo Nobel India Limited to the JSW Group for about €1.4 billion; closing anticipated in Q4 2025.
- In October 2025, AkzoNobel becomes exclusive supplier for solar-absorbing wall technology
Report Coverage:
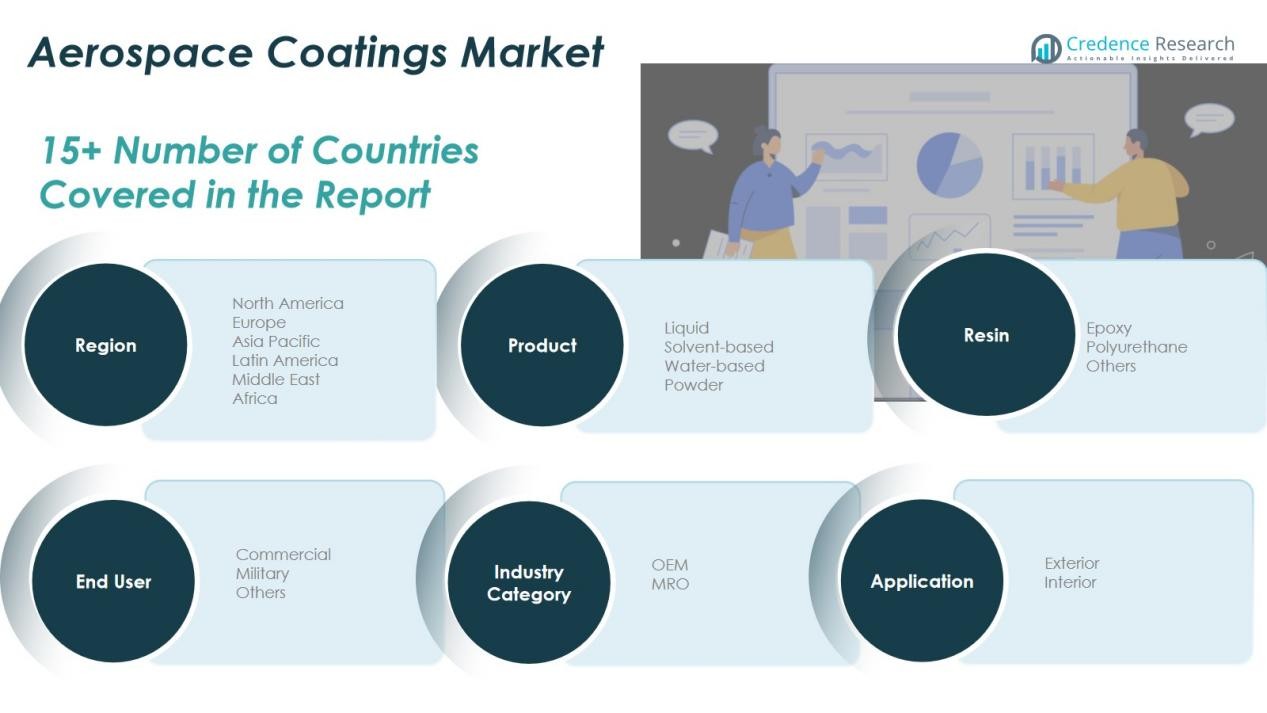
The research report offers an in-depth analysis based on Product Type, Application, Industry Category, Resin Type, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global Aerospace Coatings Market will witness steady growth driven by increasing aircraft production and fleet expansion across commercial and defense sectors.
- It will experience rising adoption of eco-friendly, low-VOC, and chrome-free coatings due to tightening environmental regulations.
- Technological innovation in nanocoatings and self-healing materials will enhance surface protection and operational efficiency.
- Expansion of MRO facilities in developing regions will create consistent demand for high-performance coating solutions.
- It will benefit from growing investments in lightweight coating systems that improve fuel efficiency and reduce maintenance costs.
- Digitalization and automation in coating application processes will improve precision, reduce waste, and enhance productivity.
- Defense and space programs will drive demand for advanced coatings offering thermal stability, stealth, and corrosion resistance.
- Partnerships between OEMs and coating manufacturers will increase, ensuring tailored solutions for evolving aircraft designs.
- It will see a growing shift toward waterborne and powder coatings aligned with sustainability goals.
- Rising air passenger traffic and infrastructure development in emerging economies will sustain long-term market expansion.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Aircraft Production and Fleet Expansion
Increasing global air travel and new aircraft orders from major manufacturers like Boeing and Airbus are driving demand for aerospace coatings, both for original equipment and ongoing maintenance. Airlines are investing in repainting and maintenance programs to improve fuel efficiency and extend aircraft lifespan, further boosting coating consumption.
Technological Advancements in High-Performance and Eco-Friendly Coatings
Continuous innovation in coating formulations, including nanotechnology-based and low-VOC systems, is enabling superior corrosion and UV resistance while meeting stricter environmental regulations. These advancements help manufacturers achieve sustainability goals and maintain high surface protection standards.
Expansion of MRO Activities
The growth of maintenance, repair, and overhaul (MRO) operations worldwide is increasing demand for advanced coatings that offer quicker application, reduced drying time, and long-lasting finishes. Airlines and defense forces are extending aircraft service life through regular repainting and refurbishing, creating ongoing opportunities for coating suppliers.
Rising Defense and Space Sector Investments
Growing investments in military aircraft, satellites, and spacecraft require specialized coatings for thermal stability, radiation resistance, and durability. Countries such as the U.S., China, and India are accelerating aerospace projects, driving demand for high-performance coatings critical to mission safety and operational performance.
Shift Toward Sustainable and Lightweight Coating Technologies
Stricter environmental regulations and the need for operational efficiency are pushing the adoption of chrome-free, waterborne, and powder coatings. Lightweight coatings that enhance fuel efficiency and resist corrosion are increasingly favored by aircraft manufacturers and MRO operators, supporting long-term market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
Which is the leading regional market for Aerospace Coatings?
What is the major growth hindering factors for global Aerospace Coatings market?
Which is major segment in Aerospace Coatings market by application?
Which is major segment in Aerospace Coatings market by materials?
How COVID 19 Impacted Aerospace Coatings Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Resin Type
- 1.2.1 Epoxy
- 1.2.2 Polyurethane
- 1.2.3 Others
- 1.3 By Application
- 1.3.1 Exterior
- 1.3.2 Interior
- 1.4 By Product Type
- 1.4.1 Liquid
- 1.4.2 Solvent-based
- 1.4.3 Water-based
- 1.4.4 Powder
- 1.5 By Industry Category
- 1.5.1 OEM
- 1.5.2 MRO
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 1,631.79 million → Forecast year: USD 2,459.98 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aerospace Coatings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aerospace Coatings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aerospace Coatings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aerospace Coatings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aerospace Coatings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aerospace Coatings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aerospace Coatings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aerospace Coatings Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 1,631.79 million → Forecast year: USD 2,459.98 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aerospace Coatings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Resin Type - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Epoxy
- 12.3.7.2 Polyurethane
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Exterior
- 12.4.7.2 Interior
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Liquid
- 12.5.7.2 Solvent-based
- 12.5.7.3 Water-based
- 12.5.7.4 Powder
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Industry Category - Market Size and Forecast
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast
- 12.6.4 Volume Forecast
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 OEM
- 12.6.7.2 MRO
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aerospace Coatings End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aerospace Coatings Geographic Market Outlook
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aerospace Coatings Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aerospace Coatings Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AkzoNobel N.V.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 PPG Industries, Inc.
- 18.4 Sherwin-Williams
- 18.5 Hentzen Coatings, Inc.
- 18.6 Mankiewicz Gebr. & Co
- 18.7 Axalta Coating Systems Ltd
- 18.8 Saint-Gobain S.A.
- 18.9 Henkel Corporation
- 18.10 IHI Ionbond AG
- 18.11 Zircotec Ltd
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

