
Market Overview
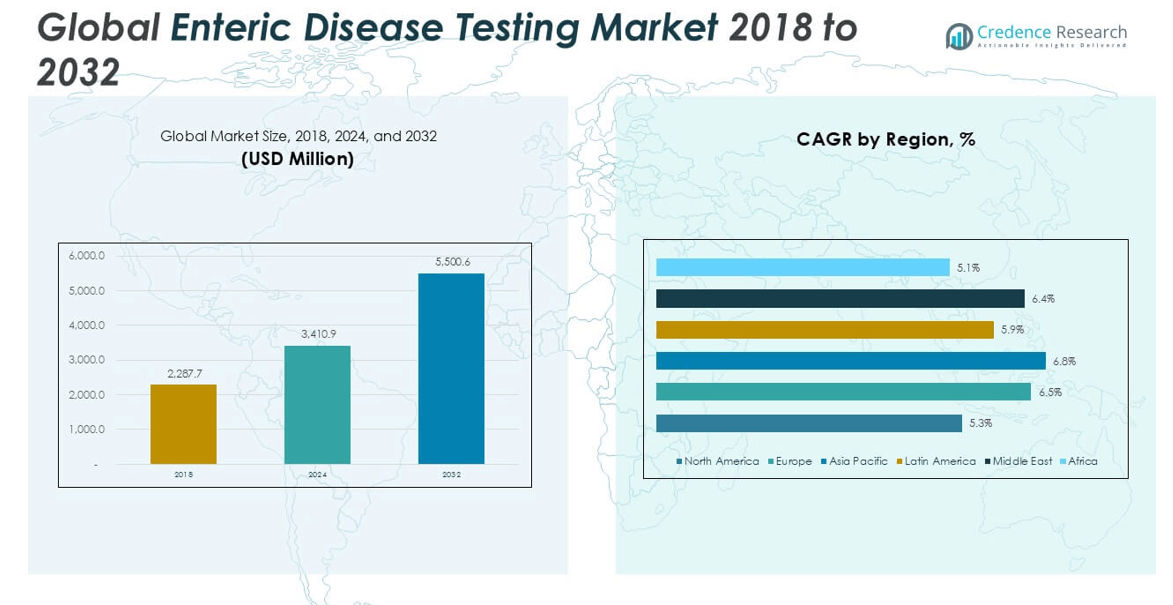
The Global Enteric Disease Testing Market is projected to grow from USD 3,410.9 million in 2024 to an estimated USD 5,500.6 million by 2032, registering a compound annual growth rate (CAGR) of 6.13% from 2025 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Enteric Disease Testing Market Size 2024 | USD 3,410.9 million |
| Enteric Disease Testing Market, CAGR | 6.13% |
| Enteric Disease Testing Market Size 2032 | USD 5,500.6 million |
Key market drivers include rising prevalence of enteric infections such as Salmonella, E. coli, and Campylobacter, along with increased government initiatives to strengthen disease surveillance systems. Trends such as rapid adoption of molecular diagnostic methods and point-of-care testing are streamlining the diagnosis and management of enteric diseases. There is also a shift toward multiplex assays and automation in laboratories, which enhances test accuracy and reduces turnaround time, supporting wider adoption in clinical settings.
Geographically, North America holds a significant share of the market due to advanced healthcare infrastructure, heightened awareness, and strong regulatory backing for infectious disease control. Asia Pacific is expected to witness the fastest growth during the forecast period owing to rising healthcare investments, increasing disease burden, and expanding diagnostic capabilities. Key players in the market include bioMérieux SA, Thermo Fisher Scientific Inc., Becton, Dickinson and Company, Abbott Laboratories, and DiaSorin S.p.A., who are focusing on product innovation, strategic collaborations, and regional expansion to strengthen their market position
Market Insights
- The Global Enteric Disease Testing Market is projected to grow from USD 3,410.9 million in 2024 to USD 5,500.6 million by 2032, at a CAGR of 6.13%.
- Rising prevalence of foodborne and waterborne infections fuels demand for accurate and rapid enteric disease diagnostics worldwide.
- Government initiatives to enhance disease surveillance and public health awareness significantly drive market expansion.
- High costs of advanced molecular diagnostic technologies limit adoption in low-resource and developing regions.
- North America dominates the market with robust healthcare infrastructure and strong regulatory frameworks supporting diagnostic growth.
- Asia Pacific shows the fastest market growth due to rising disease burden, increasing healthcare investments, and expanding diagnostic capabilities.
- Market players focus on technological innovation and strategic collaborations to address unmet diagnostic needs and expand regional presence.
Market Drivers
Rising Incidence of Waterborne and Foodborne Infections Fueling Diagnostic Demand
The Global Enteric Disease Testing Market is significantly driven by the increasing incidence of foodborne and waterborne illnesses worldwide. Contaminated food and water remain leading sources of enteric pathogens, including E. coli, Salmonella, Shigella, and Campylobacter. Developing countries continue to struggle with poor sanitation and limited access to clean drinking water, leading to frequent outbreaks. Even in developed nations, lapses in food safety protocols contribute to recurring infections. This growing disease burden is prompting public health authorities to expand diagnostic screening programs. The market is benefiting from the push to detect and manage infections early to reduce disease transmission and healthcare costs.
- For instance, the World Health Organization reported that in 2023, over 600 million cases of foodborne illnesses were recorded globally, with more than 420,000 deaths attributed to contaminated food and water, underscoring the urgent need for enhanced diagnostic capabilities.
Government Surveillance Initiatives and Health Regulations Supporting Market Growth
Governments across multiple regions are enforcing tighter health regulations and improving surveillance systems to manage the spread of enteric diseases. Initiatives by agencies such as the WHO and CDC emphasize early detection and robust reporting of gastrointestinal infections. These programs are encouraging hospitals and diagnostic labs to adopt advanced enteric disease testing solutions. Investment in national disease monitoring frameworks and laboratory infrastructure is increasing the market’s reach. Public-private partnerships are also playing a key role in funding the development and distribution of reliable diagnostic kits. These efforts are strengthening the capacity of health systems to respond to outbreaks effectively.
- For instance, according to a 2023 CDC report, the United States increased its enteric disease surveillance network to cover over 2,500 laboratories nationwide, leading to the detection and reporting of more than 1.3 million laboratory-confirmed enteric infections that year.
Technological Advancements Enhancing Accuracy and Speed of Testing
Advancements in molecular diagnostics, multiplex PCR assays, and point-of-care technologies are transforming enteric disease testing. These innovations allow for rapid, accurate identification of multiple pathogens from a single sample, improving clinical outcomes. Automation and miniaturization of equipment have reduced turnaround times and lowered error rates in laboratories. The market is experiencing higher adoption of DNA-based detection methods, particularly in regions with strong R\&D capabilities. These technologies also support large-scale screening during outbreak situations. The integration of AI and machine learning in diagnostic platforms is expected to further boost performance and precision.
Growing Healthcare Awareness and Diagnostic Penetration in Emerging Economies
In emerging markets, rising healthcare awareness and improving access to diagnostic services are expanding the customer base for enteric disease testing. Governments and NGOs are investing in public education campaigns that emphasize early diagnosis and treatment. Urbanization and growing middle-class populations are driving the demand for improved healthcare services, including laboratory diagnostics. It is also seeing demand rise due to the expansion of insurance coverage and availability of decentralized testing facilities. Manufacturers are targeting these markets with affordable, easy-to-use diagnostic kits tailored for low-resource settings. This shift is unlocking new opportunities and reshaping the competitive landscape in the Global Enteric Disease Testing Market.
Market Trends
Increased Adoption of Molecular Diagnostics Driving Accuracy and Speed
The shift from conventional culture methods to molecular diagnostics is a defining trend in the Global Enteric Disease Testing Market. Techniques such as real-time PCR, nucleic acid amplification, and sequencing offer faster and more precise pathogen identification. These methods reduce the diagnostic timeline from days to hours, helping healthcare providers initiate timely treatment. Laboratories are favoring multiplex PCR assays that detect multiple pathogens in a single test, enhancing efficiency and cost-effectiveness. This trend is gaining traction across both public health and private diagnostic labs. It is positioning molecular diagnostics as the preferred approach for routine and outbreak-related testing.
- For instance, over 15,000,000 multiplex PCR tests are used annually in public and private laboratories worldwide, with molecular diagnostics reducing the average diagnostic time to just 24 hours for enteric pathogens.
Rise of Point-of-Care and Decentralized Testing Solutions
Point-of-care (POC) testing is gaining momentum due to its ability to deliver rapid results in resource-limited settings. In rural or remote regions, where access to centralized labs is limited, POC solutions are filling critical diagnostic gaps. Portable, user-friendly devices are becoming more available and allow healthcare workers to conduct tests closer to the patient. The Global Enteric Disease Testing Market is benefiting from this trend as manufacturers develop compact systems that require minimal training. Rapid diagnostic tests (RDTs) are also enabling quick screening during disease outbreaks and emergency scenarios. It is reinforcing efforts to detect and control infections early in underserved areas.
- For instance, global surveys report that more than 1,200,000 point-of-care testing devices have been deployed worldwide, with over 80,000,000 rapid diagnostic tests conducted annually during enteric disease outbreaks and emergencies.
Integration of Automation and Digital Tools in Laboratory Workflows
Automation in diagnostic laboratories is improving testing throughput, accuracy, and consistency. Automated sample processing, data entry, and reporting reduce human error and speed up laboratory operations. Digital tools such as laboratory information management systems (LIMS) and cloud-based data sharing platforms are streamlining workflow management. The market is seeing wider integration of artificial intelligence (AI) for result interpretation and predictive analytics. These technologies help labs manage growing test volumes while maintaining quality standards. It is encouraging larger healthcare systems to adopt high-throughput testing platforms for routine diagnostics and public health surveillance.
Growing Emphasis on Syndromic Testing Panels for Better Clinical Insights
Syndromic testing panels are gaining popularity for enteric diseases due to their comprehensive approach in identifying multiple causative agents based on symptoms. These panels provide clinicians with quicker, actionable insights, particularly in cases where symptoms overlap among pathogens. The Global Enteric Disease Testing Market is aligning with this trend by offering diagnostic kits that cover bacterial, viral, and parasitic pathogens in a single assay. This approach supports more accurate clinical decisions and helps reduce unnecessary antibiotic use. Hospitals and laboratories are increasingly incorporating these panels into their standard protocols. It is enhancing diagnostic precision while supporting antimicrobial stewardship initiatives.
Market Challenges
High Cost of Advanced Diagnostics Limiting Accessibility in Low-Resource Settings
The high cost of molecular and multiplex diagnostic technologies presents a significant barrier in the Global Enteric Disease Testing Market. Many healthcare systems, particularly in low- and middle-income countries, struggle to afford advanced testing platforms and reagents. Budget constraints restrict the adoption of high-throughput systems in public health labs, limiting early detection capabilities. It faces further challenges due to the need for skilled personnel to operate complex equipment. Smaller clinics and rural health centers often rely on outdated or less accurate methods. This cost barrier widens the diagnostic gap between developed and developing regions.
- For instance, in 2024, a survey by an international health agency found that over 5,200 public health laboratories in Africa and Southeast Asia were unable to implement multiplex PCR testing for enteric diseases due to equipment costs exceeding $45,000 per unit, with more than 3,000 rural clinics continuing to use manual stool microscopy as their primary diagnostic method, according to government procurement data and laboratory capacity assessments.
Limited Infrastructure and Inconsistent Regulatory Frameworks Hindering Market Expansion
Inadequate laboratory infrastructure and inconsistent regulatory standards hinder uniform growth across global markets. The Global Enteric Disease Testing Market encounters operational delays where diagnostic labs lack automation, biosafety, or proper waste disposal mechanisms. Fragmented regulatory policies in emerging markets lead to delays in product approvals and market entry for diagnostic manufacturers. It also slows down innovation and cross-border collaborations. Variability in disease reporting and data quality across regions affects surveillance accuracy. These limitations reduce the overall efficiency of testing programs and weaken public health response systems.
Market Opportunities
Expansion of Diagnostic Services in Emerging Economies Creating Growth Potential
Rapid urbanization, rising income levels, and improving healthcare access are opening new opportunities for diagnostic expansion in emerging markets. Governments in Asia Pacific, Latin America, and Africa are investing in healthcare infrastructure and national disease surveillance programs. These initiatives create demand for reliable, affordable, and scalable enteric disease testing solutions. The Global Enteric Disease Testing Market stands to benefit as diagnostic manufacturers target underserved populations with portable and easy-to-use testing kits. It can gain traction through strategic collaborations with local healthcare providers and public health agencies. These developments are expected to support long-term market growth across low- and middle-income regions.
Technological Innovation Driving Development of Next-Generation Testing Platforms
Ongoing advancements in molecular diagnostics, AI integration, and biosensor technologies offer significant growth prospects for the market. Companies are focusing on miniaturized, faster, and multiplex testing systems that reduce turnaround times and improve accuracy. The demand for syndromic testing panels and smart diagnostic tools is rising in both clinical and point-of-care settings. The Global Enteric Disease Testing Market can capitalize on this trend by launching versatile platforms tailored to diverse healthcare environments. It has an opportunity to lead in digital diagnostics through cloud-based solutions and real-time disease tracking. These innovations can enhance response speed during outbreaks and strengthen global health security.
Market Segmentation Analysis
By Test Type
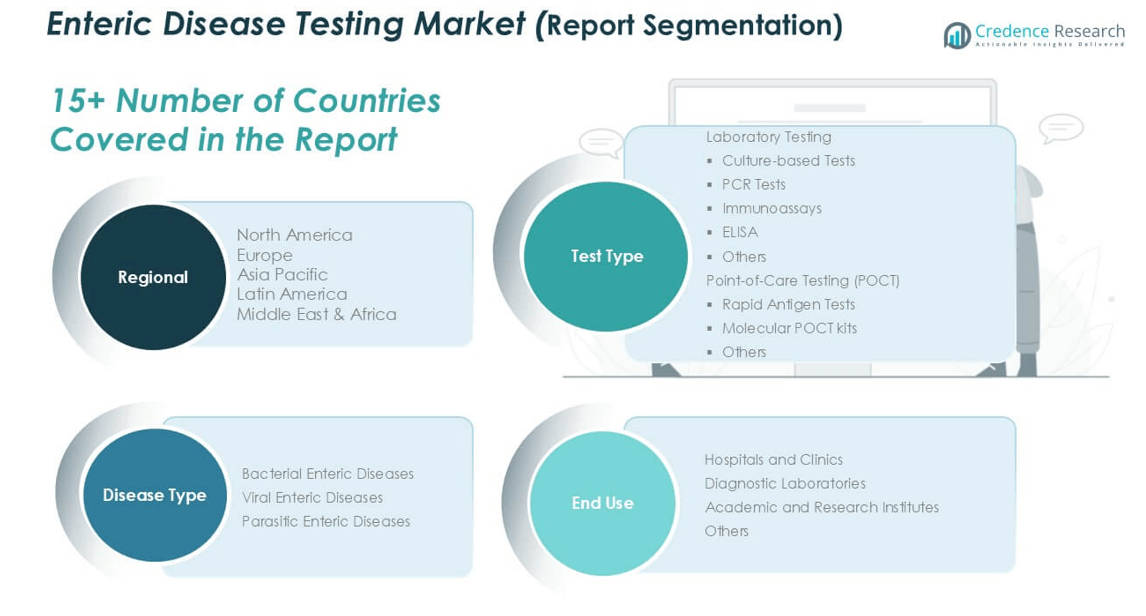
The Global Enteric Disease Testing Market is segmented by test type into laboratory testing and point-of-care testing (POCT). Laboratory testing dominates the market due to its high accuracy and reliability, with key methods including culture-based tests, PCR tests, immunoassays, and ELISA. PCR tests are gaining strong traction owing to their precision and speed in detecting multiple pathogens. Immunoassays and ELISA are widely used for detecting antigens and antibodies in clinical samples. POCT is emerging as a fast-growing segment, driven by the need for rapid diagnosis in remote and resource-limited settings. Rapid antigen tests and molecular POCT kits are expanding access to diagnostics and reducing turnaround times, especially during outbreaks.
- For instance, in 2024, the U.S. Centers for Disease Control and Prevention reported that over 3,200,000 laboratory-based enteric disease tests-including PCR, culture, and ELISA-were performed in accredited clinical laboratories across the United States, reflecting the scale and reliance on laboratory diagnostics for enteric infections.
By Disease Type
The market is categorized by disease type into bacterial, viral, and parasitic enteric diseases. Bacterial enteric diseases account for the largest share, driven by high prevalence of infections such as Salmonella, E. coli, and Shigella. Diagnostic demand remains strong due to frequent foodborne outbreaks and the need for quick identification of resistant strains. Viral enteric diseases, including norovirus and rotavirus, represent a significant share, particularly in pediatric populations. Parasitic diseases, although less frequent, maintain steady demand in tropical and low-sanitization regions. The market continues to develop advanced diagnostic panels that detect multiple disease types efficiently.
- For instance, a 2024 global health report indicated that over 120,000 laboratory-confirmed cases of parasitic enteric diseases were recorded in endemic regions, underscoring the ongoing need for advanced diagnostic panels capable of detecting multiple pathogens efficiently.
By End Use
The market is segmented by end use into hospitals and clinics, diagnostic laboratories, academic and research institutes, and others. Hospitals and clinics dominate the market due to high patient footfall and reliance on in-house testing capabilities. Diagnostic laboratories contribute significantly, offering specialized services and high-throughput capacity. Academic and research institutes support innovation in testing technologies and pathogen surveillance. The “others” segment includes NGOs and public health programs that conduct community-level screening and outbreak response. It remains an important channel for reaching underserved populations and expanding market reach.
Segments
Based on Test Type
- Laboratory Testing
- Culture-based Tests
- PCR Tests
- Immunoassays
- ELISA
- Others
- Point-of-Care Testing (POCT)
- Rapid Antigen Tests
- Molecular POCT kits
- Others
Based on Disease Type
- Bacterial Enteric Diseases
- Viral Enteric Diseases
- Parasitic Enteric Diseases
Based on End Use
- Hospitals and Clinics
- Diagnostic Laboratories
- Academic and Research Institutes
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Enteric Disease Testing Market
The North America Enteric Disease Testing Market is a key contributor, valued at USD 1,114.79 million in 2024 and expected to reach USD 1,693.10 million by 2032, registering a CAGR of 5.3%. It holds approximately 30.3% regional market share in 2024, reflecting the region’s strong healthcare infrastructure and advanced diagnostic technologies. Widespread adoption of molecular diagnostics and government initiatives to control foodborne illnesses support steady demand. The presence of major diagnostic companies and continuous innovation also strengthen the market. It benefits from high public health awareness and efficient disease surveillance systems. North America remains a strategic market for product launches and clinical research in enteric disease testing.
Europe Enteric Disease Testing Market:
Europe’s enteric disease testing market is valued at USD 760.73 million in 2024 and projected to grow to USD 1,265.15 million by 2032, exhibiting a CAGR of 6.5%. This region commands around 20.7% regional market share in 2024. It experiences growth due to stringent food safety regulations and expanding healthcare spending. Countries like Germany, France, and the UK drive demand with their focus on advanced diagnostics and outbreak prevention. Public health agencies prioritize early pathogen detection, fueling market expansion. The growing adoption of point-of-care testing and syndromic panels further boost market prospects. Europe continues to enhance diagnostic capabilities through investments in laboratory infrastructure.
Asia Pacific Enteric Disease Testing Market:
The Asia Pacific Enteric Disease Testing Market reaches USD 941.22 million in 2024, with forecasts estimating USD 1,595.18 million by 2032 and a CAGR of 6.8%. It represents approximately 25.6% regional market share in 2024. Rising prevalence of enteric infections combined with increasing healthcare infrastructure investments propel growth. China, India, Japan, and Australia serve as major contributors due to large populations and improving diagnostic adoption. Governments emphasize disease surveillance programs, increasing demand for accurate testing solutions. The expanding middle class and urbanization also enhance healthcare service utilization. Manufacturers target this region with affordable and easy-to-use diagnostic kits.
Latin America Enteric Disease Testing Market:
Latin America’s market is valued at USD 340.31 million in 2024 and expected to reach USD 539.06 million by 2032, growing at a CAGR of 5.9%. It holds about 9.3% regional market share in 2024. Brazil and Mexico lead the market with increasing government focus on controlling waterborne diseases. Healthcare modernization and rising awareness contribute to expanding testing adoption. The market faces opportunities due to rising investments in diagnostic laboratories and public health surveillance. It continues to benefit from initiatives aimed at improving sanitation and disease control. Growing demand for rapid and multiplex testing solutions drives progress.
Middle East Enteric Disease Testing Market:
The Middle East market reaches USD 187.26 million in 2024 and is projected to grow to USD 308.59 million by 2032, registering a CAGR of 6.4%. It accounts for approximately 5.1% regional market share in 2024. Increasing public health concerns and investments in healthcare infrastructure are key growth drivers. Countries like Saudi Arabia and the UAE are expanding diagnostic capabilities through government support and private sector participation. The rising prevalence of enteric diseases due to population growth fuels market demand. It benefits from increasing adoption of rapid diagnostic tests and molecular techniques. Expanding healthcare access remains a critical factor for growth.
Africa Enteric Disease Testing Market:
Africa’s enteric disease testing market is valued at USD 66.61 million in 2024 and is expected to reach USD 99.56 million by 2032, with a CAGR of 5.1%. It holds roughly 1.8% regional market share in 2024. The market growth stems from rising incidences of enteric infections and improving diagnostic infrastructure. Countries such as South Africa, Nigeria, and Kenya are expanding healthcare services and disease surveillance programs. It faces challenges related to limited resources but benefits from increasing international aid and partnerships. Demand for affordable and rapid testing solutions is growing. Efforts to strengthen laboratory networks contribute to market development.
Key players
- Abbott
- Bio-Rad Laboratories
- BD (Becton, Dickinson and Company)
- Biomerica
- Biomérieux
- Cepheid
- Coris Bioconcept
- DiaSorin S.p.A.
- Quest Diagnostics Incorporated
- Meridian Bioscience
Competitive Analysis
The Global Enteric Disease Testing Market features a competitive landscape dominated by global diagnostics companies with strong R\&D capabilities and diverse product portfolios. Key players such as Abbott, BD, and Bio-Rad Laboratories lead the market by offering advanced molecular diagnostics and immunoassay platforms. It is seeing increased competition from mid-sized firms like Biomerica and Coris Bioconcept, which focus on niche testing solutions and affordable diagnostics. Companies invest heavily in innovation, partnerships, and geographical expansion to maintain their market positions. The trend toward syndromic panels and point-of-care testing has prompted new product launches and strategic acquisitions. Competitive differentiation lies in technological innovation, regulatory approvals, and the ability to serve both developed and emerging markets efficiently.
Recent Developments
- In April 2025, Cepheid and Oxford Nanopore Technologies entered a strategic collaboration to develop and commercialize sequencing-based workflows for infectious disease diagnostics, including enteric pathogens. This partnership aims to combine Cepheid's GeneXpert system for sample preparation with Oxford Nanopore's rapid, information-rich sequencing platform. The collaboration will focus on integrating Oxford Nanopore's sequencing technology with Cepheid's GeneXpert architecture to create a seamless workflow for infectious disease analysis.
- In April 2025, Meridian Bioscience introduced new enzyme stabilization services designed to enhance diagnostics for enteric diseases, particularly by supporting qPCR, NGS, and isothermal assays. These services aim to improve assay stability, lower detection limits, and increase cost-efficiency through advanced enzyme stabilization technologies like lyophilization and air-drying.
Market Concentration and Characteristics
The Global Enteric Disease Testing Market demonstrates a moderately concentrated structure with several key players dominating the landscape through strong technological capabilities and extensive distribution networks. It is characterized by continuous innovation in molecular diagnostics, point-of-care testing, and multiplex assay development, which drive competitive differentiation. Market leaders focus on expanding their product portfolios while targeting both developed and emerging markets to capture broader customer bases. The market features a mix of large multinational corporations and specialized regional firms, fostering a dynamic competitive environment. High entry barriers due to regulatory requirements, technological complexity, and significant R&D investments maintain the dominance of established companies. It encourages collaborations and strategic partnerships to accelerate product development and market penetration, ultimately shaping the market’s competitive dynamics.
Report Coverage
The research report offers an in-depth analysis based on Test Type, Disease Type, End Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Enteric Disease Testing Market will experience sustained growth driven by increasing prevalence of gastrointestinal infections worldwide.
- Advancements in molecular and multiplex diagnostic technologies will enhance test accuracy and reduce turnaround times significantly.
- Expansion of point-of-care testing solutions will improve access to rapid diagnostics in remote and resource-limited regions.
- Emerging economies will present substantial market opportunities due to rising healthcare investments and growing awareness of enteric diseases.
- Integration of artificial intelligence and digital platforms will optimize diagnostic workflows and support real-time disease surveillance.
- Syndromic testing panels will gain prominence, allowing simultaneous detection of multiple enteric pathogens for comprehensive diagnosis.
- Regulatory frameworks will evolve to support faster approval and adoption of innovative diagnostic technologies globally.
- Strategic collaborations between diagnostic companies and public health organizations will strengthen disease monitoring and outbreak response.
- The demand for affordable, user-friendly test kits will increase to meet the needs of decentralized healthcare settings.
- Continued focus on antimicrobial stewardship will drive the use of precise diagnostic tools to reduce unnecessary antibiotic prescriptions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Foodborne and Waterborne Infections
The increasing incidence of enteric infections such as Salmonella, E. coli, and Campylobacter, driven by contaminated food and water, is fueling demand for accurate and rapid diagnostic solutions worldwide.
Government Initiatives and Enhanced Disease Surveillance
Stricter health regulations and expanded surveillance programs by governments and public health agencies are driving the adoption of advanced enteric disease testing, supporting early detection and outbreak management.
Technological Advancements in Diagnostics
Rapid adoption of molecular diagnostics, multiplex PCR assays, and automation is improving test accuracy, reducing turnaround times, and enabling simultaneous detection of multiple pathogens, thus expanding market reach.
Expansion of Diagnostic Access in Emerging Economies
Growing healthcare investments, public awareness campaigns, and the introduction of affordable, easy-to-use diagnostic kits are increasing testing penetration in emerging markets, unlocking new growth opportunities.
Shift Toward Point-of-Care and Syndromic Testing
The rise of point-of-care and syndromic testing panels is enabling faster, decentralized diagnosis, particularly in resource-limited settings, improving clinical outcomes and supporting antimicrobial stewardship.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Global Enteric Disease Testing Market in 2023, and what is its expected size by 2032?
Which diagnostic trends are shaping the enteric disease testing market?
Which regions hold the largest share and fastest growth in the enteric disease testing market?
Who are the key players dominating the Global Enteric Disease Testing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Hospitals and Clinics
- 1.2.2 Diagnostic Laboratories
- 1.2.3 Academic and Research Institutes
- 1.2.4 Others
- 1.3 By Test Type
- 1.3.1 Laboratory Testing
- 1.3.2 Culture-based Tests
- 1.3.3 PCR Tests
- 1.3.4 Immunoassays
- 1.3.5 ELISA
- 1.3.6 Point-of-Care Testing (POCT)
- 1.3.7 Rapid Antigen Tests
- 1.3.8 Molecular POCT Kits
- 1.4 By Disease Type
- 1.4.1 Bacterial Enteric Diseases
- 1.4.2 Viral Enteric Diseases
- 1.4.3 Parasitic Enteric Diseases
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,410.9 million → 2032: USD 5,500.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Enteric Disease Testing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Enteric Disease Testing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Enteric Disease Testing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Enteric Disease Testing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Enteric Disease Testing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Enteric Disease Testing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Enteric Disease Testing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Enteric Disease Testing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,410.9 million → 2032: USD 5,500.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Enteric Disease Testing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals and Clinics
- 12.3.7.2 Diagnostic Laboratories
- 12.3.7.3 Academic and Research Institutes
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Test Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Laboratory Testing
- 12.4.7.2 Culture-based Tests
- 12.4.7.3 PCR Tests
- 12.4.7.4 Immunoassays
- 12.4.7.5 ELISA
- 12.4.7.6 Point-of-Care Testing (POCT)
- 12.4.7.7 Rapid Antigen Tests
- 12.4.7.8 Molecular POCT Kits
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Disease Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Bacterial Enteric Diseases
- 12.5.7.2 Viral Enteric Diseases
- 12.5.7.3 Parasitic Enteric Diseases
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Enteric Disease Testing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Enteric Disease Testing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Enteric Disease Testing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Enteric Disease Testing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bio-Rad Laboratories
- 18.4 BD (Becton, Dickinson and Company)
- 18.5 Biomerica
- 18.6 Biomérieux
- 18.7 Cepheid
- 18.8 Coris Bioconcept
- 18.9 DiaSorin S.p.A.
- 18.10 Quest Diagnostics Incorporated
- 18.11 Meridian Bioscience
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

