
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| GI Stool Testing Market Size 2023 | USD 497.02 Million |
| GI Stool Testing Market, CAGR | 6.04% |
| GI Stool Testing Market Size 2032 | USD 794.68 Million |
Market Overview
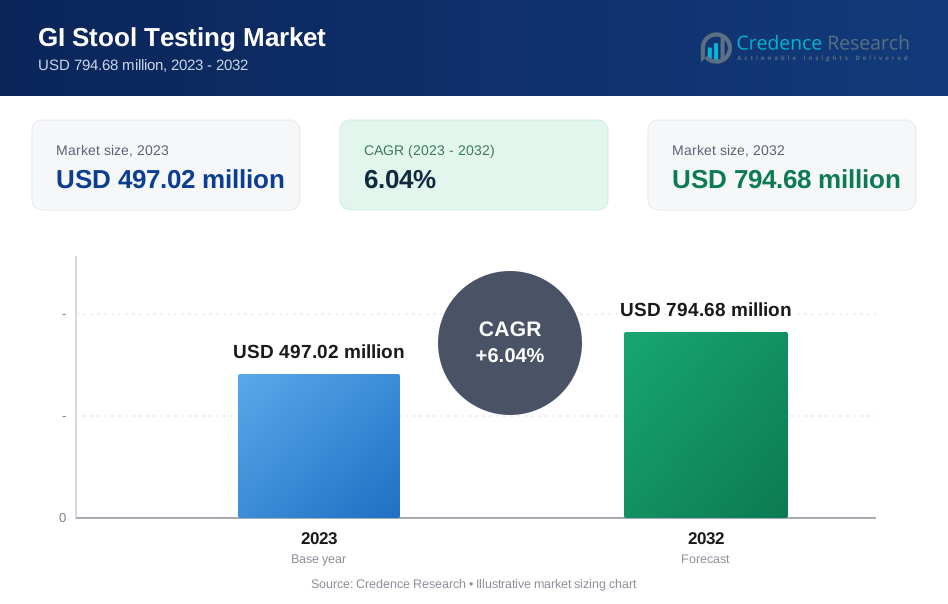
The GI Stool Testing Market is projected to grow from USD 497.02 million in 2023 to an estimated USD 794.68 million by 2032, with a compound annual growth rate (CAGR) of 6.04% from 2024 to 2032. This expansion reflects increasing awareness of gastrointestinal (GI) disorders, an aging global population, and heightened demand for non-invasive diagnostic tools.
Key drivers propelling the GI stool testing market include advancements in diagnostic technology and an increase in gastrointestinal diseases worldwide. Growing awareness of preventive healthcare has led to a rising number of routine GI screenings, boosting demand for stool testing kits. Additionally, the convenience of at-home test kits and the trend toward personalized medicine are supporting growth. The ongoing integration of artificial intelligence (AI) and machine learning in diagnostic tools also enhances the accuracy and efficiency of these tests, attracting more patients and healthcare providers.
Geographically, North America holds the largest market share due to well-established healthcare infrastructure, high healthcare expenditure, and increased adoption of advanced diagnostic technologies. Europe and the Asia-Pacific regions are also witnessing significant growth, driven by rising healthcare investments and increasing awareness of GI diseases. Key players in the global GI stool testing market include Abbott Laboratories, Bio-Rad Laboratories, Danaher Corporation, and Thermo Fisher Scientific. These companies are investing in research and development to enhance their product offerings and gain a competitive edge in this rapidly growing market.
Market Drivers
Increasing Prevalence of Gastrointestinal Diseases
The rising incidence of gastrointestinal (GI) diseases, such as colorectal cancer, irritable bowel syndrome (IBS), inflammatory bowel disease (IBD), and infections caused by various pathogens, significantly drives the GI stool testing market. Colorectal cancer remains a major cause of cancer-related deaths globally, and early detection is critical to reducing its impact. According to the World Cancer Research Fund, colorectal cancer is the third most commonly occurring cancer worldwide. For instance, in 2020, there were more than 1.9 million new cases of colorectal cancer and over 930,000 deaths due to colorectal cancer worldwide. Additionally, the global prevalence of inflammatory bowel disease (IBD) reached approximately 4.9 million cases in 2019. Furthermore, irritable bowel syndrome (IBS) affects around 11.2% of the global population, with higher prevalence rates observed in women. Conditions such as IBD, which includes Crohn’s disease and ulcerative colitis, are also on the rise. The increasing prevalence of these diseases has heightened the need for reliable, non-invasive diagnostic tools that can aid in early detection and continuous monitoring. GI stool testing provides valuable insights into the gut microbiome and helps in identifying specific pathogens, inflammatory markers, and other indicators related to GI diseases. As awareness of these conditions grows, more people are undergoing preventive screenings, driving demand for GI stool testing solutions.
Growing Awareness of Preventive Healthcare
As healthcare systems worldwide shift toward preventive care, there is a marked increase in routine screenings and diagnostic tests aimed at identifying health issues before they escalate. Preventive healthcare has been gaining traction, supported by governments, healthcare organizations, and advocacy groups promoting regular screenings for GI conditions. GI stool testing is an effective tool for detecting early signs of GI diseases, providing a non-invasive, accessible, and accurate diagnostic option that can be used for population-level screenings. For instance, it is estimated that more than 20 million GI endoscopies are performed yearly in the United States. Additionally, in 2020, more than 1.9 million new cases of colorectal cancer and over 930,000 deaths due to colorectal cancer were reported worldwide. Furthermore, the demand for home-based testing kits is rising, as evidenced by the launch of non-invasive, at-home screening tests like ColoClear by Circle in Hong Kong in June 2022. This growing focus on preventive healthcare is driven by the understanding that early diagnosis leads to more effective treatment and better patient outcomes. As a result, the adoption of GI stool testing is expanding not only in developed regions but also in emerging markets, where healthcare awareness and infrastructure are rapidly improving. The demand for home-based testing kits is also rising, as they offer patients the convenience of performing the test in the comfort of their own homes, aligning with the trend toward personalized healthcare.
Technological Advancements in Diagnostic Testing
The GI stool testing market has benefited significantly from advances in diagnostic technology. Enhanced diagnostic techniques, including polymerase chain reaction (PCR), enzyme-linked immunosorbent assay (ELISA), and multiplex nucleic acid testing, have improved the accuracy, specificity, and sensitivity of GI stool tests. Additionally, the integration of artificial intelligence (AI) and machine learning in diagnostic testing has streamlined data analysis, allowing for faster and more precise results. For instance, the FDA approved ColoSense™ in May 2024, a noninvasive multi-target stool RNA (mt-sRNA) colorectal cancer screening test that demonstrated 93% sensitivity for detecting colorectal cancer and 45% sensitivity for detecting advanced adenomas. Additionally, the GI Genius system, the first AI-based device to assist clinicians during colon cancer screening, was authorized by the FDA in April 2021. Furthermore, Duke University developed a ‘Smart Toilet’ that uses AI to monitor bowel health, providing gastroenterologists with valuable data for diagnosing chronic GI conditions. AI-based systems can identify patterns and biomarkers within stool samples, assisting healthcare providers in diagnosing and monitoring GI diseases more effectively. Innovations such as at-home testing kits with advanced sample collection and preservation technology also provide patients with more reliable results. Companies within the market are continuously investing in research and development to improve existing testing methodologies and develop new technologies, leading to increased adoption of GI stool testing across various healthcare settings. These technological advancements make GI stool testing more accessible and attractive to both healthcare providers and patients, further fueling market growth.
Increasing Healthcare Expenditure and Supportive Government Initiatives
Rising healthcare expenditure globally and supportive government initiatives are significant factors contributing to the growth of the GI stool testing market. Governments and healthcare organizations are increasingly recognizing the importance of early diagnosis and disease prevention, prompting them to invest in advanced diagnostic solutions, including GI stool testing. In developed regions such as North America and Europe, healthcare expenditure remains high, with governments actively promoting the use of diagnostic tests to reduce the burden of GI diseases on healthcare systems. Emerging economies are also prioritizing healthcare spending, with an emphasis on improving diagnostic capabilities. For instance, countries in the Asia-Pacific region are increasing investments in healthcare infrastructure and implementing initiatives to improve access to preventive care. These supportive measures from governments, along with reimbursement policies for diagnostic tests, make GI stool testing more accessible to patients. Additionally, public health campaigns promoting regular GI screenings contribute to higher market demand as they encourage individuals to seek preventive care, thereby expanding the reach and adoption of GI stool testing services.
Market Trends
Rising Adoption of At-Home Testing Kits
One prominent trend in the GI stool testing market is the increasing popularity of at-home testing kits, driven by the growing demand for convenient, accessible, and non-invasive diagnostic solutions. These kits offer patients the ability to collect stool samples from the comfort of their homes, which not only enhances user convenience but also improves adherence to routine screenings. For instance, during the COVID-19 pandemic, the use of at-home GI stool testing kits increased significantly, with health plans such as OptumCare, Humana, and Premera Blue Cross launching or expanding programs to send fecal immunochemical testing (FIT) kits to patients. Additionally, in June 2022, Prenetics Group Limited launched ColoClear by Circle, a non-invasive, at-home screening test for detecting early signs of colorectal cancer in Hong Kong. This trend has continued post-pandemic, as patients increasingly seek out healthcare solutions that fit into their lifestyles. Many at-home kits are equipped with advanced sample preservation technology, allowing for accurate results even after extended transit times. Additionally, the rise of digital health platforms has facilitated seamless test ordering, sample submission, and result access, enhancing patient engagement. Companies are investing in developing user-friendly, reliable, and cost-effective at-home testing solutions that align with the trend toward personalized and preventive healthcare.
Integration of Advanced Technologies such as AI and Machine Learning
The GI stool testing market is witnessing a significant impact from technological advancements, particularly the integration of artificial intelligence (AI) and machine learning (ML). These technologies are being used to enhance the precision, speed, and efficiency of diagnostic processes. AI and ML algorithms can analyze complex data from stool samples to identify specific pathogens, inflammatory markers, and microbiome imbalances with high accuracy. Such insights are valuable for diagnosing GI disorders and monitoring treatment progress, as well as for personalizing treatment plans based on individual gut health profiles. For instance, the FDA authorized the marketing of the GI Genius system in April 2021, which is the first device that uses artificial intelligence (AI) based on machine learning to assist clinicians in detecting lesions in the colon in real time during a colonoscopy. Additionally, the FDA approved ColoSense™ in May 2024, a noninvasive multi-target stool RNA (mt-sRNA) colorectal cancer screening test that demonstrated 93% sensitivity for detecting colorectal cancer and 45% sensitivity for detecting advanced adenomas. Companies in the market are leveraging these technologies to improve the performance of stool tests, reduce turnaround times, and offer insights that can aid in early detection and disease management. Furthermore, AI-driven tools allow healthcare providers to process larger volumes of diagnostic data, making GI stool testing more scalable and cost-effective for both patients and healthcare systems. As these technologies continue to advance, they are expected to play an increasingly integral role in enhancing the value and adoption of GI stool testing solutions.
Market Restraints and Challenges
High Cost of Advanced Diagnostic Tests and Limited Reimbursement Policies
One significant challenge for the GI stool testing market is the high cost associated with advanced diagnostic tests, which can limit accessibility for certain patient groups. Tests that utilize advanced technologies, such as polymerase chain reaction (PCR) and next-generation sequencing, provide accurate and comprehensive insights but are often costly. These higher costs can be prohibitive for patients in regions with limited healthcare funding or insufficient insurance coverage. Moreover, reimbursement policies for GI stool testing vary widely across different countries, with many healthcare systems offering only partial or no reimbursement for certain tests. In markets where insurance coverage is limited, patients may have to bear the full cost, deterring them from utilizing these diagnostic options. This lack of comprehensive reimbursement remains a challenge in both developed and emerging economies, impacting the adoption of GI stool testing solutions and ultimately restraining market growth.
Lack of Awareness and Limited Access to Diagnostic Facilities in Emerging Regions
Despite advancements in GI stool testing, a lack of awareness about the benefits of early detection and preventive healthcare continues to pose a challenge in certain parts of the world, particularly in low- and middle-income countries. In these regions, many individuals may not recognize the importance of regular GI health screenings or may avoid testing due to cultural stigmas associated with stool sample collection. Additionally, limited access to healthcare infrastructure in remote or rural areas restricts the availability of GI stool testing services, as many of these locations lack the facilities and trained personnel necessary for sample processing and analysis. This geographical disparity impacts market penetration, as individuals in underserved regions may not have the same access to these tests as those in urban areas. Addressing these challenges requires ongoing public health initiatives to raise awareness about GI diseases and preventive healthcare, as well as investments in expanding diagnostic infrastructure to ensure broader access to testing services.
Market Segmentation Analysis
By Product type
The consumables segment, comprising products like reagents, test kits, and other disposable items, holds a significant share in the GI stool testing market due to their frequent use in both clinical and at-home settings, requiring regular replenishment. As global gastrointestinal disease rates rise, the demand for consumables is expected to grow in parallel, particularly with the increasing popularity of at-home testing kits that include essential components for accurate sample collection. On the other hand, analyzers, critical in clinical and laboratory settings, play a vital role in processing and analyzing stool samples to detect pathogens and biomarkers linked to GI diseases. Though analyzers are typically more costly than consumables, they offer enhanced accuracy, efficiency, and scalability, with specialized equipment like PCR and ELISA systems making up this segment. With healthcare facilities increasingly adopting advanced diagnostic technologies, the demand for analyzers is set to grow, further bolstered by innovations such as AI and machine learning integration for improved data analysis.
By test Type
Occult blood tests, widely used in both clinical settings and at-home kits, help detect hidden blood in stool, often indicating conditions like colorectal cancer and polyps. Demand for these tests is driven by the increasing focus on early cancer detection and preventive healthcare, with growth expected as awareness of colorectal cancer screening rises. Ova and parasites tests are crucial for diagnosing parasitic GI infections, particularly in regions with poor sanitation, and are essential for conditions like giardiasis and amoebiasis. As healthcare providers work to improve diagnostic capabilities for these infections, demand for ova and parasites tests is projected to increase, especially in emerging regions. Meanwhile, fecal biomarker tests, which measure indicators like calprotectin and lactoferrin, are increasingly used for diagnosing and monitoring chronic GI conditions such as IBD and IBS. Advancements in biomarker research are making these tests more accurate and accessible, contributing to their rising demand as essential tools in the face of growing GI disease prevalence.
Segments
Based on Product Type
- Consumables
- Analyzers
Based on Test Type
- Occult Blood Tests
- Ova and Parasites Test
- Fecal Biomarkers Tests
Based on Application
- Infection
- Inflammatory Bowel Disease
- Gastroesophageal Reflux Disease
- Cancer
- Others
Based on Regional Analysis
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East & Africa
- UAE
- Saudi Arabia
- Qatar
- South Africa
- Rest of the Middle East & Africa
Regional Analysis
North America (35%):
North America holds the largest share of the GI stool testing market, accounting for approximately 35% of the global market. This dominance is driven by a well-established healthcare infrastructure, high healthcare spending, and a strong focus on preventive healthcare. The United States, in particular, sees a high prevalence of gastrointestinal conditions, including colorectal cancer, which is one of the leading causes of cancer-related deaths in the region. This has led to increased awareness and adoption of regular GI screenings, including stool tests, for early disease detection. Additionally, technological advancements in diagnostic tools and the presence of major industry players in the region contribute to North America’s significant market share.
Europe (30%):
Europe is the second-largest market for GI stool testing, holding around 30% of the global share. The demand for GI stool testing in Europe is fueled by rising awareness of gastrointestinal diseases and a growing emphasis on early detection and preventive care. Countries like Germany, France, and the United Kingdom have robust healthcare systems that support regular screening programs for GI conditions, particularly colorectal cancer. The European market benefits from supportive government initiatives, widespread insurance coverage, and strong public health campaigns promoting GI health. Additionally, advancements in diagnostic technology and the increased availability of at-home testing kits have bolstered market growth in this region.
Key players
- Abbott Laboratories
- Genova Diagnostics
- Danaher Corporation
- bioMerieux SA
- Cardinal Health
- Diasorin
- Conegenics Corporation
- Epitope Diagnostics Inc.
- Cardinal Health
- CTKBiotech Inc.
- ScheBO Biotech AG
- MERIDIAN BIOSCIENCE INC.
Competitive Analysis
The Global GI Stool Testing Market is characterized by a mix of established and emerging players, each contributing to the market's growth through innovation and product expansion. Major players like Abbott Laboratories, Danaher Corporation, and bioMérieux SA lead the market with extensive product portfolios and a strong global presence. These companies invest heavily in research and development to enhance the accuracy, efficiency, and convenience of their testing solutions. Additionally, companies such as Genova Diagnostics and Meridian Bioscience Inc. focus on specialized diagnostics, catering to niche segments of the market. Emerging players, including ScheBO Biotech AG and Epitope Diagnostics Inc., bring unique technological innovations, driving competition. Strategic partnerships, mergers, and acquisitions are common among key players as they seek to expand their market share and geographic reach. With increasing demand for at-home testing kits and advanced diagnostics, companies are likely to focus on enhancing accessibility and user experience to maintain a competitive edge.
Recent Developments
- On August 21, 2024, Abbott expanded its Pure Bliss line of infant formulas to include European-made and organic products.
- On August 21, 2024, Genova Diagnostics was mentioned in a report highlighting the growth of the Global GI Stool Testing Market.
- On January 9, 2024, Danaher Corporation launched the Danaher-IGI Beacon for CRISPR Cures in collaboration with the Innovative Genomics Institute.
- On April 9, 2024, bioMerieux presented its new 5-year strategic plan, GO28, aimed at profitable growth.
- On January 31, 2024, Cardinal Health announced the acquisition of Specialty Networks, a technology-enabled multi-specialty group purchasing and practice enhancement organization.
- In March 2024, Diasorin launched the LIAISON Streptococcus pneumoniae Ag Assay in all countries accepting the CE Mark.
- On 21 August, 2024, Conegenics Corporation was mentioned in a report highlighting the growth of the Global GI Stool Testing Market.
- On May 26, 2023, Epitope Diagnostics Inc. continued to develop and market innovative in-vitro diagnostics products.
- On August 21, 2024, ScheBO Biotech AG was mentioned in a report highlighting the growth of the Global GI Stool Testing Market.
- On August 21, 2024, MERIDIAN BIOSCIENCE INC. was mentioned in a report highlighting the growth of the Global GI Stool Testing Market.
Market Concentration and Characteristics
The Global GI Stool Testing Market is moderately concentrated, with a mix of large multinational companies and smaller specialized firms contributing to its growth. Key players such as Abbott Laboratories, Danaher Corporation, and bioMérieux SA hold significant market shares, driven by their extensive product offerings, strong research and development capabilities, and global reach. The market is characterized by ongoing technological advancements, including the integration of artificial intelligence and machine learning for improved diagnostic accuracy, as well as a growing focus on non-invasive, at-home testing solutions that enhance patient convenience. Additionally, strategic collaborations, mergers, and acquisitions among major players further consolidate the market, allowing companies to expand their geographical presence and product portfolios. The increasing demand for early detection and preventive healthcare solutions, coupled with advancements in diagnostic technologies, underscores the competitive nature and dynamic growth potential of the GI stool testing market.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Test Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for at-home GI stool testing kits is expected to rise as patients increasingly seek convenient, non-invasive diagnostic options that align with their lifestyles.
- The integration of AI and machine learning will continue to enhance test accuracy, speed up data analysis, and enable personalized insights, improving patient outcomes.
- As healthcare systems emphasize early detection and preventive care, GI stool testing is likely to become a routine screening tool, contributing to market growth.
- The global increase in gastrointestinal conditions, such as colorectal cancer and inflammatory bowel disease, will drive demand for reliable diagnostic solutions like GI stool testing.
- Ongoing biomarker research will lead to the development of more specific and sensitive tests, allowing for better diagnosis and monitoring of GI diseases.
- Asia-Pacific and Latin America are anticipated to witness high growth rates due to improving healthcare infrastructure, increasing awareness, and expanding access to diagnostic tools.
- Government and private sector investments in healthcare facilities, particularly in emerging economies, will enhance access to GI stool testing and other diagnostic services.
- As global mobility increases, so will the prevalence of parasitic and infectious diseases, driving demand for comprehensive stool tests that detect a broader range of pathogens.
- Major market players will continue to invest in research and development, focusing on innovations that improve accuracy, convenience, and user experience in GI stool testing.
- Supportive regulations and improved reimbursement frameworks will likely facilitate greater adoption of GI stool tests, particularly in developed regions, enhancing market penetration.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of Gastrointestinal Diseases
The global rise in GI conditions such as colorectal cancer, IBD, and IBS is fueling demand for reliable, non-invasive diagnostic tools like stool testing, as early detection is critical for effective treatment and disease management.
Growing Awareness of Preventive Healthcare
Healthcare systems and public health campaigns are emphasizing routine screenings and early diagnosis, leading to greater adoption of GI stool testing for population-level preventive care, especially as at-home kits become more accessible.
Technological Advancements in Diagnostic Testing
Innovations such as PCR, ELISA, and the integration of AI and machine learning have improved the accuracy, speed, and convenience of GI stool tests, making them more attractive to both healthcare providers and patients.
Rising Adoption of At-Home Testing Kits
The convenience and privacy of at-home GI stool testing kits are driving their popularity, especially post-pandemic, enabling broader screening coverage and improving patient compliance with routine GI health checks.
Supportive Government Initiatives and Healthcare Expenditure
Increased healthcare spending and government-backed screening programs, particularly in developed regions, are expanding access to advanced GI stool testing and encouraging regular preventive screenings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size and CAGR for the Global GI Stool Testing Market?
What are the main factors driving the growth of the GI Stool Testing Market?
How does the adoption of at-home testing kits impact the GI Stool Testing Market?
Which regions dominate the Global GI Stool Testing Market?
What technological advancements are shaping the GI Stool Testing Market?
Who are the key players in the GI Stool Testing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Test Type
- 1.2.1 Occult Blood Tests
- 1.2.2 Ova and Parasites Test
- 1.2.3 Fecal Biomarkers Tests
- 1.3 By Application
- 1.3.1 Infection
- 1.3.2 Inflammatory Bowel Disease
- 1.3.3 Gastroesophageal Reflux Disease
- 1.3.4 Cancer
- 1.3.5 Others
- 1.4 By Product Type
- 1.4.1 Consumables
- 1.4.2 Analyzers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 497.02 million → 2032: USD 794.68 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global GI Stool Testing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global GI Stool Testing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global GI Stool Testing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global GI Stool Testing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global GI Stool Testing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global GI Stool Testing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global GI Stool Testing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global GI Stool Testing Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 497.02 million → 2032: USD 794.68 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global GI Stool Testing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Test Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Occult Blood Tests
- 12.3.7.2 Ova and Parasites Test
- 12.3.7.3 Fecal Biomarkers Tests
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Infection
- 12.4.7.2 Inflammatory Bowel Disease
- 12.4.7.3 Gastroesophageal Reflux Disease
- 12.4.7.4 Cancer
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Consumables
- 12.5.7.2 Analyzers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global GI Stool Testing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global GI Stool Testing Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global GI Stool Testing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global GI Stool Testing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott Laboratories
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bio-Rad Laboratories
- 18.4 Danaher Corporation
- 18.5 Thermo Fisher Scientific
- 18.6 bioMerieux SA
- 18.7 Genova Diagnostics
- 18.8 Diasorin
- 18.9 MERIDIAN BIOSCIENCE INC.
- 18.10 Epitope Diagnostics Inc.
- 18.11 ScheBO Biotech AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

