
Market Overview:
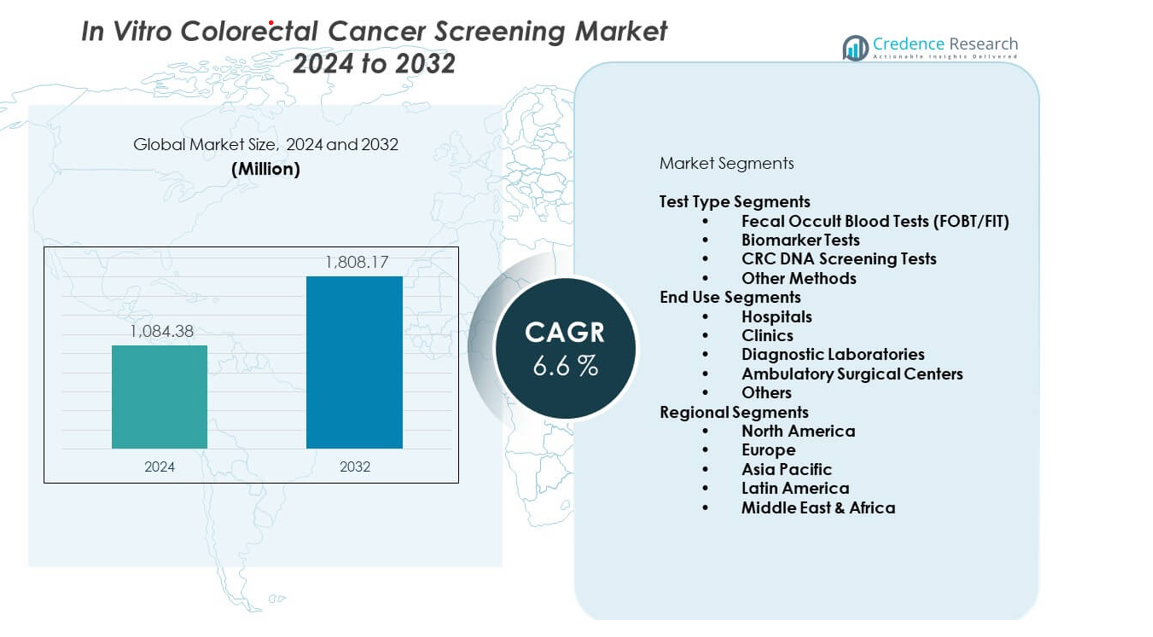
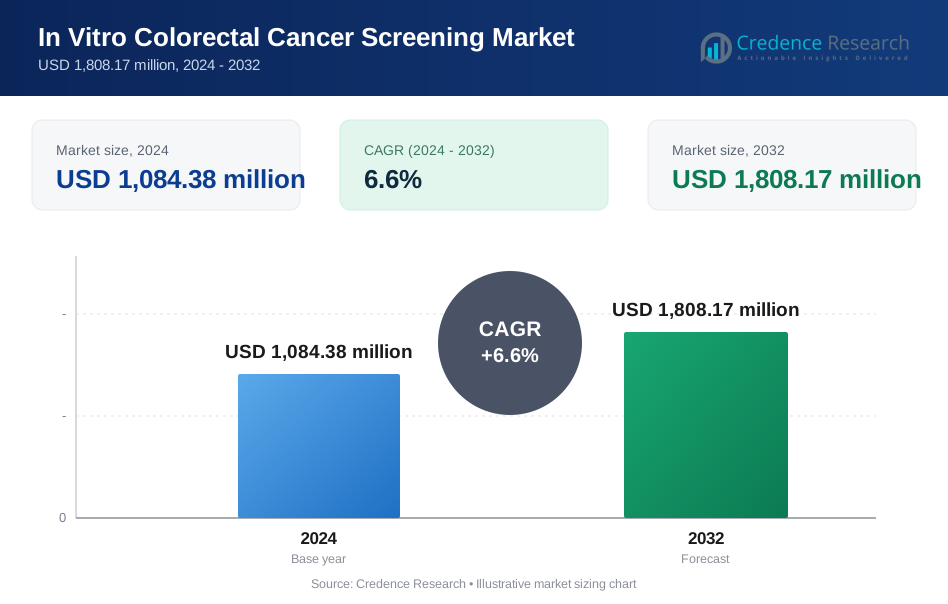
The In vitro colorectal cancer screening market is projected to grow from USD 1,084.38 million in 2024 to USD 1,808.17 million by 2032, with a CAGR of 6.6% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| In Vitro Colorectal Cancer Screening Market Size 2024 | USD 1,084.38 million |
| In Vitro Colorectal Cancer Screening Market, CAGR | 6.6% |
| In Vitro Colorectal Cancer Screening Market Size 2032 | USD 1,808.17 million |
Strong demand rises due to wider awareness of early cancer detection. Screening labs adopt advanced molecular tools that improve diagnostic accuracy. Healthcare systems push non-invasive kits for higher patient comfort. Governments expand coverage for population-based screening programs. Research groups develop markers that help detect tumors earlier. Hospitals prefer automated platforms that lower manual errors. Growth strengthens as payers support simple testing pathways.
North America leads due to strong screening adoption and mature clinical programs. Europe follows with high compliance supported by structured national initiatives. Asia Pacific emerges rapidly as healthcare access expands across large populations. China and India show rising uptake driven by improved lab capacity. Latin America grows steadily through better diagnostic funding. The Middle East begins to progress with new cancer awareness campaigns. Africa remains early-stage but gains momentum through expanding lab networks.
Market Insights:
- The In vitro colorectal cancer screening market is valued at USD 1,084.38 million in 2024 and is projected to reach USD 1,808.17 million by 2032, growing at a 6.6% CAGR driven by strong adoption of early-detection tools.
- North America holds about 40% share due to mature screening programs, Europe accounts for 30% with strong national guidelines, and Asia Pacific reaches 22% supported by expanding diagnostic capacity.
- Asia Pacific remains the fastest-growing region with its 22% share strengthened by rising CRC prevalence, improved infrastructure, and growing government-backed screening initiatives.
- FOBT/FIT leads the test type distribution with roughly 55% share, supported by affordability and integration into routine screening pathways.
- Hospitals remain the dominant end-use segment with nearly 40% share, driven by structured screening workflows and advanced diagnostic resources.
Market Drivers:
Growing Need for Early Detection Supported by Expanding Screening Programs
Growing public focus on early tumor identification strengthens demand across global health systems. Hospitals prefer non-invasive kits that support higher compliance among older adults. Policymakers promote community outreach to raise awareness about screening routines. Laboratories install automated analyzers that deliver faster processing outcomes. Research groups explore new biomarkers that refine sensitivity for small tumor fragments. Insurance bodies widen access through updated reimbursement lists. Clinicians use structured guidelines that push routine assessments. The In vitro colorectal cancer screening market gains steady momentum through sustained public health prioritization.
- For instance, Roche’s cobas e 801 analyzer processes up to 300 tests per hour, improving throughput for large centers.
Rising Use of Advanced Molecular Technologies for Higher Diagnostic Accuracy
Growth accelerates due to rapid adoption of molecular assays that boost precision. Labs select DNA-based tests that help detect cancer risk in early stages. Developers design platforms that lower false-negative rates across diverse populations. Automated sequencing tools improve workflow speed for high-volume centers. Hospitals shift toward assays with stronger predictive value for treatment planning. Vendors upgrade chemistries that enhance tumor signal detection. Research institutes support trials that validate next-generation biomarkers. It drives greater confidence among healthcare professionals.
- For instance, Exact Sciences’ Cologuard test demonstrates 92% sensitivity for colorectal cancer and 42% sensitivity for advanced precancerous lesions, as confirmed by its FDA summary.
Expansion of Home-Based Screening Driving Wider Patient Participation Rates
Demand increases as home kits build comfort for individuals avoiding hospital visits. Users prefer simple sample-collection tools that reduce clinic load. Vendors design compact systems tailored for remote settings. Health agencies encourage widespread distribution to underserved groups. Digital platforms guide users with stepwise instructions for correct testing. Labs gain more samples from regions with limited clinical access. Adoption climbs through strong awareness campaigns that highlight convenience. The In vitro colorectal cancer screening market benefits from improved reach across rural zones.
Growing Investment in Cancer Prevention Programs Strengthening Large-Scale Adoption
Governments allocate funds to support structured national cancer prevention strategies. Public hospitals integrate regular screening cycles into primary care pathways. Training programs help clinicians maintain quality across testing workflows. Screening centers expand infrastructure for higher daily throughput. Academic bodies support studies that measure population-level outcomes. Funding groups encourage innovation through grants for diagnostic development. Partnerships with private labs improve sample handling capacity. It supports long-term screening sustainability in high-risk regions.
Market Trends:
Shift Toward Multi-Analyte Platforms Improving Comprehensive Cancer Assessment
Vendors create platforms that analyze multiple markers within one run. Labs favor consolidated workflows that lower operational complexity. Developers enhance assay profiles to include risk-specific markers. Providers promote bundled testing options for broader patient groups. Hospitals seek solutions that combine molecular and immunochemical results. Research labs test hybrid panels that improve detection stability. Developers refine test chemistry to increase consistency across samples. The In vitro colorectal cancer screening market follows demand for integrated diagnostic models.
- For instance, Guardant Health’s Shield blood-based test analyzes over 500 genomic and epigenomic features per sample, as referenced in published validation studies.
Adoption of AI Tools Supporting Automated Interpretation and Risk Prediction
AI systems help labs detect subtle mutations linked to early tumor growth. Developers launch tools that process large genomic datasets with improved clarity. Hospitals adopt software that flags patient-specific probabilities with better accuracy. Screening centers integrate automation to reduce manual reading errors. Vendors enhance platforms for scalable digital evaluation. Researchers validate models that support stronger clinical decision-making. Clinicians appreciate tools that improve turn-around timelines. It encourages broader digital acceptance across diagnostic pathways.
- For instance, Siemens Healthineers’ AI-Rad Companion platform has demonstrated up to 20% improvement in diagnostic consistency across clinical sites, based on multi-center evaluations published by the company.
Growth of Digital Reporting Solutions Simplifying Patient Communication and Record Access
Hospitals use electronic dashboards to help patients understand screening results. Labs transmit digital reports that shorten communication gaps. Providers prefer structured templates that improve clarity for clinical use. Patients access secure portals for record tracking. Vendors upgrade systems to support mobile-friendly formats. Digital workflows reduce printing steps across busy labs. Health systems link reports to electronic medical records for better continuity. The In vitro colorectal cancer screening market benefits from strong digital transformation momentum.
Rising Interest in Preventive Oncology Research Enhancing Screening Innovation Pipelines
Research bodies invest in projects exploring novel biomarker libraries. Clinical teams support longitudinal studies tracking genetic changes over time. Universities strengthen collaboration with diagnostic developers. Labs validate new markers for diverse ethnic groups. Funding agencies encourage projects focused on high-risk cohorts. Early-stage incubation centers help start-ups refine screening concepts. Hospitals join multi-center trials improving scientific evidence. It fosters a robust innovation cycle across global research networks.
Market Challenges Analysis:
High Operational Costs and Limited Access Across Low-Resource Regions
The In vitro colorectal cancer screening market faces challenges linked to cost-heavy instruments and specialized workflows. Smaller hospitals struggle to maintain equipment due to high service expenses. Labs in rural regions lack trained professionals to run complex assays. Market penetration slows in areas where reimbursement rules remain unclear. Patient uptake drops when screening centers operate with limited capacity. Policymakers find it difficult to standardize protocols across fragmented systems. Developers face hurdles scaling advanced platforms in low-income areas. It restricts widespread uniform adoption in underserved populations.
Variation in Test Accuracy and Limited Public Awareness Affecting Screening Uptake
Labs report inconsistent outcomes when older immunochemical kits lack sensitivity. Users remain unaware of early screening benefits in many developing regions. Doctors face difficulty convincing patients to complete routine assessments. Cultural barriers reduce acceptance of stool-based testing methods. Hospitals with limited outreach programs experience slower enrollment. Developers struggle to align test reliability across diverse genetic profiles. Governments find it challenging to launch sustained education campaigns. It creates gaps that restrict full-scale screening coverage.
Market Opportunities:
Expansion Potential Across High-Risk Population Groups Through Tailored Testing Approaches
Opportunities grow as health systems design tests for genetic risk clusters. Hospitals enhance screening cycles for families with hereditary cancer traits. Labs refine marker panels supporting earlier detection timelines. Vendors introduce simplified kits that attract younger adults. Public health bodies include risk-based strategies in national plans. Governments support programs for remote communities with limited hospital access. Research groups design validation studies for ethnicity-specific biomarkers. The In vitro colorectal cancer screening market gains room for strong expansion.
Rising Scope for Integrated Digital Ecosystems Supporting Scalable Screening Models
Growth potential increases as hospitals invest in digital tools for unified workflows. Labs adopt remote-reporting features that smooth patient tracking. Developers launch AI-backed assistants improving operator confidence. Health systems link screening platforms to telehealth programs. Vendors design scalable cloud-based modules for regional networks. Investors target startups offering flexible diagnostic technologies. It enables smoother expansion across both public and private institutions.
Market Segmentation Analysis:
Test Type Segments
The In vitro colorectal cancer screening market is shaped by diverse test types that support broad screening needs across global healthcare systems. Fecal Occult Blood Tests (FOBT/FIT) remain widely used due to their simple workflow and strong integration into routine population-based programs. Biomarker Tests gain traction through innovations that offer stronger accuracy and higher detection confidence for early-stage lesions. CRC DNA Screening Tests strengthen diagnostic value with sensitivity that helps identify precancerous changes. Other Methods contribute through emerging serological and molecular platforms that help expand options for risk-based screening pathways. It gains steady adoption as clinicians seek solutions that fit both high-volume and personalized screening environments.
- For instance, the FDA notes that stool DNA tests such as Cologuard deliver a specificity of 87% for cancer and advanced precancerous lesions, reinforcing clinical confidence.
End Use Segments
End-use adoption spans hospitals, clinics, diagnostic laboratories, ambulatory surgical centers, and other healthcare settings. Hospitals lead through structured screening integration that supports early case identification and referral workflows. Clinics provide accessible screening points for routine patient visits, helping raise overall participation. Diagnostic Laboratories experience rapid growth due to their ability to manage high testing volumes and support outsourced molecular analysis. Ambulatory Surgical Centers contribute by offering pre-procedure assessments and streamlined referrals. Other end users extend adoption across community networks where early detection programs continue to expand.
- For instance, Quest Diagnostics processes more than 550,000 tests per day across its national network, enabling high-volume CRC screening support through FIT and DNA-based platforms.
Segmentation:
Test Type Segments
- Fecal Occult Blood Tests (FOBT/FIT)
- Biomarker Tests
- CRC DNA Screening Tests
- Other Methods
End Use Segments
- Hospitals
- Clinics
- Diagnostic Laboratories
- Ambulatory Surgical Centers
- Others
Regional Segments
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the In vitro colorectal cancer screening market, accounting for about 40% of global demand. Strong screening mandates guide consistent adoption across hospitals and diagnostic centers. Healthcare systems support early testing through well-established reimbursement structures. Manufacturers benefit from mature infrastructure that helps accelerate product deployment. Awareness programs improve participation among high-risk groups. Partnerships between labs and insurers raise compliance with routine screening cycles. It maintains leadership through continuous investment in preventive oncology.
Europe
Europe represents roughly 30% of global share, supported by structured national screening programs across major countries. Governments maintain organized pathways that guide routine testing for adults over specific age thresholds. Hospitals integrate advanced molecular tests into standardized care protocols. Diagnostic labs expand capacity to manage rising stool-based and DNA-based screening volumes. Public health bodies reinforce preventive efforts through awareness campaigns across diverse populations. Strong collaboration between research institutes and industry supports biomarker innovation. It sustains growth through high adoption of evidence-backed screening models.
Asia Pacific
Asia Pacific accounts for about 22% of global share and stands as the fastest-growing region. Rising colorectal cancer prevalence increases demand for scalable and cost-effective screening tools. Governments expand screening initiatives across urban and semi-urban populations. Hospitals improve diagnostic infrastructure to manage higher test volumes. Private labs grow rapidly due to outsourcing trends and expanding molecular capabilities. Awareness efforts strengthen participation as aging populations increase risk levels. It gains strong momentum through growing healthcare investment and wider access to testing technologies.
Key Player Analysis:
- Exact Sciences Corporation
- Abbott Laboratories
- Hoffmann-La Roche AG
- Epigenomics AG
- Beckman Coulter Inc.
- Sysmex Corporation
- Siemens Healthineers AG
- Quest Diagnostics Incorporated
- Guardant Health, Inc.
- MDxHealth SA
- Eiken Chemical Co., Ltd.
- Randox Laboratories Ltd.
- Oncocyte Corporation
- bioMérieux SA
- QIAGEN N.V.
Competitive Analysis:
The In vitro colorectal cancer screening market features strong competition driven by innovation in molecular diagnostics and early detection technologies. Major companies strengthen their position with DNA-based tests, biomarker assays, and automated laboratory systems. Firms invest in R&D to improve sensitivity and ease of use across high-volume settings. New entrants focus on blood-based biomarkers, challenging established stool test providers. Strategic partnerships support global expansion and validation studies. Hospitals and diagnostic labs influence competition through adoption preferences. It remains dynamic due to rapid technology upgrades and expanding preventive healthcare programs.
Recent Developments:
- In August 2025, Exact Sciences acquired exclusive rights to Freenome's blood-based colorectal cancer screening tests and the underlying technology for colorectal cancer, subject to customary regulatory approvals.
- Abbott Laboratories announced in November 2025 that it would acquire Exact Sciences Corporation for approximately $21 billion, marking Abbott's largest healthcare acquisition in two years. The acquisition adds a new growth vertical to Abbott's cancer diagnostics portfolio and positions the company to lead in the fast-growing $60 billion U.S. cancer screening and precision oncology diagnostics segments.
Report Coverage:
The research report offers an in-depth analysis based on Test Type Segments and End Use Segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing adoption of molecular and DNA-based screening tools.
- Rising focus on home-based kits for wider participation.
- Expanding integration of AI tools in diagnostic workflows.
- Increasing investment in biomarker research.
- Strengthening role of digital reporting in patient communication.
- Higher demand from aging populations in developing countries.
- Stronger collaborations between labs and technology firms.
- Wider adoption of blood-based CRC detection assays.
- Rising healthcare expenditure across emerging regions.
- Growing emphasis on preventive oncology programs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Need for Early Detection Supported by Expanding Screening Programs
Increasing public awareness and government-backed initiatives are driving the adoption of in vitro colorectal cancer screening, as early detection significantly improves treatment outcomes and survival rates. Hospitals and health systems are integrating non-invasive kits and structured screening workflows to boost compliance and reach broader populations.
Rising Use of Advanced Molecular Technologies for Higher Diagnostic Accuracy
The adoption of molecular and DNA-based assays is accelerating, as these technologies offer higher sensitivity and specificity for early-stage colorectal cancer and precancerous lesions. Laboratories and hospitals are investing in automated analyzers and next-generation biomarker tests to improve diagnostic confidence and workflow efficiency.
Expansion of Home-Based Screening Driving Wider Patient Participation Rates
Home-based screening kits are gaining popularity due to their convenience and ability to reach individuals who may avoid clinical visits, particularly in underserved or rural areas. This trend is supported by digital platforms and awareness campaigns, leading to increased sample collection and broader market penetration.
Growing Investment in Cancer Prevention Programs Strengthening Large-Scale Adoption
Governments and public health bodies are allocating more funds to structured national cancer prevention strategies, integrating regular screening into primary care, and supporting infrastructure expansion. These investments are enabling higher throughput, better clinician training, and sustainable screening programs, especially in high-risk and aging populations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the In vitro colorectal cancer screening market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the In vitro colorectal cancer screening market projected to grow between 2024 and 2032?
Which is the leading region of the market for in-vitro colorectal cancer screening?
What are the key drivers for the growth of the in-vitro colorectal cancer screening market?
Which is the major segment in the in-vitro colorectal cancer screening market by Imaging Type?
Who are the leading companies in the In vitro colorectal cancer screening market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Hospitals
- 1.2.2 Clinics
- 1.2.3 Diagnostic Laboratories
- 1.2.4 Ambulatory Surgical Centers
- 1.2.5 Others
- 1.3 By Test Type
- 1.3.1 Fecal Occult Blood Tests (FOBT/FIT)
- 1.3.2 Biomarker Tests
- 1.3.3 CRC DNA Screening Tests
- 1.3.4 Other Methods
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,084.38 million → 2032: USD 1,808.17 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global In Vitro Colorectal Cancer Screening Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global In Vitro Colorectal Cancer Screening Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global In Vitro Colorectal Cancer Screening Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global In Vitro Colorectal Cancer Screening Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global In Vitro Colorectal Cancer Screening Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global In Vitro Colorectal Cancer Screening Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global In Vitro Colorectal Cancer Screening Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global In Vitro Colorectal Cancer Screening Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,084.38 million → 2032: USD 1,808.17 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global In Vitro Colorectal Cancer Screening Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Clinics
- 12.3.7.3 Diagnostic Laboratories
- 12.3.7.4 Ambulatory Surgical Centers
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Test Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fecal Occult Blood Tests (FOBT/FIT)
- 12.4.7.2 Biomarker Tests
- 12.4.7.3 CRC DNA Screening Tests
- 12.4.7.4 Other Methods
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global In Vitro Colorectal Cancer Screening End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global In Vitro Colorectal Cancer Screening Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global In Vitro Colorectal Cancer Screening Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global In Vitro Colorectal Cancer Screening Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Exact Sciences Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Abbott Laboratories
- 18.4 Hoffmann-La Roche AG
- 18.5 Epigenomics AG
- 18.6 Beckman Coulter Inc.
- 18.7 Sysmex Corporation
- 18.8 Siemens Healthineers AG
- 18.9 Quest Diagnostics Incorporated
- 18.10 Guardant Health, Inc.
- 18.11 QIAGEN N.V.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

