
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Lyme Disease Diagnostics Market Size 2024 | USD 2,659.5 Million |
| Lyme Disease Diagnostics Market, CAGR | 6.36% |
| Lyme Disease Diagnostics Market Size 2032 | USD 4,356.04 Million |
Market Overview
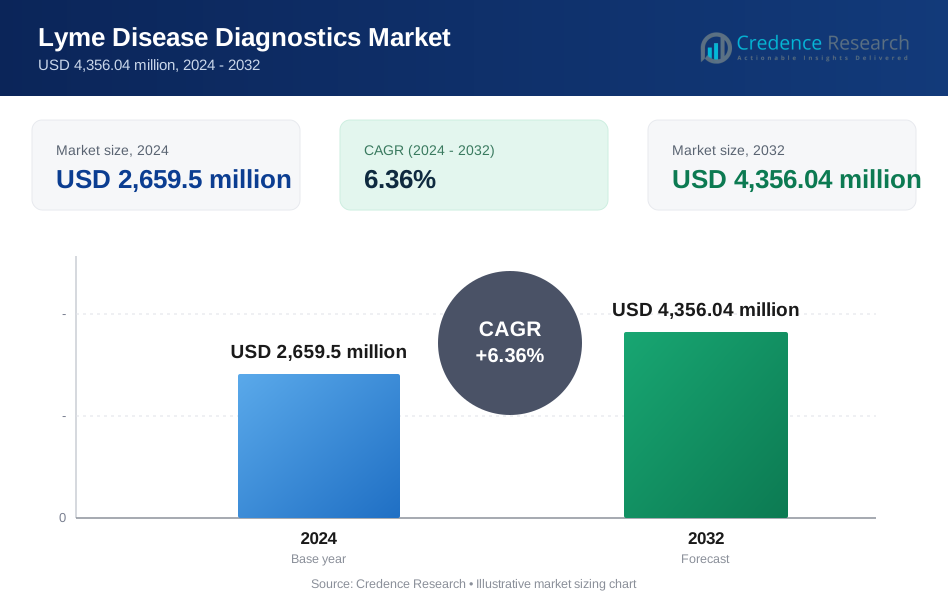
The Lyme Disease Diagnostics Market is projected to grow from USD 2,659.5 million in 2024 to USD 4,356.04 million by 2032, achieving a compound annual growth rate (CAGR) of 6.36%.
The Lyme Disease Diagnostics market is driven by the rising incidence of Lyme disease, increasing awareness about the condition, and advancements in diagnostic technologies. The growing adoption of molecular and serological tests enhances the accuracy and speed of diagnosis, improving patient outcomes. Additionally, the integration of point-of-care testing and the development of innovative biomarkers are key trends propelling market growth. Furthermore, government initiatives and funding for Lyme disease research and awareness campaigns contribute to the increasing demand for efficient diagnostic solutions, positioning the market for significant expansion in the coming years.
The Lyme disease diagnostics market exhibits significant geographical variation, with North America holding the largest market share due to the high incidence of Lyme disease in the region. Europe follows closely, driven by increasing awareness and improved diagnostic methods. Key players in this market include established companies like Abbott Laboratories, Quest Diagnostics, and LabCorp, which dominate through innovative testing solutions. Other significant contributors, such as F. Hoffmann-La Roche AG and bioMérieux SA, enhance market competitiveness by advancing diagnostic technologies. These players are crucial in driving growth and expanding access to reliable Lyme disease diagnostics across various regions.
Market Drivers
Rising Incidence of Lyme Disease
The rising incidence of Lyme disease is significantly impacting its diagnostics market. Geographic expansion is evident, as Lyme disease becomes increasingly prevalent in regions where ticks thrive, notably North America, Europe, and Asia. Climate change also plays a critical role, with warmer temperatures and changing weather patterns fostering ideal conditions for tick populations to flourish. For instance, the CDC reported over 63,000 cases of Lyme disease in 2022, with estimates suggesting that approximately 476,000 people may be diagnosed and treated for Lyme disease each year in the United States. This combination of factors necessitates enhanced diagnostic capabilities to address the growing number of cases effectively.
Increased Awareness and Early Detection
Increased public awareness and early detection efforts are pivotal in improving Lyme disease outcomes. Public health campaigns have successfully raised awareness about the symptoms, prevention strategies, and the critical importance of early diagnosis. For instance, National Lyme Disease Awareness Month in May includes various activities such as fundraisers, educational events, and public proclamations to spread information on preventing Lyme and tick-borne diseases. Additionally, educating healthcare providers to promptly recognize and treat Lyme disease is essential for reducing complications. These initiatives are driving demand for more sophisticated diagnostic tools to facilitate early intervention and improve patient care.
Technological Advancements
Technological advancements are transforming Lyme disease diagnostics. The development of more accurate and sensitive tests, such as polymerase chain reaction (PCR) and enzyme-linked immunosorbent assays (ELISA), has significantly enhanced diagnostic accuracy. Furthermore, the emergence of point-of-care testing allows for rapid diagnosis, particularly in remote or resource-limited areas, thereby improving access to timely treatment. These innovations are crucial for effectively managing the disease and supporting public health initiatives.
Government Initiatives and Economic Impact
Government initiatives and regulations play a vital role in advancing Lyme disease diagnostics. Increased funding for research into diagnostic tools and treatments fosters innovation, while disease surveillance programs monitor the prevalence of Lyme disease and guide diagnostic efforts. The economic impact of Lyme disease is substantial, as untreated cases can lead to significant healthcare costs and lost productivity. Moreover, the ongoing debate surrounding chronic Lyme disease and persistent symptoms drives the demand for definitive diagnostic tools, further emphasizing the need for continued investment and research in this area.
Market Trends
Point-of-Care Testing and Multiplex Testing
Point-of-care (POC) testing is revolutionizing Lyme disease diagnostics by providing rapid results that facilitate immediate treatment decisions. These tests can be performed in various settings, including doctors' offices, urgent care centers, and even at home, enhancing patient accessibility and convenience. For instance, a study published in the Journal of Clinical Microbiology describes a new rapid assay for Lyme disease that could lead to a practical test for use by healthcare providers. Coupled with POC testing, multiplex testing is also gaining traction in the diagnostics landscape. This innovative approach allows for the simultaneous detection of Lyme disease and other tick-borne illnesses, significantly improving diagnostic efficiency. Early detection of co-infections can be crucial for comprehensive patient management, as co-infections may contribute to exacerbated symptoms. Together, POC and multiplex testing are transforming how Lyme disease is diagnosed and treated, ultimately leading to better patient outcomes.
Digital Health Solutions and Personalized Medicine
The integration of digital health solutions is further enhancing Lyme disease management. Remote monitoring platforms enable healthcare providers to track patient symptoms over time, facilitating timely interventions and remote consultations that improve patient engagement and compliance. Furthermore, data analysis tools can sift through large datasets to identify patterns and trends in Lyme disease prevalence and treatment outcomes, aiding public health initiatives and guiding clinical decisions. On the other hand, personalized medicine is emerging as a promising approach to Lyme disease treatment. Advances in genomics and proteomics are paving the way for tailored treatment strategies based on individual genetic makeups. By targeting specific biomarkers, personalized medicine holds the potential to enhance treatment efficacy and improve patient outcomes significantly. As the understanding of Lyme disease deepens, these advancements will play a crucial role in developing more effective and individualized treatment plans.
Market Challenges Analysis
Lack of Standardization and Test Limitations
The Lyme disease diagnostics landscape faces significant challenges due to a lack of standardization and inherent test limitations. Variability in diagnostic tests can lead to inconsistencies in sensitivity and specificity, resulting in unreliable test results that complicate clinical decision-making. For example, some tests may generate false negatives, particularly in early-stage infections or chronic Lyme disease cases, causing critical delays in necessary treatment. Conversely, false positive results can prompt unnecessary anxiety and unwarranted treatment interventions. The complexity of interpreting test results further exacerbates these challenges, particularly in cases of early-stage infection or chronic Lyme disease, where symptoms may overlap with other conditions. This lack of clarity in diagnostic processes underscores the need for improved standardization across testing methodologies to ensure consistent and reliable results.
Cost, Accessibility, and Regulatory Hurdles
In addition to diagnostic inconsistencies, the financial and geographic barriers to accessing Lyme disease diagnostics present formidable challenges. The high cost of diagnostic tests can limit accessibility for many patients, particularly those without adequate insurance coverage. Geographic disparities are also a significant concern, as individuals in rural or underserved areas may find it challenging to access diagnostic facilities and expert healthcare providers. For instance, a survey by IGeneX found that nearly 36 percent of patients with a tick-borne disease spent more than $10,000 on tests, treatments, appointments, and other costs associated with their disease. Compounding these issues are regulatory hurdles associated with the approval and reimbursement of new diagnostic tests. The lengthy and costly approval processes can hinder the timely introduction of innovative testing methods, while difficulties in obtaining reimbursement from insurance providers for less conventional or experimental approaches can discourage healthcare providers from utilizing potentially effective diagnostics. Moreover, the lack of sufficient knowledge and training among some healthcare providers can lead to misdiagnosis, further delaying treatment and negatively impacting patient health outcomes. Addressing these challenges is crucial for improving the overall effectiveness and accessibility of Lyme disease diagnostics, ultimately enhancing patient care and outcomes.
Market Segmentation Analysis:
By Diagnostic Test:
The Lyme disease diagnostics market is primarily segmented by diagnostic tests, which include serological tests, ELISA, Western Blot, Polymerase Chain Reaction (PCR) tests, and other methods such as culture tests and antigen tests. Among these, serological tests dominate the market due to their widespread use and effectiveness in detecting antibodies produced in response to Lyme disease infection. The ELISA test is favored for its high sensitivity and is often employed as the first-line screening tool. In contrast, the Western Blot test serves as a confirmatory test, especially when initial serological tests yield positive results. PCR tests are gaining traction for their ability to detect the genetic material of the Lyme-causing bacterium, providing a rapid and accurate diagnosis. The demand for innovative diagnostic methods continues to rise, prompting research into advanced testing options that enhance sensitivity and specificity.
By Sample:
The Lyme disease diagnostics market is also segmented by sample type, including blood, cerebrospinal fluid (CSF), and other samples such as joint fluid and urine. Blood samples are the most commonly used due to their ease of collection and effectiveness in detecting antibodies. Serological tests utilizing blood samples are well-established and provide reliable results. In cases where neurological involvement is suspected, CSF analysis may be necessary, as it allows for direct examination of the central nervous system. The use of other sample types, such as joint fluid and urine, is emerging, particularly for specific diagnostic tests. These diverse sample types facilitate comprehensive diagnosis and enable healthcare providers to tailor treatment strategies effectively, ultimately enhancing patient outcomes in Lyme disease management.
Segments:
Based on Diagnostic Test
- Serological Test
- ELISA
- Western Blot
- Polymerase Chain Reaction (PCR) Test
- Others (Culture Test, Antigen Test, etc.)
Based on Sample
- Blood
- Cerebrospinal Fluid (CSF)
- Others (Joint Fluid, Urine, etc.)
Based on End-user
- Hospitals
- Diagnostic Laboratories
- Others (Clinics, Research Institutes, etc.)
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the Lyme disease diagnostics market, accounting for approximately 60% of the global market revenue. This dominance is primarily attributed to the high incidence of Lyme disease in regions such as the northeastern United States and parts of Canada. The region benefits from advanced healthcare infrastructure and a strong emphasis on public health initiatives that promote awareness and early detection of Lyme disease. Furthermore, the availability of innovative diagnostic technologies, such as polymerase chain reaction (PCR) tests and serological assays, enhances the accuracy of diagnoses. Public health campaigns, coupled with the training of healthcare professionals, are critical in fostering early recognition and treatment, thereby driving the demand for diagnostic services in this region.
Europe
Europe accounts for nearly 25% of the Lyme disease diagnostics market, with countries like Germany, France, and the United Kingdom experiencing a notable increase in Lyme disease cases. The rise in tick populations due to climate change and shifting geographical conditions has contributed to the growing prevalence of Lyme disease in various European regions. The European market is characterized by a rising demand for efficient and accurate diagnostic tests, particularly serological assays and PCR testing. Increasing awareness among the public and healthcare providers regarding Lyme disease symptoms and prevention measures is driving market growth. Additionally, ongoing research and development efforts are focused on enhancing diagnostic methods, which will further improve detection rates and patient outcomes in the region. The combination of heightened awareness and innovative testing solutions positions Europe as a key player in the global Lyme disease diagnostics market.
Key Player Analysis
- Abbott Laboratories
- bioMérieux SA
- Bio-Rad Laboratories, Inc.
- DiaSorin S.p.A
- Hoffmann-La Roche AG
- LabCorp
- Meridian Bioscience, Inc.
- Quest Diagnostics
- Quidel Corporation
- T2 Biosystems, Inc.
- Thermo Fisher Scientific Inc.
- QIAGEN
Competitive Analysis
The Lyme disease diagnostics market is characterized by intense competition among several leading players, including Abbott Laboratories, Quest Diagnostics, LabCorp, Bio-Rad Laboratories, Inc., F. Hoffmann-La Roche AG, and T2 Biosystems, Inc. These companies leverage their extensive research and development capabilities to innovate and improve diagnostic tests. Companies are increasingly focusing on improving the accuracy and speed of diagnostic tests, particularly serological tests and molecular assays. The rise in public awareness of Lyme disease has heightened demand for reliable diagnostic solutions, prompting firms to invest in research and development. Additionally, the shift towards point-of-care testing solutions is transforming the landscape, allowing for quicker diagnosis in various healthcare settings. Collaborations and partnerships among industry players are also becoming more common as they seek to enhance their product offerings and expand their market presence. As a result, the competitive dynamics in the Lyme disease diagnostics market are expected to intensify, driving further advancements and improving patient outcomes.
Recent Developments
- In April 2023, Abbott Laboratories announced a collaboration with the Climate Amplified Disease and Epidemics (CLIMADE) consortium, a group of more than 100 scientists from public health departments and other industries. These global scientists are striving to assess and potentially mitigate the impact of climate change on disease outbreaks using data science technology and diagnostic testing.
- In July 2022, T2 Biosystems, Inc. announced that the FDA granted Breakthrough Device Designation for the company’s T2Lyme Panel. The T2Lyme Panel is a direct-from-blood molecular diagnostic test introduced to detect the Lyme disease-causing bacteria, including Borrelia burgdorferi, Borrelia garinii, and Borrelia afzelii. The test runs on the FDA-cleared T2Dx Instrument.
- In June 2022, Quidel Corporation announced a multifaceted partnership with Global Lyme Alliance in an effort to significantly raise public awareness about Lyme disease, which affects nearly 500,000 people in the U.S. annually. The first rapid point-of-care diagnostic Lyme disease test with FDA approval was developed by Quidel Corporation.
Market Concentration & Characteristics
The Lyme disease diagnostics market exhibits moderate concentration, characterized by a mix of established players and emerging companies striving to capture market share. Major companies dominate the landscape by leveraging advanced technologies and extensive distribution networks to deliver a diverse range of diagnostic tests, including serological tests and molecular assays. The market is marked by rapid technological advancements, with innovations such as point-of-care testing and multiplex assays gaining traction due to their ability to provide quick and accurate results. Additionally, regulatory frameworks significantly influence market dynamics, as companies must navigate complex approval processes for new diagnostic products. Competitive strategies often include partnerships and collaborations, aimed at enhancing product development and expanding geographical reach. Overall, the Lyme disease diagnostics market is characterized by continuous evolution driven by technological innovation, heightened awareness of Lyme disease, and an increasing demand for efficient diagnostic solutions in various healthcare settings.
Report Coverage
The research report offers an in-depth analysis based on Diagnostic Test, Sample, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market for Lyme disease diagnostics is expected to witness significant growth, driven by rising awareness and incidence rates.
- Continued advancements in molecular diagnostics will enhance the accuracy and speed of Lyme disease detection.
- Increased adoption of point-of-care testing will facilitate immediate diagnosis and treatment decisions in various healthcare settings.
- Research into novel biomarkers for Lyme disease will likely lead to improved diagnostic tools and personalized treatment approaches.
- The emergence of digital health solutions will support remote monitoring and patient engagement in Lyme disease management.
- Greater focus on chronic Lyme disease will drive demand for innovative diagnostic methods and targeted therapies.
- Public health initiatives will further promote awareness and education about Lyme disease symptoms and prevention strategies.
- Collaborations between government bodies and private companies will enhance funding and research efforts in Lyme disease diagnostics.
- The global market is anticipated to expand as Lyme disease becomes more prevalent in emerging regions.
- Regulatory challenges will remain, but streamlined approval processes may accelerate the introduction of new diagnostic tests.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Incidence of Lyme Disease
The increasing prevalence of Lyme disease, particularly in North America and Europe due to expanding tick habitats and climate change, is driving demand for more diagnostic testing and solutions.
Increased Awareness and Early Detection
Public health campaigns and educational initiatives are improving recognition of Lyme disease symptoms and the importance of early diagnosis, leading to higher testing rates and market growth.
Technological Advancements in Diagnostics
Innovations such as PCR, ELISA, and point-of-care testing are enhancing the accuracy, speed, and accessibility of Lyme disease diagnostics, making them more attractive to healthcare providers and patients.
Government Initiatives and Funding
Government support through research funding, surveillance programs, and awareness campaigns is fostering the development and adoption of advanced diagnostic tools, further expanding the market.
Adoption of Point-of-Care and Multiplex Testing
The shift towards rapid, on-site diagnostic solutions and multiplex assays that can detect multiple tick-borne diseases simultaneously is improving patient management and driving market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Lyme Disease Diagnostics market?
What factors are driving the growth of the Lyme Disease Diagnostics?
What are the key segments within the Lyme Disease Diagnostics?
What are some challenges faced by the Lyme Disease Diagnostics?
Who are the major players in the Lyme Disease Diagnostics?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Sample
- 1.2.1 Blood
- 1.2.2 Cerebrospinal Fluid (CSF)
- 1.2.3 Others (Joint Fluid, Urine, etc.)
- 1.3 By End-user
- 1.3.1 Hospitals
- 1.3.2 Diagnostic Laboratories
- 1.3.3 Others (Clinics, Research Institutes, etc.)
- 1.4 By Diagnostic Test
- 1.4.1 Serological Test
- 1.4.2 ELISA
- 1.4.3 Western Blot
- 1.4.4 Polymerase Chain Reaction (PCR) Test
- 1.4.5 Others (Culture Test, Antigen Test, etc.)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,659.5 million → 2032: USD 4,356.04 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Lyme Disease Diagnostics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Lyme Disease Diagnostics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Lyme Disease Diagnostics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Lyme Disease Diagnostics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Lyme Disease Diagnostics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Lyme Disease Diagnostics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Lyme Disease Diagnostics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Lyme Disease Diagnostics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,659.5 million → 2032: USD 4,356.04 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Lyme Disease Diagnostics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Sample - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Blood
- 12.3.7.2 Cerebrospinal Fluid (CSF)
- 12.3.7.3 Others (Joint Fluid, Urine, etc.)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-user - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Diagnostic Laboratories
- 12.4.7.3 Others (Clinics, Research Institutes, etc.)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Diagnostic Test - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Serological Test
- 12.5.7.2 ELISA
- 12.5.7.3 Western Blot
- 12.5.7.4 Polymerase Chain Reaction (PCR) Test
- 12.5.7.5 Others (Culture Test, Antigen Test, etc.)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Lyme Disease Diagnostics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Lyme Disease Diagnostics Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Lyme Disease Diagnostics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Lyme Disease Diagnostics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott Laboratories
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Quest Diagnostics
- 18.4 LabCorp
- 18.5 F. Hoffmann-La Roche AG
- 18.6 bioMérieux SA
- 18.7 Bio-Rad Laboratories, Inc.
- 18.8 DiaSorin S.p.A
- 18.9 T2 Biosystems, Inc.
- 18.10 Quidel Corporation
- 18.11 Thermo Fisher Scientific Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

