
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Meat Processing Equipment Market Size 2023 | USD 11,734.00 million |
| Meat Processing Equipment Market, CAGR | 5.2% |
| Meat Processing Equipment Market Size 2032 | USD 18,517.73 million |
Market Overview:
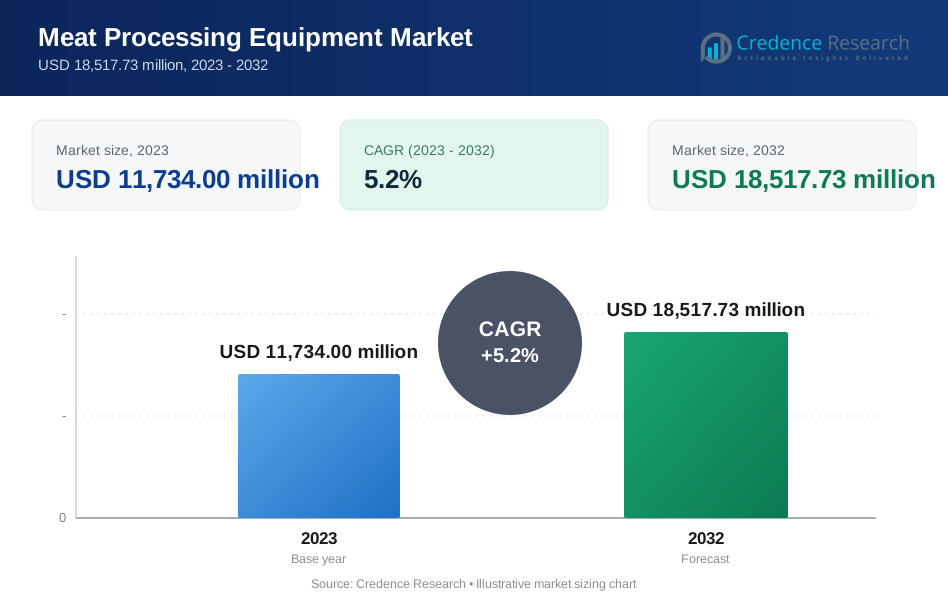
The Meat Processing Equipment Market is projected to grow from USD 11,734.00 million in 2023 to an estimated USD 18,517.73 million by 2032, with a compound annual growth rate (CAGR) of 5.2% from 2024 to 2032.
The primary drivers of the meat processing equipment market include the rising consumer demand for protein-rich diets, which has led to an increase in processed meat consumption worldwide. The growing trend of convenience foods, driven by busy lifestyles, also boosts the demand for meat processing equipment as manufacturers expand production to meet these demands. Additionally, technological advancements such as automation and AI integration in meat processing equipment have enhanced efficiency, quality, and safety, attracting investments in the industry. Regulatory emphasis on food safety standards, along with the need to reduce labor dependency, has encouraged meat processing companies to invest in advanced equipment. Moreover, the trend toward sustainability in the food processing industry is prompting innovations in energy-efficient equipment, further driving market growth.
Regionally, North America and Europe hold significant shares in the global meat processing equipment market, attributed to high consumption levels of processed meat and well-established food processing industries. The Asia-Pacific region is expected to witness the fastest growth rate due to a surge in meat consumption, rapid urbanization, and rising disposable incomes in emerging economies like China and India. Furthermore, Latin America and the Middle East & Africa are also anticipated to grow steadily, driven by an increasing demand for processed meat products and infrastructural development in the food processing sector. The presence of major industry players in these regions, combined with government support for the food processing sector, enhances regional growth prospects.
Market Drivers:
Rising Demand for Processed Meat Products:
The growing consumer preference for ready-to-eat and convenient food options has significantly increased the demand for processed meat products, directly fueling the need for advanced meat processing equipment. Rapid urbanization and busy lifestyles have driven a shift toward convenient foods that require minimal preparation, and processed meat products fit this demand perfectly. For instance, Tyson Foods reported a significant increase in sales of its ready-to-eat products, attributing this growth to the rising demand for convenience foods. As consumers prioritize time-saving food solutions, the processed meat industry is expanding to meet this demand, requiring more specialized equipment to handle higher production volumes efficiently. This trend is particularly evident in developed markets such as North America and Europe, where convenience and quality are valued by consumers, as well as in emerging economies where disposable incomes are rising
Emphasis on Food Safety and Quality Standards:
The meat processing industry is highly regulated, with stringent standards imposed to ensure food safety and quality. This regulatory emphasis compels meat processors to invest in high-quality equipment that can meet compliance requirements and improve overall production quality. Foodborne illnesses are a major concern globally, and strict safety regulations are pushing manufacturers to adopt equipment that minimizes contamination risks and maintains consistent hygiene. Advanced meat processing equipment, often featuring features like antimicrobial surfaces and automated cleaning systems, helps companies comply with these stringent standards while reducing human intervention in the process. By enhancing food safety and quality control, these regulatory drivers not only mitigate risks but also bolster consumer trust, ultimately benefiting market growth.
Technological Advancements in Meat Processing Equipment:
Technological advancements are transforming the meat processing equipment market, with innovations like automation, artificial intelligence, and Internet of Things (IoT) integration enhancing operational efficiency. Automated equipment reduces the dependency on manual labor, which can be costly and challenging to manage, especially during labor shortages. For instance, Marel has developed AI-enabled machinery that can precisely sort, cut, and package meat products, improving both efficiency and accuracy in production. IoT integration also allows real-time monitoring of equipment performance, predictive maintenance, and seamless tracking of the production process, ensuring smoother operations and minimizing downtime. These technologies not only optimize production processes but also reduce waste and energy consumption, making meat processing more sustainable and cost-effective in the long run
Growing Consumer Demand for Protein-Rich Diets:
The global shift toward health and wellness has increased consumer interest in protein-rich diets, with meat being a primary source of protein for many. As awareness of the benefits of high-protein diets grows, demand for meat products, especially processed meat, is expected to increase further. This dietary trend, coupled with the rise in sports nutrition and fitness-oriented products, has led meat processors to expand production capacities and adopt more efficient equipment to meet this growing consumer demand. Meat processing equipment that can handle increased production volumes while maintaining product quality is essential for companies looking to capitalize on this trend. This growing emphasis on protein intake not only supports market growth but also encourages innovation in the types of processed meat products being offered, further boosting demand for specialized equipment.
Market Trends:
Automation and Robotics Integration:
One of the key trends in the meat processing equipment market is the integration of automation and robotics, as companies strive to improve efficiency and precision. Automated equipment, such as robotic arms and advanced slicing machines, can handle repetitive and labor-intensive tasks with greater speed and accuracy than human labor. This technology is especially beneficial in streamlining processes like cutting, deboning, and packaging, reducing labor costs and minimizing product wastage. By 2025, the adoption of automation in meat processing is projected to increase by nearly 30% across the industry, driven by the rising cost of labor and the demand for higher productivity. Robotics and automation are expected to become standard features in new equipment installations, enhancing both scalability and profitability for meat processing companies.
Increasing Adoption of Sustainable Equipment:
Sustainability has become a crucial factor in the food processing industry, and the meat processing equipment market is no exception. Equipment manufacturers are focusing on eco-friendly designs that minimize energy consumption, reduce water usage, and lower waste production. For example, machines with energy-efficient motors and water-saving systems are gaining traction as companies aim to reduce their environmental footprint. Furthermore, advancements in recycling capabilities are allowing equipment to be used longer and with less waste. Industry analysts predict that the demand for sustainable meat processing equipment will grow at an annual rate of around 8% over the next few years as companies adopt these technologies to align with corporate sustainability goals and meet consumer expectations for environmentally responsible practices.
Growth of Plant-Based Meat Processing Equipment:
The rise of plant-based and alternative protein products has opened a new niche within the meat processing equipment market. As consumer interest in plant-based proteins grows, traditional meat processing companies and new entrants are investing in equipment specifically designed for the production of plant-based meats. These products often require specialized processing methods to achieve a texture and flavor similar to animal-based meat, and this has led to the development of new equipment categories, such as high-moisture extrusion machines and advanced blending systems. For instance, Bühler Group, a technology provider for food processing, notes that their high moisture extrusion systems for plant-based meat production can process up to 1,000 kg of product per hour. Beyond Meat, a leading plant-based meat company, invested $32 million in new production equipment in 2020 to expand their manufacturing capabilities. The plant-based meat equipment market is expected to expand by nearly 20% over the next five years, reflecting the increasing popularity of meat alternatives and the need for equipment capable of handling these innovative products.
Technological Advancements in Food Safety and Traceability:
Traceability and food safety remain central to the meat processing industry, and new technological advancements are making it easier to meet these demands. Equipment now frequently includes digital tracking systems that monitor every stage of the production process, from raw material handling to packaging. Blockchain technology and QR code scanning capabilities have also become prominent in tracking meat products' origins and processing history, providing transparency for consumers and improving recall management. For instance, according to IBM, their Food Trust blockchain platform for food traceability has been adopted by major meat producers and can reduce the time to trace the origin of food products from days to seconds. With food safety regulations becoming stricter worldwide, the market for traceability-enabled equipment is expected to grow by over 15% annually through 2028. These advancements not only support compliance but also bolster consumer trust, giving companies a competitive edge in a highly regulated industry.
Market Restraints and Challenges:
High Initial Investment Costs:
One of the primary restraints in the meat processing equipment market is the high initial cost associated with purchasing and installing advanced machinery. Automated and technologically sophisticated equipment often requires significant capital investment, which can be a barrier for small and medium-sized enterprises (SMEs) with limited budgets. The cost of integrating technologies like robotics, artificial intelligence, and IoT capabilities into processing lines can deter smaller companies, limiting market penetration. Additionally, the need for continuous upgrades to keep pace with technological advancements further adds to the cost burden, affecting the return on investment for many businesses.
Stringent Regulatory Compliance:
Compliance with strict food safety and quality regulations poses a challenge for companies in the meat processing equipment market. These regulations vary by region and often require manufacturers to adopt costly equipment modifications to meet safety, hygiene, and environmental standards. For instance, adhering to standards such as the Hazard Analysis and Critical Control Points (HACCP) and other international quality certifications can be both time-consuming and costly. Frequent regulatory updates also force companies to regularly adjust their processes and invest in specialized equipment, which can strain financial resources and operational flexibility, especially for smaller firms.
Limited Skilled Workforce:
The increasing automation of meat processing equipment requires a skilled workforce trained in handling sophisticated machinery, yet a shortage of qualified operators poses a challenge for the industry. Operating automated systems, managing AI-driven equipment, and interpreting data from IoT-integrated machines require specific skills and expertise. Many processing plants, particularly in developing regions, struggle to find workers with the necessary technical knowledge, which can lead to inefficiencies or increased downtime. This shortage not only impacts production efficiency but also raises costs associated with training and development, making it difficult for companies to fully utilize advanced processing technologies.
Fluctuations in Meat Supply and Prices:
Volatility in the supply and pricing of raw meat products is another restraint impacting the meat processing equipment market. Factors such as diseases, climate conditions, and trade restrictions can disrupt meat supplies and drive up prices, directly affecting production costs and profitability. These fluctuations create challenges for processing companies in terms of maintaining steady production levels and managing costs, impacting the demand for new equipment and the industry’s overall growth potential.
Market Segmentation Analysis:
The meat processing equipment market is segmented into various categories by product type, meat type, automation level, and application, each contributing uniquely to the market’s growth.
By product type, cutting, blending, tenderizing, filling, slicing, grinding, smoking, and massaging equipment dominate, with cutting and grinding equipment accounting for significant shares due to their essential roles in initial processing stages. Advanced machinery, such as brine injectors, emulsifying machines, and ice flakers, is also gaining traction for specialized applications, driven by demand for product variety and enhanced flavors.
By meat type, processed pork and processed beef hold the largest share in the market, propelled by the high consumption levels in North America and Europe. Processed mutton and niche meats, including horse, rabbit, camel, and yak, represent a smaller but steadily growing segment, especially in regions with cultural preferences for these meats.
By automation segment divides into automatic and semi-automatic equipment, with automatic systems growing rapidly as companies strive to reduce labor costs and increase efficiency. Automation in meat processing not only enhances productivity but also supports stringent quality control standards, making it a preferred choice among large-scale processors.
By application, fresh processed meat, raw cooked meat, and cured meat categories account for substantial demand, with applications across catering, meat shops, hotels, restaurants, and dedicated meat processing units. Further processing applications in poultry industries and other specialized processes like sun-drying, mincing, and grinding are also contributing to market expansion, particularly as the industry explores innovative products to meet evolving consumer tastes.
Segmentation:
By Product:
- Cutting Equipment
- Blending Equipment
- Tenderizing Equipment
- Filling Equipment
- Slicing Equipment
- Grinding Equipment
- Smoking Equipment
- Massaging Equipment
- Other Types (Brine Injectors, Emulsifying Machines, and Ice Flakers)
By Meat Type:
- Processed Pork
- Processed Beef
- Processed Mutton
- Others (Horses, rabbits, Camels, and Yak)
By Automation:
- Automatic
- Semi-Automatic
By Application:
- Fresh Processed Meat
- Raw Cooked Meat
- Precooked Meat
- Raw Fermented Sausage
- Cured Meat
- Dried Meat
- Catering
- Meat Shop
- Hotel
- Restaurant
- Meat Processing Unit
- Poultry Industries
- Further Processing
- Other (Sun-Drying Meat, Mincing, and Grinding Meat)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The meat processing equipment market shows distinct regional trends, with North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa each holding a unique share in the global market.
North America currently leads with the largest market share, accounting for approximately 35% of the global market. The region’s dominance is driven by high meat consumption rates, a well-developed meat processing industry, and extensive adoption of automation and advanced processing technologies. The U.S., being one of the largest meat consumers and producers globally, significantly contributes to this share, with demand for processed meats such as beef and pork being major factors supporting equipment investments.
Europe holds the second-largest market share, representing around 28% of the global market. The European market is characterized by strict regulatory standards on food safety, driving demand for high-quality and compliant meat processing equipment. Countries like Germany, France, and the UK are prominent consumers due to a combination of high meat consumption and established food processing industries. Additionally, Europe’s focus on sustainable and energy-efficient technologies has pushed manufacturers to adopt eco-friendly equipment, further supporting the market's growth in this region.
The Asia-Pacific region is the fastest-growing market for meat processing equipment, with an expected annual growth rate surpassing other regions. Currently accounting for approximately 22% of the global market share, the region is projected to increase significantly due to rising urbanization, population growth, and increasing disposable incomes in countries like China, India, and Japan. Changing dietary habits, with more people incorporating meat into their diets, are also driving the demand for processed meat products. As more consumers in these markets seek convenience foods, the adoption of advanced meat processing equipment in the Asia-Pacific region is anticipated to rise, particularly in automated and semi-automated segments.
Latin America accounts for around 10% of the market share, showing steady growth fueled by rising meat consumption, especially in countries like Brazil and Argentina, which have strong meat production industries. The demand for processing equipment is supported by growing export activities and increasing demand for processed meats within the region. However, economic fluctuations and infrastructure limitations pose challenges that can impact the pace of growth.
The Middle East & Africa holds the smallest share of the market, at approximately 5%, but shows potential for growth due to increasing demand for meat and processed products, particularly in urbanized areas. Economic development and rising consumer preference for convenience foods are key drivers. However, challenges like economic instability and low technological adoption in some countries have limited the rapid growth seen in other regions. As infrastructure improves, the demand for modern meat processing equipment in this region is expected to gradually increase, especially in the Gulf Cooperation Council (GCC) countries, where consumption of processed meat is on the rise.
Key Player Analysis:
- Bettcher Industries, Inc.
- Equipamientos cárnicos, S.L. (MAINCA)
- Fortifi Food Processing Solutions.
- Marel
- Mepaco
- Minerva Omega Group s.r.l.
- Nemco Food Equipment, LTD.
- RAM Beef Equipment, LLC
- The Middleby Corporation
- Tomra Systems ASA
Competitive Analysis:
The meat processing equipment market is highly competitive, with numerous key players focusing on technological innovation, product quality, and expansion into emerging markets. Major companies, including Marel, GEA Group, JBT Corporation, and The Middleby Corporation, dominate the landscape by offering a wide range of advanced processing equipment designed for efficiency, precision, and compliance with stringent food safety standards. These companies invest heavily in research and development to introduce automation, robotics, and IoT-enabled systems that meet evolving industry demands. Smaller players and regional companies also contribute to the market by offering specialized or cost-effective solutions, appealing to small and medium-sized enterprises (SMEs). Competitive strategies, such as mergers, acquisitions, and partnerships, are common, allowing companies to strengthen their market presence and broaden product portfolios. The intensifying competition, combined with increasing consumer demand for processed meat products, continues to drive innovation and market consolidation within the meat processing equipment sector.
Recent Developments:
- In July 2024, Fortifi Food Processing Solutions acquired LIMA S.A.S., a French company specializing in the design and manufacture of meat processing equipment. This acquisition strengthens Fortifi's capabilities in protein processing and supports its growth strategy, enhancing its portfolio alongside brands such as Bettcher Industries and Frontmatec.
- In May 2022, Bettcher Industries, Inc. acquired Frontmatec, a producer of automated protein processing equipment. This acquisition aims to broaden Bettcher's expertise and product range in the protein processing sector. Integrating Frontmatec's technology is expected to reinforce Bettcher's market position, offering customers more advanced solutions for protein processing.
- In July 2022, JBT Corporation acquired Alco-food-machines GmbH & Co. KG (Alco) to expand its product offerings in further processing, enhancing its ability to serve the protein processing market with a wider range of solutions.
Market Concentration & Characteristics:
The meat processing equipment market is moderately concentrated, with a few dominant players holding significant market shares due to their extensive product portfolios, technological expertise, and established global presence. Major companies like Marel, GEA Group, and JBT Corporation lead the market, leveraging advanced automation, robotics, and IoT-enabled solutions to meet industry demands for efficiency and compliance with food safety standards. Smaller and regional players contribute by focusing on specialized equipment or cost-effective solutions, catering primarily to small and medium-sized enterprises (SMEs). The market is characterized by high capital investment requirements, a strong emphasis on product quality and innovation, and stringent regulatory standards, particularly in developed regions. Additionally, companies frequently engage in strategic mergers, acquisitions, and partnerships to expand market share and enhance product offerings. As demand for processed meat products grows, the competitive landscape remains dynamic, driving continuous technological advancements and service enhancements in the industry.
Report Coverage:
The research report offers an in-depth analysis based on By Product, By Meat Type, By Automation and By Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing automation and robotics adoption will streamline operations and reduce labor costs across the industry.
- Demand for sustainable, energy-efficient equipment is expected to grow as companies prioritize eco-friendly practices.
- Asia-Pacific’s rapid urbanization and rising disposable incomes will drive significant demand for meat processing equipment.
- Advancements in AI and IoT integration will enable precise monitoring, predictive maintenance, and process optimization.
- Plant-based and alternative protein processing equipment will see expansion as consumer interest in meat substitutes rises.
- Stricter food safety regulations will spur investment in equipment with advanced hygiene and traceability features.
- Growing protein consumption globally will lead to increased equipment sales, especially in emerging markets.
- Increased focus on product innovation will drive R&D spending, leading to more versatile, multi-functional equipment.
- Strategic mergers and acquisitions are likely to accelerate, consolidating market positions and expanding product portfolios.
- The rise of e-commerce in equipment sales may make advanced technology more accessible to smaller businesses.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Convenience and Ready-to-Eat Foods
Busy lifestyles and urbanization have led to a surge in demand for processed and ready-to-eat meat products, prompting manufacturers to invest in advanced processing equipment to increase production capacity and efficiency.
Stringent Food Safety and Quality Regulations
Tightening global food safety standards require meat processors to adopt high-quality, hygienic, and automated equipment, driving upgrades and new purchases to ensure compliance and reduce contamination risks.
Technological Advancements and Automation
The integration of automation, robotics, AI, and IoT in meat processing equipment is enhancing operational efficiency, reducing labor dependency, and enabling real-time monitoring, which attracts investment and accelerates equipment adoption.
Rising Demand for Protein-Rich Diets
Increasing consumer focus on health and wellness is boosting the consumption of protein-rich foods, particularly processed meats, leading processors to expand capacity and invest in equipment that can handle higher volumes while maintaining quality.
Sustainability and Energy Efficiency Initiatives
Growing emphasis on sustainability in the food industry is driving demand for energy-efficient, water-saving, and eco-friendly meat processing equipment, as companies seek to reduce their environmental footprint and align with regulatory and consumer expectations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Meat Processing Equipment Market?
What factors are driving the demand for meat processing equipment?
Which region is expected to grow the fastest?
What challenges does the meat processing equipment market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Cutting Equipment
- 1.2.2 Blending Equipment
- 1.2.3 Tenderizing Equipment
- 1.2.4 Filling Equipment
- 1.2.5 Slicing Equipment
- 1.2.6 Grinding Equipment
- 1.2.7 Smoking Equipment
- 1.2.8 Massaging Equipment
- 1.2.9 Other Types (Brine Injectors, Emulsifying Machines, Ice Flakers)
- 1.3 By Meat Type
- 1.3.1 Processed Pork
- 1.3.2 Processed Beef
- 1.3.3 Processed Mutton
- 1.3.4 Others (Horses, Rabbits, Camels, Yak)
- 1.4 By Automation
- 1.4.1 Automatic
- 1.4.2 Semi-Automatic
- 1.5 By Application
- 1.5.1 Fresh Processed Meat
- 1.5.2 Raw Cooked Meat
- 1.5.3 Precooked Meat
- 1.5.4 Raw Fermented Sausage
- 1.5.5 Cured Meat
- 1.5.6 Dried Meat
- 1.5.7 Catering
- 1.5.8 Meat Shop
- 1.5.9 Hotel
- 1.5.10 Restaurant
- 1.5.11 Meat Processing Unit
- 1.5.12 Poultry Industries
- 1.5.13 Further Processing
- 1.5.14 Other (Sun-Drying Meat, Mincing, Grinding Meat)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 11,734.00 million → 2032: USD 18,517.73 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Meat Processing Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Meat Processing Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Meat Processing Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Meat Processing Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Meat Processing Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Meat Processing Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Meat Processing Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Meat Processing Equipment Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 11,734.00 million → 2032: USD 18,517.73 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Meat Processing Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cutting Equipment
- 12.3.7.2 Blending Equipment
- 12.3.7.3 Tenderizing Equipment
- 12.3.7.4 Filling Equipment
- 12.3.7.5 Slicing Equipment
- 12.3.7.6 Grinding Equipment
- 12.3.7.7 Smoking Equipment
- 12.3.7.8 Massaging Equipment
- 12.3.7.9 Other Types (Brine Injectors, Emulsifying Machines, Ice Flakers)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Meat Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Processed Pork
- 12.4.7.2 Processed Beef
- 12.4.7.3 Processed Mutton
- 12.4.7.4 Others (Horses, Rabbits, Camels, Yak)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Automation - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automatic
- 12.5.7.2 Semi-Automatic
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Fresh Processed Meat
- 12.6.7.2 Raw Cooked Meat
- 12.6.7.3 Precooked Meat
- 12.6.7.4 Raw Fermented Sausage
- 12.6.7.5 Cured Meat
- 12.6.7.6 Dried Meat
- 12.6.7.7 Catering
- 12.6.7.8 Meat Shop
- 12.6.7.9 Hotel
- 12.6.7.10 Restaurant
- 12.6.7.11 Meat Processing Unit
- 12.6.7.12 Poultry Industries
- 12.6.7.13 Further Processing
- 12.6.7.14 Other (Sun-Drying Meat, Mincing, Grinding Meat)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Meat Processing Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Meat Processing Equipment Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Meat Processing Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Meat Processing Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Marel
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GEA Group
- 18.4 JBT Corporation
- 18.5 The Middleby Corporation
- 18.6 Bettcher Industries, Inc.
- 18.7 Fortifi Food Processing Solutions
- 18.8 Minerva Omega Group s.r.l.
- 18.9 Tomra Systems ASA
- 18.10 Equipamientos cárnicos, S.L. (MAINCA)
- 18.11 Mepaco
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

