
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Micro Data Centers Market Size 2023 | USD 5,673.28 Million |
| Micro Data Centers Market, CAGR | 14.36% |
| Micro Data Centers Market Size 2032 | USD 18,723.49 Million |
Market Overview
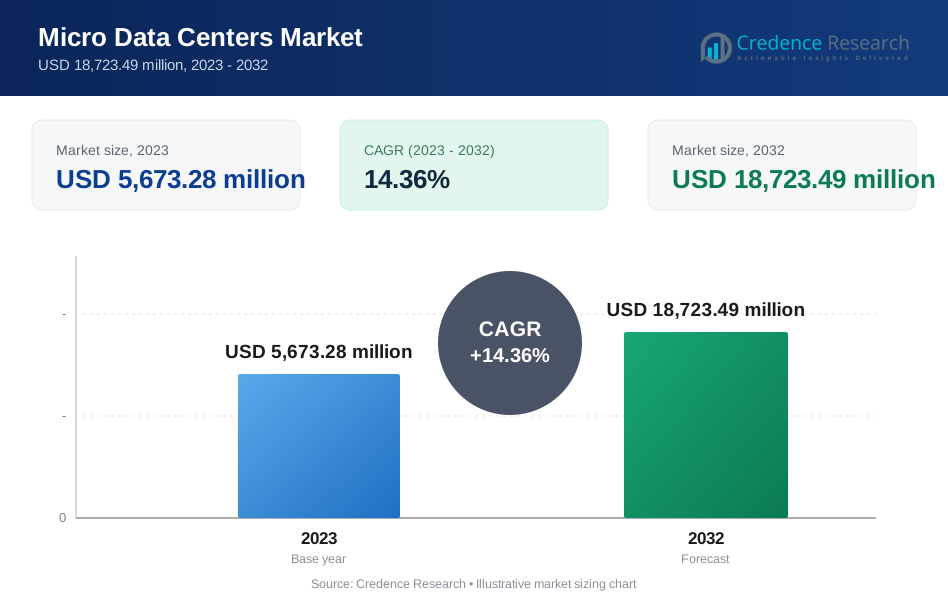
The Micro Data Centers Market is projected to grow from USD 5,673.28 million in 2023 to an estimated USD 18,723.49 million by 2032, with a compound annual growth rate (CAGR) of 14.36% from 2024 to 2032. This growth reflects the increasing demand for compact, scalable, and efficient data storage solutions that support edge computing, IoT integration, and data processing close to the source.
Key drivers contributing to this market's growth include the surge in IoT-enabled devices and the expansion of edge computing to manage high data volumes in real-time. As organizations seek to optimize their IT infrastructure, micro data centers provide a viable solution with reduced operational costs, minimal space requirements, and simplified installation and maintenance. Trends such as increasing investments in data center infrastructures and the adoption of cloud services further reinforce the market’s upward trajectory, with major companies actively innovating to enhance data security, energy efficiency, and storage capabilities.
Geographically, North America dominates the micro data centers market due to high adoption rates of advanced technology and robust IT infrastructure. However, the Asia-Pacific region is expected to exhibit the highest growth rate, driven by the rapid digital transformation in emerging economies and the expansion of smart city initiatives. Key players in this market include Schneider Electric, Eaton Corporation, Vertiv Group Corp., and Huawei Technologies Co., Ltd., who are leading innovations to address evolving demands and enhance product offerings in response to industry requirements.
Market Drivers
Growing Demand for Edge Computing and Real-Time Data Processing
The rising adoption of edge computing is a significant driver for the micro data centers market. As more devices generate vast amounts of data through IoT (Internet of Things), it has become critical to process data close to its origin. For instance, workers use an average of 36 cloud-based services every day, while the average enterprise uses 1,295 cloud services, demonstrating the massive data processing requirements. Traditional data centers face challenges in terms of latency and bandwidth when managing large data volumes over long distances. Micro data centers address these issues by providing a compact, scalable, and flexible infrastructure that allows businesses to process data at the edge of networks. This enables real-time data processing, reducing latency and bandwidth requirements while improving response times for critical applications. Industries such as manufacturing, healthcare, and telecommunications are investing in edge computing to ensure seamless data transfer, faster decision-making, and reduced downtime, all of which contribute to the growing demand for micro data centers.
Rise in IoT Devices and Expansion of Digital Infrastructure
The rapid proliferation of IoT devices across various sectors is another crucial factor driving the micro data centers market. For instance, enterprises typically utilize 2.6 public clouds and 2.7 private clouds in their operations, highlighting the complex infrastructure needs. The expansion of digital infrastructure has led to an exponential increase in data generated by connected devices in smart homes, factories, and cities. For instance, among enterprises using cloud computing, 82.7% use it for email services and 68% for file storage, showing the diverse applications requiring data processing. This data requires efficient storage and processing solutions that are both scalable and cost-effective. Micro data centers offer the ideal solution, as they are easy to deploy and maintain while meeting the performance needs of IoT applications. They also enhance data security and reduce the risks associated with transferring sensitive information over large distances. As companies worldwide continue to integrate IoT technology, the need for on-premise, near-edge data centers will grow, providing momentum for the micro data centers market.
Increasing Adoption of Cloud Services and Hybrid Data Environments
The adoption of cloud computing has redefined data management, yet many enterprises still require on-premise solutions to address specific needs. For instance, large enterprises demonstrate high cloud adoption rates, with 77.6% purchasing cloud services in 2023, indicating the scale of hybrid infrastructure requirements. As more businesses embrace hybrid data environments, they are looking for infrastructure that supports a blend of cloud and on-site processing capabilities. For instance, the information and communication sector leads cloud adoption with 79% of businesses in this sector using cloud computing services, demonstrating sector-specific demands. Micro data centers offer a bridge between these environments, allowing organizations to store data securely on-site while accessing cloud resources as needed. They also enhance flexibility, enabling businesses to maintain data sovereignty and comply with data privacy regulations. For instance, cloud data centers currently account for 3% of the world's total energy consumption, emphasizing the need for efficient, localized data processing solutions. With the increasing reliance on hybrid cloud solutions, micro data centers are becoming an essential component in supporting the efficient functioning of these environments, thereby driving the market growth.
Growing Focus on Energy Efficiency and Reduced Operational Costs
Micro data centers are emerging as a preferred solution for organizations prioritizing energy efficiency and cost-effectiveness. Traditional data centers consume considerable energy due to the need for constant cooling and maintenance. Micro data centers, however, are designed to be energy-efficient and require minimal cooling and space, significantly lowering operational costs. In addition, they offer modular designs, allowing companies to scale infrastructure without the high capital expenditure associated with traditional data centers. This cost-effective nature makes micro data centers particularly appealing to small and medium-sized enterprises, which often lack the resources to build large-scale data centers. Moreover, the focus on sustainable, energy-efficient data infrastructure aligns with global trends in green technology and environmental responsibility, further accelerating demand for micro data centers.
Market Trends
Integration of Advanced Cooling Solutions and Energy-Efficient Technologies
A prominent trend in the micro data centers market is the focus on energy-efficient technologies, particularly through advanced cooling solutions. As data processing demands increase, so does the need for effective cooling to prevent hardware overheating and maintain optimal performance. Traditional data centers often consume high levels of energy for cooling, but micro data centers, designed to be compact and scalable, are increasingly incorporating energy-efficient cooling mechanisms. For instance, JetCool's microconvective liquid cooling technology has demonstrated a reduction in chip temperatures by 30 degrees while conducting heat 3,000 times more effectively than traditional air cooling systems. Techniques such as liquid cooling, in-row cooling, and economizer systems are becoming more popular, offering enhanced energy management and reducing overall operational costs. These advanced solutions are essential as companies prioritize sustainability and strive to reduce their environmental footprint. The integration of energy-efficient systems not only minimizes power consumption but also aligns with global sustainability goals, a significant factor for enterprises committed to corporate social responsibility.
Increased Adoption of Modular and Customizable Micro Data Center Solutions
Another key trend is the rising demand for modular and customizable micro data center solutions. Traditional data centers require substantial investment, space, and time for deployment, limiting flexibility for companies that need rapid scaling capabilities. Micro data centers, however, offer modular solutions that are easy to deploy, configure, and scale based on demand. For instance, modular data centers require commercial commitments of 15 to 25 years with vendors, highlighting the long-term nature of these infrastructure investments. Customization options allow organizations to tailor data centers to their specific needs, adjusting storage capacity, security measures, and connectivity options. This modularity appeals particularly to industries with fluctuating data needs, such as retail, finance, and telecommunications, where data demands can vary seasonally or based on market conditions. The scalability of micro data centers ensures that businesses can expand or reduce their data infrastructure quickly and affordably, optimizing performance without committing to high upfront costs. Furthermore, the modular approach facilitates seamless integration with cloud-based and hybrid environments, supporting organizations' efforts to create flexible, resilient IT ecosystems.
Market Restraints and Challenges
High Initial Setup and Maintenance Costs
Although micro data centers offer operational efficiencies and lower long-term costs, the initial setup and configuration expenses present a significant barrier for many organizations, particularly small and medium-sized enterprises. The costs associated with procuring equipment, implementing advanced cooling and energy-efficient technologies, and ensuring robust security measures can be substantial. Additionally, while micro data centers are designed for minimal maintenance, certain installations may require specialized maintenance staff or outsourcing to manage technical aspects and security protocols effectively. These requirements can increase operational costs, potentially outweighing the benefits for companies with limited resources. The high upfront investment and ongoing maintenance costs can deter organizations from adopting micro data centers, particularly when cost-effective alternatives like shared data center services are available.
Security Concerns and Limited On-Site Expertise
Security is a significant concern in the micro data centers market, especially for companies implementing edge computing in remote locations with limited physical security. While micro data centers offer enhanced data processing speeds by positioning infrastructure closer to data sources, this decentralization can increase vulnerability to cyber-attacks, unauthorized access, and data breaches. Many organizations may also lack the on-site expertise needed to handle the complexities of micro data center management, such as monitoring physical security, cybersecurity, and equipment troubleshooting. Smaller data centers in remote or unmanned locations are particularly vulnerable, as they may not have the resources or personnel to implement rigorous security protocols. These security and expertise challenges may slow the adoption of micro data centers among businesses that prioritize data protection and compliance, potentially limiting market growth in sensitive or highly regulated industries.
Market Segmentation Analysis
By Component
The micro data centers market is divided into solutions and services. The solutions segment dominates, driven by the high demand for compact, scalable data center infrastructure across various industries. This includes hardware such as servers, storage, cooling systems, and power management units. Meanwhile, services are growing steadily due to increasing demand for maintenance, installation, monitoring, and consulting services. Companies rely on these services to maximize the efficiency and lifespan of their micro data centers, ensuring seamless operations and addressing security needs. The services segment is expected to see further growth as companies increasingly outsource management tasks to specialized providers.
By Rack Unit
Rack unit segmentation reflects different micro data center sizes suited to various enterprise needs. The Up to 24U segment is popular among small and medium-sized enterprises (SMEs) and locations with limited space, as these micro data centers are compact and cost-effective. The 24U to 40U segment, catering to mid-size to larger installations, sees demand from organizations with moderate data needs, including industries like healthcare and retail. The Above 40U segment addresses high-capacity needs in large organizations or high-data applications, particularly within sectors like telecommunications and IT. This segmentation by rack size allows companies to select a data center solution that aligns with their specific space and processing requirements.
Segments
Based on Component
- Solution
- Services
Based on rack unit
- Upto 24U
- 24U to 40U
- Above 40U
- Based on enterprise size
- Large Enterprises
- Small and Medium-Sized Enterprises (SMEs)
Based on industry
- BFSI
- IT & Telecommunication
- Healthcare
- Industrial
- Others
Based on region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis
North America (35%)
North America holds the largest market share, accounting for approximately 35% of the global micro data centers market. The United States and Canada, as leaders in technological advancement and digital infrastructure, drive this demand. High adoption rates of edge computing, IoT, and 5G technologies fuel North America’s dominance, particularly in sectors like IT and telecommunications, banking, and retail. Additionally, stringent regulatory requirements for data privacy and security, coupled with a growing focus on sustainable and energy-efficient solutions, propel market growth in this region. Large enterprises and service providers are investing heavily in compact data solutions to reduce latency, improve data processing efficiency, and enhance customer experience.
Asia-Pacific (28%)
The Asia-Pacific region is the fastest-growing in the global micro data centers market, accounting for roughly 28% of the market share. Rapid digital transformation across industries, the expansion of smart city initiatives, and increasing penetration of IoT and 5G networks are key growth drivers in this region. Countries such as China, Japan, India, and South Korea are investing significantly in micro data center solutions to support their expanding data requirements. The rise of SMEs in emerging economies and the demand for cost-effective, scalable data storage solutions further contribute to Asia-Pacific’s high growth rate. As companies strive to deliver seamless data processing at the edge, the demand for micro data centers in Asia-Pacific is expected to continue rising.
Key players
- IBM Corporation
- Rittal GmbH & Co. KG
- Vertiv Group Corp.
- Delta Power Solutions
- ALTRON
- Eaton Corporation
- Dell Inc.
- Huawei Technologies Co. Ltd.
- Panduit Corp.
- Hitachi Energy Ltd.
Competitive Analysis
The Global Micro Data Centers Market is highly competitive, with leading companies focusing on technological innovation, strategic partnerships, and expanding their product portfolios to strengthen their market positions. IBM Corporation and Vertiv Group Corp. leverage their robust R&D capabilities and advanced product offerings to address growing demands in edge computing and energy efficiency. Huawei Technologies Co. Ltd. and Dell Inc. are expanding their market reach through aggressive investments in emerging markets, particularly in Asia-Pacific, where digital transformation is accelerating.Other key players like Eaton Corporation and Rittal GmbH & Co. KG differentiate themselves by focusing on modular solutions and sustainable infrastructure, appealing to industries aiming for energy efficiency. Smaller but impactful players, such as Panduit Corp. and Delta Power Solutions, contribute by offering niche, customized solutions tailored to specific enterprise needs. This diverse competitive landscape is marked by a blend of large, established players and smaller, specialized companies, each adapting to meet the evolving demands of the global micro data centers market.
Recent Developments
- In April 2024, IBM announced its intent to acquire HashiCorp, a leading multi-cloud infrastructure automation company, for $6.4 billion. While not directly related to micro data centers, this acquisition could potentially enhance IBM's capabilities in managing and automating distributed computing environments, including micro data centers.
- In May 2024, Rittal showcased its RiMatrix Micro Data Centres at an industry event, highlighting their customizable solutions for efficient data processing. These micro data centers are designed to meet the evolving needs of industries dealing with rapid digital transformation.
- In January 2024, Vertiv announced plans to more than double its global manufacturing capacity for switchgear, busway, and integrated modular solutions by the end of 2025. This expansion aims to support the increasing demand for data center power infrastructure, including applications for AI and high-performance computing.
- In May 2024, Delta showcased its energy-saving power, cooling, and ICT infrastructure solutions for cloud to edge AI data centers at COMPUTEX 2024. This included solutions applicable to micro data centers, emphasizing energy efficiency and thermal management.
- In 2024, Altron announced a name change for its key modular data center products. The company rebranded its Mobile DC to EdgeDC and Micro DC to StackDC, along with introducing a new product called CoreDC. These changes reflect Altron's focus on edge computing and modular data center solutions.
- In May 2024, Huawei held the Global Data Center Facility Summit 2024 in Singapore, where they showcased all-scenario, all-ecosystem, and all-service end-to-end (E2E) solutions for data centers. This included innovations in micro data center technologies, emphasizing fast deployment, flexible cooling, and green energy solutions.
- In September 2024, Hitachi completed the acquisition of MA micro automation GmbH, a leading provider of robotic and automation technology. While not directly related to micro data centers, this acquisition could potentially enhance Hitachi's capabilities in automating and optimizing data center operations, including micro data centers.
Market Concentration and Characteristics
The Global Micro Data Centers Market exhibits a moderately concentrated structure, with several dominant players, including IBM Corporation, Vertiv Group Corp., and Huawei Technologies, holding substantial market shares due to their established brand presence, comprehensive product offerings, and R&D capabilities. These key companies set market standards by continuously innovating in energy efficiency, modularity, and security features to meet evolving customer needs. However, the market also sees contributions from smaller, specialized firms that focus on niche or customized solutions, such as Delta Power Solutions and Panduit Corp., catering to specific industry demands. The market's characteristics include rapid technological advancements, driven by rising edge computing requirements and IoT integration, along with a strong emphasis on scalability and sustainability. This blend of large, established players and agile, niche firms supports a competitive yet innovation-driven environment, poised for sustained growth as global demand for compact, efficient data storage solutions rises.
Report Coverage
The research report offers an in-depth analysis based on Component, rack unit, industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- As edge computing gains prominence, the demand for micro data centers will rise, driven by the need for localized data processing with minimal latency.
- Expanding IoT applications across industries will accelerate the deployment of micro data centers, enabling efficient data management close to the source.
- Future micro data centers will incorporate advanced cooling and energy-efficient solutions to address global sustainability standards and reduce operational costs.
- Modular, scalable micro data centers will become essential as businesses prioritize flexible infrastructure that can grow with their data processing needs.
- Rising digital transformation in emerging economies, particularly in Asia-Pacific and Latin America, will drive significant demand for cost-effective micro data center solutions.
- With data privacy regulations tightening worldwide, micro data centers will evolve to include robust security and compliance features for sensitive data management.
- Micro data centers will serve as vital components in hybrid cloud strategies, offering organizations on-premise data processing while enabling seamless cloud integration.
- Beyond IT and telecommunications, sectors like healthcare, retail, and manufacturing will increasingly adopt micro data centers to support their unique data requirements.
- Automation technologies, including AI-driven monitoring and predictive maintenance, will improve micro data center efficiency and reduce human intervention in operations.
- To enhance capabilities and market reach, key players will engage in strategic partnerships and mergers, shaping a competitive and dynamic micro data center landscape.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Global Micro Data Centers Market?
What is driving the growth of the Global Micro Data Centers Market?
Why are micro data centers essential in modern industries?
Which regions are leading the micro data centers market?
Who are the key players in the micro data centers market?
What trends are influencing the future of micro data centers?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Micro Data Centers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Micro Data Centers Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 5,673.28 million → 2032: USD 18,723.49 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Micro Data Centers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Micro Data Centers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Micro Data Centers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Micro Data Centers Market Drivers
- 3.3 Micro Data Centers Market Restraints & Challenges
- 3.4 Micro Data Centers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Micro Data Centers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Micro Data Centers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Micro Data Centers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Micro Data Centers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Micro Data Centers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Micro Data Centers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Micro Data Centers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Micro Data Centers Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Micro Data Centers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Micro Data Centers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Micro Data Centers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Micro Data Centers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Micro Data Centers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Micro Data Centers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Micro Data Centers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Micro Data Centers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Micro Data Centers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Micro Data Centers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Micro Data Centers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
