
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
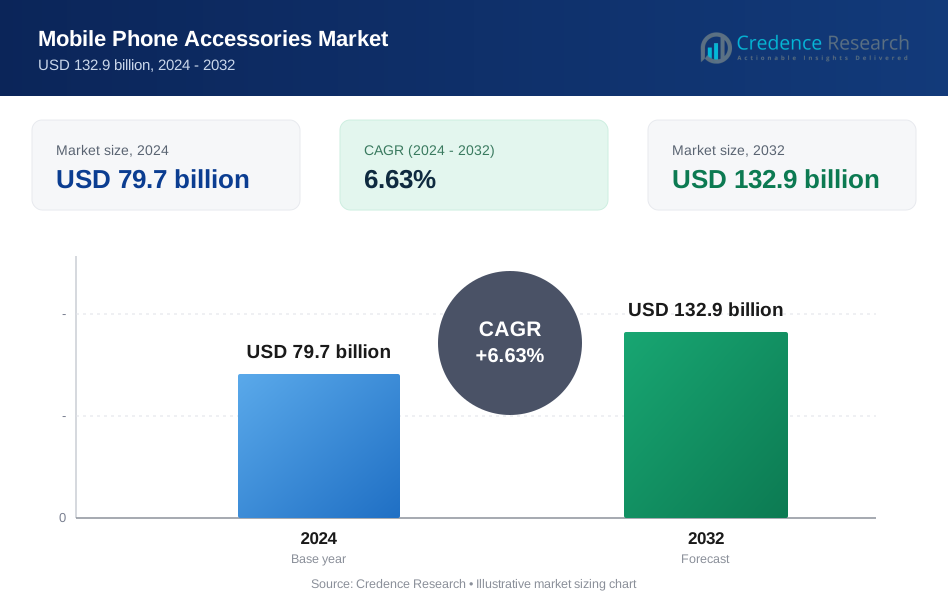
| Mobile Phone Accessories Market Size 2024 | USD 79.7 billion |
| Mobile Phone Accessories Market CAGR | 6.63% |
| Mobile Phone Accessories Market Size 2032 | USD 132.9 billion |
Market Overview
The Mobile Phone Accessories market size was valued at USD 54.6 billion in 2018 and USD 79.7 billion in 2024, and is anticipated to reach USD 132.9 billion by 2032, at a CAGR of 6.63% during the forecast period. The Mobile Phone Accessories market is characterized by strong competition among top players such as Apple Inc., Samsung Electronics Co., Ltd., Belkin International, Inc., Anker Innovations Limited, Logitech International S.A., Aukey Technology Co., Ltd., RAVPower, Mophie, OtterBox, and Case-Mate. These companies maintain their leadership through robust product portfolios, continuous innovation, and expansive global distribution networks. Asia Pacific leads the market with a 35.6% share, driven by high smartphone adoption and large consumer bases in countries like China and India. North America and Europe follow, with market shares of 15.4% and 18.7% respectively, supported by premium product demand and advanced retail infrastructure.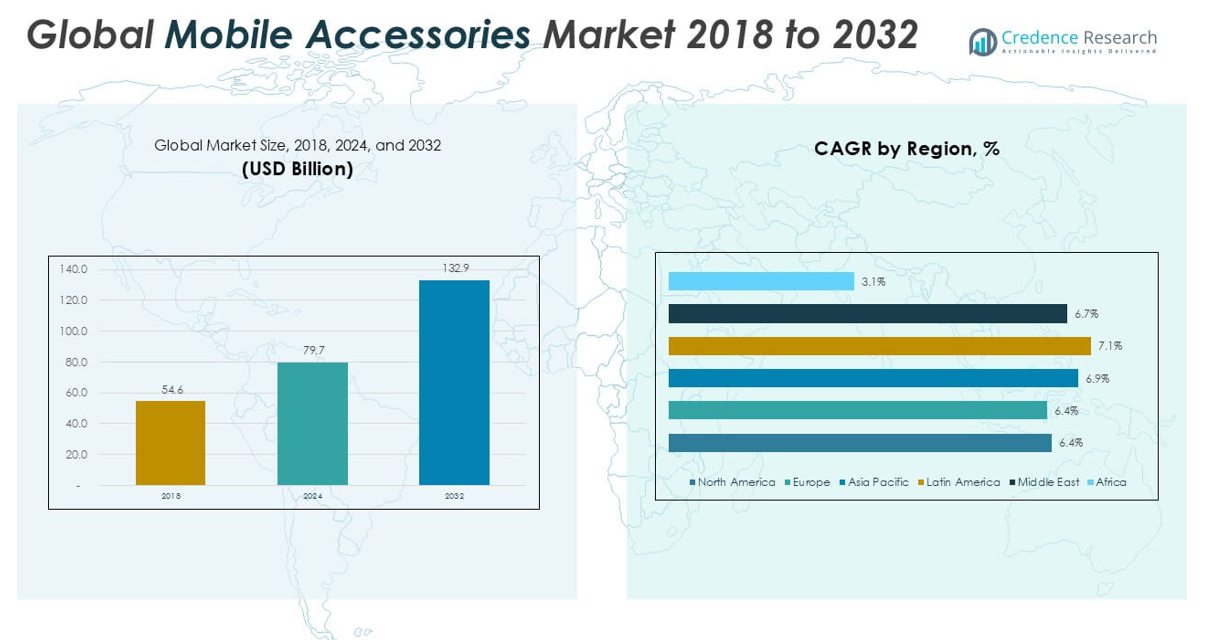
Market Insights
- The Mobile Phone Accessories market reached USD 79.7 billion in 2024 and is projected to achieve USD 132.9 billion by 2032, registering a CAGR of 6.63% during the forecast period.
- Rising global smartphone adoption, increasing demand for protective and functional accessories, and frequent device upgrades continue to drive robust market growth across all regions.
- Key trends include the shift toward wireless and smart accessories, rapid innovation in fast-charging and eco-friendly products, and growing consumer preference for customization and premium quality.
- The market is highly competitive, led by major players such as Apple Inc., Samsung Electronics Co., Ltd., Belkin International, Anker Innovations Limited, Logitech, and others, with Asia Pacific holding a dominant 35.6% regional share and mobile cases being the leading product segment.
Market Segmentation Analysis:
By Product Type: Mobile cases represent the largest share within the product type segment, primarily driven by the consistent demand for device protection and personalization. Rugged and designer cases dominate this space, appealing to a wide spectrum of consumers who value both durability and style. Chargers account for a substantial share of the Mobile Phone Accessories market, with fast-charging and wireless chargers emerging as the leading sub-segments. Consumer preference for efficient and quick power solutions drives this segment, especially as device usage intensifies. Mobile earphones & chargers form a robust segment, where true wireless earbuds command the highest market share. The battery segment captures a notable portion of the market, with replacement batteries and extended-life options leading the way. Consumers are replacing batteries more frequently due to increased mobile usage for gaming, streaming, and business. Power banks have become an indispensable accessory, especially among travelers and professionals requiring uninterrupted connectivity.- For instance, Xiaomi’s Mi Power Bank 3 Ultra Compact provides a capacity of 10,000 mAh and supports up to three devices simultaneously with its dual USB-A and single USB-C ports.
- For instance, Caterpillar’s Cat S62 Pro smartphone is designed for tough environments, meeting MIL-STD-810H standards for drop resistance up to 1.8 meters onto steel.
Market Overview
Rising Smartphone Penetration Growing global smartphone adoption drives robust demand for Mobile Phone Accessories. As emerging economies witness higher smartphone ownership, the need for protective cases, chargers, earphones, and power banks continues to rise. Consumers are increasingly seeking products that enhance device functionality, comfort, and longevity, which directly fuels market expansion. The proliferation of affordable smartphones in both urban and rural markets ensures sustained growth for the accessory ecosystem across diverse user demographics.- For instance, Samsung shipped 272 million smartphones worldwide in 2022, supporting increased demand for corresponding accessories.
- or instance, Belkin’s BOOST↑CHARGE PRO 3-in-1 Wireless Charger with MagSafe delivers up to 15 watts of wireless power for iPhone 12 and later, enabling simultaneous charging for iPhone, Apple Watch, and AirPods.
Key Trends & Opportunities
Shift Toward Wireless and Smart Accessories Consumer preference is shifting toward wireless and smart accessories, such as Bluetooth earphones, wireless chargers, and smart wearables. The convenience of untethered devices and integration with IoT ecosystems appeal to tech-focused users. This trend creates opportunities for manufacturers to introduce innovative products that address seamless connectivity, portability, and multi-device compatibility, expanding their footprint among early adopters and lifestyle-driven buyers.- For instance, Apple’s AirPods Max are equipped with custom-built 40-mm dynamic drivers and nine microphones, offering high-fidelity audio and adaptive noise cancellation, while seamlessly connecting across Apple devices using the H1 chip.
Key Challenges
Intense Market Competition and Price Pressure The Mobile Phone Accessories market faces intense competition, particularly from low-cost manufacturers and unbranded products. This environment puts pressure on established brands to differentiate through quality, innovation, and marketing. Price wars can erode profit margins, making it challenging for premium brands to maintain market share while balancing affordability and profitability. Counterfeit and Low-quality Products The prevalence of counterfeit and substandard products poses a significant challenge to the market. Fake accessories often fail to meet safety and performance standards, undermining consumer trust and damaging brand reputations. Regulatory oversight and consumer education are required to combat this issue and ensure the market’s healthy, sustainable growth. Rapid Technological Change Frequent advances in mobile device technology can render certain accessories obsolete. Manufacturers must invest continuously in research and development to stay ahead of changing compatibility requirements and evolving consumer preferences. Failure to adapt quickly risks inventory obsolescence and loss of relevance in a highly dynamic market.
Regional Analysis
North America North America accounted for USD 10.25 billion in 2018, rising to USD 14.81 billion in 2024, and is projected to reach USD 24.36 billion by 2032, with a CAGR of 6.4%. The region commands an estimated 15.4% market share in 2024, supported by strong smartphone adoption, frequent device upgrades, and high consumer spending on premium accessories. Technological advancements and widespread e-commerce channels further drive market growth. Early adoption of wireless charging and smart wearables reinforces North America’s role as a key revenue contributor in the global Mobile Phone Accessories market. Europe Europe reached a value of USD 12.49 billion in 2018, which grew to USD 17.96 billion in 2024 and is forecast to reach USD 29.36 billion by 2032, reflecting a CAGR of 6.4%. Holding a 18.7% share in 2024, Europe’s market is propelled by growing demand for stylish, functional accessories and the trend toward sustainability. Regulatory emphasis on product quality and safety boosts consumer trust. Robust retail networks and rapid uptake of new technologies ensure Europe remains a critical market for mobile accessory manufacturers. Asia Pacific Asia Pacific leads the global Mobile Phone Accessories market, valued at USD 22.68 billion in 2018, USD 33.60 billion in 2024, and expected to hit USD 57.13 billion by 2032, at a CAGR of 6.9%. Representing 35.6% of the market in 2024, the region benefits from surging smartphone penetration, population growth, and affordable device options. China and India are primary demand centers, fueled by price sensitivity and tech-savvy consumers. Expanding online retail and continuous innovation reinforce Asia Pacific’s dominant position. Latin America Latin America recorded USD 3.39 billion in 2018, increasing to USD 5.08 billion in 2024, and is projected to reach USD 8.78 billion by 2032, registering the highest CAGR at 7.1%. The region holds a 5.4% share in 2024, driven by expanding smartphone access and a youthful population. Market growth is supported by increasing internet connectivity, rising disposable incomes, and strong demand for affordable accessories. Local manufacturing and growing online distribution further fuel Latin America’s Mobile Phone Accessories sector. Middle East The Middle East market reached USD 4.67 billion in 2018, expanded to USD 6.85 billion in 2024, and is estimated to achieve USD 11.48 billion by 2032, with a CAGR of 6.7%. Capturing a 7.2% share in 2024, the market benefits from rising urbanization, increased smartphone usage, and a growing preference for high-quality accessories. Regional investments in digital infrastructure and a vibrant retail environment support further expansion, while consumer interest in premium products strengthens the market outlook. Africa Africa’s market grew from USD 1.09 billion in 2018 to USD 1.36 billion in 2024 and is forecast at USD 1.74 billion by 2032, with a CAGR of 3.1%. The region holds a modest 1.4% market share in 2024, limited by lower smartphone penetration and economic challenges. However, ongoing efforts to improve digital access and the popularity of low-cost accessories are gradually increasing demand. Urban centers show faster growth, supported by expanding retail networks and the adoption of entry-level smartphones across key African marketsMarket Segmentations:
By Product Type- Mobile Cases
- Chargers
- Mobile Earphones & Chargers
- Battery
- Power Banks
- Others
- Construction
- Bricks and Blocks
- Road Construction
- Portland Cement and Concrete
- Agriculture
- Mining
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Mobile Phone Accessories market features a mix of global technology leaders, specialized accessory manufacturers, and innovative new entrants. Major players such as Apple Inc., Samsung Electronics Co., Ltd., Belkin International, Inc., and Anker Innovations Limited dominate through strong brand recognition, extensive product portfolios, and continuous innovation in design and functionality. Companies like Logitech International S.A., Aukey Technology Co., Ltd., RAVPower, Mophie, OtterBox, and Case-Mate further intensify market competition by targeting niche segments and delivering specialized solutions such as rugged cases, advanced power banks, and wireless charging devices. These key players leverage wide distribution channels, strategic collaborations, and frequent product launches to maintain their competitive edge. The market also sees increasing competition from regional brands and low-cost manufacturers, which challenge established players on pricing and local relevance. Continuous investment in research, sustainable materials, and technology integration remains vital for sustaining market leadership.Key Player Analysis
- Apple Inc.
- Samsung Electronics Co., Ltd.
- Belkin International, Inc.
- Anker Innovations Limited
- Logitech International S.A.
- Aukey Technology Co., Ltd.
- RAVPower
- Mophie
- OtterBox
- Case-Mate
Recent Developments
- In March 2024, Apple has launched a new mobile phone case, watch band and iPhone camera mount accessories which will be available in pastel colors.
- In September 2024, Belkin, a leading consumer electronics brand for over 40 years, announced 11 new travel-ready products across its mobile charging category, as well as solutions to enable more flexible options to work while on the go.
- In July 2024, Samsung's accessory brand, Samsung Friends, is preparing to launch a number of new cases and add-ons for its latest mobile devices, including the Galaxy Buds 3 series, Galaxy Watches, and Galaxy Z Fold 6 and Z Flip 6 foldable phones.
- In September 2023, Samsung electronics co have launched a new Samsung eco friends accessories lineup which have made accessories from recycling materials.
- In April 2022, Samsung Electronics Co., Ltd. announced a partnership with plant-based designer Sean Wotherspoon to launch an eco-friendly smartphone case and watch accessories. The device accessories are all sourced sustainably using 100% recycled materials, also all the cases and watch bands are biodegradable.
Market Concentration & Characteristics
The Mobile Phone Accessories Market displays moderate to high market concentration, with a few global leaders holding significant market share and a broad base of regional and local players operating in competitive niches. It is characterized by constant innovation, fast-paced product life cycles, and high consumer sensitivity to trends, design, and technology integration. Leading companies such as Apple Inc., Samsung Electronics Co., Ltd., Belkin International, and Anker Innovations Limited shape product standards and set pricing benchmarks, while emerging brands compete on affordability and specialized features. The market benefits from strong brand loyalty and extensive distribution networks, particularly in Asia Pacific, North America, and Europe. It exhibits a clear segmentation by product type, with mobile cases and chargers commanding the largest shares, and a growing emphasis on wireless, eco-friendly, and smart accessory categories. Intense competition, rapid technological changes, and consumer demand for both quality and affordability define its key characteristics, keeping the market dynamic and highly responsive.Report Coverage
The research report offers an in-depth analysis based on Product Type, Distribution Channel, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook
- Anticipated acceleration in wireless charging and true wireless audio accessory adoption
- Continued expansion of sustainable and recycled-material products
- Growth of smart accessories integrating IoT features and health monitoring
- Rising customization demand for personalized cases and skins
- Increased focus on fast-charging capabilities and high-capacity power banks
- Expansion of accessory ecosystems tied to foldable and 5G devices
- E-commerce dominance powering direct-to-consumer accessory sales
- Emerging regional penetration in Asia Pacific and Latin America markets
- Ongoing consolidation and partnerships among major brands to innovate
- Strengthening of quality and safety standards to counter counterfeit products
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Smartphone Penetration
The increasing adoption of smartphones, especially in emerging markets, is directly fueling demand for accessories such as cases, chargers, earphones, and power banks, as consumers seek to enhance device functionality and longevity.
Technological Advancements and Product Innovation
Continuous innovation in wireless charging, fast-charging technologies, and smart accessories is driving frequent upgrades and repeat purchases, expanding the market for premium and value-added mobile phone accessories.
Growth of E-commerce Channels
The rapid expansion of online retail platforms has made mobile phone accessories more accessible, offering consumers a wide variety of choices, competitive pricing, and convenient delivery, which is accelerating market growth globally.
Shift Toward Wireless and Smart Accessories
Consumer preference is increasingly shifting toward wireless and smart accessories, such as Bluetooth earphones and wireless chargers, driven by the convenience of untethered devices and integration with IoT ecosystems.
Sustainability and Eco-friendly Materials
Growing consumer and regulatory focus on sustainability is encouraging manufacturers to develop accessories using recycled or biodegradable materials, opening new market opportunities and differentiating brands committed to environmental responsibility.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Mobile Phone Accessories Market?
What are the key segments within the Mobile Phone Accessories Market?
What are some challenges faced by the Mobile Phone Accessories Market?
Who are the major players in the Mobile Phone Accessories Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Mobile Cases
- 1.2.2 Chargers
- 1.2.3 Mobile Earphones & Headphones
- 1.2.4 Battery
- 1.2.5 Power Banks
- 1.2.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 79.7 billion → 2032: USD 132.9 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Mobile Phone Accessories Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Mobile Phone Accessories Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Mobile Phone Accessories Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Mobile Phone Accessories Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Mobile Phone Accessories Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Mobile Phone Accessories Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Mobile Phone Accessories Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Mobile Phone Accessories Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 79.7 billion → 2032: USD 132.9 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Mobile Phone Accessories Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Mobile Cases
- 12.3.7.2 Chargers
- 12.3.7.3 Mobile Earphones & Headphones
- 12.3.7.4 Battery
- 12.3.7.5 Power Banks
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 Global Mobile Phone Accessories Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Mobile Phone Accessories Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Mobile Phone Accessories Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Apple Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Samsung Electronics Co., Ltd.
- 17.4 Belkin International, Inc.
- 17.5 Anker Innovations Limited
- 17.6 Logitech International S.A.
- 17.7 Aukey Technology Co., Ltd.
- 17.8 RAVPower
- 17.9 Mophie
- 17.10 OtterBox
- 17.11 Case-Mate
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

