
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Immunohistochemistry Market Size 2024 | USD 3102.96 Million |
| Immunohistochemistry Market, CAGR | 5.42% |
| Immunohistochemistry Market Size 2032 | USD 4731.81 Million |
Market Overview:
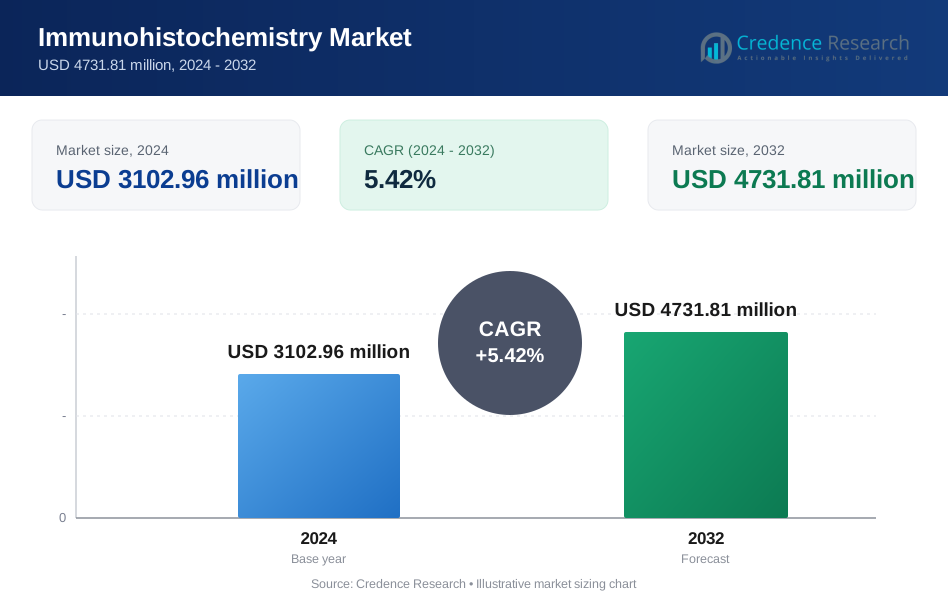
The Immunohistochemistry Market is projected to grow from USD 3102.96 million in 2024 to an estimated USD 4731.81 million by 2032, with a compound annual growth rate (CAGR) of 5.42% from 2024 to 2032.
The growing incidence of cancer and infectious diseases is a key driver of the Immunohistochemistry Market, as IHC plays a crucial role in early diagnosis, prognosis assessment, and therapeutic decision-making. The increasing emphasis on personalized medicine and companion diagnostics is further propelling the demand for advanced IHC solutions. Additionally, technological advancements in automated platforms, multiplex staining, and digital pathology are enhancing the efficiency and accuracy of IHC-based diagnostics. The rising adoption of biomarkers in drug discovery and development, along with stringent regulatory approvals for diagnostic tests, is further shaping market growth. However, high costs associated with IHC reagents and instruments, along with reimbursement challenges in emerging markets, pose certain restraints.
North America dominates the Immunohistochemistry Market, supported by well-established healthcare infrastructure, increased investment in research and development, and the presence of key industry players. The United States leads the region due to high cancer incidence rates and growing applications in drug discovery. Europe follows closely, driven by advancements in molecular diagnostics and government initiatives supporting cancer screening programs. The Asia-Pacific region is witnessing rapid growth, fueled by rising healthcare expenditure, increasing awareness about early disease diagnosis, and the expansion of clinical laboratories. Countries such as China, Japan, and India are experiencing growing demand for IHC techniques due to improving healthcare infrastructure and increased adoption of precision medicine. Meanwhile, Latin America and the Middle East & Africa present emerging opportunities as investments in diagnostic laboratories and research facilities continue to rise.
Market Insights:
- The Immunohistochemistry (IHC) market is projected to grow from USD 3102.96 million in 2024 to USD 4731.81 million by 2032, registering a CAGR of 5.42% during the forecast period.
- The rising prevalence of cancer and chronic diseases is a key driver, as IHC plays a vital role in early diagnosis, prognosis assessment, and therapeutic decision-making in oncology and infectious diseases.
- Technological advancements in automated platforms, multiplex staining, and digital pathology are enhancing diagnostic accuracy and efficiency, supporting the broader adoption of IHC-based solutions.
- The expansion of personalized medicine and companion diagnostics is increasing demand for IHC in targeted therapies, with pharmaceutical companies integrating biomarker analysis into drug development.
- High costs of IHC reagents, instruments, and automated systems, along with regulatory and reimbursement challenges, pose restraints, particularly in emerging markets.
- North America leads the market with a 38% share, driven by strong healthcare infrastructure and R&D investments, while Asia-Pacific is the fastest-growing region, supported by rising healthcare expenditure and growing clinical research.
- Increasing investments in biomarker research, precision medicine, and healthcare infrastructure worldwide will further drive IHC adoption in diagnostics and drug discovery.
Market Drivers:
Rising Prevalence of Chronic Diseases
The increasing burden of chronic diseases, particularly cancer, cardiovascular disorders, and infectious diseases, is a primary driver of the Immunohistochemistry (IHC) Market. IHC plays a crucial role in disease diagnosis, prognosis assessment, and therapeutic decision-making by enabling precise detection of specific antigens in tissue samples. For instacne, according to data published by the World Health Organization (WHO), in 2022, there were an estimated 20 million new cancer cases and 9.7 million deaths. The global surge in cancer incidence has heightened the demand for advanced diagnostic techniques, with IHC serving as a critical tool for tumor classification and biomarker identification. Additionally, the rising geriatric population, which is more susceptible to chronic illnesses, is further contributing to market expansion as healthcare providers seek accurate and efficient diagnostic solutions.
Advancements in Diagnostic Technologies
Continuous advancements in diagnostic technologies are enhancing the efficiency, accuracy, and reliability of IHC-based testing. The integration of automation, multiplex staining, and digital pathology has streamlined laboratory workflows, reducing turnaround times and improving diagnostic precision. Automated IHC platforms have minimized manual errors and increased reproducibility, making them a preferred choice in clinical laboratories and research institutions. For instance, in September 2022, Sakura Finetek launched its newest solution, Tissue-Tek Genie, an advanced staining system designed to provide rapid, high-quality, and standardized results to enhance diagnostic accuracy in histopathology. Furthermore, innovations in antibody development and staining techniques are expanding the application of IHC in identifying novel biomarkers, particularly in oncology and neurodegenerative diseases. These technological improvements are strengthening the adoption of IHC, driving market growth across diagnostic and research applications.
Expansion of Personalized Medicine and Companion Diagnostics
The increasing focus on personalized medicine and companion diagnostics is significantly boosting the demand for IHC solutions. As targeted therapies become more prevalent, IHC plays a critical role in determining patient eligibility for specific treatments by identifying predictive and prognostic biomarkers. Pharmaceutical and biotechnology companies are integrating IHC-based biomarker analysis into drug discovery and clinical trials, ensuring that therapies are tailored to individual patient profiles. For example, in April 2024, Bio-Rad Laboratories, Inc. announced the launch of its first ultrasensitive multiplexed digital PCR assay, the ddPLEX ESR1 Mutation Detection Kit, expanding the company's Droplet Digital PCR (ddPCR) offering for the oncology market. Regulatory agencies are also encouraging the development of companion diagnostics alongside targeted therapies, further reinforcing the market's growth trajectory. The expanding application of IHC in guiding treatment decisions and optimizing therapeutic outcomes is positioning it as an indispensable tool in modern precision medicine.
Growing Investments in Healthcare Infrastructure and Research
Increasing investments in healthcare infrastructure, particularly in emerging economies, are supporting the growth of the IHC market. Governments and private organizations are allocating substantial funds to improve diagnostic capabilities, expand laboratory facilities, and enhance research initiatives. For instance, in the Budget 2025, the Indian government has set aside Rs. 98,311 crore for the development, maintenance and enhancement of the country's healthcare system in the upcoming financial year, up by 9.8 percent from the previous fiscal year. The establishment of oncology research centers, pathology laboratories, and academic institutions is driving the demand for IHC reagents, antibodies, and imaging systems. Additionally, collaborations between diagnostic companies and research organizations are accelerating biomarker discovery and clinical validation, further expanding the scope of IHC applications. As healthcare systems worldwide emphasize early disease detection and precision diagnostics, the demand for IHC solutions is expected to witness sustained growth.
Market Trends:
Increasing Adoption of Artificial Intelligence and Digital Pathology
The integration of artificial intelligence (AI) and digital pathology is transforming the Immunohistochemistry (IHC) market, enabling more efficient and accurate diagnostic workflows. AI-powered image analysis tools are enhancing the interpretation of IHC-stained tissue samples by improving pattern recognition, quantification of biomarkers, and reducing interobserver variability. Digital pathology solutions are facilitating remote consultations, enabling pathologists to access and analyze slides from any location. For instance, the Mayo Clinic and Memorial Sloan Kettering Cancer Center have adopted whole-slide imaging technology, allowing pathologists to review IHC slides digitally from any location. These advancements are particularly beneficial in regions with limited access to expert pathologists, supporting the expansion of IHC-based diagnostics in both developed and emerging markets.
Rising Demand for Multiplex Immunohistochemistry
The growing emphasis on multiplex immunohistochemistry (mIHC) is driving innovation in the market, particularly in oncology and immunology research. Unlike traditional single-marker staining techniques, mIHC allows the simultaneous detection of multiple biomarkers in a single tissue sample, providing comprehensive insights into complex disease mechanisms. This approach is gaining traction in cancer research and drug development, where understanding the tumor microenvironment and immune response is critical. For example, Remark et al. developed the multiplexed immunohistochemical consecutive staining on a single slide (MICSSS) technique, which utilizes iterative cycles of tagging, image scanning, and destaining of a chromogenic substrate on a single slide. Pharmaceutical and biotechnology companies are increasingly adopting multiplexing techniques to identify potential therapeutic targets, optimize treatment strategies, and enhance precision medicine applications.
Expansion of Companion Diagnostics in Targeted Therapies
The increasing use of IHC in companion diagnostics is a significant trend shaping the market. Regulatory authorities, including the FDA and EMA, are emphasizing the co-development of diagnostic tests alongside targeted therapies to improve treatment outcomes. IHC-based companion diagnostics are being widely used to identify patient subgroups that are most likely to benefit from specific drugs, particularly in oncology. For instance, the first companion diagnostic to be approved using the FDA's guidance on group claims allowed a single test to be used for a broad group of approved therapies for NSCLC, enabling the treatment of patients with exon19 deletions and L858R mutated EGFR without requiring a specific clinical trial for each test and therapeutic combination. The approval of IHC assays for targeted therapies in breast, lung, and colorectal cancer has accelerated their clinical adoption. As pharmaceutical companies continue to develop personalized treatment options, the demand for companion diagnostic tests using IHC is expected to rise.
Growing Investments in Biomarker Research and Drug Development
The expansion of biomarker research and drug development is contributing to the increasing utilization of IHC in preclinical and clinical studies. Research institutions and pharmaceutical companies are investing heavily in biomarker discovery programs to develop novel diagnostic and therapeutic solutions. IHC is being used extensively in translational research to validate disease-specific markers and assess drug efficacy. For instance, AstraZeneca and Daiichi Sankyo are collaborating to develop and sell Enhertu, an antibody-drug conjugate (ADC) that targets HER2-positive cancers. This collaboration is an example of growing investments in biomarker research and drug development. The rise of immunotherapy and the need for predictive biomarkers in cancer treatment are further driving IHC applications. With increasing collaborations between industry players and academic research centers, the market is expected to witness continuous advancements in biomarker identification and validation, supporting the development of next-generation diagnostic and therapeutic approaches.
Market Challenges Analysis:
High Costs Associated with Immunohistochemistry Procedures
The high costs of IHC reagents, antibodies, and automated staining systems present a significant challenge to market expansion. Laboratories and healthcare facilities must invest in expensive instruments and consumables, increasing the financial burden, particularly in resource-limited settings. Additionally, the cost of maintaining and upgrading IHC systems further adds to operational expenses. Small and mid-sized diagnostic laboratories often struggle to adopt advanced IHC techniques due to budget constraints, limiting market penetration in developing regions.
Stringent Regulatory Approvals and Compliance Requirements
The complex regulatory landscape for IHC products and diagnostic assays poses a challenge for market players. Regulatory bodies such as the FDA, EMA, and other health authorities require extensive clinical validation and approvals before IHC-based tests can be commercialized. Compliance with stringent quality standards adds to the time and cost of product development, delaying market entry for new IHC solutions. Additionally, variations in regulatory frameworks across different regions create barriers for manufacturers seeking global expansion, increasing the complexity of market access.
Shortage of Skilled Pathologists and Laboratory Professionals
A lack of trained pathologists and laboratory professionals proficient in IHC analysis is restraining market growth, particularly in developing countries. Accurate interpretation of IHC-stained tissue samples requires specialized expertise, and the shortage of skilled professionals leads to diagnostic errors and delayed test results. The increasing workload on existing pathologists further impacts the efficiency of diagnostic workflows, highlighting the need for advanced training programs and automation in pathology laboratories.
Challenges in Reimbursement Policies and Insurance Coverage Uncertainty in reimbursement policies and insurance coverage for IHC-based diagnostic tests is another challenge affecting market growth. In many regions, healthcare providers and patients face difficulties in obtaining reimbursement for IHC procedures, limiting accessibility to advanced diagnostic solutions. Inconsistent insurance policies and variations in reimbursement rates across different healthcare systems further add to the financial strain on laboratories and diagnostic centers, impacting the widespread adoption of IHC technologies.
Market Opportunities:
The expansion of precision medicine and biomarker-driven therapies presents a significant growth opportunity for the Immunohistochemistry (IHC) market. As the demand for targeted therapies increases, IHC is becoming an essential tool in identifying predictive and prognostic biomarkers across various disease areas, particularly in oncology. Pharmaceutical and biotechnology companies are increasingly incorporating IHC in drug discovery, clinical trials, and companion diagnostics, driving the need for innovative reagents and automated platforms. The growing integration of artificial intelligence (AI) and digital pathology in IHC workflows further enhances efficiency and accuracy, enabling broader adoption across diagnostic laboratories and research institutions. Investments in AI-based image analysis solutions are expected to streamline pathologist workflows, reduce diagnostic errors, and expand access to IHC testing in remote and underserved regions.
Emerging economies present substantial market expansion opportunities due to increasing healthcare investments, improved diagnostic infrastructure, and rising awareness of early disease detection. Countries in Asia-Pacific, Latin America, and the Middle East & Africa are witnessing a surge in the adoption of advanced diagnostic techniques, driven by government initiatives and private-sector investments in healthcare modernization. The growing number of pathology laboratories, research institutions, and oncology centers in these regions is creating a favorable environment for market growth. Additionally, the development of cost-effective and multiplex IHC solutions tailored to regional healthcare needs offers new avenues for manufacturers to expand their market presence and address the rising demand for affordable, high-quality diagnostic solutions.
Market Segmentation Analysis:
The Immunohistochemistry (IHC) market is segmented based on product, application, and end-use, with each segment contributing to market growth through technological advancements and increasing adoption in diagnostic and research applications.
By Product, antibodies hold a significant market share, with primary antibodies being widely used for detecting specific biomarkers, while secondary antibodies enhance signal amplification. The equipment segment is expanding due to the rising demand for slide staining systems, tissue microarrays, tissue processing systems, and slide scanners, which improve diagnostic accuracy and laboratory efficiency. Reagents, including histological stains, blocking sera, chromogenic substrates, fixation reagents, stabilizers, organic solvents, proteolytic enzymes, and diluents, play a crucial role in IHC assays. The kits segment is also gaining traction, driven by increasing demand for standardized and ready-to-use solutions in clinical and research laboratories.
By Application, the diagnostics segment dominates the market, with cancer diagnostics being the primary driver due to the critical role of IHC in tumor classification and biomarker detection. Infectious diseases, cardiovascular diseases, autoimmune diseases, diabetes mellitus, and nephrological diseases are also key areas where IHC is increasingly utilized for early diagnosis and treatment planning. The research segment is witnessing steady growth, fueled by expanding biomarker discovery programs and pharmaceutical research initiatives.
By End-Use, hospitals and diagnostic laboratories account for the largest share, driven by increasing patient demand for accurate and timely disease diagnosis. Research institutes are also contributing to market growth by utilizing IHC for drug development and biomarker validation. The others category, including biotechnology companies and contract research organizations, is expanding as IHC applications diversify across the healthcare and life sciences sectors.
Segmentation:
By Product
- Antibodies
- Primary Antibodies
- Secondary Antibodies
- Equipment
- Slide Staining System
- Tissue Microarrays
- Tissue Processing Systems
- Slide Scanners
- Others
- Reagents
- Histological Stains
- Blocking Sera and Reagents
- Chromogenic Substrates
- Fixation Reagents
- Stabilizers
- Organic Solvents
- Proteolytic Enzymes
- Diluents
- Kits
By Application
- Diagnostics
- Cancer
- Infectious Diseases
- Cardiovascular Diseases
- Autoimmune Diseases
- Diabetes Mellitus
- Nephrological Diseases
- Research
By End-Use
- Hospitals & Diagnostic Laboratories
- Research Institutes
- Others
Regional Analysis:
North America
North America holds the largest market share, accounting for approximately 38% of the global Immunohistochemistry (IHC) market. The region's dominance is driven by well-established healthcare infrastructure, advanced research facilities, and high healthcare spending. The United States leads the market due to the rising prevalence of cancer and chronic diseases, coupled with strong government initiatives supporting cancer diagnostics and biomarker research. The presence of major pharmaceutical and biotechnology companies investing in personalized medicine and companion diagnostics further strengthens market growth. Additionally, the adoption of digital pathology, AI-driven diagnostics, and automated IHC platforms continues to accelerate the demand for IHC solutions across hospitals, diagnostic laboratories, and research institutions.
Europe
Europe holds a significant market share of approximately 28%, supported by a robust regulatory framework, increasing adoption of molecular diagnostics, and government funding for cancer research. Countries such as Germany, the United Kingdom, and France are at the forefront of IHC advancements, benefiting from well-established pathology laboratories and leading academic research institutions. The growing emphasis on early disease detection and precision diagnostics is fueling the demand for IHC-based biomarker testing. Additionally, the rising prevalence of neurodegenerative diseases is driving the use of IHC in neurology research. Regulatory bodies such as the EMA are playing a crucial role in ensuring the quality and effectiveness of IHC-based diagnostic assays, further boosting market growth.
Asia-Pacific
The Asia-Pacific region is experiencing the fastest market growth, with a market share of approximately 25%, driven by rapid healthcare infrastructure development, increasing prevalence of cancer, and rising healthcare investments. Countries such as China, Japan, and India are emerging as key markets due to government initiatives promoting early disease screening, improved diagnostic capabilities, and research collaborations. The expanding pharmaceutical and biotechnology sectors in the region are also driving the adoption of IHC in clinical trials and biomarker research. Additionally, the growing number of pathology laboratories and academic research institutions is fueling demand for IHC reagents and automated staining systems. The increasing availability of cost-effective IHC solutions tailored to regional needs is further supporting market expansion.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa together account for a smaller but growing market share of approximately 9%, with increasing opportunities in diagnostic laboratory expansion and healthcare modernization. Countries such as Brazil and Mexico are witnessing growth in oncology diagnostics and biomarker-based research, supported by rising government and private-sector investments. In the Middle East & Africa, increasing awareness of early disease detection, improving healthcare infrastructure, and collaborations with international diagnostic companies are driving market expansion. However, challenges such as limited access to advanced diagnostic technologies and reimbursement constraints continue to impact market penetration in these regions.
Key Player Analysis:
- Thermo Fisher Scientific Inc.
- Hoffmann-La Roche Ltd.
- Merck KGaA
- Danaher Corporation
- PerkinElmer, Inc.
- Bio-Rad Laboratories, Inc.
- Cell Signaling Technology, Inc.
- Bio SB
- Agilent Technologies, Inc.
- Abcam plc.
Competitive Analysis:
The Immunohistochemistry (IHC) market is highly competitive, with key players focusing on technological advancements, strategic collaborations, and product innovations to strengthen their market position. Leading companies, including F. Hoffmann-La Roche Ltd, Agilent Technologies, Danaher Corporation, Thermo Fisher Scientific, and Merck KGaA, dominate the market by offering advanced IHC solutions, including automated staining systems, high-specificity antibodies, and digital pathology integration. Companies are investing in research and development to enhance the accuracy and efficiency of IHC assays, particularly for cancer diagnostics and biomarker discovery. Strategic partnerships between pharmaceutical firms and diagnostic companies are driving the development of companion diagnostics, further expanding the application of IHC in precision medicine. For instance, in October 2024, Arbele announced a strategic collaboration with BioAI Health to develop a prototype of an immunohistochemistry (IHC)-based quantification algorithm, leveraging AI to advance targeted immunotherapeutics of bispecific T-cell engagers (TCEs) and antibody-drug conjugates (ADCs). Additionally, emerging players are focusing on cost-effective and multiplex IHC solutions to cater to growing demand in developing regions. As competition intensifies, innovation, regulatory approvals, and geographic expansion remain critical factors for sustained market leadership.
Recent Developments:
- In February 2025, Thermo Fisher Scientific announced its agreement to acquire Solventum's Purification & Filtration business for approximately $4.1 billion. This acquisition is highly complementary to Thermo Fisher's bioproduction business and will strengthen its offering in the high-growth bioprocessing market.
- In March 2023, Aptamer Group plc [Company] launched Optimer-Fc, a new reagent solution designed for use in automated immunohistochemistry (IHC). This innovative product aims to advance research, diagnostics, and forensics by offering increased accuracy and selectivity in detecting disease biomarkers.
- In September 2023, Ibex Medical Analytics [Company] introduced Galen Breast HER2, an AI-powered solution that assists pathologists in providing accurate and reproducible HER2 scores for breast cancer patients.
- In April 2024, Bio-Rad Laboratories [Company] launched its first ultrasensitive multiplexed digital PCR assay, the ddPlex ESR1 Mutation Detection Kit. This research-use assay enables simultaneous detection, discrimination, and absolute quantification of seven known relevant ESR1 mutations in a single well, with analytical sensitivity down to 0.01 percent variant allele fraction.
Market Concentration & Characteristics:
The Immunohistochemistry (IHC) market is moderately concentrated, with a few dominant players controlling a significant share of the industry. Leading companies such as F. Hoffmann-La Roche Ltd, Agilent Technologies, Danaher Corporation, Thermo Fisher Scientific, and Merck KGaA have established strong market positions through extensive product portfolios, technological advancements, and global distribution networks. These companies invest heavily in research and development to introduce innovative reagents, automated staining systems, and digital pathology solutions. The market is characterized by rapid technological advancements, increasing adoption of automation, and the growing integration of artificial intelligence (AI) in pathology. The demand for highly specific and sensitive antibodies, multiplex IHC solutions, and companion diagnostics is rising, particularly in oncology and neuroscience research. Additionally, emerging players are introducing cost-effective IHC solutions to penetrate developing markets. As competition intensifies, companies are focusing on strategic partnerships, acquisitions, and regulatory approvals to expand their global footprint.
Report Coverage:
The research report offers an in-depth analysis based on product, application, and end-use, It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Immunohistochemistry (IHC) market is expected to witness steady growth, driven by increasing applications in cancer diagnostics, neurology, and infectious disease research.
- Advancements in automated IHC platforms and AI-driven image analysis will enhance diagnostic accuracy and workflow efficiency in pathology laboratories.
- The rising adoption of multiplex IHC techniques will enable simultaneous detection of multiple biomarkers, expanding its role in personalized medicine and drug discovery.
- Increasing demand for companion diagnostics will drive collaborations between pharmaceutical companies and diagnostic firms to develop targeted therapies.
- Emerging economies in Asia-Pacific, Latin America, and the Middle East & Africa will experience strong market growth due to expanding healthcare infrastructure and improved access to diagnostic technologies.
- Continuous innovations in reagents, antibodies, and staining techniques will enhance the specificity and sensitivity of IHC-based diagnostics.
- The integration of digital pathology and telemedicine will improve remote access to IHC diagnostics, particularly in underserved regions.
- Stringent regulatory requirements for diagnostic assays and biomarker validation will shape market dynamics, influencing product approvals and commercialization strategies.
- The development of cost-effective IHC solutions will increase adoption rates in mid-sized laboratories and developing healthcare markets.
- Strategic mergers, acquisitions, and partnerships will remain key growth strategies for market players seeking to expand their global presence.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Diseases
The increasing global incidence of cancer, cardiovascular, and infectious diseases is driving demand for immunohistochemistry, as IHC is essential for accurate diagnosis, prognosis, and therapeutic decision-making, especially in oncology.
Advancements in Diagnostic Technologies
Continuous innovation in automated platforms, multiplex staining, and digital pathology is improving the efficiency, reproducibility, and accuracy of IHC testing, making it more accessible and reliable for clinical and research applications.
Expansion of Personalized Medicine and Companion Diagnostics
The shift toward personalized medicine and targeted therapies is boosting the need for IHC-based biomarker analysis, as pharmaceutical and biotech companies integrate IHC into drug discovery, clinical trials, and companion diagnostics to optimize patient outcomes.
Growing Investments in Healthcare Infrastructure and Research
Increased funding from governments and private organizations for healthcare modernization, laboratory expansion, and biomarker research - especially in emerging economies - is expanding the adoption of IHC solutions in diagnostics and drug development.
Integration of Artificial Intelligence and Digital Pathology
The adoption of AI-powered image analysis and digital pathology platforms is enhancing the interpretation of IHC results, reducing diagnostic errors, and enabling remote consultations, which supports broader and more efficient use of IHC in both developed and developing regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Immunohistochemistry Market?
What factors are driving the growth of the Immunohistochemistry Market?
What are some challenges faced by the Immunohistochemistry Market?
Who are the major players in the Immunohistochemistry Market?
Which region leads the Immunohistochemistry Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Hospitals & Diagnostic Laboratories
- 1.2.2 Research Institutes
- 1.2.3 Others (Biotechnology Companies, Contract Research Organizations)
- 1.3 By Product
- 1.3.1 Antibodies (Primary, Secondary)
- 1.3.2 Equipment (Slide Staining System, Tissue Microarrays, Tissue Processing Systems, Slide Scanners, Others)
- 1.3.3 Reagents (Histological Stains, Blocking Sera and Reagents, Chromogenic Substrates, Fixation Reagents, Stabilizers, Organic Solvents, Proteolytic Enzymes, Diluents)
- 1.3.4 Kits
- 1.4 By Application
- 1.4.1 Diagnostics (Cancer, Infectious Diseases, Cardiovascular Diseases, Autoimmune Diseases, Diabetes Mellitus, Nephrological Diseases)
- 1.4.2 Research
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3102.96 million → 2032: USD 4731.81 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Immunohistochemistry Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Immunohistochemistry Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Immunohistochemistry Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Immunohistochemistry Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Immunohistochemistry Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Immunohistochemistry Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Immunohistochemistry Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Immunohistochemistry Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3102.96 million → 2032: USD 4731.81 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Immunohistochemistry Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals & Diagnostic Laboratories
- 12.3.7.2 Research Institutes
- 12.3.7.3 Others (Biotechnology Companies, Contract Research Organizations)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Antibodies (Primary, Secondary)
- 12.4.7.2 Equipment (Slide Staining System, Tissue Microarrays, Tissue Processing Systems, Slide Scanners, Others)
- 12.4.7.3 Reagents (Histological Stains, Blocking Sera and Reagents, Chromogenic Substrates, Fixation Reagents, Stabilizers, Organic Solvents, Proteolytic Enzymes, Diluents)
- 12.4.7.4 Kits
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Diagnostics (Cancer, Infectious Diseases, Cardiovascular Diseases, Autoimmune Diseases, Diabetes Mellitus, Nephrological Diseases)
- 12.5.7.2 Research
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Immunohistochemistry End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Immunohistochemistry Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Immunohistochemistry Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Immunohistochemistry Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thermo Fisher Scientific Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Hoffmann-La Roche Ltd.
- 18.4 Merck KGaA
- 18.5 Danaher Corporation
- 18.6 PerkinElmer, Inc.
- 18.7 Bio-Rad Laboratories, Inc.
- 18.8 Cell Signaling Technology, Inc.
- 18.9 Bio SB
- 18.10 Agilent Technologies, Inc.
- 18.11 Abcam plc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

