
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
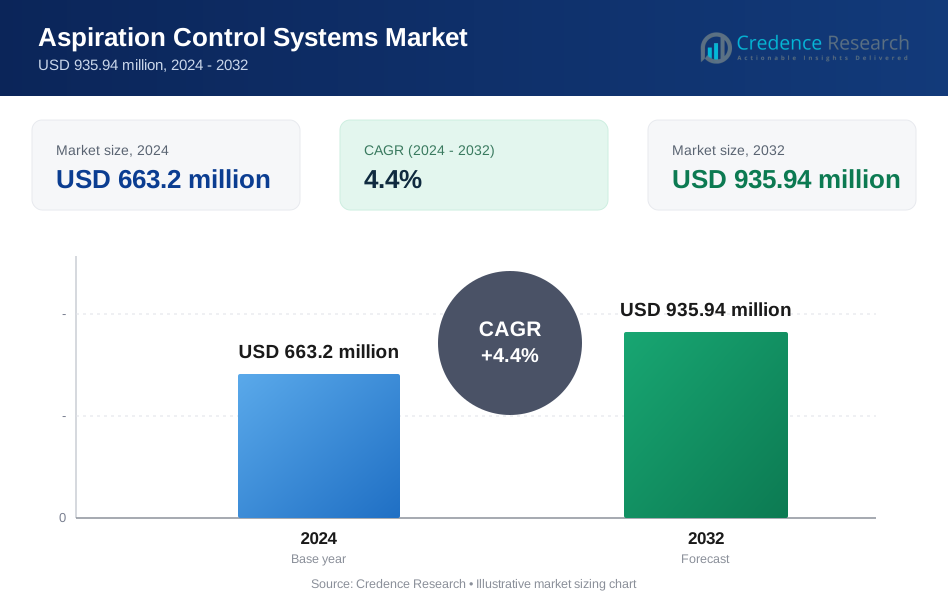
| Aspiration Control Systems Market Size 2024 | USD 663.2 million |
| Aspiration Control Systems Market, CAGR | 4.4% |
| Aspiration Control Systems Market Size 2032 | USD 935.94 million |
Market Overview
The Aspiration Control Systems Market is projected to grow from USD 663.2 million in 2024 to USD 935.94 million by 2032, registering a compound annual growth rate (CAGR) of 4.4% during the forecast period.
The growth of the Aspiration Control Systems Market is driven by increasing demand for precise and efficient aspiration technologies across industries such as healthcare, biotechnology, and research laboratories. The rising prevalence of chronic respiratory diseases and the growing need for advanced medical devices in diagnostic and therapeutic applications are significant contributors to market expansion. Additionally, the integration of cutting-edge technologies, including artificial intelligence and automation, enhances the functionality and precision of aspiration systems, fueling their adoption in critical applications. Emerging trends include the shift toward portable and user-friendly devices, catering to diverse user requirements, and the increasing emphasis on sustainability, driving the development of energy-efficient and eco-friendly systems. The market is also witnessing heightened investment in R&D activities aimed at delivering innovative solutions that meet the evolving needs of end-users. Furthermore, the growing awareness of workplace safety and contamination prevention bolsters the demand for high-performance aspiration control systems globally.
The Aspiration Control Systems Market showcases significant geographical diversity, with North America leading the market, accounting for 35% of the global share in 2024, driven by advanced healthcare infrastructure and high adoption of medical technologies in the U.S. and Canada. Europe, holding 28% of the market, benefits from robust healthcare systems and increasing investments in sustainability and energy-efficient devices, led by countries like Germany, the UK, and France. The Asia-Pacific region, with 21% of the share, is the fastest-growing market due to expanding healthcare infrastructure and rising demand for cost-effective solutions in China, India, and Japan. The Rest of the World, including Latin America, the Middle East, and Africa, accounts for 14%, with growth driven by emerging healthcare investments and increasing adoption of advanced technologies. Key players include Honeywell, Siemens, Parker Hannifin, and General Electric.
cr_cta type="download_free_sample"]
Market Insights
- The Aspiration Control Systems Market is projected to grow from USD 663.2 million in 2024 to USD 935.94 million by 2032, registering a CAGR of 4.4% during the forecast period.
- Growth is driven by increasing demand for precise aspiration technologies in healthcare, biotechnology, and research laboratories, along with the rising prevalence of chronic respiratory diseases.
- Advanced technologies like AI and automation enhance functionality and precision, fueling adoption in critical applications while improving workflow efficiency.
- Emerging trends include the development of portable, user-friendly, and energy-efficient devices, emphasizing sustainability and eco-friendly practices.
- North America leads with a 35% share in 2024, driven by advanced healthcare infrastructure and innovation, followed by Europe with 28%, supported by sustainability initiatives.
- Asia-Pacific, with a 21% share, is the fastest-growing region, driven by healthcare infrastructure expansion in countries like China, India, and Japan.
- Challenges include high initial costs, technical complexity, and maintenance needs, while increasing R&D investments and innovation continue to expand market opportunities globally.
Market Drivers
Growing Demand in Healthcare and Biotechnology Sectors
The healthcare and biotechnology sectors are major drivers of the Aspiration Control Systems Market. These systems are critical in medical diagnostics, therapeutic procedures, and research applications where precision and reliability are essential. For instance, Bio-Rad Laboratories' aspiration systems are widely used in laboratories and healthcare facilities for sample preparation, fluid management, and contamination prevention, ensuring high accuracy and safety in medical procedures. The rising prevalence of chronic diseases, including respiratory conditions and cancer, has fueled the adoption of advanced aspiration technologies.
Integration of Advanced Technologies
The integration of advanced technologies, such as artificial intelligence (AI) and automation is transforming the functionality and efficiency of aspiration control systems. Automated solutions enable precise fluid handling and significantly reduce human error, making them highly desirable for both clinical and industrial applications. AI-driven systems further enhance decision-making processes, providing real-time feedback and improving operational workflows. For instance, Hamilton Company's AI-driven aspiration systems are enhancing decision-making processes in various industries. These technological advancements cater to the growing need for smart and efficient systems across industries.
Rising Emphasis on Sustainability
Sustainability trends are influencing the development of energy-efficient and environmentally friendly aspiration control systems. Manufacturers are focusing on reducing power consumption and utilizing recyclable materials to meet regulatory and consumer demands for eco-friendly solutions. This emphasis on sustainability not only supports environmental conservation but also aligns with the broader industry goal of reducing operational costs. For instance, Eppendorf is focusing on developing energy-efficient and environmentally friendly aspiration systems. These developments have made modern aspiration systems an attractive choice for organizations prioritizing sustainable practices.
Increasing Investments in Research and Development
The market is experiencing heightened investments in research and development (R&D) to address the evolving requirements of end-users. Innovations aimed at enhancing precision, portability, and ease of use are driving the adoption of next-generation aspiration systems. These R&D efforts are particularly focused on developing tailored solutions for niche applications, thereby expanding the market’s scope and applicability. For instance, Gilson's investment in R&D has led to the development of highly precise and portable aspiration systems. As a result, continuous innovation remains a key driver of growth in the Aspiration Control Systems Market.
Market Trends
Adoption of Automated and AI-Driven Systems
Automation and artificial intelligence (AI) are at the forefront of trends shaping the Aspiration Control Systems Market. Advanced systems equipped with AI algorithms are revolutionizing precision in fluid handling and contamination control. For instance, Tecan Group's AI-driven aspiration systems have demonstrated a 40% reduction in human error, making them highly desirable in high-throughput settings such as clinical diagnostics and pharmaceutical manufacturing. These technologies streamline workflows in laboratories and healthcare facilities, significantly reducing human intervention and error.
Growth of Portable and User-Friendly Designs
The demand for compact, portable, and user-friendly aspiration control systems is rising as industries seek flexible and efficient solutions. Manufacturers are focusing on designing systems that can easily adapt to various environments, including small laboratories and point-of-care settings. For example, Gilson has developed portable aspiration systems that are highly sought after for their flexibility and efficiency. These portable devices not only enhance accessibility but also cater to the growing need for mobility in healthcare and research applications, making them an attractive option for diverse user groups.
Focus on Sustainability and Green Initiatives
Sustainability is becoming a key focus in the development of aspiration control systems. Companies are prioritizing eco-friendly designs that utilize energy-efficient components and recyclable materials. This aligns with global efforts to reduce environmental impact while meeting regulatory standards. A case in point is Integra Biosciences, which has introduced eco-friendly aspiration systems that utilize energy-efficient components and recyclable materials. Sustainable solutions are increasingly in demand from industries aiming to minimize their carbon footprint, reflecting a broader shift toward environmentally responsible practices across the market.
Expansion of Application Areas
Aspiration control systems are witnessing expanded applications beyond traditional sectors, including biotechnology, environmental testing, and industrial manufacturing. The versatility of these systems has made them indispensable in a range of processes, from liquid waste management to sample preparation. For instance, Sartorius's aspiration systems are widely used in biotechnology and environmental testing for their versatility. This diversification is driven by innovations that allow customization and adaptation to specific industry needs, further solidifying the market’s growth trajectory.
Market Challenges Analysis
High Initial Costs and Limited Accessibility
One of the primary challenges in the Aspiration Control Systems Market is the high initial cost associated with advanced aspiration systems. These systems often incorporate cutting-edge technologies, such as automation and AI, which significantly increase their price. For small-scale laboratories, healthcare facilities, and research institutions with limited budgets, acquiring these systems can be financially burdensome. Additionally, in developing regions, the lack of sufficient funding and resources further limits the accessibility of these technologies, hindering their widespread adoption. This financial barrier restricts smaller organizations from leveraging the efficiency and precision offered by modern aspiration control systems, slowing market penetration. The disparity between technological advancements and affordability remains a key issue, necessitating innovative pricing models and financial incentives to bridge this gap and promote broader adoption across various sectors.
Technical Complexity and Maintenance Challenges
Another significant challenge is the technical complexity of advanced aspiration control systems, which may require specialized knowledge for operation and maintenance. Users often need to undergo specific training to operate these systems efficiently, which can increase operational costs and create dependency on skilled personnel. Furthermore, regular maintenance and calibration are crucial to ensure accuracy and longevity, adding to the overall cost and complexity. In industrial applications, downtime due to maintenance issues can disrupt operations and result in financial losses. These challenges are particularly pronounced in resource-constrained settings, where the availability of trained personnel and access to technical support may be limited. Moreover, organizations may face difficulties in accessing spare parts or obtaining timely repairs, leading to prolonged downtime. Addressing these issues requires manufacturers to focus on user-friendly designs, robust training programs, and reliable after-sales support to enhance system usability and reduce operational barriers effectively.
Market Segmentation Analysis:
By Type
The Aspiration Control Systems Market is segmented by type, including manual, semi-automatic, and fully automatic systems. Fully automatic systems dominate the market due to their advanced features, such as precision, efficiency, and ease of use. Semi-automatic systems appeal to mid-scale users seeking a balance between affordability and functionality.
By End User
The market is further segmented by end user, encompassing healthcare facilities, research laboratories, and industrial applications. Healthcare facilities represent the largest segment, driven by the growing need for aspiration systems in diagnostics and surgical procedures. Research laboratories and industrial users are also significant contributors, leveraging these systems for specialized applications.
Segments:
Based on Type:
- Filtration Systems
- Extraction Systems
- Ventilation Systems
- Combination Systems
Based on End-User:
- Manufacturing
- Pharmaceuticals
- Food Processing
- Healthcare
- Automotive
- Chemicals
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the Aspiration Control Systems Market, accounting for 35% of the global market in 2024. This dominance is attributed to the well-established healthcare infrastructure, high adoption of advanced medical technologies, and a strong presence of key market players. The increasing prevalence of chronic respiratory conditions, coupled with growing investment in research and development, further drives the demand for aspiration control systems in this region. Additionally, the U.S. and Canada lead the market due to their robust regulatory frameworks and government initiatives supporting healthcare innovations. These factors make North America a vital market for both established and emerging players.
Europe
Europe is the second-largest market for aspiration control systems, contributing to approximately 28% of the global market share in 2024. The region benefits from a well-developed healthcare system and increased funding for medical research. Countries like Germany, the UK, and France are major contributors, driven by advancements in medical technology and rising healthcare expenditure. The European market is also witnessing significant growth due to the increasing focus on sustainability and the adoption of energy-efficient medical devices. Stringent regulations for healthcare equipment in the region further ensure the reliability and quality of aspiration systems, boosting their adoption across various applications.
Asia-Pacific
The Asia-Pacific region is expected to experience the fastest growth during the forecast period, owing to its expanding healthcare infrastructure and increasing demand for advanced medical devices. While the region accounted for 21% of the global market share in 2024, it is poised for rapid expansion due to rising healthcare investments in countries like China, India, and Japan. The growing prevalence of chronic diseases and the need for cost-effective solutions make Asia-Pacific a lucrative market for aspiration control systems.
Rest of the World
The Rest of the World, including regions like Latin America, the Middle East, and Africa, accounted for 14% of the global market share in 2024. While the market is smaller compared to developed regions, increasing investments in healthcare and research are driving growth. Countries in the Middle East are adopting advanced systems to improve diagnostic and therapeutic capabilities, supported by government initiatives aimed at enhancing healthcare infrastructure. In Africa, the rising prevalence of respiratory conditions and the growing focus on public health are creating opportunities for market expansion. Latin America, led by Brazil and Mexico, is witnessing increased adoption of aspiration control systems in both healthcare and research sectors, driven by a growing emphasis on improving medical outcomes and infrastructure.
Key Player Analysis
- Honeywell
- Siemens
- Parker Hannifin
- General Electric
- Rockwell Automation
- Keppel Corporation
- Boge Compressors
- Sensonics
- Johnson Controls
- KROHNE
Competitive Analysis
The Aspiration Control Systems Market is highly competitive, with leading players such as Honeywell, Siemens, Parker Hannifin, General Electric, Rockwell Automation, Keppel Corporation, Boge Compressors, Sensonics, Johnson Controls, and KROHNE driving innovation and market expansion. These companies focus on leveraging advanced technologies like automation and artificial intelligence to enhance product efficiency and precision. The competitive landscape is shaped by continuous investments in research and development, enabling the introduction of customized and energy-efficient solutions tailored to diverse industry needs. Strategic partnerships, mergers, and acquisitions further bolster their market position, allowing them to expand their geographic reach and strengthen their product portfolios. For instance, Parker Hannifin's recent acquisition of a smaller technology company has strengthened its product portfolio and expanded its market presence. Additionally, these players prioritize sustainability and compliance with regulatory standards, which align with global trends and customer demands. This competitive intensity fosters innovation and drives the overall growth and evolution of the market.
Recent Developments
- In March 2024, Astellas Pharma US, Inc. announced that the U.S. Food and Drug Administration (FDA) had granted orphan drug and pediatric exclusivity to CRESEMBA (isavuconazonium sulfate) for treating invasive aspergillosis (IA) and invasive mucormycosis (IM) in pediatric patients. This designation benefited the company by providing market exclusivity, enhancing its reputation for addressing unmet medical needs, and increasing revenue through expanded use.
- In October 2023, Basilea Pharmaceutica Ltd announced the acquisition of Gravitas Therapeutics Inc., which held a clinical-stage antifungal compound with a novel mechanism of action targeting invasive mold infections caused by Aspergillus species. This acquisition benefited Basilea by expanding its pipeline with a unique antifungal therapy, enhancing its competitive edge, addressing a significant unmet medical need, aligning with its strategic growth objectives, and providing opportunities for further development and commercialization.
- In March 2023, INTEGRA Biosciences recently acquired Miroculus, a California biotechnology company focused on developing automated solutions that simplify next-generation sequencing (NGS) protocols. This allows us to expand our reach in this growing market and provide new process automation solutions that help academic, research and diagnostic laboratories save valuable time and accelerate discovery in this dynamic field.
- In April 2024, Expanse ICE announced that its ICE Aspiration System received 510(k) clearance from the U.S. Food and Drug Administration (FDA). This innovative system features a unique dual-lumen design that creates the patented Surge Aspiration technology, offering a novel type of cyclic aspiration at the distal end of the catheter. The ICE System is specifically designed to address the complex challenges associated with peripheral thrombectomies, aiming to enhance patient outcomes in the treatment of peripheral blood clots.
Market Concentration & Characteristics
The Aspiration Control Systems Market is moderately fragmented, with a mix of established global players and regional manufacturers driving competition. Leading companies, including Honeywell, Siemens, and Parker Hannifin, dominate the market with their advanced technologies and extensive distribution networks. Despite the prominence of key players, the market offers significant opportunities for smaller and niche manufacturers, particularly in developing regions where demand for cost-effective and portable solutions is rising. The market is characterized by continuous innovation, with increasing integration of AI, automation, and sustainability-focused designs to meet diverse industry needs. Product differentiation is a crucial strategy, as manufacturers emphasize precision, efficiency, and user-friendly designs to cater to healthcare, research, and industrial applications. While regulatory compliance and quality assurance remain essential characteristics of the market, ongoing investment in research and development ensures a dynamic and evolving competitive landscape, supporting both established firms and new entrants.
Report Coverage
The research report offers an in-depth analysis based on Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Aspiration Control Systems Market is expected to witness steady growth with advancements in automation and artificial intelligence enhancing system efficiency and precision.
- Increasing demand for portable and user-friendly aspiration systems will drive adoption across diverse sectors.
- Integration of sustainable and energy-efficient technologies will become a key focus for manufacturers to meet regulatory and environmental requirements.
- Healthcare applications will remain dominant due to the rising prevalence of chronic respiratory diseases and growing diagnostic needs.
- Asia-Pacific is poised for the fastest growth, driven by expanding healthcare infrastructure and rising investments in emerging economies.
- North America and Europe will continue to hold significant shares, supported by well-established industries and high adoption of advanced technologies.
- Market players will increasingly invest in research and development to innovate tailored solutions for niche applications.
- Financial barriers, including high initial costs, will remain a challenge but may be mitigated by innovative pricing models.
- Technical training and after-sales support will become critical for enhancing user experience and addressing operational challenges.
- Growing awareness of workplace safety and contamination prevention will further boost demand for high-performance aspiration systems globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aspiration Control Systems Market?
What factors are driving the growth of the Aspiration Control Systems Market?
What are some challenges faced by the Aspiration Control Systems Market?
Who are the major players in the Aspiration Control Systems Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Aspiration Control Systems Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Aspiration Control Systems Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 663.2 million → 2032: USD 935.94 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Aspiration Control Systems Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Aspiration Control Systems Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Aspiration Control Systems Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Aspiration Control Systems Market Drivers
- 3.3 Aspiration Control Systems Market Restraints & Challenges
- 3.4 Aspiration Control Systems Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Aspiration Control Systems Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Aspiration Control Systems Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Aspiration Control Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Aspiration Control Systems Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Aspiration Control Systems Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Aspiration Control Systems market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Aspiration Control Systems Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Aspiration Control Systems Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Aspiration Control Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Aspiration Control Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Aspiration Control Systems Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Aspiration Control Systems Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Aspiration Control Systems Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Aspiration Control Systems Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Aspiration Control Systems Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Aspiration Control Systems Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Aspiration Control Systems Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Aspiration Control Systems Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Aspiration Control Systems Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
