
AI skills pressure and time-poor staff shape employer demand
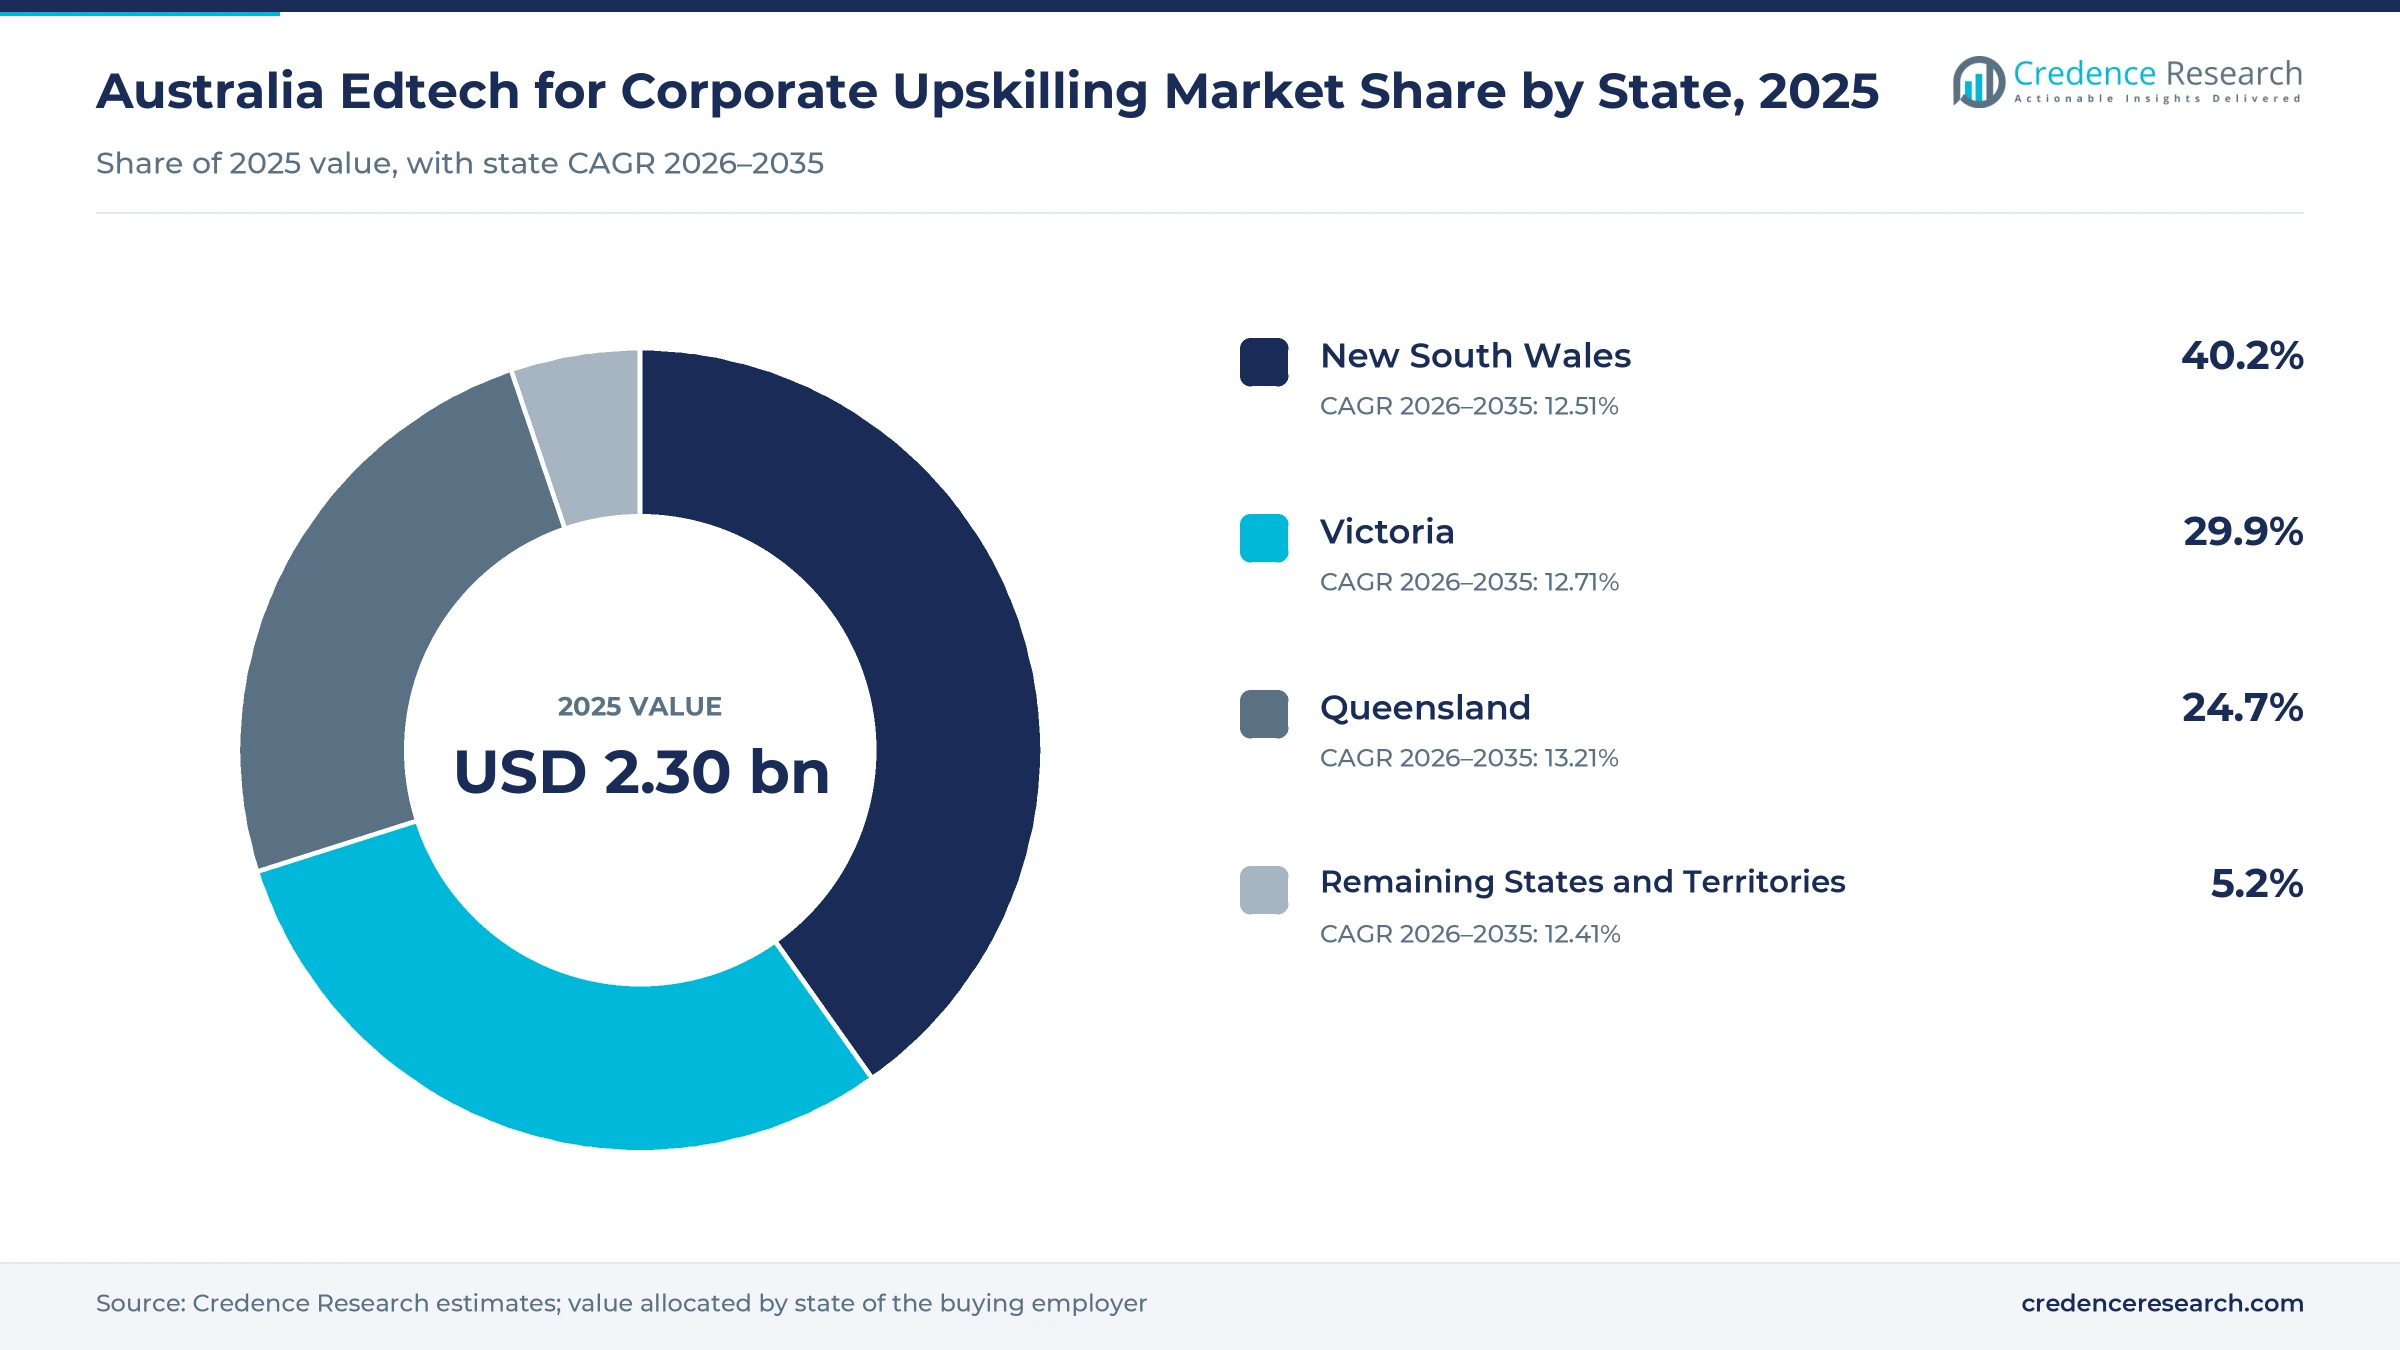
The Australia Edtech for corporate upskilling market was valued at USD 2.30 billion in 2025 and is projected to increase from USD 2.60 billion in 2026 to USD 7.67 billion by 2035, registering a CAGR of 12.74% during 2026–2035. Demand comes from employers that need staff to use generative AI, meet compliance rules and adapt to new digital tools while working from many locations. New South Wales held the largest state share, 40.2% in 2025, because Sydney hosts most financial, professional and technology head offices. Queensland is the fastest-growing state at 13.21% a year, as its workforce expands and employers shift training online. Victoria adds demand from university-led online providers and large service employers in Melbourne. The national AI plan released in December 2025 also put workforce AI skills at the center of federal policy, which raises employer spending on short online courses.
Which learning products and services does the estimate cover?
The estimate measures employer spending in Australia on learning platforms, content libraries, AI learning tools and digital learning services that build staff skills. It covers public cloud, private cloud and on-premises deployments sold through seat subscriptions, enterprise licenses and project or cohort fees. Values are measured at the first point of sale to the employing organization.
The estimate excludes degree tuition paid by individuals, school and university teaching systems and classroom training that does not use a digital product. The value chain runs from cloud and content providers through platform vendors, universities, online course firms and consultancies to employers in finance, technology, health, public services, resources and production across New South Wales, Victoria, Queensland and other states.
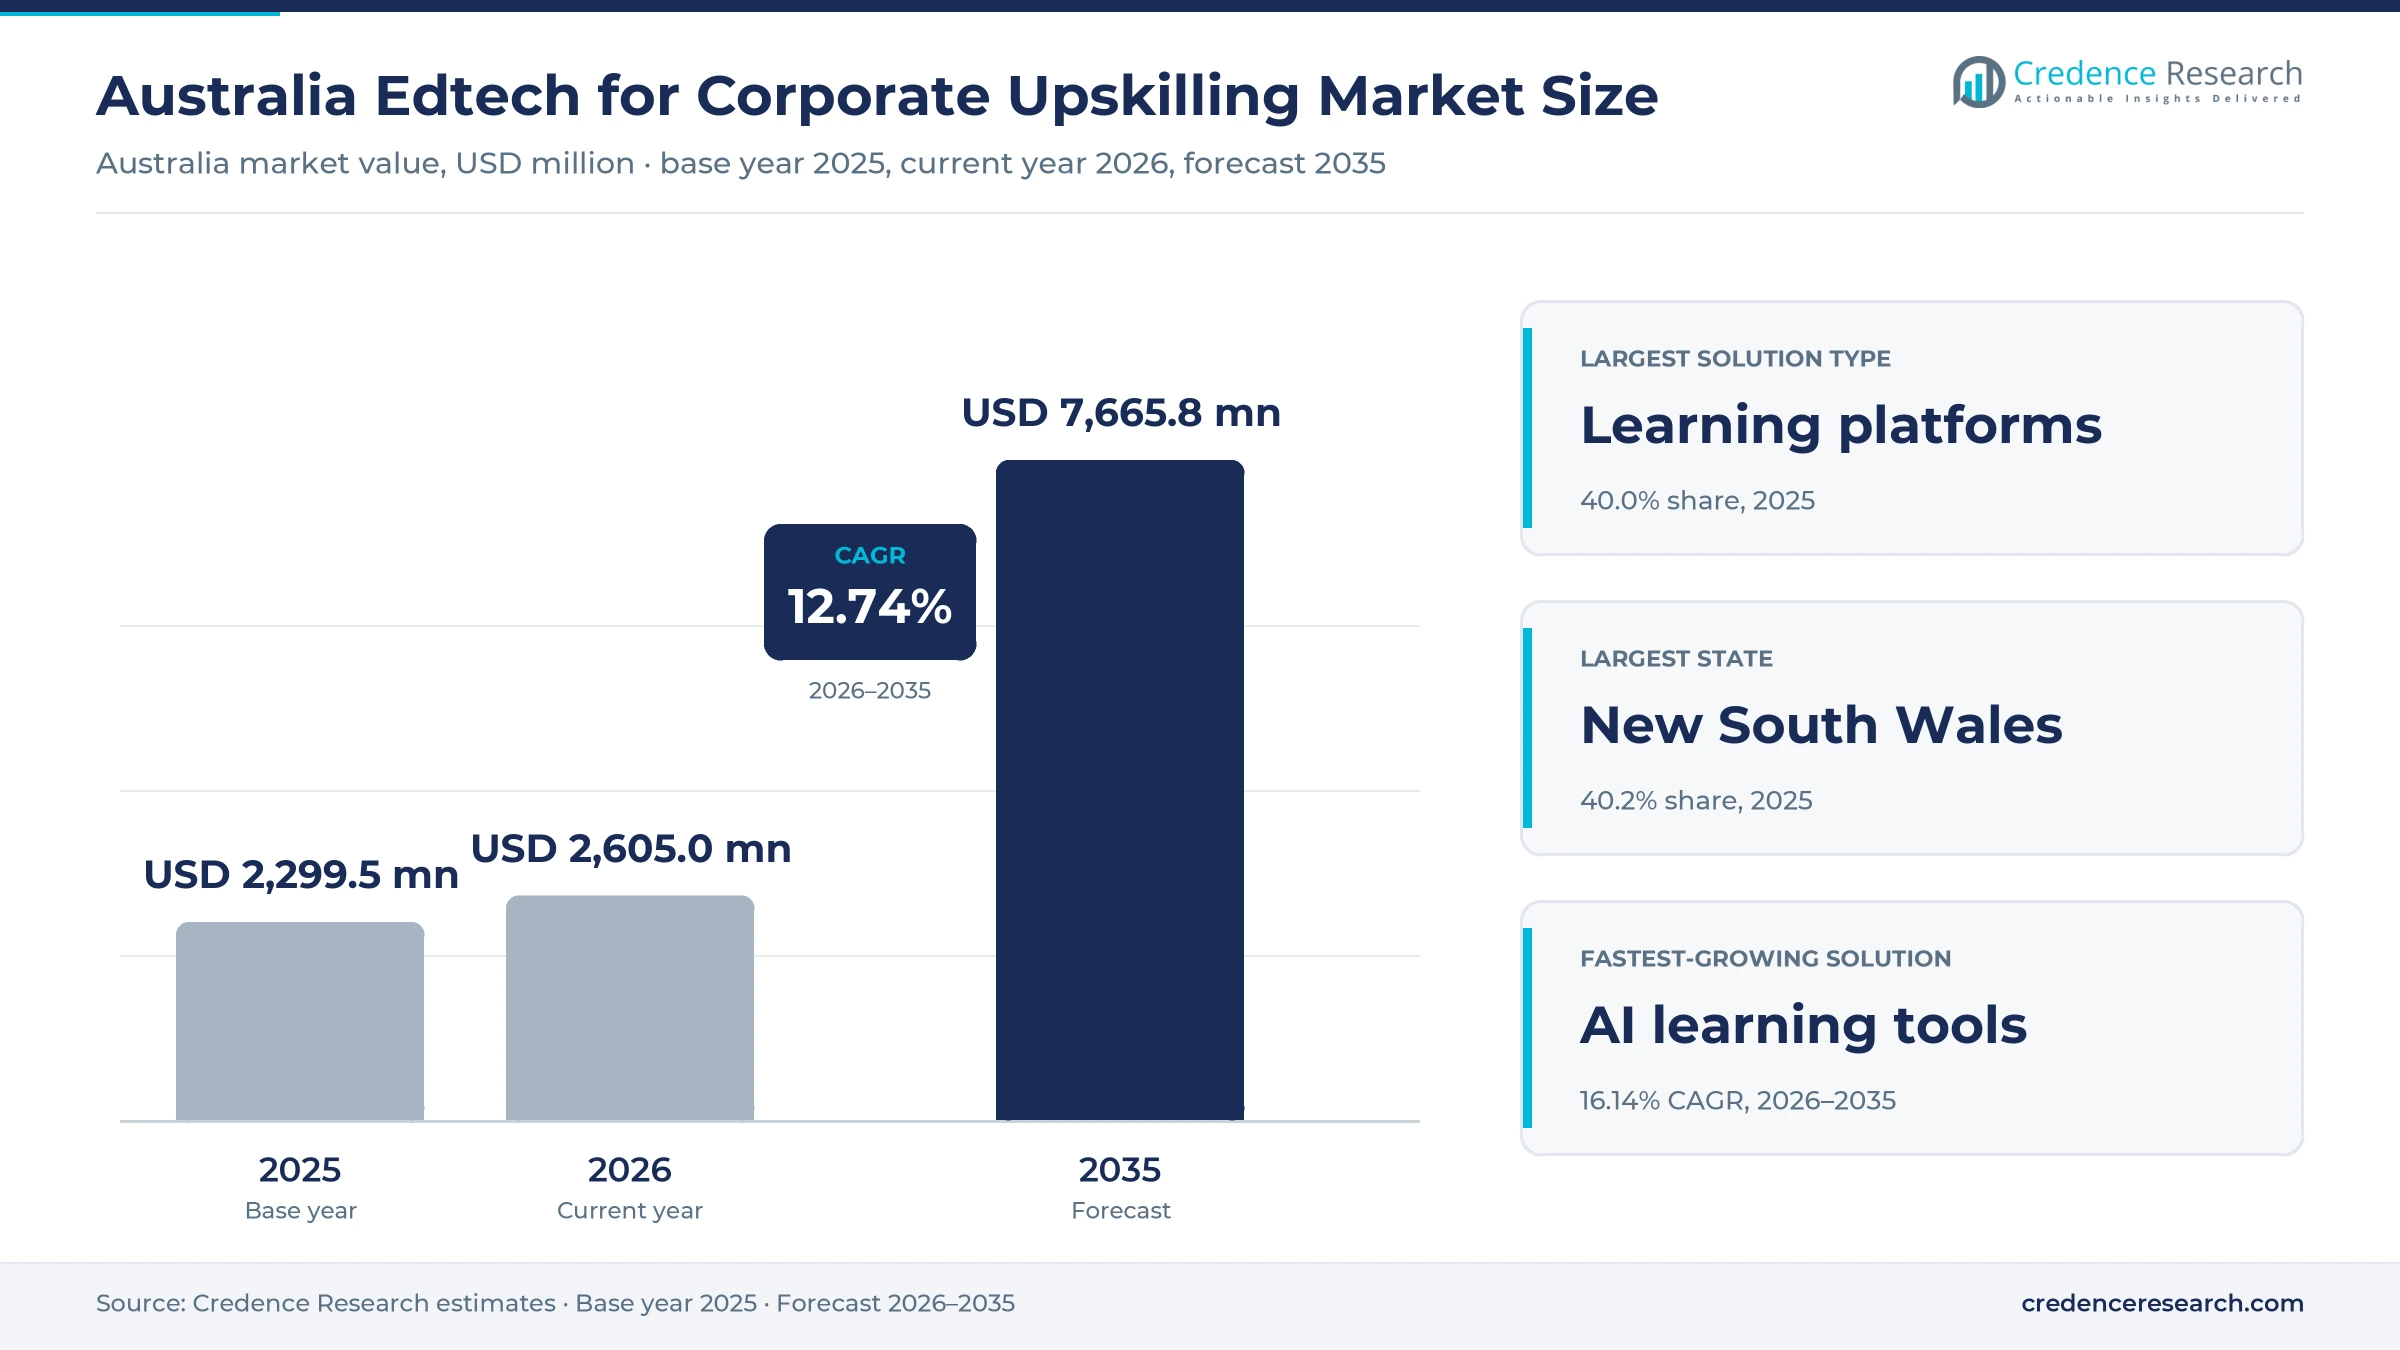
Australia Edtech for Corporate Upskilling Market Insights
- The Australia Edtech for corporate upskilling market was valued at USD 2.30 billion in 2025 and is projected to reach USD 7.67 billion by 2035, registering a CAGR of 12.74% during 2026–2035.
- New South Wales held a 40.2% share of 2025 value, because Sydney hosts most financial and professional service head offices.
- Learning platforms led solution demand with a 40.0% share of 2025 value, because employers need one system to assign and track courses.
- The federal government released its national AI plan on Dec. 2, 2025, which names AI skills training as a core workforce priority.
- About 36% of employed Australians usually worked from home in August 2025, which favors online delivery over classroom training.
Learning platforms lead while AI learning tools grow fastest
Why do learning platforms lead solution demand?
Based on solution type, the market is categorized into learning platforms, content libraries, AI learning tools and digital learning services. Learning Platforms led with a 40.0% share of 2025 value, because employers need one system to assign courses, track completion and report compliance. AI Learning Tools grow fastest at 16.14% a year, as employers use generative AI to build lessons and coach staff.
How do digital skills shape application demand?
Based on application, the market is categorized into compliance and onboarding, digital and technical skills, and leadership and business skills. Digital and Technical Skills led with a 41.0% share of 2025 value, because employers must train staff on AI, data and cloud tools. Digital and Technical Skills also grow fastest at 13.53% a year, as job skill needs change quickly and staff seek new credentials.
Why do financial and professional services lead industry demand?
Based on end-use industry, the market is categorized into financial and professional services, technology and consumer services, healthcare and public services, and resources and production. Financial and Professional Services led with a 34.0% share of 2025 value, because banks and advisory firms carry heavy compliance and digital training loads. Technology and Consumer Services grow fastest at 13.12% a year, as technology firms retrain staff on AI tools.
Why do large employers lead enterprise size demand?
Based on enterprise size, the market is categorized into small employers, medium employers and large employers. Large Employers led with a 55.0% share of 2025 value, because they buy enterprise licenses for thousands of staff and run formal learning teams. Small Employers grow fastest at 13.90% a year, as low-cost subscriptions and federal AI adoption support reach smaller firms.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Solution Type | Learning Platforms | 40.0% | AI Learning Tools | 16.14% |
| By Application | Digital and Technical Skills | 41.0% | Digital and Technical Skills | 13.53% |
| By End-Use Industry | Financial and Professional Services | 34.0% | Technology and Consumer Services | 13.12% |
| By Enterprise Size | Large Employers | 55.0% | Small Employers | 13.90% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
AI readiness, content links and remote delivery lift demand
How does AI workforce readiness lift employer spending?
AI workforce readiness lifts employer spending, because firms must teach staff to use generative tools safely and well. Jobs and Skills Australia found in August 2025 that automation may affect just over 20% of roles, and its report made 10 recommendations, according to coverage of the study. LinkedIn ranked AI literacy as the top rising skill in Australia in March 2025, and 87% of Australian professionals said they use AI tools at work, as education press reported. The national AI plan of Dec. 2, 2025, also listed an AI Skills Accelerator and VET microcredentials. As a result, AI learning tools grow at 16.14% a year, the fastest solution rate.
Why does enterprise content integration speed adoption?
Enterprise content integration speeds adoption, because employers want courses built around their own systems, processes and job tasks. RMIT Online for Business offers tailor-made courses, four-hour express courses and workforce credentialing that verifies staff skills without course content. Its Telstra case study reports 300 staff upskilled and assessed in the first year, with a 100% completion rate. One course was co-created with 23 Telstra subject matter experts in 12 weeks. Employers then load this content into learning management systems that track completion. In turn, learning platforms hold a 40.0% share of 2025 value, the largest solution share, because they connect custom content with staff records.
How does distributed workforce delivery favor online learning?
Distributed workforce delivery favors online learning, because staff now work across homes, offices and field sites. About 36% of employed people usually worked from home in August 2025, according to national working arrangements data released on Dec. 12, 2025. Internet use reached 96.13% of the population in 2024, according to World Bank data, so nearly every worker can reach online courses. SafetyCulture said in October 2023 that more than 1.5 million workers accessed its frontline platform, which lets managers build lessons on phones. As a result, digital and technical skills hold a 41.0% share of 2025 value, as remote and field staff learn new tools online.
Why does employer-funded training sustain demand?
Employer-funded training sustains demand, because most workplace learning in Australia is paid for by the employer rather than the worker. An Ai Group analysis of 2024 household survey data, published on July 20, 2026, found that 86% of employees doing work-related training had it fully paid by their employer. About nine in 10 of those workers trained during paid hours, and employer investment in paid training time reached at least $3.7 billion in 2024. These budgets now shift from classroom courses toward workplace training delivered online. In turn, large employers hold a 55.0% share of 2025 value, because they run the largest paid training programs.
Short courses, AI literacy and credentials reshape buying
How is the shift to short on-demand courses changing buying?
The shift to short on-demand courses is changing buying, because many staff say they have no time for long programs. Participation in work-related training and adult learning fell to 34% in 2024-25 from 39% in 2020-21, according to reporting on the national survey. About 60.3% of full-time workers cited lack of time as a barrier to further study. RMIT Online responded with express courses of about four hours that teams can take on demand or in groups. As a result, content libraries and short courses gain weight in seat subscriptions sold to busy employers, and corporate upskilling budgets move toward bite-sized formats.
Why is the rise of AI literacy reshaping course catalogs?
The rise of AI literacy is reshaping course catalogs, because employers now treat basic AI skills as a core requirement for most office jobs. LinkedIn reported that AI-related hires in Australia rose 240% since 2016, and AI talent hiring grew 31% year on year. It also projected that job skill requirements will change by 66% by 2030 compared with 2016. The national AI plan asks every Australian Public Service agency to appoint a Chief AI Officer and train staff in generative AI tools. In turn, vendors add adaptive learning paths that adjust AI lessons to each learner, which makes AI literacy the fastest-moving topic in corporate upskilling catalogs.
Can small employer AI adoption open new demand?
Small employer AI adoption opens new demand, because many small firms lack learning teams and need low-cost courses. The national AI plan placed the AUD 17 million AI Adopt Program under the National AI Centre to help small and medium firms adopt AI. Cost is also a growing barrier, as 35.7% of full-time workers cited financial reasons in 2024-25, up from 18.4% in 2020-21. Monthly seat subscriptions with no setup fee lower that barrier for small teams. As a result, small employers grow at 13.90% a year, the fastest enterprise size rate, as corporate upskilling tools reach firms without learning teams.
Is there room for growth in workforce skills credentials?
Workforce skills credentials create room for growth, because employers and staff want proof of new skills that travels between jobs. RMIT Online offers more than 50 shareable credentials and a workforce credentialing service backed by its university. LinkedIn found that 59% of Australians were looking for a new job in 2025, while 41% did not know how to match their skills to roles. The national AI plan also names VET microcredentials as a route to AI skills. In turn, providers of professional online courses can sell credential bundles to employers, which links corporate upskilling spending to hiring and promotion decisions.
Time pressure, cost and weak completion slow adoption
How does time pressure limit course completion?
Time pressure limits course completion, because full-time staff often cannot set aside hours for learning during busy weeks. Many workers cite workload as the main reason they skip further study. As a result, employers pay for seats that staff never use, which weakens the case for renewal. Vendors respond with short lessons, mobile access and manager nudges, while employers set protected learning time in paid hours to lift completion.
Why do rising costs slow smaller buyers?
Rising costs slow smaller buyers, because enterprise licenses and custom content projects require budgets that small firms rarely hold. A growing share of workers also cite cost as a barrier to further study. In turn, small employers often rely on free videos that lack tracking or credentials. Vendors respond with monthly per-seat plans and bundled content, while government AI adoption programs help small firms plan their training.
How does weak proof of impact delay renewals?
Weak proof of impact delays renewals, because finance teams want evidence that courses improve work output. Most employers track completions but rarely link learning to sales, safety or service results. As a result, learning budgets face cuts when business conditions tighten. Vendors respond with skills assessments, analytics dashboards and credentials that show what staff can do, which helps learning teams defend their budgets.
Why do data and privacy rules complicate AI tools?
Data and privacy rules complicate AI tools, because AI tutors and course builders process staff records and company documents. Employers in finance, health and government must keep this data inside approved systems. In turn, some buyers delay AI features or demand private cloud setups. Vendors respond with local data hosting, clear model policies and admin controls that let employers decide which content an AI tool can use.
New South Wales leads while Queensland grows fastest
| State | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales | 0.92 | 40.2% | 12.51% |
| Victoria | 0.69 | 29.9% | 12.71% |
| Queensland | 0.57 | 24.7% | 13.21% |
| Remaining States and Territories | 0.12 | 5.2% | 12.41% |
Why does New South Wales hold the largest share?
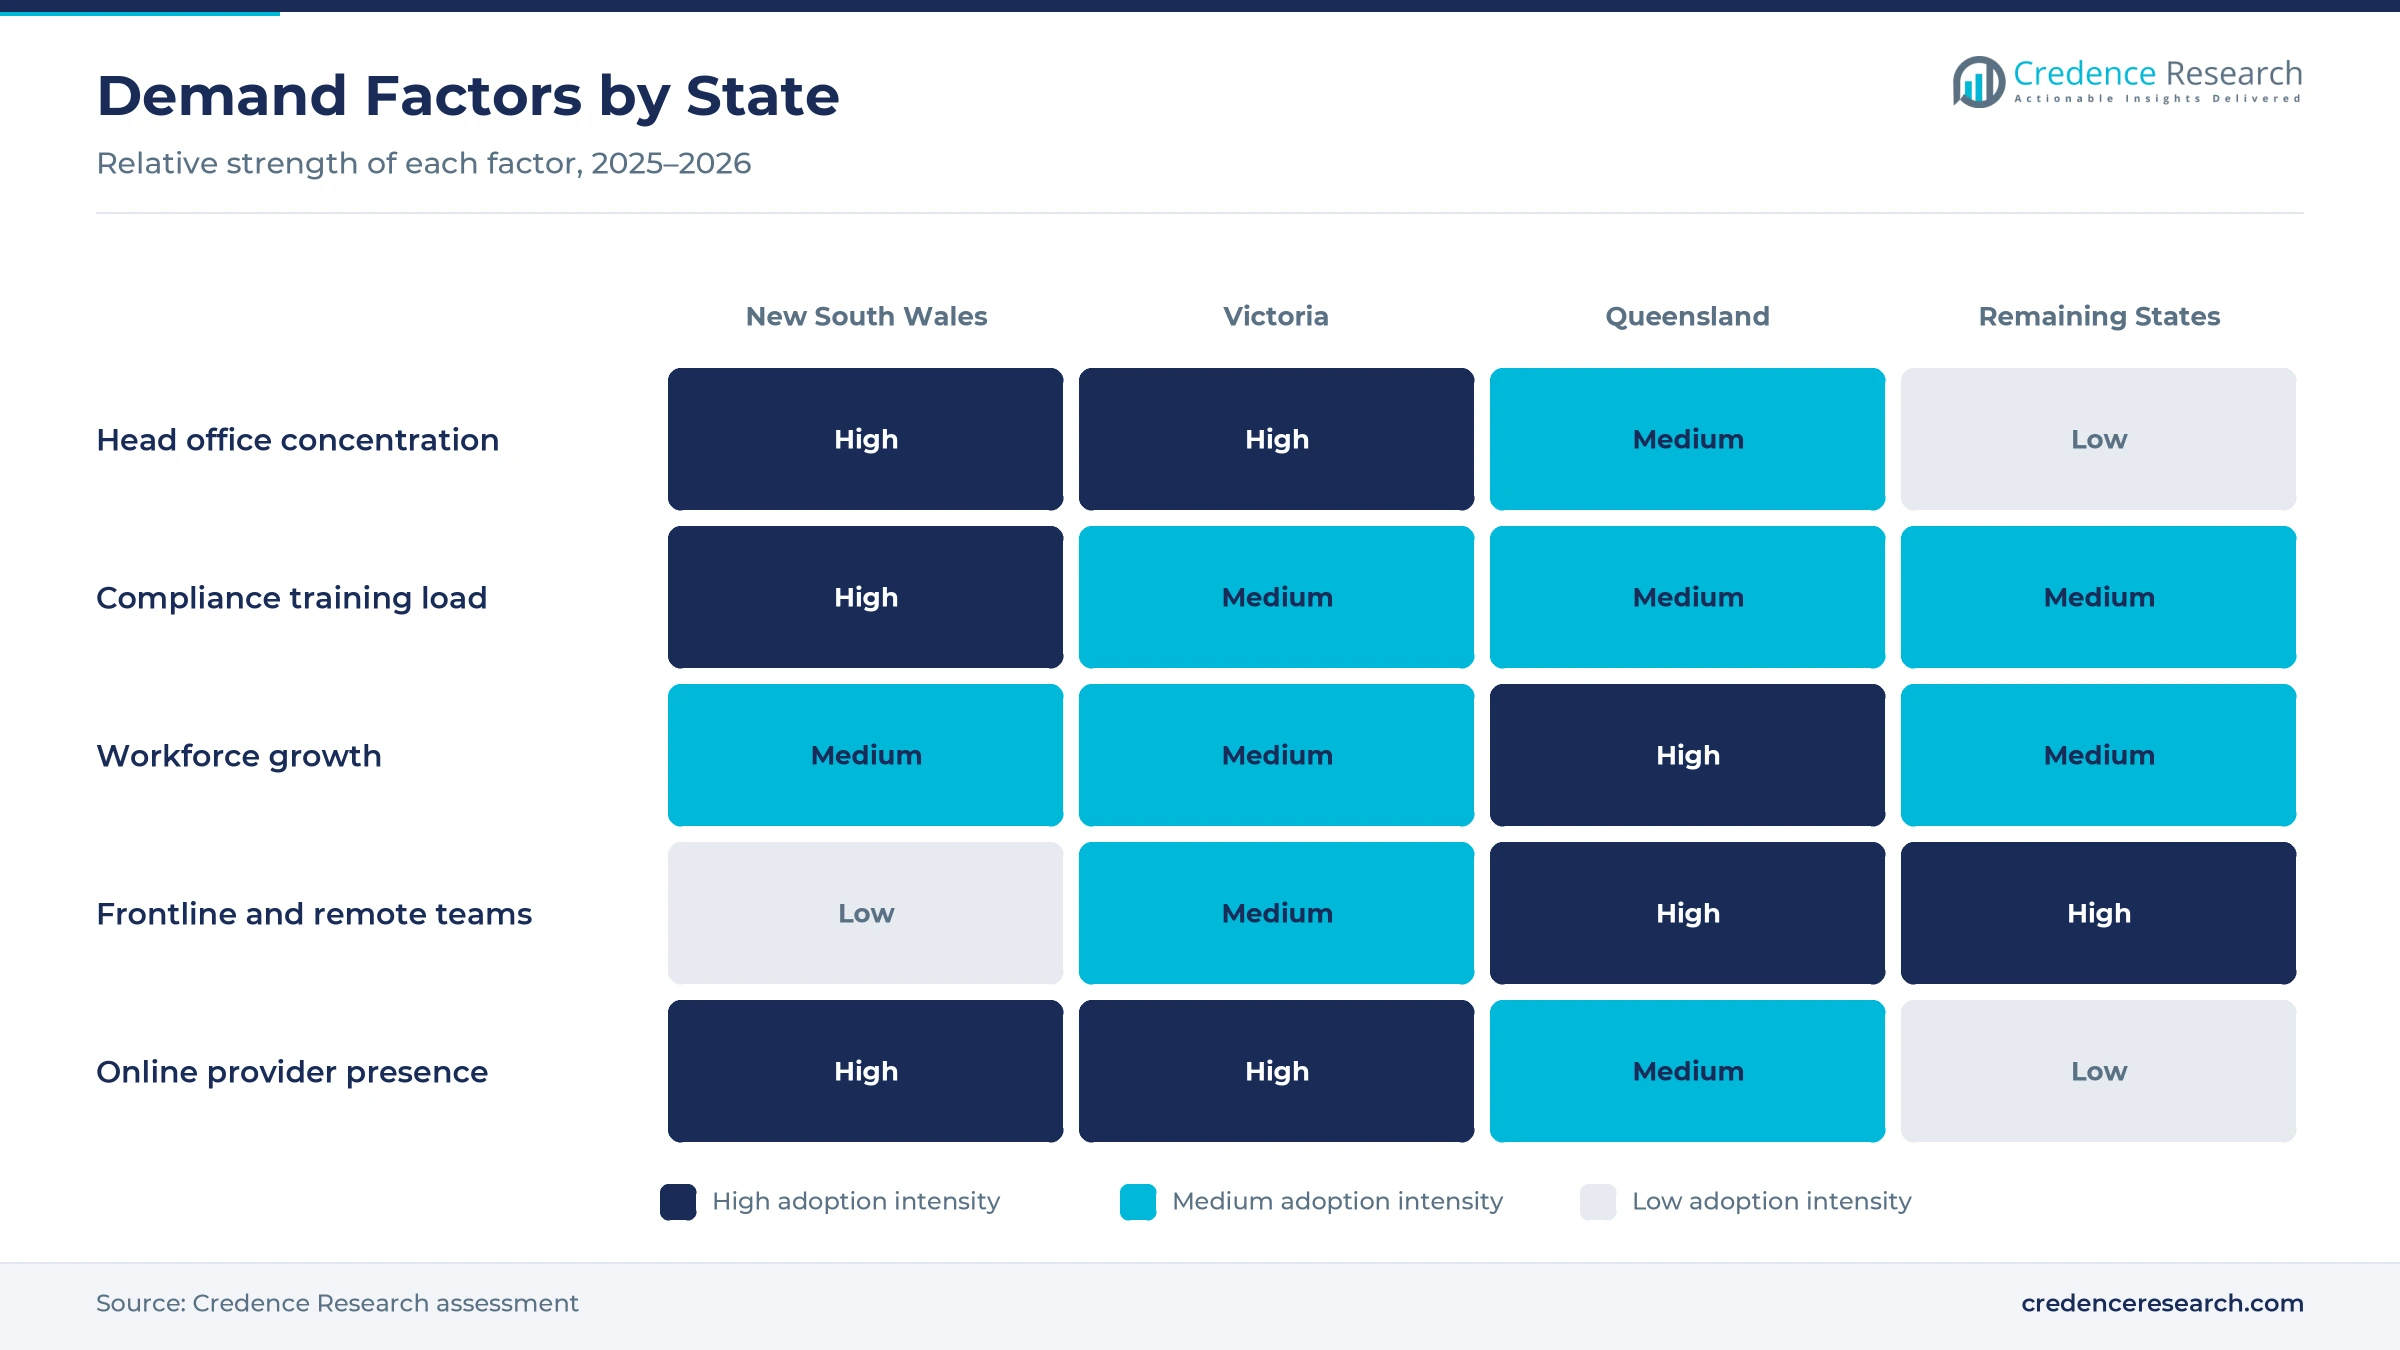
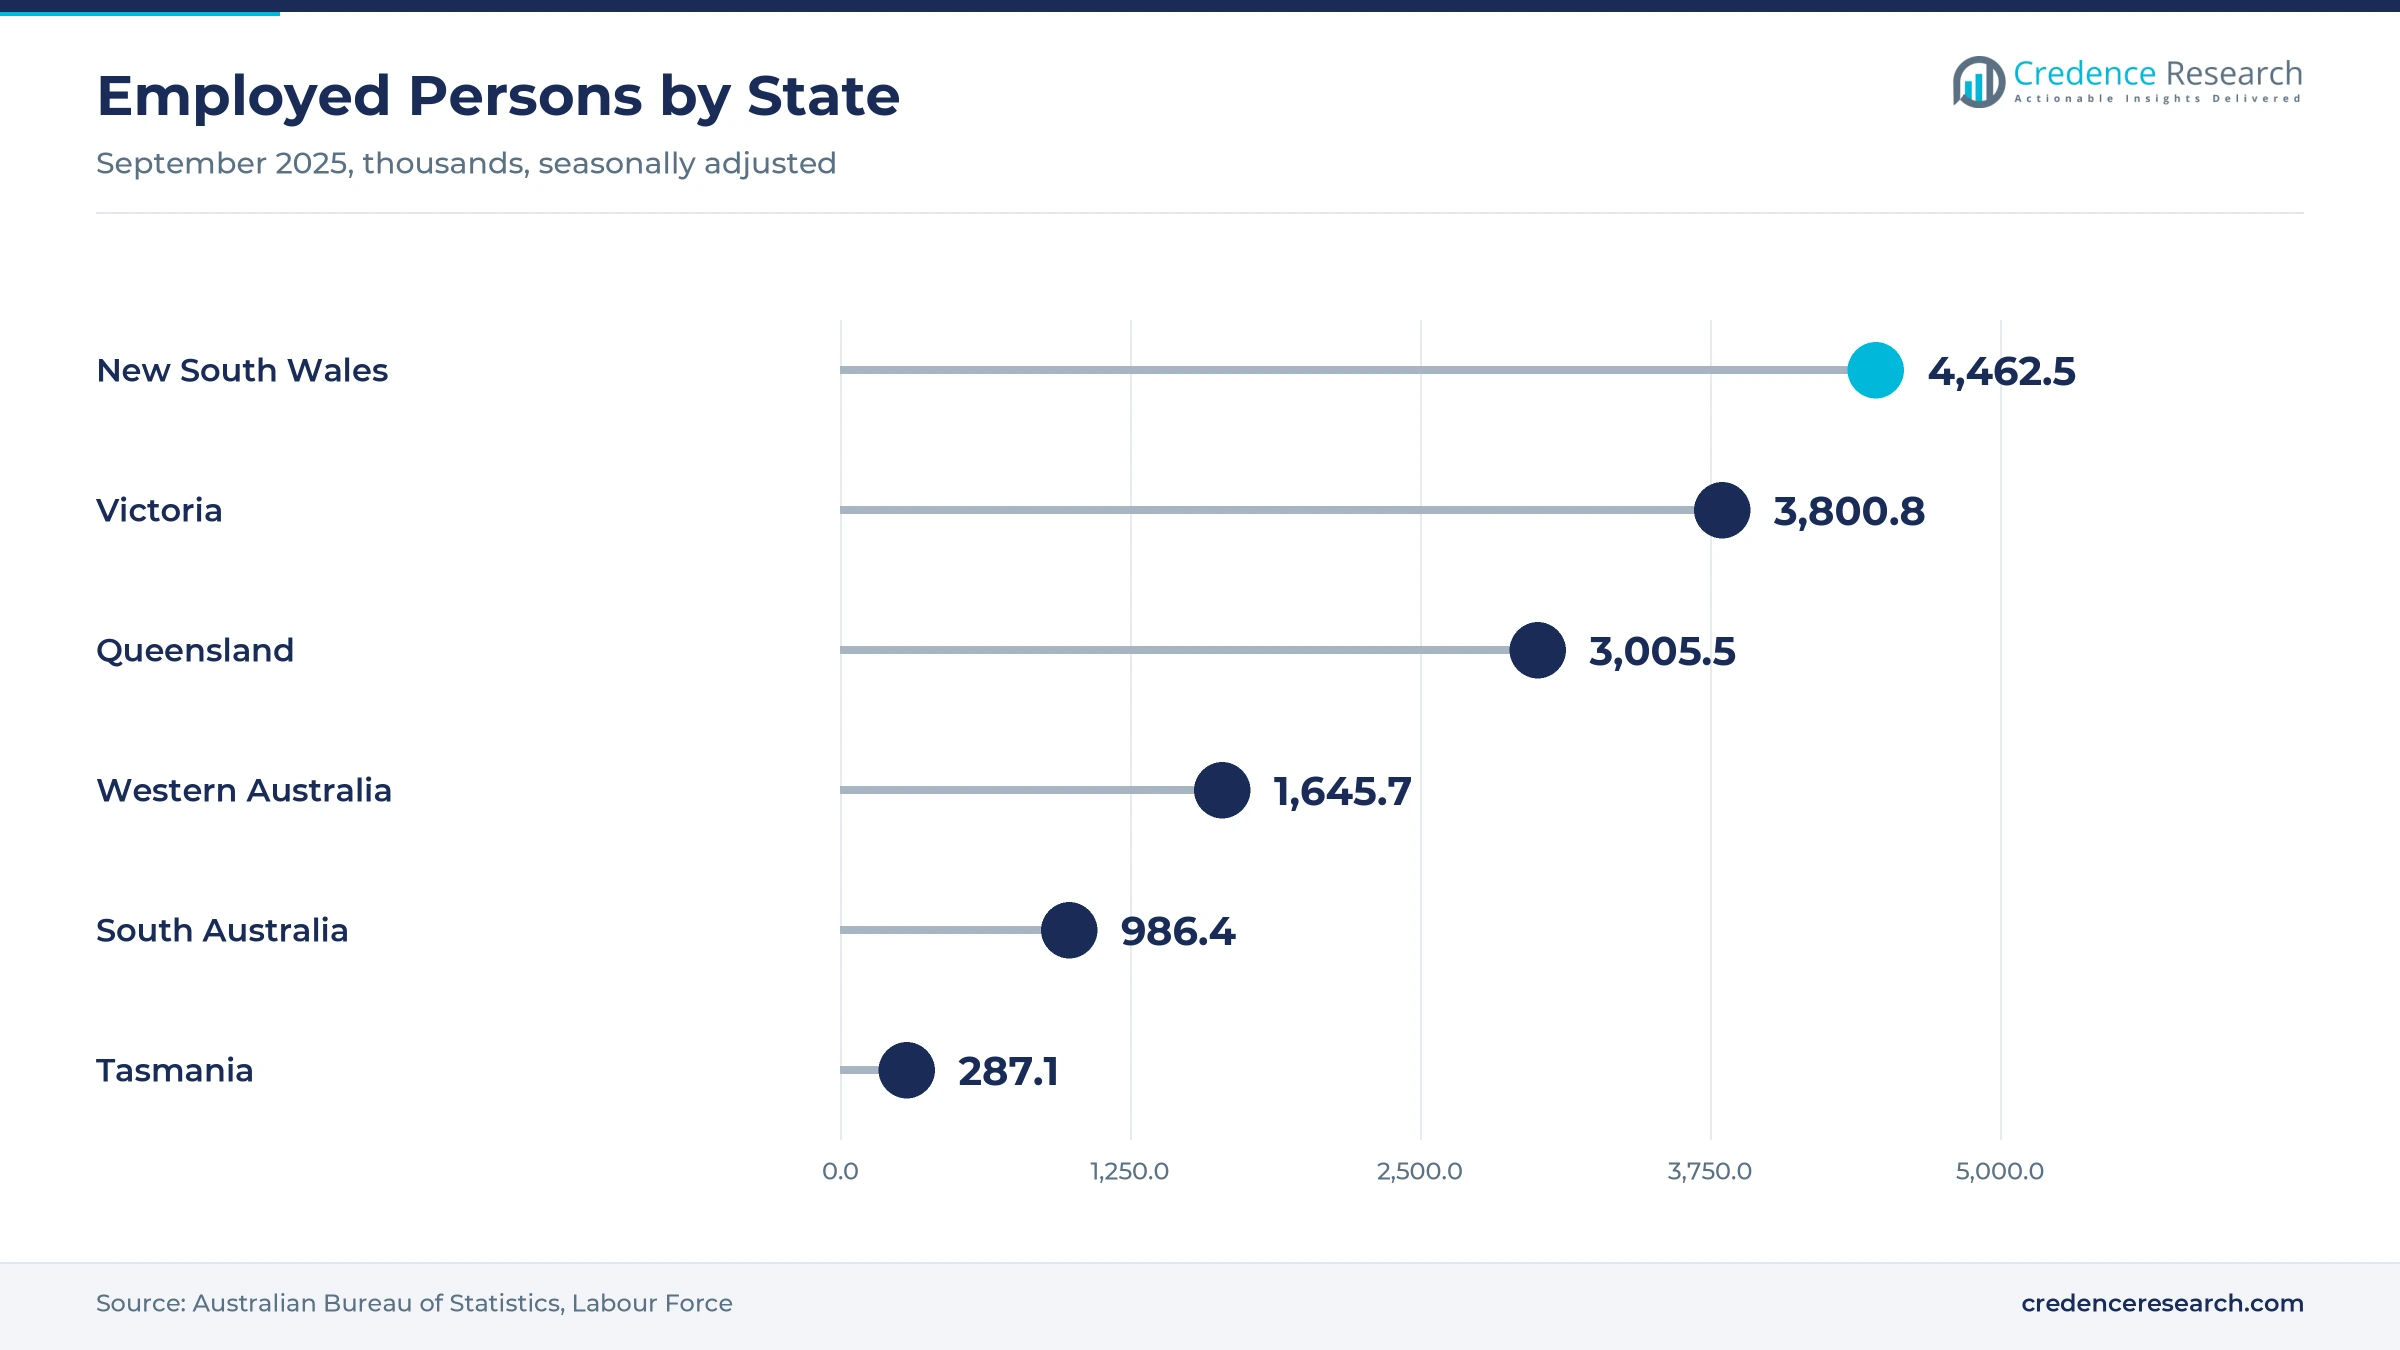
New South Wales held a 40.2% share of 2025 value and grows at 12.51% a year, because Sydney hosts the head offices of most banks, insurers and professional service firms. The state had about 4.46 million employed people in September 2025, the largest workforce in the country. Its financial employers also carry heavy compliance training loads, which keeps demand for learning platforms high. Banks and insurers in Sydney also buy AI and data courses for large office teams.
How does Victoria support university-led provision?
Victoria held a 29.9% share of 2025 value and grows at 12.71% a year, because Melbourne hosts both large service employers and university-led online providers. The state had about 3.80 million employed people in September 2025. RMIT Online is based at a Melbourne university, and Udemy announced Melbourne as its regional business hub in Australia in November 2022. Udemy said at the time that its platform served nearly one million learners in Australia.
Why is Queensland the fastest-growing state?
Queensland held a 24.7% share of 2025 value and grows fastest at 13.21% a year, because its workforce is expanding and employers are moving training online. The state had about 3.01 million employed people in September 2025. Health, public services and resources employers in the state also run large frontline teams that need mobile training across wide distances. These employers favor phone-based lessons that staff can complete between shifts.
What shapes demand in the remaining states?
The remaining states and territories held a 5.2% share of 2025 value and grow at 12.41% a year. Western Australia had about 1.65 million employed people in September 2025, while South Australia had about 0.99 million. Resources, defense and public sector employers in these states buy safety, compliance and technical courses for remote sites.
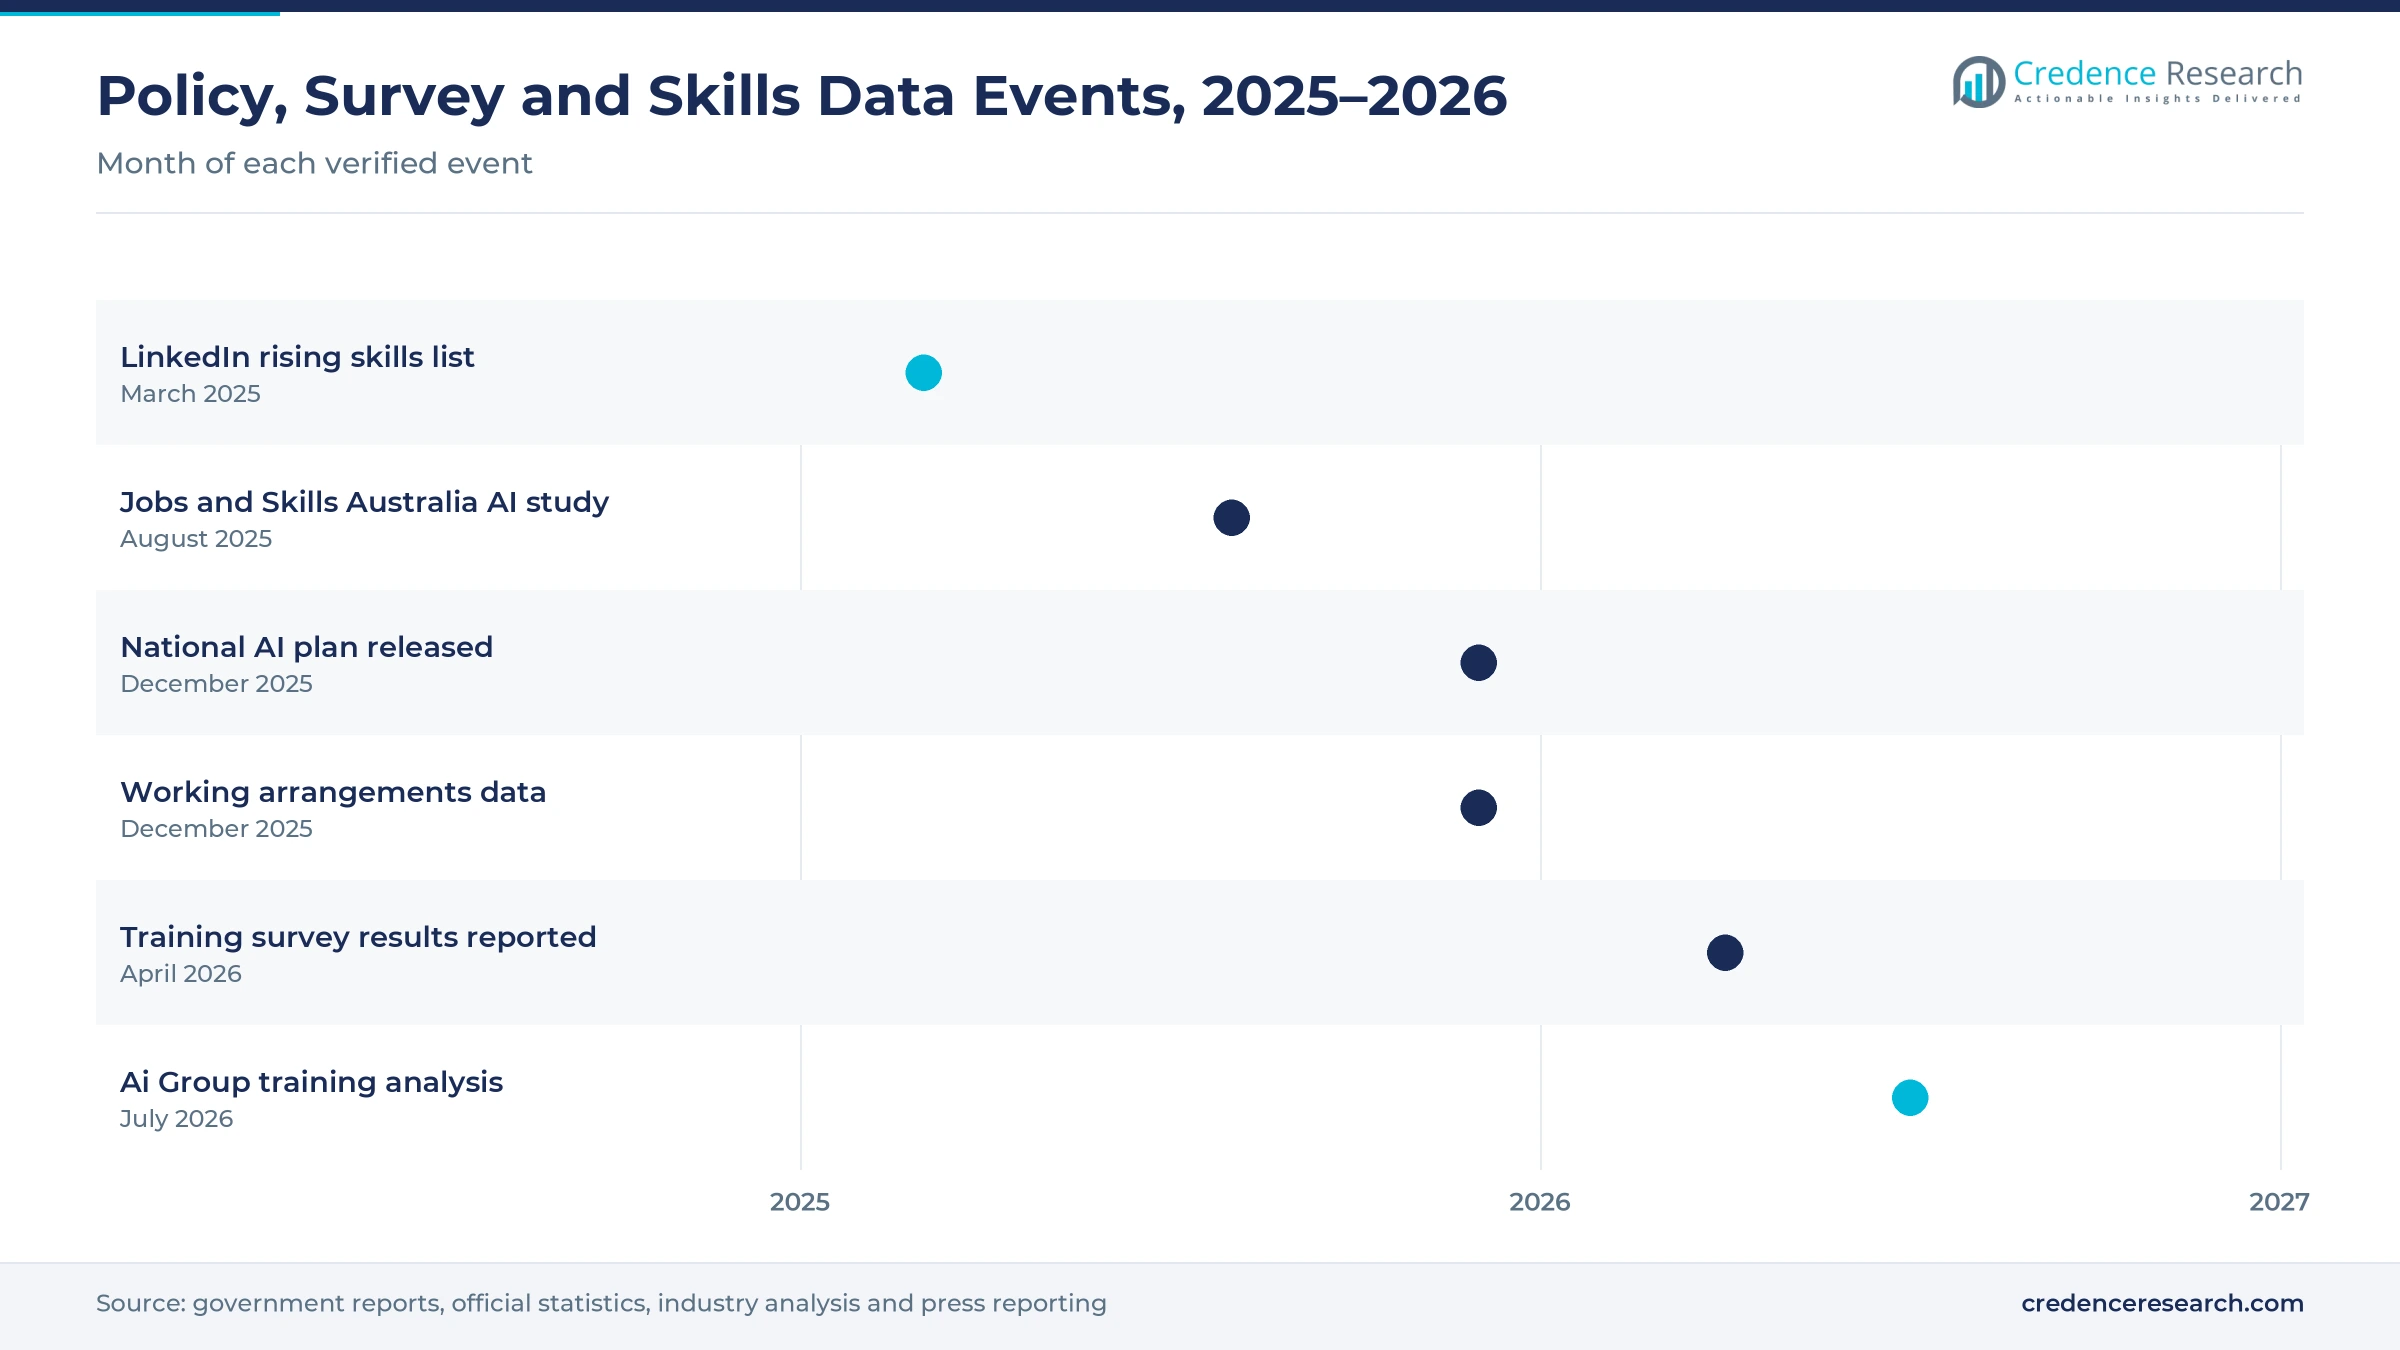
Policy, survey and skills data milestones, 2025–2026
| Development | Status and market relevance |
|---|---|
| In March 2025, LinkedIn ranked AI literacy as the top rising skill in Australia. | Signals employer demand for AI courses |
| In August 2025, Jobs and Skills Australia released its study on generative AI and work. | Frames national policy on workforce AI skills |
| In December 2025, the federal government released its national AI plan. | Names AI skills training and AI adoption support for small firms |
| In December 2025, the statistics bureau reported that 36% of employed people usually worked from home. | Supports online delivery of workforce learning |
| In July 2026, Ai Group published an analysis showing 86% of work-related training was fully employer-paid. | Confirms employer budgets as the main funding source |
Generative course design, analytics and skills credentials
- Generative course builders turn company documents into lessons and quizzes in minutes, which lets small teams create training without designers.
- AI learning assistants answer staff questions and suggest next lessons, which keeps learning close to daily work tasks.
- Learning analytics link completions to skills and job roles, which helps employers show the value of training budgets.
- Digital credentials record verified skills in a shareable format, which lets staff carry proof of learning between employers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Platforms and universities compete on skills proof
Competition combines global learning platforms with Australian university providers and frontline software firms. LinkedIn, which runs LinkedIn Learning, publishes Australian skills data drawn from 16 million members on the platform. RMIT Online sells tailor-made courses, express courses and workforce credentialing, and its Telstra program reached 300 staff in the first year. Udemy Business named Melbourne its regional business hub and lists Australia Post and P&N Group as customers. SafetyCulture unveiled an updated frontline operations platform in October 2023 that builds training in with AI-generated lessons, and it said more than 75,000 businesses used its tools. LinkedIn announced its 2025 rising skills list for Australia in March 2025, with AI literacy in first place. Companies compete on course quality, links to employer systems, proof of skills gains and the speed of new AI content.
Leading workforce learning providers in Australia
| Company | Type | Role in the market |
|---|---|---|
| LinkedIn Learning | Global learning platform | Publishes Australian skills data from 16 million members |
| RMIT Online | University online provider | Builds tailor-made courses and credentials for employers |
| Udemy Business | Online course marketplace | Runs its regional business hub from Melbourne |
| SafetyCulture | Frontline operations platform | Offers AI-built lessons for field and frontline teams |
Credence Research view on Australian workforce learning tech
Credence Research's view is that Australian employer spending on digital learning tools will grow fast because AI, remote work and compliance rules all push training online. Learning platforms keep the largest solution share, while AI learning tools grow fastest as employers build lessons with generative AI. New South Wales keeps the largest share, and Queensland grows fastest among the states. However, time pressure and weak proof of impact will slow renewals. Vendors that link learning to measured skills should gain share fastest.
How the workforce learning tech estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines labor force and working arrangement statistics, training survey results, government policy documents and company information on products and customers. Segment splits and state growth rates are Credence Research estimates, while state shares follow the client-defined split. Sources used are official statistics, government reports, company publications and news reporting, and no interviews or surveys were used.
AI skills and flexible delivery carry demand to 2035
Spending on workforce learning technology in Australia is expected to reach USD 7.67 billion by 2035, a 12.74% CAGR during 2026–2035, as employers make AI skills a standard part of every job. Growth should be fastest through 2030 while firms retrain staff on generative tools under the national AI plan. After that, credentials and skills analytics will carry more value as employers link training to hiring and promotion. Stronger proof of impact would raise this outlook, while tight budgets would lower it.
Frequently Asked Questions
How big is the Australia Edtech for corporate upskilling market?
Which solution type leads demand?
Which state leads the market?
Why do large employers lead enterprise size demand?
How does the national AI plan affect demand?
Which application leads the market?
Who are the leading companies in the market?
What are the main challenges for vendors?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Solution Type
- 1.2.1 Learning Platforms
- 1.2.2 Content Libraries
- 1.2.3 AI Learning Tools
- 1.2.4 Digital Learning Services
- 1.3 By Application
- 1.3.1 Compliance and Onboarding
- 1.3.2 Digital and Technical Skills
- 1.3.3 Leadership and Business Skills
- 1.4 By End-Use Industry
- 1.4.1 Financial and Professional Services
- 1.4.2 Technology and Consumer Services
- 1.4.3 Healthcare and Public Services
- 1.4.4 Resources and Production
- 1.5 By Enterprise Size
- 1.5.1 Small Employers
- 1.5.2 Medium Employers
- 1.5.3 Large Employers
- 1.6 By State
- 1.6.1 New South Wales
- 1.6.2 Victoria
- 1.6.3 Queensland
- 1.6.4 Remaining States and Territories
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 2.30 billion → 2035: USD 7.67 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Edtech for Corporate Upskilling Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Edtech for Corporate Upskilling Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Australia Edtech for Corporate Upskilling Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Australia Edtech for Corporate Upskilling Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Edtech for Corporate Upskilling Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Edtech for Corporate Upskilling Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Edtech for Corporate Upskilling Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Edtech for Corporate Upskilling Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 2.30 billion → 2035: USD 7.67 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Edtech for Corporate Upskilling Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Solution Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Learning Platforms
- 12.3.6.2 Content Libraries
- 12.3.6.3 AI Learning Tools
- 12.3.6.4 Digital Learning Services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Compliance and Onboarding
- 12.4.6.2 Digital and Technical Skills
- 12.4.6.3 Leadership and Business Skills
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Financial and Professional Services
- 12.5.6.2 Technology and Consumer Services
- 12.5.6.3 Healthcare and Public Services
- 12.5.6.4 Resources and Production
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Enterprise Size - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Base-Year Market Share, 2025
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Small Employers
- 12.6.6.2 Medium Employers
- 12.6.6.3 Large Employers
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 By State - Market Size and Forecast, 2025-2035
- 12.7.1 Segment Definition and Scope
- 12.7.2 Historical Market Size, 2018-2025
- 12.7.3 Revenue Forecast, 2025-2035
- 12.7.4 Base-Year Market Share, 2025
- 12.7.5 Segment CAGR and Growth Drivers
- 12.7.6 Subsegment Market Size and Forecast
- 12.7.6.1 New South Wales
- 12.7.6.2 Victoria
- 12.7.6.3 Queensland
- 12.7.6.4 Remaining States and Territories
- 12.7.7 Subsegment Pricing and Adoption Trends
- 12.7.8 Leading Suppliers and Competition
- 12.7.9 Regional Demand and Opportunities
- 12.8 Segment Growth Comparison
- 12.9 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Edtech for Corporate Upskilling End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Edtech for Corporate Upskilling Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Edtech for Corporate Upskilling Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Edtech for Corporate Upskilling Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 LinkedIn Learning
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 RMIT Online
- 18.4 Udemy Business
- 18.5 SafetyCulture
- 18.6 Cornerstone OnDemand
- 18.7 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

