
Market Overview:
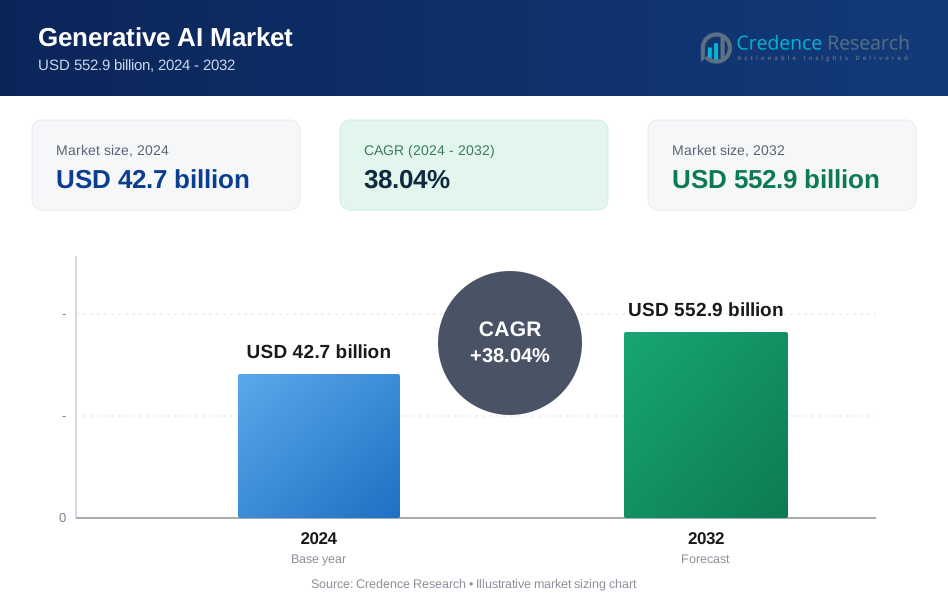
The Global Generative AI (Gen AI) Market size was valued at USD 4.5 billion in 2018 to USD 42.7 billion in 2024 and is anticipated to reach USD 552.9 billion by 2032, at a CAGR of 38.04% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Generative AI (Gen AI) Market Size 2024 | USD 42.7 Billion |
| Generative AI (Gen AI) Market, CAGR | 38.04% |
| Generative AI (Gen AI) Market Size 2032 | USD 552.9 Billion |
Market growth is driven by rising enterprise demand for automation, creative content generation, and process optimization. Organizations deploy Gen AI for text, code, design, and predictive tasks across industries like healthcare, media, finance, and telecom. Widespread cloud adoption and high-performance computing infrastructure support large-scale model training and deployment. Open-source frameworks, improved GPUs, and investment in AI platforms reduce entry barriers. Businesses integrate Gen AI tools to enhance user engagement, cut operational costs, and accelerate digital innovation across workflows.
Asia Pacific leads adoption due to strong government support, localized model development, and rapid digital transformation in countries like China, Japan, and India. North America maintains a stronghold through cloud platforms and deep research ecosystems. Europe sees steady growth with a focus on responsible AI deployment and regulatory compliance. Latin America and the Middle East show early momentum, especially in customer support and retail, while Africa is gradually building capabilities with localized solutions and mobile-first demand.

Market Insights:
- The Global Generative AI (Gen AI) Market was valued at USD 4.5 billion in 2018, reached USD 42.7 billion in 2024, and is projected to hit USD 552.9 billion by 2032, growing at a CAGR of 38.04%.
- Asia Pacific led the market with the highest share, followed by Europe and North America. These regions dominate due to strong cloud infrastructure, enterprise digitization, and government-backed AI investments.
- Europe is the fastest-growing region at a CAGR of 38.70%, driven by responsible AI adoption, regulatory support, and multilingual model development.
- In 2024, model builders accounted for approximately 57% of the market while app builders held the remaining 43%, based on visual analysis of the customer segment chart.
- The app builders segment is expanding faster due to growing demand for consumer-facing generative tools integrated into platforms, workflows, and productivity apps.
Market Drivers
Enterprise Integration Across Diverse Sectors Unlocking Productivity And Decision-Making Gains
The Global Generative AI (Gen AI) Market is expanding due to rapid enterprise adoption across diverse verticals. Companies in media, healthcare, finance, and manufacturing use Gen AI for content automation, diagnostics, financial modeling, and design workflows. It enables faster decision-making, lower operational costs, and personalized customer engagement. The ability to reduce manual tasks and optimize processes creates measurable value across departments. Firms also deploy it to augment product development and accelerate innovation timelines. Data-rich organizations lead adoption, using AI outputs to streamline analytics. Software platforms embed Gen AI features for business intelligence, document summarization, and chat support. Integration with enterprise IT systems enhances user access and boosts scalability.
- For instance, Morgan Stanley deployed its AI @ Morgan Stanley assistant powered by OpenAI’s models across its wealth management teams, giving advisors instant access to answers from around 100,000 internal research reports and documents, with 98% of advisor teams adopting the tool.
Scalable Model Training Through Cloud Infrastructure And High-Performance Computing Investments
Gen AI growth benefits from strong cloud infrastructure and access to high-performance computing resources. Leading cloud vendors offer pre-trained models and APIs to support developers and enterprises. These services reduce the cost and complexity of custom model training. It allows faster experimentation, deployment, and scaling without large on-premises hardware. GPU clusters and specialized AI chips improve training speed and inference performance. Enterprise demand for flexible, secure model access fuels multi-cloud and hybrid deployment strategies. Cloud-native development tools support model tuning and prompt engineering. Industry players also invest in AI accelerators to optimize workloads across use cases. This boosts innovation cycles and reduces time to market.
Wider Access To Open-Source Models And Tools Supporting Rapid Developer Adoption
Open-source ecosystems are accelerating the Global Generative AI (Gen AI) Market. Pretrained models, libraries, and frameworks such as Hugging Face, LangChain, and Llama increase accessibility. Developers can build prototypes and applications with limited infrastructure. Collaboration across research communities leads to faster innovation and fine-tuned models. Organizations benefit from customizable tools and community-backed performance improvements. Licensing flexibility allows enterprises to evaluate models without high upfront costs. Open model weights also support transparency and security audits. This encourages responsible deployment in regulated sectors like healthcare and banking. It reduces vendor lock-in while improving deployment agility and control.
- For instance, Meta’s release of the Llama 2 open‑source models led to over 30 million downloads on platforms like Hugging Face within six months, accelerating prototype development and adoption in commercial and research environments.
Rising Investments And Venture Funding Fueling Competitive Product Expansion Globally
High capital inflows from venture firms and corporate investors support Gen AI product development. Funding accelerates research, team expansion, and go-to-market efforts for startups and established players. Companies race to release Gen AI features across chatbots, writing assistants, code generators, and design tools. Competition drives faster improvements in accuracy, contextual understanding, and multi-modal output quality. Large enterprises form innovation partnerships with model labs to shape enterprise-grade solutions. AI-native startups also attract strategic acquisitions by tech giants. Governments support innovation through public-private AI initiatives and sandboxes. This funding momentum increases market dynamism and product diversity across geographies.
Market Trends
Shift Toward Multi-Modal Generative AI Models Capable Of Handling Text, Image, Audio, And Video Tasks
The Global Generative AI (Gen AI) Market is evolving with the rise of multi-modal models. Developers now design systems that process and generate outputs across text, images, video, and audio. These models expand use cases in marketing, virtual assistants, film editing, and gaming. Enterprises use multi-modal AI to create immersive customer experiences and content at scale. This capability improves human-AI interaction through richer inputs and outputs. It also supports automation across industries such as entertainment, healthcare, and e-commerce. Research focuses on improving coherence and synchronization across modalities. These models also enable more accurate visual-text pairings and conversational agents.
Growing Demand For Domain-Specific And Industry-Tailored Foundation Models With Verticalized Capabilities
Vendors increasingly develop industry-specific Gen AI models tailored to legal, medical, financial, or scientific tasks. This trend addresses the need for accuracy, compliance, and domain understanding. Companies train models on curated datasets to reduce hallucinations and increase relevance. The Global Generative AI (Gen AI) Market benefits as regulated industries seek high-assurance deployments. Enterprise buyers prefer vertical solutions that integrate with core applications. Vendors also deliver fine-tuned models with built-in templates and role-specific workflows. It improves productivity in document review, diagnostics, and reporting. These models offer greater interpretability and ease of use across non-technical teams.
Expansion Of Responsible AI Governance, Model Testing, And Alignment Frameworks Across Enterprises
Responsible AI deployment has become a core trend across global enterprises and vendors. Organizations invest in governance frameworks, bias audits, and model alignment tools. Governments propose Gen AI regulations focused on transparency, content labeling, and ethical use. The Global Generative AI (Gen AI) Market adapts to these changes by embedding compliance features. Model developers build guardrails to prevent toxic or misleading outputs. Enterprises require red-teaming, prompt injection testing, and audit logs. Vendors promote explainability features to support regulated deployments in banking and healthcare. These developments support trust and accountability across large-scale applications.
- For instance, IBM’s watsonx.governance provides enterprise‑grade audit, bias detection, and explainability tools for AI models, helping organizations strengthen compliance and risk oversight across finance and healthcare deployments. It includes governance frameworks and reporting features that support responsible model management.
Integration With Workflow Automation Tools And No-Code Platforms To Boost End-User Productivity
Gen AI capabilities are merging with workflow automation platforms and no-code environments. This trend democratizes AI development and increases adoption by non-engineering teams. It enables marketing, HR, and operations to generate content, analyze data, or streamline tasks. The Global Generative AI (Gen AI) Market benefits from faster solution creation cycles. Embedded Gen AI widgets now appear in tools like CRMs, ERPs, and productivity suites. Users access AI-powered features without switching platforms or writing code. This approach supports wide-scale adoption in small and mid-sized businesses. It also encourages AI integration in daily operational decisions.
- For instance, Salesforce Einstein Copilot in its CRM platform automates sales task generation and handles billions of customer interactions daily via no-code prompts, enabling 80% faster task completion.

Market Challenges Analysis
Lack of Standardization, Model Interpretability, and Accuracy Control Across Commercial Use Cases
The Global Generative AI (Gen AI) Market faces persistent challenges related to model accuracy, transparency, and consistency. Outputs often include hallucinations, biases, or unverifiable information, creating risks for commercial users. Enterprises require more robust validation tools before deploying Gen AI at scale. Current benchmarks vary across providers, making performance comparison difficult. Many models lack transparency into decision paths and internal logic, limiting trust. This creates compliance hurdles in sectors such as finance and healthcare. Standard evaluation protocols and sector-specific metrics remain underdeveloped. Without interpretability and traceability, regulated industries hesitate to adopt Gen AI in critical operations.
High Energy Consumption, Infrastructure Costs, And Talent Shortages Limiting Equitable Global Adoption
Training large Gen AI models requires massive compute and energy resources, often concentrated in select regions. These costs restrict access for startups, universities, and developing economies. Even inference operations demand significant cloud and storage capacity, increasing TCO for enterprises. The Global Generative AI (Gen AI) Market also faces a shortage of skilled professionals in model development, prompt engineering, and AI ethics. Smaller firms struggle to attract talent, delaying adoption and limiting innovation diversity. Rising operational costs further strain AI budgets in volatile markets. Environmental concerns about carbon emissions from model training also attract regulatory attention.
Market Opportunities
Growing AI Demand in Government, Education, And Public Services Driving Long-Term Vertical Adoption
The Global Generative AI (Gen AI) Market holds long-term opportunities across public sector applications. Governments explore AI for translation, citizen support, and document summarization. Education systems use Gen AI for curriculum creation, tutoring, and content accessibility. Public health departments apply it for communication, triage, and behavioral messaging. These segments need cost-efficient, scalable solutions that Gen AI can deliver. Vendors offering localized language support and compliance can capture demand. Deployment in these areas improves service delivery and reduces workload on human agents.
Localization, Language Diversity, And Cultural Relevance Unlocking Growth In Emerging Markets
Emerging economies present strong Gen AI growth potential through language-specific and culturally adapted solutions. Enterprises in Asia, Africa, and Latin America seek tools supporting regional dialects and contexts. The Global Generative AI (Gen AI) Market can expand through multilingual model offerings. Vendors investing in local data partnerships and ethical sourcing gain user trust. This opens use cases in retail, media, customer support, and public outreach. Localization also enables affordable education and content tools for underserved populations.
Market Segmentation Analysis:
By component, software dominates the Global Generative AI (Gen AI) Market due to widespread deployment of pre-trained models, APIs, and embedded AI features. Services segment grows steadily with rising demand for integration support, fine-tuning, and managed deployments across enterprises. It enables organizations to scale Gen AI use while minimizing operational risks and infrastructure costs.
- For instance, OpenAI's GPT-4o model supports a 128K token context window with real-time multimodal reasoning across text, audio, and vision, as announced in their official May 2024 launch.
By customer, model builders lead adoption by developing core generative frameworks, custom LLMs, and training pipelines. App builders form a fast-growing segment, embedding Gen AI into productivity tools, creative platforms, and vertical SaaS solutions. This shift increases accessibility for non-technical users and supports commercial application delivery.
By application, content generation holds a major share due to use cases in marketing, design, documentation, and media production. Natural Language Processing (NLP) drives demand through chat, summarization, and classification. Computer vision and robotics support industrial and retail automation, while predictive analytics gains traction in finance and logistics. Chatbots and virtual assistants are growing across enterprise workflows and customer service.
By end user, media and entertainment dominate due to strong content production needs. BFSI, IT & telecom, and healthcare segments adopt Gen AI for knowledge automation, customer insights, and decision support. Automotive and gaming sectors explore AI for simulation, design, and user interaction. It sees rising integration across sectors looking to boost efficiency, engagement, and innovation.
- For instance, Runway's Gen-3 Alpha model generates 10-second 720p videos from text prompts in seconds, as per their June 2024 announcement used in Hollywood pilots.
Segmentation:
By Component
- Software
- Services
By Customer
- Model Builders
- App Builders
By Application
- Computer Vision
- Natural Language Processing (NLP)
- Robotics & Automation
- Content Generation
- Chatbots & Intelligent Virtual Assistants
- Predictive Analytics
- Others
By End User
- Media & Entertainment
- Banking, Financial Services, and Insurance (BFSI)
- IT & Telecommunication
- Healthcare
- Automotive & Transportation
- Gaming
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Regional Analysis:
North America
The North America Global Generative AI (Gen AI) Market size was valued at USD 1.09 billion in 2018 to USD 10.10 billion in 2024 and is anticipated to reach USD 127.17 billion by 2032, at a CAGR of 37.57% during the forecast period. North America accounts for approximately 23% of the global market share. It leads adoption due to the presence of major technology providers, high enterprise readiness, and advanced cloud infrastructure. The U.S. drives most investments through strong innovation ecosystems in AI hubs like Silicon Valley and Seattle. Major companies integrate Gen AI in productivity tools, customer support, and content services. Canada supports AI through national programs and partnerships between academia and startups. Demand grows across healthcare, BFSI, and media sectors. It benefits from deep venture capital flows and high public awareness of generative tools.
Europe
The Europe Global Generative AI (Gen AI) Market size was valued at USD 1.23 billion in 2018 to USD 11.89 billion in 2024 and is anticipated to reach USD 159.79 billion by 2032, at a CAGR of 38.70% during the forecast period. Europe holds around 26% of the global market share. It sees strong momentum in Germany, the UK, and France, where enterprises integrate Gen AI in enterprise software, industrial automation, and life sciences. Regulatory focus on responsible AI drives demand for explainability, transparency, and governance frameworks. Public-private initiatives support cross-border R&D and deployment pilots. Vendors localize Gen AI models to meet multilingual and sector-specific needs. The region also supports open-source collaborations and AI ethics councils. Demand grows across manufacturing, public sector, and healthcare.
Asia Pacific
The Asia Pacific Global Generative AI (Gen AI) Market size was valued at USD 1.58 billion in 2018 to USD 14.90 billion in 2024 and is anticipated to reach USD 193.52 billion by 2032, at a CAGR of 38.11% during the forecast period. Asia Pacific contributes approximately 30% of the global market share. China, Japan, South Korea, and India lead deployments across cloud services, smart cities, and education. Local tech giants invest heavily in large language models, infrastructure, and AI-as-a-service offerings. Government-backed AI strategies support adoption across public services and national R&D. Gen AI gains traction in regional languages, ecommerce, and video content generation. Startups build domain-specific apps in fintech, logistics, and edtech. Infrastructure scalability and mobile-first demand create unique regional opportunities.
Latin America
The Latin America Global Generative AI (Gen AI) Market size was valued at USD 0.34 billion in 2018 to USD 3.12 billion in 2024 and is anticipated to reach USD 39.26 billion by 2032, at a CAGR of 37.56% during the forecast period. Latin America holds about 6% of the global market share. Brazil and Mexico anchor the region’s growth through enterprise digitization and cloud expansion. Organizations deploy Gen AI for customer engagement, content marketing, and back-office optimization. Education and public sector experiments explore AI for access, translation, and learning tools. Local firms adapt global models to Spanish and Portuguese markets. Infrastructure and skills gaps remain key barriers, but startup ecosystems show early momentum. Demand increases in retail, telecom, and financial services.
Middle East
The Middle East Global Generative AI (Gen AI) Market size was valued at USD 0.22 billion in 2018 to USD 1.92 billion in 2024 and is anticipated to reach USD 22.67 billion by 2032, at a CAGR of 36.48% during the forecast period. The region holds around 4% of the global market share. The UAE and Saudi Arabia lead adoption with AI-focused national agendas, digital economy goals, and smart city projects. Enterprises use Gen AI for Arabic NLP, chatbots, and predictive systems. Public investment accelerates development through partnerships and AI sandboxes. It supports deployment in energy, government services, and education. Regional tech hubs promote AI startups with incentives and research grants. Gen AI tools gain use across finance, tourism, and logistics. Language diversity and cloud investments support market expansion.
Africa
The Africa Global Generative AI (Gen AI) Market size was valued at USD 0.09 billion in 2018 to USD 0.81 billion in 2024 and is anticipated to reach USD 10.51 billion by 2032, at a CAGR of 38.15% during the forecast period. Africa captures nearly 2% of the global market share. South Africa, Nigeria, Kenya, and Egypt drive early adoption through AI initiatives and startup activity. Governments use Gen AI for digital learning, translation, and public communication. It supports applications in healthcare access, fintech, and agritech. Local developers adapt open-source models for underserved languages. Infrastructure challenges and funding limitations slow growth, but mobile-first demand creates unique entry points. The region gains global attention for ethical, inclusive, and localized AI solutions.
Key Player Analysis:
- Amazon Web Services (AWS)
- Microsoft
- IBM
- Google LLC
- ai
- Synthesia
- Genie AI Ltd
- D-ID
- MOSTLY AI Inc.
- Other Key Players
Competitive Analysis:
The Global Generative AI (Gen AI) Market features a dynamic competitive landscape driven by technology giants and emerging startups. Leading players such as Amazon Web Services, Microsoft, Google, and IBM dominate with extensive cloud infrastructure, foundation models, and platform integrations. Specialized firms like Rephrase.ai, Synthesia, and D-ID focus on video, voice, and image generation, expanding niche use cases. Competition intensifies through acquisitions, partnerships, and continuous model upgrades. Companies race to offer enterprise-grade tools with higher accuracy, scalability, and responsible AI features. Open-source frameworks also influence the market, enabling agile innovation among smaller vendors. It sees increasing investment in regional expansion and verticalized solutions. Firms differentiate through proprietary training data, multilingual support, and security frameworks. The market rewards vendors that balance performance, ease of use, and regulatory readiness.
Recent Developments:
- In January 2026, Google LLC advanced AI-driven commerce by launching the Universal Commerce Protocol enabling shopping agents and reinforcing its position in generative AI retail applications.
Report Coverage:
The research report offers an in-depth analysis based on Component, Customer, Application, End User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Enterprise adoption will deepen as organizations embed generative models into core workflows, customer engagement platforms, and decision-support systems.
- Foundation models will evolve toward higher accuracy, better context handling, and stronger alignment with enterprise governance needs.
- Multi-modal capabilities will expand, enabling unified text, image, audio, and video generation within single platforms.
- Vertical-specific solutions will gain traction as vendors tailor models for healthcare, finance, manufacturing, and public services.
- Responsible AI frameworks will shape product design, pushing vendors to prioritize transparency, bias control, and audit readiness.
- Integration with no-code and low-code platforms will broaden access for non-technical users across business functions.
- Cloud-native deployment will remain central, supporting scalability, security, and rapid experimentation for enterprises.
- Emerging markets will drive new demand through localization, language diversity, and mobile-first use cases.
- Partnerships between hyperscalers, startups, and governments will accelerate ecosystem maturity and solution reach.
- Competitive differentiation will rely on data quality, deployment ease, and sustained innovation rather than model size alone.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Enterprise Integration Across Diverse Sectors
Organizations in industries such as media, healthcare, finance, and manufacturing are rapidly adopting generative AI to automate content creation, streamline workflows, and enhance decision-making, leading to measurable productivity gains and cost reductions.
Scalable Model Training Through Cloud Infrastructure
The availability of robust cloud platforms and high-performance computing resources enables faster, more affordable model training and deployment, allowing enterprises of all sizes to experiment and scale generative AI solutions without heavy upfront investment.
Wider Access to Open-Source Models and Tools
Open-source frameworks and pretrained models have lowered entry barriers, enabling developers and enterprises to quickly build, customize, and deploy generative AI applications, accelerating innovation and adoption across sectors.
Rising Investments and Venture Funding
Significant venture capital and corporate investments are fueling rapid product development, research, and go-to-market strategies, intensifying competition and expanding the range of generative AI solutions available globally.
Localization and Multilingual Model Development
Vendors are increasingly focusing on localized and multilingual generative AI models to address the needs of emerging markets and regulated industries, unlocking new growth opportunities and supporting adoption in diverse linguistic and cultural contexts.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Generative AI (Gen AI) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Generative AI (Gen AI) Market projected to grow between 2024 and 2032?
Which Global Generative AI (Gen AI) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Generative AI (Gen AI) Market?
Which region commanded the largest share of the Global Generative AI (Gen AI) Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Customer
- 1.2.1 Model Builders
- 1.2.2 App Builders
- 1.3 By End User
- 1.3.1 Media & Entertainment
- 1.3.2 Banking, Financial Services, and Insurance (BFSI)
- 1.3.3 IT & Telecommunication
- 1.3.4 Healthcare
- 1.3.5 Automotive & Transportation
- 1.3.6 Gaming
- 1.4 By Component
- 1.4.1 Software
- 1.4.2 Services
- 1.5 By Application
- 1.5.1 Content Generation
- 1.5.2 Natural Language Processing (NLP)
- 1.5.3 Computer Vision
- 1.5.4 Robotics & Automation
- 1.5.5 Chatbots & Intelligent Virtual Assistants
- 1.5.6 Predictive Analytics
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 42.7 billion → 2032: USD 552.9 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Generative AI Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Generative AI Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Generative AI Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Generative AI Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Generative AI Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Generative AI Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Generative AI Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Generative AI Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 42.7 billion → 2032: USD 552.9 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Generative AI Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Customer - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Model Builders
- 12.3.7.2 App Builders
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Media & Entertainment
- 12.4.7.2 Banking, Financial Services, and Insurance (BFSI)
- 12.4.7.3 IT & Telecommunication
- 12.4.7.4 Healthcare
- 12.4.7.5 Automotive & Transportation
- 12.4.7.6 Gaming
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Component - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Software
- 12.5.7.2 Services
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Content Generation
- 12.6.7.2 Natural Language Processing (NLP)
- 12.6.7.3 Computer Vision
- 12.6.7.4 Robotics & Automation
- 12.6.7.5 Chatbots & Intelligent Virtual Assistants
- 12.6.7.6 Predictive Analytics
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Generative AI End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Generative AI Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Generative AI Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Generative AI Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amazon Web Services (AWS)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Microsoft
- 18.4 IBM
- 18.5 Google LLC
- 18.6 OpenAI
- 18.7 Synthesia
- 18.8 Genie AI Ltd
- 18.9 D-ID
- 18.10 MOSTLY AI Inc.
- 18.11 Rephrase.ai
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

