
Calcium Nitrate Market Overview:
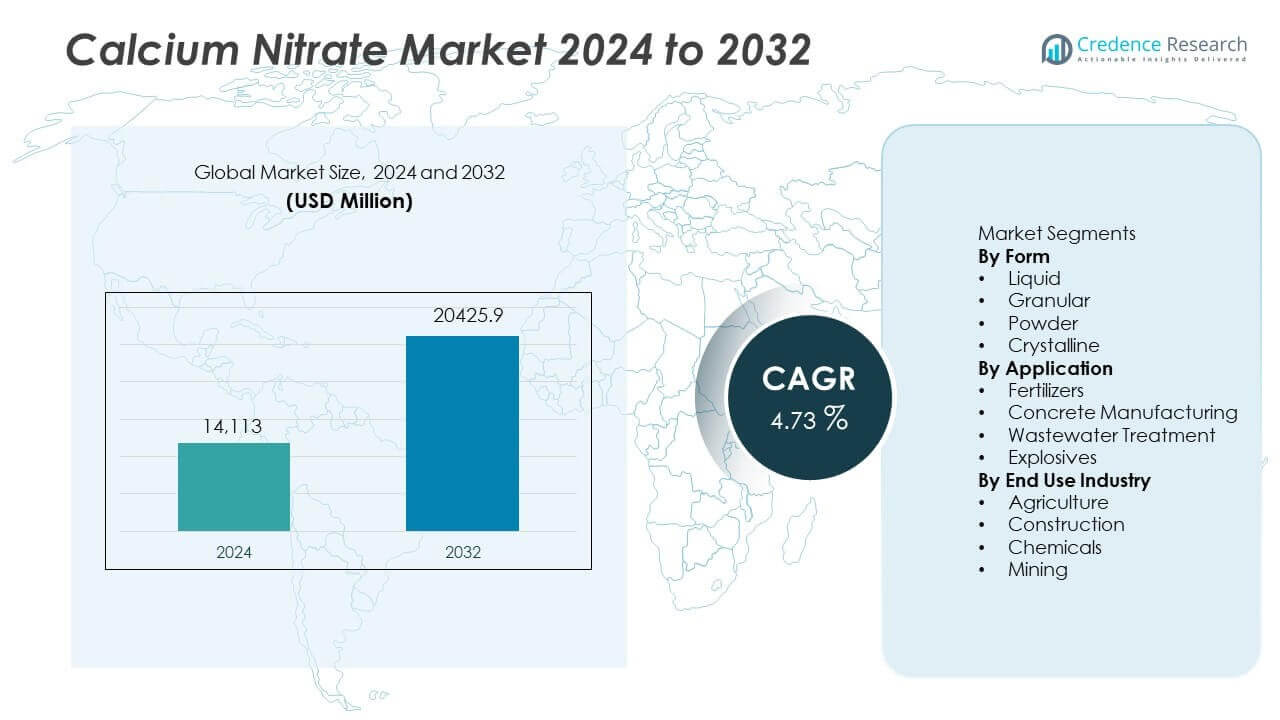
Calcium Nitrate market size was valued at USD 14,113 million in 2024 and is projected to reach USD 20,425.9 million by 2032, reflecting a CAGR of 4.73% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Calcium Nitrate Market Size 2024 | USD 14,113 million |
| Calcium Nitrate Market, CAGR | 4.73% |
| Calcium Nitrate Market Size 2032 | USD 20,425.9 million |
Calcium Nitrate Market Insights
- Demand rises due to high adoption in fertilizers, concrete accelerators, wastewater treatment, and explosives, supported by strong agricultural productivity needs and infrastructure expansion.
- Fertilizers lead the application segment with 46% share as calcium nitrate improves nutrient delivery, crop strength, and yield performance across large farming regions.
- Asia Pacific holds 36% share and leads due to strong agricultural production and construction activity, while North America follows with 30% share supported by advanced farming systems and infrastructure development.
- Market restraints include fluctuating raw material costs and regulatory requirements linked to fertilizer use and nitrogen emissions, though leading companies strengthen capacity, improve supply chains, and expand innovative product offerings to maintain competitive advantage.
Calcium Nitrate Market Segmentation Analysis:
By Form:
Liquid calcium nitrate leads the form segment with 39% share, driven by strong adoption in agriculture and wastewater treatment where fast dissolution and high nutrient availability improve efficiency. Granular and powder forms follow due to their suitability for blending, storage, and controlled application in fertilizers and industrial processes. Crystalline forms gain traction in specialized chemical and construction uses requiring high purity. The dominance of liquid reflects ease of handling, rapid absorption, and compatibility with irrigation systems. Rising agricultural productivity requirements and improved soil conditioning practices continue to reinforce market demand across global farming regions.
- For instance, Yara’s YaraLiva products contain 15.5 grams of nitrogen per 100 grams and fully dissolve at 20 °C with solubility above 1200 grams per liter, enabling fertigation use.
By Application:
Fertilizers dominate the application segment with 46% share, supported by rising crop production needs and increasing use of calcium nitrate to improve nutrient uptake, soil structure, and yield performance. Concrete manufacturing represents a significant secondary application due to its ability to accelerate setting time and enhance strength development in construction projects. Wastewater treatment benefits from improved odor control and nitrogen removal performance, while explosives continue using calcium nitrate as an oxidizing component. The leading role of fertilizers reflects global agricultural expansion, soil health awareness, and the need to address nutrient deficiencies in high-value crops.
- For instance, Haifa Group’s Multicote line delivers controlled nutrient release over several months, while their Haifa Cal Greenhouse Grade provides high-purity calcium and nitrogen specifically formulated for greenhouse crops.
By End Use Industry:
Agriculture holds the largest end-use share at 47%, driven by ongoing demand for high-performance fertilizers and nutrient management solutions. Construction follows due to strong use in concrete accelerators that improve curing and durability in large-scale infrastructure and building projects. Chemicals benefit from stable oxidizing properties and compatibility in synthesis processes, while mining applications leverage calcium nitrate for blasting and excavation activities. Growth in agriculture reflects increasing global food demand, intensive farming practices, and rising focus on crop quality. Expanding construction activity and industrial development further support long-term consumption across end-use markets.
Key Growth Drivers
Rising Demand for High-Performance Fertilizers
The market expands as calcium nitrate becomes essential in improving nutrient efficiency, crop yield, and soil structure across diverse farming systems. Its high solubility and rapid nutrient release support precision agriculture and hydroponics, driving stronger adoption in high-value crops such as fruits and vegetables. Increasing focus on food security and sustainable soil management strengthens market presence. Farmers prefer calcium nitrate to address calcium deficiencies and improve nitrogen delivery, enhancing plant strength and disease resistance. Global agricultural intensification and rising commercial farming activity continue to boost long-term demand.
- For instance, SQM’s Ultrasol® Calcium Nitrate supplies 15.5 grams of nitrogen and 19 grams of calcium per 100 grams, with full dissolution in irrigation water below 25 °C, enabling uniform fertigation delivery.
Growing Use in Concrete and Construction Projects
Construction applications drive market momentum as calcium nitrate enhances cement hydration, shortens curing time, and improves concrete durability in large-scale infrastructure projects. Urban development, transportation upgrades, and industrial expansion fuel demand across emerging and developed regions. The material offers performance advantages in cold-weather concreting, reducing delays and improving onsite productivity. Rising investment in commercial and residential projects strengthens consumption. Advanced building standards and structural safety requirements further support calcium nitrate’s role in construction materials.
- For instance, BASF’s calcium nitrate–based accelerator solutions enable initial concrete set time reduction of up to 2 hours at dosages between 1 and 2 kilograms per cubic meter under low-temperature conditions.
Expansion in Wastewater and Industrial Treatment Processes
Calcium nitrate adoption increases in wastewater treatment due to its role in odor control, corrosion prevention, and biological stabilization. Municipal systems and industrial facilities use calcium nitrate to enhance nitrogen removal and improve treatment efficiency. Growing environmental regulations drive investment in chemical treatment methods that support safe discharge standards and process reliability. Industries across chemicals, manufacturing, and food processing integrate calcium nitrate into treatment lines to improve system performance. Rising awareness of sustainable water management reinforces long-term market growth.
Key Trends & Opportunities
Growing Adoption in Specialty Agriculture and Hydroponics
Specialty farming, greenhouse production, and soilless cultivation expand calcium nitrate usage due to strong compatibility with controlled nutrient delivery systems. Hydroponic operations prefer calcium nitrate for balanced nitrogen availability and improved plant structure. Increasing demand for premium produce, reduced pesticide dependence, and year-round cultivation creates new commercial opportunities. These systems support precise dosing, reducing waste and boosting crop uniformity.
- For instance, EuroChem’s AN/CN Hydro Grade provides 15.5 grams of nitrogen and 19 grams of calcium per 100 grams, with verified complete solubility in irrigation water below 25 °C, supporting drip and ebb-flow systems.
Product Innovation in Construction and Material Science
Manufacturers explore new formulations that enhance concrete strength, reduce cracking, and improve environmental resistance. Calcium nitrate integration supports longer structural life and lower maintenance. Expanding infrastructure megaprojects and advanced building technologies create continuous demand for performance-driven additives.
- For instance, hardening admixtures utilize specialized chemical formulations to increase early compressive strength within the first day of curing when added at recommended dosage rates.
Key Challenges
Price Pressure and Raw Material Supply Constraints
The market faces cost fluctuations tied to variable raw material sourcing, transportation expenses, and production energy needs. Regional supply constraints and logistics challenges add risk to long-term planning. These dynamics influence fertilizer pricing and industrial cost structures, affecting margins.
Environmental and Regulatory Compliance Demands
Strict regulations on nitrogen discharge, fertilizer use, and chemical handling create compliance barriers, especially in agriculture and municipal treatment. Market participants must invest in process upgrades and environmental safeguards to meet evolving standards. This increases operating costs and slows market expansion in sensitive regions.
Regional Analysis
North America
North America holds 30% share, driven by strong fertilizer demand, industrial activity, and extensive construction projects. The region benefits from advanced farming systems, rising adoption of controlled nutrient delivery, and increasing use of calcium nitrate in vegetables, fruits, and greenhouse crops. Concrete accelerators support fast-paced infrastructure development and enhance material performance in colder climates. Wastewater treatment facilities continue expanding chemical dosing programs to improve odor control and nitrogen reduction. Established manufacturing networks ensure steady product availability and support long-term growth. Continued investment in sustainable agriculture and infrastructure strengthens calcium nitrate consumption across the region.
Europe
Europe accounts for 27% share, supported by advanced agricultural practices and strong environmental compliance standards. Farmers use calcium nitrate to enhance nitrogen efficiency, crop resilience, and soil health across intensive farming regions in countries such as Spain, Italy, and the Netherlands. Industrial and construction applications grow alongside infrastructure renewal, concrete reinforcement, and public works expansion. Wastewater treatment gains momentum as municipalities adopt chemical solutions to improve emission control and corrosion prevention. Sustainability policies encourage precision fertilization and low-impact materials, increasing product value. Strong supply chains and research capabilities further reinforce Europe’s competitive position.
Asia Pacific
Asia Pacific leads with 36% share, driven by high agricultural output, rapid urban development, and strong industrial expansion in China, India, Japan, and Southeast Asia. Farmers adopt calcium nitrate to support high-yield crops, reduce soil degradation, and improve nutrient efficiency across diverse climates. Construction activity fuels demand for concrete accelerators in residential, commercial, and infrastructure projects. Wastewater treatment continues to grow due to rising population density and stricter environmental regulations. Expanding chemical and mining industries add further value. Large domestic production capacity and competitive pricing position Asia Pacific as the primary global growth engine.
Latin America
Latin America holds 4% share, supported by agricultural development and rising fertilizer application across Brazil, Argentina, and Chile. The region focuses on crop productivity improvement, driven by export markets and expanding horticulture sectors. Calcium nitrate adoption grows in fruits, vegetables, and high-value crops, while construction projects and mining activity create additional industrial demand. Economic fluctuations and import reliance present challenges, yet modernization of farming systems and infrastructure investment provide long-term growth opportunities. Wastewater treatment and municipal upgrades also expand chemical usage. The region continues strengthening supply networks and agricultural practices.
Middle East & Africa
The Middle East & Africa account for 3% share, driven by expanding agricultural initiatives, construction projects, and industrial development. Countries invest in crop diversification and irrigation-supported farming, increasing fertilizer demand, particularly in calcium-rich soils. Infrastructure expansion and concrete durability requirements create consistent consumption across commercial and civil projects. Mining applications support explosives and blasting operations. Water treatment investments rise as urban populations grow and environmental standards strengthen. Market growth remains steady despite supply chain limitations and higher import dependence. Government programs supporting food security and industrial expansion will continue shaping demand across the region.
Calcium Nitrate Market Segmentations:
By Form
- Liquid
- Granular
- Powder
- Crystalline
By Application
- Fertilizers
- Concrete Manufacturing
- Wastewater Treatment
- Explosives
By End Use Industry
- Agriculture
- Construction
- Chemicals
- Mining
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The calcium nitrate market features strong competition among key players such as Yara International, Haifa Group, SQM, GFS Chemicals, Uralchem JSC, Shanxi Jiaocheng Tianlong Chemical, Rural Liquid Fertilisers, Sterling Chemicals, Prathista Industries, and Nitro Química. These companies drive growth through large-scale fertilizer production, distribution strength, and continuous product innovation. Market leaders focus on expanding agricultural-grade calcium nitrate portfolios to meet rising crop nutrition needs, supported by strong global supply chains. Construction and industrial applications also shape strategic positioning, with companies investing in high-performance concrete additives and environmentally compliant wastewater solutions. Partnerships, capacity expansion, and regional manufacturing investments improve market access and cost efficiency. Sustainability initiatives, including cleaner production processes and water-efficient agriculture programs, influence competitive advantage. With rising global fertilizer demand, leading suppliers continue strengthening their footprint through technology upgrades, product diversification, and value-added services tailored to modern farming and industrial requirements.
Key Player Analysis
- Yara International
- Haifa Group
- SQM (Sociedad Química y Minera de Chile)
- GFS Chemicals
- Uralchem JSC
- Shanxi Jiaocheng Tianlong Chemical
- Rural Liquid Fertilisers
- Sterling Chemicals
- Prathista Industries
- Nitro Química
Recent Developments
- In December 2025, Uralchem JSC was linked to a Russia urea JV with Indian firms.
- In February 2025, Haifa Group launched Haifa Soluble DUO in North West Europe.
Report Coverage
The research report offers an in-depth analysis based on Form, Application, End Use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise for high-performance fertilizers supporting crop quality and yield stability.
- Construction activity will boost the use of concrete accelerators in infrastructure expansion.
- Wastewater treatment applications will grow due to rising environmental compliance.
- Mining and explosives demand will increase with industrial and resource development.
- Precision agriculture will support higher adoption of liquid calcium nitrate.
- Asia Pacific will maintain leadership as farming and construction investments expand.
- Material and process innovation will improve product efficiency and sustainability.
- Producers will expand capacity to strengthen pricing control and supply reliability.
- Digital farming trends will support calcium nitrate usage in advanced crop systems.
- Strategic partnerships and trade expansion will enhance market reach and growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Calcium Nitrate market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Calcium Nitrate market projected to grow between 2024 and 2032?
Which Calcium Nitrate market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Calcium Nitrate market?
Who are the leading companies in the Calcium Nitrate market?
Which region commanded the largest share of the Calcium Nitrate market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14,113 million → 2032: USD 20,425.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Calcium Nitrate Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Calcium Nitrate Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Calcium Nitrate Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Calcium Nitrate Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Calcium Nitrate Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Calcium Nitrate Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Calcium Nitrate Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Calcium Nitrate Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14,113 million → 2032: USD 20,425.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Calcium Nitrate Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Calcium Nitrate Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Calcium Nitrate Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Calcium Nitrate Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

