
Market Overview
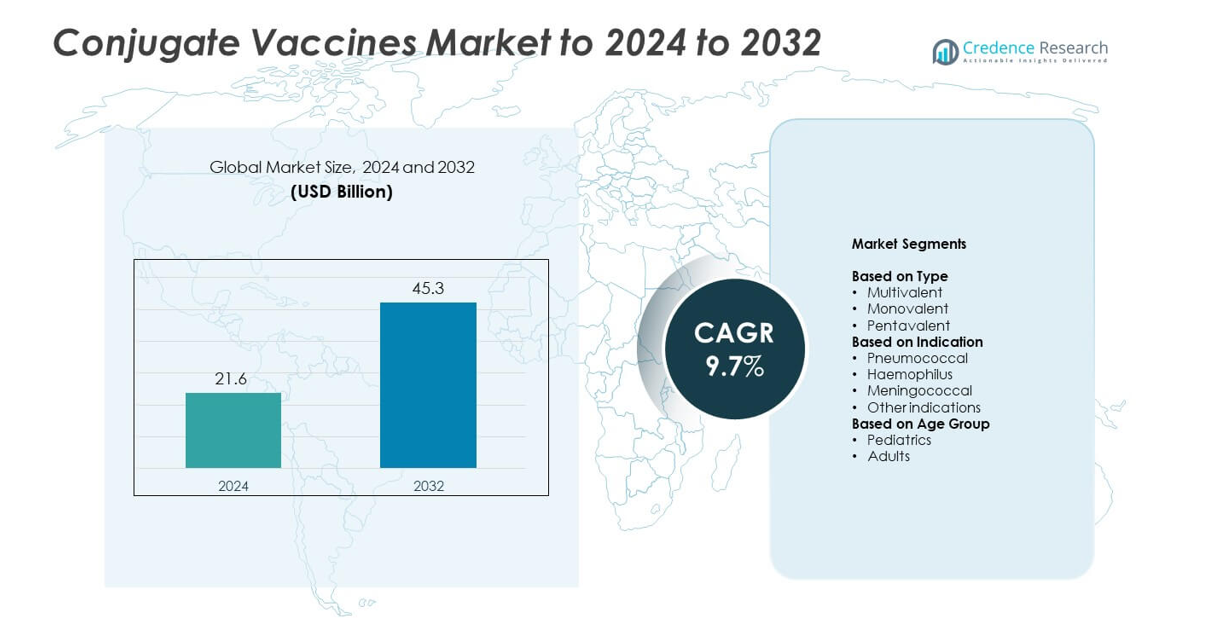
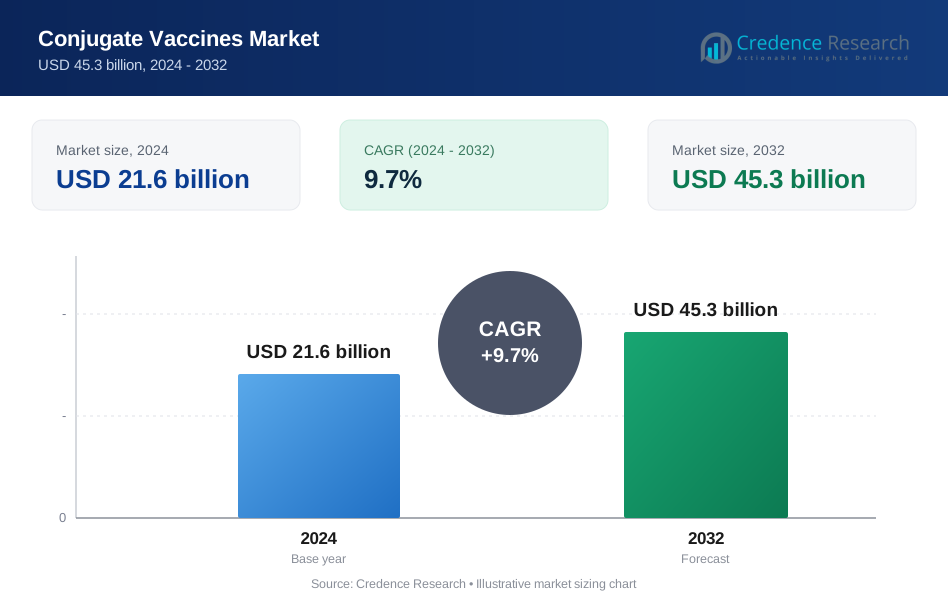
Conjugate Vaccines Market size was valued at USD 21.6 billion in 2024 and is anticipated to reach USD 45.3 billion by 2032, at a CAGR of 9.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Conjugate Vaccines Market Size 2024 | USD 21.6 billion |
| Conjugate Vaccines Market, CAGR | 9.7% |
| Conjugate Vaccines Market Size 2032 | USD 45.3 billion |
The Conjugate Vaccines Market is driven by leading companies such as Pfizer, Inc., Serum Institute of India Pvt. Ltd., GSK plc, Sanofi, Merck & Co., Inc., Novartis AG, CSL Limited, Bharat Biotech, Biological E. Ltd, Bavarian Nordic, Bio-Med, Taj Pharmaceuticals Ltd., and GSPBL. These manufacturers compete through expanded higher-valent formulations, large-scale immunization supply contracts, and strong global distribution networks. North America leads the market with about 41% share in 2024, supported by high vaccination uptake and strong healthcare infrastructure. Europe follows with nearly 30% share, driven by robust national immunization programs. Asia Pacific remains the fastest-growing region with around 20% share due to rising birth rates and expanding access to pediatric vaccines.
Market Insights
- The Conjugate Vaccines Market reached USD 21.6 billion in 2024 and is projected to hit USD 45.3 billion by 2032, growing at a CAGR of 9.7%.
- Strong market growth is driven by expanding national immunization programs and high demand for pneumococcal vaccines, which held about 52% share in 2024.
- Higher-valent vaccine development and rising adult vaccination awareness shape key trends, with Asia Pacific emerging as one of the fastest-growing regions.
- Competition remains intense as major manufacturers expand production capacity and focus on broader serotype coverage, while multivalent vaccines lead the type segment with nearly 58% share.
- North America leads with about 41% share, followed by Europe at nearly 30%, while Asia Pacific holds around 20% and continues to grow due to increasing pediatric vaccinations.
Market Segmentation Analysis:
By Type
Multivalent vaccines held the dominant share of about 58% in 2024. Their lead came from broad protection against multiple serogroups and strong use in national immunization programs. Healthcare agencies prefer multivalent products because they reduce the number of doses and improve compliance. Growing demand for expanded-coverage pneumococcal conjugate vaccines and wider adoption in both pediatric and adult groups support this segment. Monovalent and pentavalent vaccines grow at a steady pace as countries upgrade immunization schedules and expand disease-specific protection.
- For instance, Pfizer agreed to supply up to 740 million Prevenar 13 doses by 2025.
By Indication
Pneumococcal conjugate vaccines accounted for the largest share of nearly 52% in 2024. High prevalence of pneumococcal infections, strong government procurement, and routine pediatric immunization drive this dominance. Global health bodies continue to scale pneumococcal vaccination programs due to strong clinical efficacy and reduced hospitalization risk. Rising uptake of next-generation higher-valent pneumococcal products also strengthens this segment. Haemophilus and meningococcal vaccines expand as countries widen newborn and adolescent immunization coverage.
- For instance, GSK agreed to supply 720 million Synflorix doses by the mid-2020s.
By Age Group
Pediatrics led the market with about 61% share in 2024. Strong uptake of routine childhood vaccination, high inclusion of conjugate vaccines in national schedules, and large birth cohorts support this lead. Pediatric programs emphasize early protection against pneumococcal, meningococcal, and Haemophilus diseases, making conjugate vaccines a core part of immunization strategies. Adult vaccination grows steadily as awareness of pneumococcal disease risk rises and governments promote immunization for older adults and high-risk groups.
Key Growth Drivers
Rising Immunization Coverage
Global immunization programs continue to expand as governments strengthen vaccine mandates and invest in nationwide rollouts. Conjugate vaccines gain priority due to high effectiveness against pneumococcal, meningococcal, and Haemophilus infections. Strong support from public health agencies and international organizations boosts vaccine uptake across low and middle-income countries. Higher birth rates in developing regions and rapid improvements in healthcare access further contribute to consistent demand.
- For instance, Serum Institute of India currently produces around 1.9 billion vaccine doses annually as of 2023.
Advancements in Higher-Valent Vaccines
The shift toward higher-valent conjugate vaccines fuels rapid market expansion. Manufacturers develop vaccines offering broader serotype protection, which increases clinical value and strengthens adoption across pediatric and adult groups. Regulatory approvals for next-generation pneumococcal conjugate vaccines accelerate market penetration. These advanced formulations reduce disease burden more effectively, encouraging larger public procurement and wider inclusion in national immunization schedules.
- For instance, Merck's V116 pneumococcal conjugate vaccine covers 21 serotypes across eight Phase 3 studies.
Growing Adult Vaccination Awareness
Awareness of adult vulnerability to pneumococcal and meningococcal infections continues to rise. Health systems encourage adult immunization to reduce hospitalization risk among older adults and immunocompromised groups. This shift expands the target population beyond pediatrics, creating new revenue opportunities for manufacturers. Strong recommendations from public health authorities and employer-based vaccination programs further support adult-segment growth.
Key Trends & Opportunities
Expansion of National Immunization Programs
Many countries expand routine vaccination schedules by adding new conjugate vaccines and increasing coverage across underserved regions. Governments focus on reducing childhood and adult mortality linked to vaccine-preventable infections. Digital tracking tools and improved cold-chain networks enhance last-mile delivery. These developments create strong opportunities for long-term procurement partnerships and increased public-sector demand.
- For instance, AstraZeneca has delivered over 3 billion Vaxzevria doses to more than 180 countries.
R&D Focus on Combination Vaccines
Manufacturers invest in combination vaccines that reduce the number of injections and improve patient compliance. These products streamline immunization workflows and lower operational burden on healthcare systems. Combination conjugate vaccines gain interest due to enhanced convenience, reduced clinic visits, and stronger acceptance among parents and caregivers. Growing demand for efficient immunization strategies strengthens opportunities in this area.
- For instance, Takeda's QDENGA dengue vaccine has been studied in over 60,000 participants worldwide.
Improved Manufacturing Capacity
Global vaccine producers increase production capacity to support rising demand from both pediatric and adult markets. Investments in advanced bioprocessing, scalable fermentation systems, and fill-finish technologies help reduce supply gaps. Improved capacity ensures stable availability during outbreak seasons and supports large public tenders. This trend opens new opportunities for regional supply partnerships.
Key Challenges
High Development and Production Costs
Conjugate vaccines require complex manufacturing steps, including polysaccharide purification and protein conjugation, which raise production costs. These expenses limit participation by smaller manufacturers and reduce affordability in low-income regions. High clinical trial costs and stringent regulatory requirements further slow the entry of new products. As a result, pricing pressures and funding constraints remain major hurdles for broader market penetration.
Supply and Distribution Limitations
Many countries face gaps in cold-chain infrastructure and uneven healthcare access, which disrupt vaccine distribution. Remote regions experience delays in routine immunization, reducing coverage for key conjugate vaccines. Limited storage capacity and logistical challenges increase the risk of stockouts during high-demand periods. These constraints continue to affect timely vaccine delivery and hinder market growth.
Regional Analysis
North America
North America held about 41% share in 2024 due to strong immunization programs, high healthcare spending, and wide access to advanced conjugate vaccines. The region benefits from established vaccination infrastructure and strong uptake of pneumococcal and meningococcal vaccines among children and adults. Ongoing support from public health agencies and steady introduction of higher-valent products strengthen long-term demand. The presence of leading vaccine developers and consistent government procurement further maintains the region’s dominant position.
Europe
Europe accounted for nearly 30% share in 2024, supported by strong public health policies, high vaccination awareness, and widespread inclusion of conjugate vaccines in national immunization schedules. The region shows stable demand across both pediatric and adult groups, particularly for pneumococcal and meningococcal vaccines. Government-funded programs ensure high coverage rates, while ongoing R&D initiatives boost product availability. Expanded surveillance systems and strong regulatory oversight continue to support market growth across major European countries.
Asia Pacific
Asia Pacific held around 20% share in 2024 and is among the fastest-growing regions due to rising birth rates, improving healthcare access, and growing government investments in vaccination programs. Countries expand national immunization schedules to include more conjugate vaccines for newborns and high-risk populations. Increasing awareness of disease burden and wider adoption of higher-valent vaccines strengthen market traction. Rapid urbanization and growing private healthcare networks also support higher vaccine uptake across the region.
Latin America
Latin America captured nearly 6% share in 2024, driven by expanding childhood immunization programs and support from regional health organizations. Several countries improve vaccine accessibility through public procurement and partnerships with global health agencies. Rising awareness of pneumococcal and meningococcal infections encourages broader coverage in infants and adolescents. Economic constraints and supply chain gaps remain challenges, but continued investments in healthcare systems support gradual market expansion across the region.
Middle East and Africa
The Middle East and Africa region held about 3% share in 2024, reflecting limited but growing adoption of conjugate vaccines. Immunization efforts strengthen through government-led initiatives and international funding aimed at reducing vaccine-preventable diseases. Expanding pediatric vaccination coverage and improved distribution networks support incremental progress. However, uneven healthcare access and supply challenges slow widespread uptake. Ongoing collaborations with global health bodies and rising awareness of infectious disease risks help create long-term growth potential.
Market Segmentations:
By Type
- Multivalent
- Monovalent
- Pentavalent
By Indication
- Pneumococcal
- Haemophilus
- Meningococcal
- Other indications
By Age Group
- Pediatrics
- Adults
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Conjugate Vaccines Market is shaped by leading companies such as Pfizer, Inc., Taj Pharmaceuticals Ltd., Serum Institute of India Pvt. Ltd., GSK plc, Bavarian Nordic, Merck & Co., Inc., CSL Limited, Novartis AG, Bharat Biotech, Sanofi, Biological E. Ltd, Bio-Med, and GSPBL. The market features strong competition driven by continuous product innovation, expansion of higher-valent formulations, and large-scale supply commitments to national immunization programs. Manufacturers focus on scaling production capacity, improving conjugation technologies, and enhancing global distribution reach, especially across developing regions. Strategic partnerships with public health agencies and advancements in clinical programs strengthen market positioning. Companies also prioritize regulatory approvals and competitive pricing to secure government tenders. Rising demand across pediatric and adult vaccination segments pushes firms to expand research pipelines and upgrade manufacturing infrastructure. The competition further intensifies with growing interest in combination vaccines and broader serotype coverage.
Key Player Analysis
- Pfizer, Inc.
- Taj Pharmaceuticals Ltd.
- Serum Institute of India Pvt. Ltd.
- GSK plc
- Bavarian Nordic
- Merck & Co., Inc.
- CSL Limited
- Novartis AG
- Bharat Biotech
- Sanofi
- Biological E. Ltd
- Bio-Med
- GSPBL
Recent Developments
- In 2025, Biological E. Ltd has entered a strategic partnership with Bavarian Nordic to expand access to Bavarian Nordic's Chikungunya vaccine, including technology transfer to Biological E's facilities for local manufacturing intended for low- and middle-income countries.
- In 2025, Merck & Co., Inc. received European Commission approval for CAPVAXIVE®, a 21-valent pneumococcal conjugate vaccine aimed at preventing invasive pneumococcal disease and pneumonia in adults
- In 2024, Sanofi, in collaboration with SK Bioscience, launched a Phase III clinical trial program for PCV21, a pneumococcal conjugate vaccine candidate covering more than 20 serotypes.
Report Coverage
The research report offers an in-depth analysis based on Type, Indication, Age Group and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Higher-valent conjugate vaccines will gain wider adoption across all age groups.
- National immunization programs will expand coverage for pneumococcal and meningococcal vaccines.
- Adult vaccination rates will rise as awareness of infection risks increases.
- Manufacturers will invest more in combination conjugate vaccines for better compliance.
- Global production capacity will grow to support stable supply and reduce shortages.
- New regulatory approvals will accelerate the entry of advanced conjugate formulations.
- Digital tracking tools will enhance vaccine delivery and improve coverage in remote areas.
- Public–private partnerships will expand to support immunization in low-income regions.
- R&D will focus on broader serotype protection and improved immunogenicity.
- Market competition will intensify as more firms enter emerging economies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Conjugate Vaccines Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Conjugate Vaccines Market projected to grow between 2025 and 2032?
Who are the major players in the global Conjugate Vaccines Market?
What are the major market drivers of the Conjugate Vaccines industry?
What are the major market restraints of the Conjugate Vaccines industry?
What are the major market opportunities of the Conjugate Vaccines industry?
Who are the leading companies in the Conjugate Vaccines Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Conjugate Vaccines Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Conjugate Vaccines Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 21.6 billion → 2032: USD 45.3 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Conjugate Vaccines Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Conjugate Vaccines Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Conjugate Vaccines Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Conjugate Vaccines Market Drivers
- 3.3 Conjugate Vaccines Market Restraints & Challenges
- 3.4 Conjugate Vaccines Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Conjugate Vaccines Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Conjugate Vaccines Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Conjugate Vaccines category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Conjugate Vaccines Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Conjugate Vaccines Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Conjugate Vaccines. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Conjugate Vaccines Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Conjugate Vaccines Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Conjugate Vaccines Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Conjugate Vaccines (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Conjugate Vaccines
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Conjugate Vaccines Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Conjugate Vaccines Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Conjugate Vaccines Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Conjugate Vaccines Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Conjugate Vaccines Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Conjugate Vaccines Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Conjugate Vaccines Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Conjugate Vaccines Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
