
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| France Data Center Renovation Market Size 2024 | USD 745.85 Million |
| France Data Center Renovation Market, CAGR | 12.99% |
| France Data Center Renovation Market Size 2032 | USD 1,981.67 Million |
Market Overview
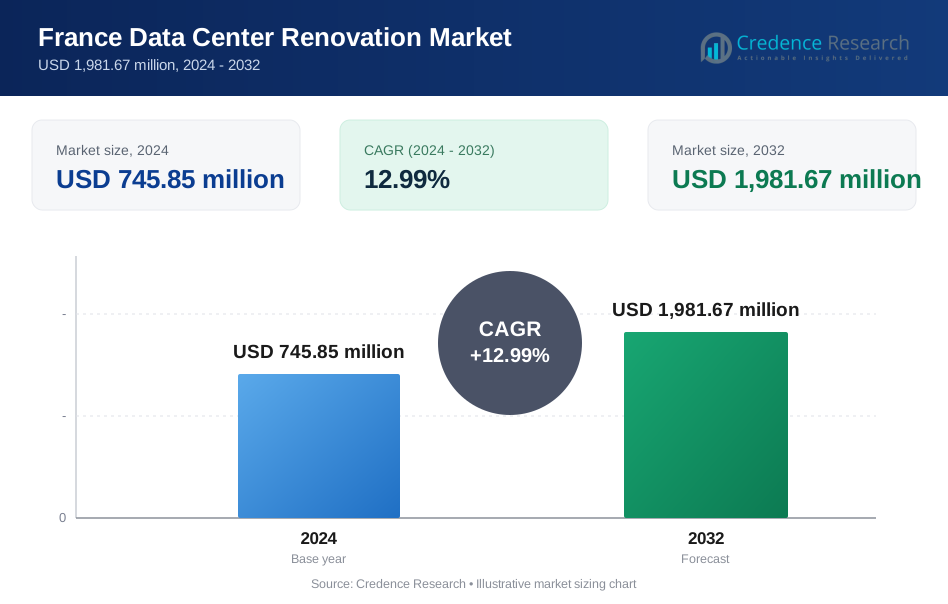
France Data Center Renovation Market size was valued at USD 745.85 million in 2024 and is anticipated to reach USD 1,981.67 million by 2032, at a CAGR of 12.99% during the forecast period (2024-2032).
The France Data Center Renovation Market is experiencing significant growth due to increasing demand for energy-efficient infrastructure, sustainability initiatives, and enhanced data security requirements. Enterprises and colocation providers are modernizing aging facilities to optimize power consumption, cooling efficiency, and operational reliability. The rise of cloud computing, edge data centers, and AI-driven workloads is further driving the need for infrastructure upgrades. Additionally, stringent EU energy regulations and France’s commitment to carbon neutrality are pushing operators toward green data center solutions. The growing adoption of modular and prefabricated components accelerates renovation timelines while ensuring cost-effectiveness. Trends such as liquid cooling, automation, and hybrid cloud integration are reshaping renovation strategies. The surge in IoT devices, 5G deployment, and increasing data traffic necessitates continuous infrastructure enhancement. As businesses prioritize resilience, scalability, and compliance, the market is set to witness sustained investments in innovative and future-ready data center solutions.
France's data center renovation market is witnessing significant growth across key regions, driven by rising digital transformation initiatives, sustainability mandates, and increasing demand for high-performance computing. Northern France, with its strong industrial base and connectivity to major European hubs, remains a focal point for modernization projects. Southern France is gaining traction due to its renewable energy resources and expanding IT infrastructure, while Eastern and Western France are seeing investments in high-density computing and colocation services. Leading industry players, including Hewlett Packard Enterprise, Schneider Electric, Cisco Systems, IBM, and Microsoft, are actively contributing to the market with advanced renovation solutions. These companies focus on integrating AI-driven automation, liquid cooling technologies, and energy-efficient infrastructure upgrades to meet evolving industry needs. Additionally, increasing partnerships between technology firms and data center operators are fostering innovative solutions that enhance operational efficiency and sustainability. The market is poised for continued expansion, driven by regulatory policies and rapid advancements in cloud computing and AI.
Market Insights
- The France Data Center Renovation market was valued at USD 745.85 million in 2024 and is expected to reach USD 1,981.67 million by 2032, growing at a CAGR of 12.99% from 2024 to 2032.
- Increasing demand for energy-efficient and sustainable data centers is driving renovations, with companies focusing on upgrading cooling systems, power management, and automation technologies.
- The adoption of AI, cloud computing, and edge computing is influencing renovation strategies, prompting businesses to modernize infrastructure for better efficiency and scalability.
- Key players such as Hewlett Packard Enterprise, Schneider Electric, Cisco Systems, and Microsoft are investing in advanced renovation solutions, fostering market competition.
- High initial costs and technical complexities in upgrading existing data center infrastructure pose challenges to market growth.
- Northern France and Southern France are leading regions for data center renovations, driven by strong IT investments and renewable energy adoption.
- The market is expected to see continued expansion due to strict regulatory policies, digital transformation initiatives, and advancements in AI-driven data center operations.
Market Drivers
Expanding Digital Transformation and Cloud Adoption
The rapid growth of digital transformation initiatives across various industries is fueling the need for modernized data center infrastructure. Enterprises are increasingly migrating to cloud-based solutions, deploying AI-driven applications, and integrating IoT devices, necessitating scalable and high-performance data centers. For instance, France has undertaken a number of initiatives to accelerate digital transformation, including providing digital tools and services for businesses. According to new economic modeling, achieving the EU’s Digital Decade agenda could unlock over €488 billion in economic value for France. As data volumes surge, companies seek hybrid cloud architectures that demand renovated facilities with improved connectivity, storage, and processing power. The increasing adoption of Software-Defined Data Centers (SDDCs) and edge computing also necessitates upgrading legacy infrastructure. Moreover, France’s push toward smart cities and digital government services further accelerates data center modernization efforts, ensuring enhanced data security, availability, and operational efficiency.
Stringent Regulatory Compliance and Security Concerns
France’s stringent data protection laws and cybersecurity regulations are compelling data center operators to invest in infrastructure upgrades. The implementation of GDPR and evolving cybersecurity threats have heightened the focus on data privacy, secure networks, and resilient IT infrastructure. For instance, under Article 22 of the law, vitally important operators must report incidents detected on their IT systems to the relevant authorities. Renovation projects often include the deployment of advanced fire suppression systems, biometric security, and AI-powered threat detection solutions to mitigate security risks. Additionally, data centers must comply with ISO 27001 and other industry-specific certifications, which necessitate periodic upgrades in network security, physical security, and redundancy measures. The increasing risk of cyberattacks and data breaches further underscores the need for renovation efforts that enhance data protection and business continuity.
Rising Demand for Energy-Efficient and Sustainable Infrastructure
The growing emphasis on energy efficiency and sustainability is a key driver for the France Data Center Renovation Market. Data centers consume substantial amounts of power, prompting operators to adopt energy-efficient cooling systems, advanced power management solutions, and renewable energy sources. France’s commitment to carbon neutrality by 2050 and compliance with EU energy efficiency regulations are pushing data center operators to modernize outdated infrastructure. Liquid cooling technologies, efficient HVAC systems, and AI-driven energy optimization are becoming integral to renovation strategies. Additionally, government incentives for green data centers encourage businesses to invest in renovations that reduce carbon footprints and operational costs while ensuring compliance with evolving environmental standards.
Rising Adoption of High-Density Computing and Automation
The shift towards high-density computing, AI, and automation is reshaping the France Data Center Renovation Market. As businesses deploy AI-driven analytics, machine learning, and big data applications, they require higher computing power and optimized cooling solutions. This trend is driving renovations that incorporate liquid cooling, intelligent airflow management, and high-capacity power distribution. Furthermore, automation technologies such as robotic process automation (RPA), AI-driven monitoring, and predictive maintenance are enhancing data center efficiency, reducing downtime, and improving overall operational resilience. Renovation strategies now focus on integrating smart management systems that enable real-time monitoring of power usage, temperature fluctuations, and equipment performance, ensuring improved energy efficiency and operational agility.
Market Trends
Growing Emphasis on Green and Sustainable Renovations
The increasing focus on energy efficiency and environmental sustainability is driving data center renovations across France. Operators are integrating renewable energy sources, advanced cooling techniques, and AI-driven energy management systems to minimize power consumption and carbon emissions. Liquid cooling solutions, free-air cooling, and heat reuse technologies are gaining traction, helping data centers comply with EU energy efficiency directives and France’s carbon neutrality goals. For instance, a local government in Lorient, France, introduced an innovative eco-friendly containerized network infrastructure center that utilizes recycled materials, free cooling systems, on-site solar power generation, and rainwater collection. Additionally, the adoption of sustainable building materials and modular designs allows for cost-effective renovations while reducing environmental impact. As businesses and regulatory bodies push for eco-friendly data centers, investment in green certifications and sustainable infrastructure upgrades continues to rise.
Increased Adoption of Automation and AI-Driven Operations
Automation and AI-powered data center management are becoming integral to renovation strategies, enhancing operational efficiency and reducing human intervention. Operators are leveraging AI and machine learning algorithms for predictive maintenance, real-time monitoring, and intelligent resource allocation. Automated cooling optimization, power distribution, and network traffic management are helping data centers reduce downtime and optimize performance. Additionally, robotic process automation (RPA) is streamlining routine tasks such as server maintenance, security checks, and inventory management, allowing IT teams to focus on higher-value operations. The increasing integration of AI-driven infrastructure monitoring ensures improved reliability, security, and cost efficiency in modernized data centers.
Rising Demand for Hybrid and Edge Data Centers
The growing adoption of hybrid cloud models and edge computing is influencing renovation strategies in France’s data center market. Businesses require scalable, high-performance infrastructure that supports cloud-native applications, AI workloads, and real-time data processing. As a result, data centers are upgrading network capabilities, storage solutions, and computing power to accommodate hybrid cloud environments. Additionally, the rise of 5G, IoT, and real-time analytics is increasing demand for edge data centers, necessitating renovations that enhance latency reduction, localized data processing, and decentralized network architectures. Companies investing in edge-ready renovations can ensure faster, more reliable data access while reducing operational costs associated with centralized facilities.
Enhanced Security and Compliance Measures
As cyber threats evolve, data security and regulatory compliance are major drivers of renovation projects. Organizations are upgrading security systems with advanced encryption, multi-factor authentication, and biometric access controls to mitigate risks. For instance, a new cybersecurity center was launched by the French government in Paris. The implementation of GDPR and strict data sovereignty laws in France requires data centers to adopt stronger compliance measures, including network segmentation, real-time threat detection, and improved disaster recovery solutions. Additionally, operators are investing in fire-resistant enclosures, AI-powered cybersecurity frameworks, and automated risk management tools to enhance physical and digital security. Renovation efforts focused on security enhancements are crucial for maintaining regulatory compliance and protecting sensitive business data in an increasingly cyber-vulnerable landscape.
Market Challenges Analysis
High Renovation Costs and Complex Implementation
The France Data Center Renovation Market faces significant challenges due to the high costs associated with infrastructure upgrades and complex implementation processes. Renovating existing data centers requires substantial investment in energy-efficient cooling systems, security enhancements, and automation technologies, making it financially burdensome for small and mid-sized operators. For instance, construction costs for a data center in Europe increased by 6.5%, reaching an average of $9.1 million per MW. Additionally, integrating new-age solutions while ensuring minimal disruption to ongoing operations poses logistical difficulties. Upgrading legacy infrastructure to support hybrid cloud environments, AI-driven automation, and edge computing often necessitates specialized expertise and extended project timelines. Moreover, businesses must navigate compatibility issues between old and new systems, increasing operational risks and downtime. These challenges demand strategic planning, phased upgrades, and advanced project management to balance cost-efficiency and technological advancements in data center renovation efforts.
Stringent Regulatory Compliance and Sustainability Pressures
Compliance with strict data security regulations, energy efficiency mandates, and sustainability targets adds complexity to renovation projects. France’s adherence to GDPR, ISO 27001, and EU-wide energy directives requires data centers to implement advanced cybersecurity measures, reduce carbon emissions, and adopt sustainable practices. Ensuring compliance involves retrofitting infrastructure with high-security access controls, AI-driven threat detection systems, and eco-friendly power solutions, which can be both costly and resource-intensive. Additionally, meeting sustainability goals demands a transition to renewable energy sources, liquid cooling systems, and heat reuse technologies, which may not be feasible for all data center operators. Failure to comply with environmental and security standards can lead to penalties, reputational damage, and operational inefficiencies. Overcoming these regulatory and sustainability hurdles requires a proactive approach, continuous innovation, and collaboration with industry experts to future-proof data center infrastructure while maintaining cost-effectiveness and compliance.
Market Opportunities
The France Data Center Renovation Market presents significant growth opportunities driven by the rising demand for energy-efficient and sustainable infrastructure. With increasing regulatory pressure to reduce carbon footprints and improve energy efficiency, data center operators can invest in green technologies, such as liquid cooling systems, renewable energy integration, and AI-powered energy management solutions. Government incentives and tax benefits for eco-friendly renovations further encourage businesses to modernize their facilities while reducing operational costs. Additionally, the growing adoption of modular and prefabricated components enables faster and more cost-effective renovations, providing a competitive edge to operators who prioritize scalability and environmental responsibility. As sustainability remains a key focus, companies that proactively adopt low-carbon infrastructure and circular economy practices will benefit from enhanced market positioning and long-term profitability.
The increasing reliance on cloud computing, AI-driven workloads, and edge computing offers additional opportunities for data center renovations in France. Organizations are upgrading their infrastructure to support hybrid cloud environments, 5G networks, and real-time data processing, driving demand for enhanced connectivity, high-performance computing, and automated management systems. The rapid digital transformation across industries, including finance, healthcare, and e-commerce, further fuels the need for resilient, secure, and scalable data centers. Additionally, rising cybersecurity threats and stricter data protection regulations create opportunities for operators to invest in advanced security measures, AI-driven threat detection, and biometric access controls. Companies that prioritize future-proofing their data centers with high-density computing capabilities, automation, and compliance-driven upgrades will gain a competitive advantage, ensuring long-term growth in an evolving digital landscape.
Market Segmentation Analysis:
By Renovation Type:
The France Data Center Renovation Market is segmented into mechanical renovation, electrical renovation, and infrastructure renovation, each playing a crucial role in optimizing operational efficiency. Mechanical renovation focuses on upgrading cooling systems, HVAC solutions, and airflow management to enhance energy efficiency and prevent overheating in high-density environments. The growing adoption of liquid cooling, free-air cooling, and AI-driven thermal management is driving investment in mechanical upgrades. Electrical renovation involves modernizing power distribution units (PDUs), uninterruptible power supplies (UPS), and energy storage solutions to improve reliability and minimize downtime. The shift toward renewable energy integration and smart grid technologies is further accelerating demand for electrical renovations. Infrastructure renovation encompasses structural enhancements, such as modular expansions, seismic retrofitting, and advanced fire suppression systems, ensuring compliance with evolving safety regulations. As data centers prioritize scalability, resilience, and sustainability, investments in these renovation types are expected to grow significantly, aligning with France’s energy efficiency mandates and digital transformation initiatives.
By Renovation Goal:
Data center renovation efforts in France are primarily driven by three key objectives: improved energy efficiency, increased capacity and density, and modernization and upgrading. The focus on improved energy efficiency stems from stringent EU energy regulations, carbon neutrality targets, and rising operational costs, prompting operators to adopt AI-powered energy management systems, high-efficiency cooling, and renewable energy solutions. The need for increased capacity and density is fueled by growing data traffic, AI-driven workloads, and the expansion of cloud services, leading businesses to implement high-density server racks, advanced cooling mechanisms, and optimized space utilization. Lastly, modernization and upgrading efforts aim to replace outdated IT infrastructure, enhance cybersecurity measures, and integrate automation technologies, ensuring data centers remain competitive, secure, and future-ready. As digital transformation accelerates across industries, renovation strategies focusing on sustainability, scalability, and operational resilience will drive market growth, positioning France as a leader in energy-efficient and high-performance data centers.
Segments:
Based on Renovation Type:
- Mechanical Renovation
- Electrical Renovation
- Infrastructure Renovation
Based on Renovation Goal:
- Improved Energy Efficiency
- Increased Capacity and Density
- Modernization and Upgrading
Based on Component:
- Cooling Systems
- Power Systems
- Racks and Enclosures
- Security Systems
Based on Age:
- 0-5 Years
- 6-10 Years
- 11-15 Years
- 16-20 Years
- Over 20 Years
Based on the Geography:
- Northern France
- Southern France
- Eastern France
- Western France
Regional Analysis
Northern France
Northern France holds the largest market share of approximately 35% in the France Data Center Renovation Market, driven by its strong industrial base, dense population centers, and proximity to major European data hubs. The presence of key cities like Paris and Lille, along with extensive fiber-optic networks and energy infrastructure, makes the region a prime location for data center investments and renovations. Operators in Northern France are focusing on energy-efficient cooling solutions, hybrid cloud integrations, and advanced automation technologies to enhance data center performance and sustainability. Additionally, strict environmental regulations and France’s commitment to carbon neutrality are encouraging businesses to upgrade legacy infrastructure with AI-driven energy management systems and renewable energy sources. As a result, the region continues to attract large-scale renovation projects from hyperscale cloud providers and colocation service providers seeking to modernize their data processing and storage capabilities.
Southern France
Southern France accounts for around 25% of the market share, fueled by the increasing adoption of green data center solutions and demand for enhanced digital infrastructure. Cities like Marseille and Toulouse have become strategic hubs due to their growing IT and telecommunications sectors, attracting data center operators looking to expand their presence. The region benefits from strong renewable energy sources, including solar and wind power, which align with the industry’s push toward sustainable renovations. Data centers in Southern France are heavily investing in solar-powered cooling systems, high-density energy storage, and AI-powered operational efficiency enhancements. Additionally, the rise of edge computing and 5G deployments is prompting businesses to renovate their facilities to accommodate low-latency processing and hybrid cloud architectures. With government incentives and rising enterprise adoption of cloud-based services, Southern France is poised for steady growth in data center renovation initiatives.
Eastern France
Eastern France holds approximately 20% of the market share, driven by the need for increased computing power and improved disaster recovery capabilities. The region is witnessing an influx of investment in high-density server deployments, upgraded cooling technologies, and AI-driven automation to accommodate growing data storage and processing requirements. Additionally, businesses in Eastern France are focusing on resilient data center infrastructures, incorporating seismic reinforcements, advanced fire suppression systems, and enhanced cybersecurity measures. The strategic location near Switzerland and Germany makes the region an attractive cross-border data processing hub, encouraging international businesses to invest in renovations. As demand for hybrid cloud and AI-driven data analytics continues to rise, Eastern France is expected to experience a steady increase in renovation activities, ensuring long-term market expansion.
Western France
Western France accounts for approximately 20% of the market share, driven by expanding colocation services, smart city initiatives, and increasing reliance on cloud computing. The region is seeing significant investments in infrastructure modernization, including modular data center expansions, enhanced security frameworks, and liquid cooling technologies. Cities like Nantes and Rennes are focusing on upgrading existing data centers with automation-driven energy management solutions to improve efficiency and sustainability. Additionally, the rise of AI, IoT, and big data applications is pushing businesses to enhance their network connectivity, storage capacities, and processing power. With strong government support for digital transformation projects, Western France is set to witness consistent growth in data center renovation activities, solidifying its position as an emerging hub for advanced IT infrastructure and cloud-based services.
Key Player Analysis
- Hewlett Packard Enterprise
- Emerson Electric
- Eaton
- ABB
- Honeywell
- Cisco Systems
- Dell Technologies
- Lenovo
- Schneider Electric
- Microsoft
- Siemens
- IBM
- Vertiv
- Johnson Controls
Competitive Analysis
The France Data Center Renovation market is highly competitive, with key players such as Hewlett Packard Enterprise, Schneider Electric, Cisco Systems, IBM, Microsoft, Emerson Electric, Eaton, ABB, Honeywell, Dell Technologies, Lenovo, Siemens, Google, Vertiv, and Johnson Controls driving innovation and expansion. These companies are focusing on integrating advanced technologies such as AI-driven automation, liquid cooling, and energy-efficient power management to enhance data center operations. Leading firms are actively investing in R&D to develop sustainable solutions, ensuring compliance with evolving energy regulations and environmental standards. Partnerships and acquisitions are common strategies among these players to strengthen their market presence and expand service offerings. For instance, France is the third largest ICT market in Europe and a growth market for high-tech and innovative companies with the highest number of science graduates in Europe and many of the international top company's R&D centers located here. Additionally, companies are leveraging hybrid cloud and edge computing advancements to modernize aging infrastructures and meet the rising demand for high-performance computing. The competitive landscape remains dynamic, with increasing investments in smart data center solutions and strong collaborations with regional enterprises to drive growth and technological advancements.
Recent Developments
- In December 2024, Microsoft announced the completion of construction on three Azure availability zones in Saudi Arabia, with availability expected in 2026. These zones are part of Microsoft's ongoing investments in the Kingdom, focusing on providing highly secure and globally trusted cloud services to governments and key industries.
- In October 2024, Johnson Controls announced its participation in Data Centre World Asia 2024, where it will showcase its integrated solutions for smarter, safer, and more resilient data center operations. The company aims to highlight its commitment to sustainable infrastructure and advanced technology.
- In October 2024, Dell's founder and CEO, Michael Dell, predicted that data center capacity will need to increase by 100 times over the next 10 years due to the rising demand for AI services.
- In June 2024, Schneider Electric opened a new 105,000-square-foot integration facility in Red Oak, Texas, designed to build pre-engineered and prefabricated IT infrastructure to meet the growing demand for data centers in the U.S. This facility will accelerate the production of integrated modular data center solutions, reducing production costs and expediting delivery.
- In May 2024, Dell Technologies unveiled enhancements to its Dell AI Factory, combining its XE 9680 with direct liquid cooling to support AI workloads. The company also introduced new storage capabilities with PowerStore 4.0, offering greater efficiency and better speeds.
Market Concentration & Characteristics
The France Data Center Renovation market exhibits a moderately high level of market concentration, with a mix of global technology leaders and specialized regional players driving competition. Established companies such as Hewlett Packard Enterprise, Schneider Electric, Cisco Systems, and Microsoft dominate the market, leveraging their extensive portfolios, strong R&D capabilities, and strategic partnerships to deliver advanced renovation solutions. The market is characterized by a strong focus on energy efficiency, automation, and sustainability, as data center operators seek to modernize infrastructure while reducing operational costs and carbon footprints. Increasing demand for AI-driven solutions, modular data center upgrades, and hybrid cloud integration is shaping the competitive landscape. Additionally, regulatory policies and sustainability mandates are influencing renovation strategies, compelling companies to adopt innovative cooling and power management technologies. As digital transformation accelerates, the market is expected to witness further consolidation, with key players expanding their service offerings to address evolving industry demands.
Report Coverage
The research report offers an in-depth analysis based on Renovation Type, Renovation Goal, Component, Age and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The France Data Center Renovation market will continue to grow, driven by increasing digital transformation and cloud adoption.
- Energy efficiency and sustainability initiatives will remain a top priority, encouraging investments in eco-friendly cooling and power solutions.
- AI and automation technologies will play a crucial role in optimizing data center operations and reducing downtime.
- The adoption of modular and scalable infrastructure will increase, enabling faster and more cost-effective renovations.
- Rising demand for edge computing will drive the need for localized and efficient data processing capabilities.
- Companies will focus on enhancing cybersecurity measures to protect renovated data centers from evolving threats.
- Hybrid cloud integration will continue to influence renovation strategies, allowing businesses to balance flexibility and performance.
- Government regulations and carbon neutrality goals will push data center operators toward greener infrastructure upgrades.
- The competitive landscape will see increased mergers, acquisitions, and strategic collaborations to expand market presence.
- Advancements in liquid cooling and high-density computing solutions will redefine data center renovation trends.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the France Data Center Renovation Market?
What factors are driving the growth of the France Data Center Renovation Market?
What are the key segments within the France Data Center Renovation Market?
What are some challenges faced by the France Data Center Renovation Market?
Who are the major players in the France Data Center Renovation Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 France Data Center Renovation Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global France Data Center Renovation Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 745.85 million → 2032: USD 1,981.67 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 France Data Center Renovation Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. France Data Center Renovation Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 France Data Center Renovation Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 France Data Center Renovation Market Drivers
- 3.3 France Data Center Renovation Market Restraints & Challenges
- 3.4 France Data Center Renovation Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 France Data Center Renovation Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 France Data Center Renovation Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, France Data Center Renovation category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 France Data Center Renovation Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. France Data Center Renovation Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the France Data Center Renovation market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 France Data Center Renovation Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 France Data Center Renovation Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 France Data Center Renovation Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in France Data Center Renovation (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New France Data Center Renovation Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global France Data Center Renovation Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America France Data Center Renovation Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe France Data Center Renovation Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific France Data Center Renovation Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America France Data Center Renovation Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East France Data Center Renovation Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa France Data Center Renovation Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. France Data Center Renovation Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
