
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
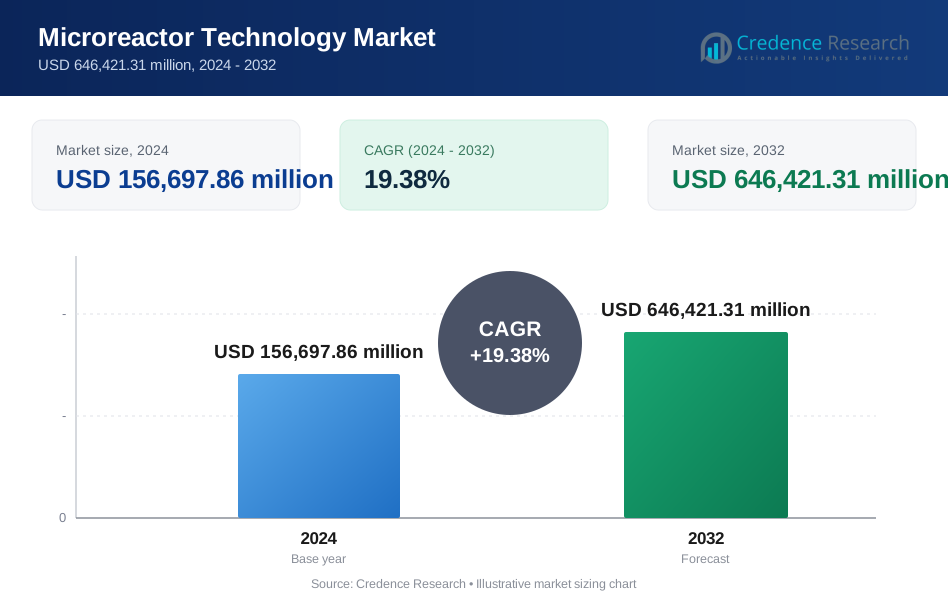
| Microreactor Technology Market Size 2024 | USD 156,697.86 million |
| Microreactor Technology Market, CAGR | 19.38% |
| Microreactor Technology Market Size 2032 | USD 646,421.31 million |
Market Overview:
The Microreactor Technology Market is expected to grow significantly, increasing from USD 156,697.86 million in 2024 to USD 646,421.31 million by 2032, at a compound annual growth rate (CAGR) of 19.38%.
The Microreactor Technology Market is driven by the growing demand for clean and efficient energy solutions, particularly in remote and off-grid locations. The increasing need for sustainable power sources in industries such as mining, defense, and space exploration is accelerating market growth. Technological advancements, such as the development of compact, portable, and cost-effective microreactors, are further fueling this demand. Additionally, government initiatives to support clean energy transitions and reduce carbon footprints are creating a favorable regulatory environment. The rise in investments from private and public sectors in nuclear energy innovation is also a significant trend, driving the adoption of microreactor technology. Furthermore, the growing focus on energy security and the ability to deploy microreactors in isolated areas without reliance on traditional infrastructure is enhancing their appeal. As global energy needs evolve, microreactors are poised to play a crucial role in meeting energy demands efficiently and sustainably.
The Microreactor Technology Market is geographically dominated by North America, which holds the largest market share, driven by strong governmental support and advanced nuclear technologies. Europe follows, with countries like the UK and France leading nuclear innovation, contributing to a substantial share of the market. The Asia-Pacific region is experiencing rapid growth, especially in China and Japan, where investments in nuclear energy are increasing to meet rising energy demands. The rest of the world, including Latin America, the Middle East, and Africa, holds a smaller share but shows growing interest in microreactors for remote energy solutions. Key players such as Corning, Chemtrix, Ehrfeld Mikrotechnik BTS, and Syrris are at the forefront of innovation across these regions, focusing on product advancements and strategic expansions to cater to the evolving energy landscape.
Market Insights:
- The Microreactor Technology Market is forecasted to grow from USD 156,697.86 million in 2024 to USD 646,421.31 million by 2032, with a CAGR of 19.38%.
- Growing demand for clean, efficient energy solutions, particularly in remote and off-grid locations, is a key driver of market expansion.
- Technological advancements, such as the development of compact, portable, and cost-effective microreactors, are fueling demand across industries like mining, defense, and space exploration.
- Supportive government policies, clean energy initiatives, and regulatory frameworks are creating a favorable environment for microreactor technology.
- Increased private and public investments in nuclear energy innovation are accelerating market growth and microreactor adoption.
- North America holds the largest market share, followed by Europe, while Asia-Pacific is experiencing rapid growth due to rising investments in nuclear energy.
- The ability to deploy microreactors in isolated areas, ensuring energy security without reliance on traditional infrastructure, is enhancing their global appeal.
Market Drivers:
Rising Demand for Clean Energy Solutions:
The increasing global emphasis on reducing carbon emissions and transitioning to sustainable energy sources is a key driver of the Microreactor Technology Market. Governments, businesses, and consumers are prioritizing clean energy solutions to address environmental challenges. For instance, the U.S. Department of Defense has initiated projects to deploy microreactors for powering remote military bases, ensuring reliable and low-carbon energy supply. Microreactors, with their ability to produce clean, low-carbon energy, are becoming an attractive alternative to traditional fossil fuel-based power generation. Their compact size and ability to generate power in remote or off-grid locations make them highly valuable for industries seeking sustainable energy solutions without relying on large-scale infrastructure.
Technological Advancements in Nuclear Energy:
Advancements in nuclear technology have made microreactors more feasible and appealing. Innovations in reactor design, safety features, and fuel efficiency have enabled the development of smaller, more cost-effective reactors that can be deployed in diverse environments. These technological improvements have significantly reduced the cost and complexity of building and operating microreactors, thus broadening their potential market applications. As a result, microreactor technology is gaining traction across industries that require reliable, scalable, and low-emission energy sources.
Supportive Government Policies and Regulations:
Government support for clean energy technologies, including microreactors, is a significant driver of market growth. Many countries have introduced policies and incentives to promote nuclear energy as part of their energy transition plans. These initiatives often include funding for research and development, regulatory streamlining, and investment in infrastructure. By creating a favorable regulatory environment, governments are encouraging private-sector participation in the development and commercialization of microreactors, further accelerating their adoption.
Growing Need for Energy Security and Independence:
Microreactors offer a viable solution to the growing demand for energy security, particularly in regions that face challenges related to energy access or infrastructure limitations. For instance, NASA has explored microreactors for lunar and Martian missions under its Kilopower project, which demonstrated a compact reactor capable of generating up to 10 kilowatts of power for extended periods. Their ability to provide a stable and continuous power supply in remote or isolated locations makes them an ideal solution for industries such as mining, military operations, and space exploration. As global energy supply chains face increasing uncertainty, microreactors are becoming an essential tool for ensuring energy independence and resilience in critical sectors.
Market Trends:
Advancement in Reactor Design and Efficiency:
One of the most significant trends in the Microreactor Technology Market is the continuous advancement in reactor design and operational efficiency. Companies are focusing on developing reactors that are not only compact but also highly efficient in terms of fuel use and power output. Innovations such as high-temperature gas-cooled reactors (HTGRs) and molten salt reactors are enhancing the performance of microreactors, enabling them to operate more effectively in a variety of environments. These advancements are making microreactors more commercially viable and positioning them as an attractive solution for decentralized energy generation.
Integration with Renewable Energy Systems:
Another emerging trend is the integration of microreactor technology with renewable energy systems. As the demand for renewable energy sources continues to grow, there is a push toward hybrid systems that combine nuclear and renewable power generation. For instance, the National Renewable Energy Laboratory (NREL) has been working on hybrid systems where microreactors are paired with renewable sources like solar and wind to enhance grid reliability and efficiency. Microreactors, with their ability to provide reliable, baseload power, are being integrated with solar, wind, and other renewable energy sources to create more resilient and flexible energy systems. This hybrid approach can help balance the intermittent nature of renewable energy and ensure a consistent power supply.
Increased Investment in Research and Development:
The growing interest in microreactor technology is leading to increased investment in research and development across the sector. Governments and private entities are dedicating more resources to developing advanced microreactors that can meet specific needs across industries. This includes refining safety protocols, reducing costs, and improving scalability. For instance, Oklo Inc. is developing the Aurora microreactor, which uses advanced fuel to provide clean energy for remote locations and industrial applications. Investment in R&D is accelerating the pace of innovation, making microreactors a more viable option for commercial deployment in the near future.
Expansion in Remote and Off-Grid Applications:
Microreactors are gaining traction in remote and off-grid applications, particularly in industries that operate in isolated areas, such as mining, military, and space exploration. Their ability to provide consistent and reliable power without relying on traditional infrastructure is driving their adoption in these sectors. As the demand for energy in remote locations grows, microreactors are increasingly seen as a practical solution to meet these needs while minimizing environmental impact.
Market Challenges Analysis:
Regulatory and Safety Concerns:
A significant challenge facing the Microreactor Technology Market is the complex regulatory environment surrounding nuclear energy. While microreactors offer promising benefits, their deployment must adhere to stringent safety standards and regulations that vary by country and region. Ensuring that microreactors meet these safety requirements involves a comprehensive and often time-consuming approval process, which can slow down their commercial deployment and increase operational delays. For instance, in Canada, Global First Power's microreactor project at Chalk River Laboratories is subject to extensive environmental assessments and licensing processes under the Canadian Nuclear Safety Commission. Additionally, the public’s perception of nuclear technology, which is often associated with safety concerns, adds another layer of complexity. Overcoming these regulatory hurdles and building public trust in the safety and reliability of microreactors are crucial challenges that need to be addressed for the technology to gain widespread acceptance and foster industry growth in the long term. Educating the public on the advantages and safety measures of microreactors could play a key role in overcoming these barriers.
High Initial Costs and Financial Viability:
Despite advancements in microreactor technology, the high upfront costs associated with their development, testing, and deployment remain a significant challenge. While microreactors promise long-term savings and efficiency, the initial capital investment required for research, regulatory approval, and manufacturing can be substantial. Additionally, the market for microreactors is still emerging, and widespread adoption may be slow due to financial constraints faced by many potential users, such as small-scale industries and remote communities with limited budgets. The financial viability of microreactors is also influenced by factors like fuel supply, maintenance costs, and the need for specialized infrastructure. Securing sufficient investment to overcome these financial barriers and ensuring affordable pricing models for end users is essential to the growth and success of the microreactor technology market, enabling its widespread adoption in various sectors. Efficient financing mechanisms will be critical to expanding the market and reducing overall costs for stakeholders.
Market Opportunities:
The Microreactor Technology Market presents significant opportunities driven by the growing global demand for clean, efficient, and reliable energy sources. As industries and governments continue to prioritize the reduction of carbon emissions, microreactors offer a sustainable alternative to traditional power generation methods. Their ability to provide small-scale, decentralized energy solutions makes them particularly appealing for remote and off-grid applications. Sectors such as mining, defense, and space exploration, where access to consistent energy is crucial, are increasingly looking to microreactors as a reliable solution. Additionally, the integration of microreactors with renewable energy sources presents opportunities to create hybrid energy systems that can address the intermittent nature of renewables, providing a stable power supply and enhancing energy resilience.
Another key opportunity lies in the global push for energy security and independence. Microreactors can serve as a solution for regions that face energy access challenges or are vulnerable to disruptions in traditional power supply chains. Their compact size and ability to operate in isolated locations without relying on large infrastructure make them ideal for remote communities, islands, and military installations. Moreover, as technological advancements continue to drive down the cost of microreactor development and operation, the market will likely see increased adoption in a broader range of industries. Government support for nuclear innovation, along with the growing interest in clean energy solutions, presents a promising landscape for microreactors to play a vital role in addressing future energy needs across various sectors.
Market Segmentation Analysis:
By Product Type:
The Microreactor Technology Market can be segmented based on product types, which include various types of nuclear reactors designed for different applications. These include portable reactors, modular reactors, and transportable reactors, each offering unique benefits in terms of size, mobility, and energy output. Portable reactors are ideal for remote applications, while modular reactors provide scalability and flexibility in energy production. The growing demand for smaller, efficient energy solutions is driving the adoption of these product types, making them crucial for industries requiring decentralized power sources.
By Mixing:
The market also segments by mixing technologies used in microreactors, which play a vital role in optimizing reactor efficiency and fuel utilization. Advanced mixing methods, such as molten salt or gas-cooled reactors, are gaining traction for their ability to enhance thermal management and energy conversion processes. These mixing technologies help improve the overall performance and sustainability of microreactors, supporting their increasing role in various industries such as defense, mining, and space exploration.
Segments:
Based on Product Type
- T-reactor
- Falling Film Reactor
Based on Mixing
- Asia Microreactor
- Round Bottom Flask
- Jackated
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America is projected to dominate the Microreactor Technology Market, accounting for the largest market share in 2024, with 38%. The region’s strong focus on advancing nuclear technology, coupled with government support for clean energy initiatives, is driving market growth. The U.S., in particular, is leading the development of microreactor technology due to increasing investments from both private companies and the federal government. Programs such as the Department of Energy’s Advanced Reactor Demonstration Program (ARDP) and regulatory advancements are streamlining the commercialization of microreactors in various industries. Moreover, the demand for energy security and sustainable solutions in remote areas, including military and mining sectors, is further boosting the adoption of microreactors across North America.
Europe:
Europe is expected to hold a significant share of the Microreactor Technology Market in 2024, contributing 28% of the global market. The region's emphasis on reducing carbon emissions and achieving energy independence is driving the adoption of microreactors as a viable solution for clean energy generation. Countries such as the UK, France, and Finland are at the forefront of nuclear innovation, with several research and development projects underway to advance microreactor technologies. Additionally, the European Union’s commitment to nuclear energy as part of its energy transition strategy, coupled with supportive policies and funding for advanced reactors, is accelerating market growth. The region’s increasing focus on deploying microreactors for remote and off-grid applications, including islands and isolated communities, is expected to further fuel demand.
Asia-Pacific:
The Asia-Pacific region is poised for rapid growth in the Microreactor Technology Market, with a market share of 22% in 2024. Countries such as China, Japan, and South Korea are investing heavily in nuclear technology as part of their efforts to meet rising energy demands while reducing reliance on fossil fuels. China, in particular, is advancing its microreactor development programs, with a focus on modular reactors for both domestic and export markets. The region’s industrial growth, coupled with the need for reliable power in remote areas and islands, is driving the adoption of microreactors. Additionally, the growing interest in microreactors for space exploration and defense applications is contributing to the market's expansion in Asia-Pacific.
Rest of the World:
The rest of the world, including regions such as Latin America, the Middle East, and Africa, is expected to hold a smaller market share in 2024, 12%. However, there is growing interest in microreactor technology for addressing energy challenges in remote and underserved areas. The potential to provide decentralized, reliable power in these regions is driving investments and pilot projects focused on microreactor deployment. Countries in the Middle East and Africa are particularly looking to microreactors as a solution to energy security and diversification, as well as a means to reduce reliance on traditional fossil fuel-based energy sources.
Key Player Analysis:
- Vapourtec
- Microinnova Engineering
- Future Chemistry
- Little Things Factory
- Ehrfeld Mikrotechnik BTS
- YMC
- Soken Chemical and Engineering
- Uniqsis
- Nakamura Choukou
- Syrris
- Chemtrix
- AM Technology
- Corning
Competitive Analysis:
The Microreactor Technology Market is highly competitive, with several leading players driving innovation and development. Companies such as Corning, Chemtrix, Little Things Factory, AM Technology, Soken Chemical and Engineering, Ehrfeld Mikrotechnik BTS, Microinnova Engineering, Nakamura Choukou, Uniqsis, YMC, Future Chemistry, Syrris, and Vapourtec are at the forefront of this market. These companies are focusing on advancing microreactor design and enhancing reactor efficiency to cater to a wide range of industries, including energy, pharmaceuticals, and chemicals. Strategic collaborations, mergers, and acquisitions are commonly employed by these players to strengthen their market presence and expand their product portfolios. Additionally, ongoing investments in research and development enable these companies to innovate and develop new technologies that address the increasing demand for sustainable, decentralized energy solutions. As the market evolves, competition among these key players is expected to intensify, particularly in regions like North America and Europe, where nuclear energy adoption is advancing rapidly.
Recent Developments:
- In March 2024, Prodigy Clean Energy and Des Nedhe Group signed a memorandum of understanding (MoU) to explore the potential use of Prodigy's Transportable Nuclear Power Plants (TNPPs) for powering remote mining operations and communities across Canada.
- In December 2023, Rolls-Royce presented a nuclear Space Micro-Reactor Concept Model at the UK Space Conference in Belfast, as part of a UK Space Agency-funded initiative to demonstrate the first UK lunar modular nuclear reactor.
- In June 2023, Westinghouse Electric Company established eVinciTM Technologies LLC as a distinct business unit and, to accelerate the commercialization of its eVinciTM microreactor, opened a new 87,000-square-foot design and manufacturing facility near downtown Pittsburgh. This facility will house engineering, licensing operations, prototype trials, testing, business development, and sales.
Market Concentration & Characteristics:
The Microreactor Technology Market is characterized by moderate market concentration, with a mix of established players and emerging companies driving innovation. Major corporations, such as Corning, Chemtrix, and Syrris, are leading advancements in reactor design and production, while newer firms contribute to technological developments and niche applications. The market is highly competitive due to the growing demand for efficient and sustainable energy solutions. Companies focus on developing compact, cost-effective microreactors to meet the energy needs of various industries, including mining, defense, and space exploration. Technological innovation, partnerships, and strategic investments are key strategies employed by market participants to maintain a competitive edge. Additionally, the market is shaped by regulatory frameworks, government incentives, and global energy trends, making adaptability and compliance critical to success. As the market evolves, the concentration may shift, allowing smaller players to gain traction through innovations and collaborative efforts with larger entities.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Mixing and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Microreactors are expected to play a crucial role in meeting the growing demand for clean and decentralized energy solutions.
- Advancements in microreactor design will continue to enhance their efficiency and scalability across industries.
- Increasing government support and regulatory frameworks will further accelerate the commercialization of microreactor technologies.
- The energy sector, particularly in remote and off-grid areas, will benefit significantly from microreactor deployment.
- Rising investments in nuclear energy innovation will drive further research and development in microreactor technologies.
- Industries like mining, defense, and space exploration will increasingly adopt microreactors for stable and sustainable power supply.
- The ability to reduce reliance on traditional infrastructure will make microreactors attractive for energy security and resilience.
- Collaboration between private companies and governments will lead to the rapid deployment of microreactors in underserved regions.
- Technological improvements in safety and fuel efficiency will enhance the global acceptance of microreactors.
- The market will witness greater participation from emerging players, promoting innovation and competition.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Microreactor Technology Market?
What factors are driving the growth of the Microreactor Technology Market?
What are some challenges faced by the Microreactor Technology Market?
Who are the major players in the Microreactor Technology Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Microreactor Technology Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Microreactor Technology Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 156,697.86 million → 2032: USD 646,421.31 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Microreactor Technology Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Microreactor Technology Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Microreactor Technology Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Microreactor Technology Market Drivers
- 3.3 Microreactor Technology Market Restraints & Challenges
- 3.4 Microreactor Technology Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Microreactor Technology Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Microreactor Technology Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Microreactor Technology category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Microreactor Technology Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Microreactor Technology Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Microreactor Technology market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Microreactor Technology Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Microreactor Technology Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Microreactor Technology Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Microreactor Technology (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Microreactor Technology Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Microreactor Technology Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Microreactor Technology Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Microreactor Technology Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Microreactor Technology Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Microreactor Technology Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Microreactor Technology Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Microreactor Technology Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Microreactor Technology Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
