
Market Overview:
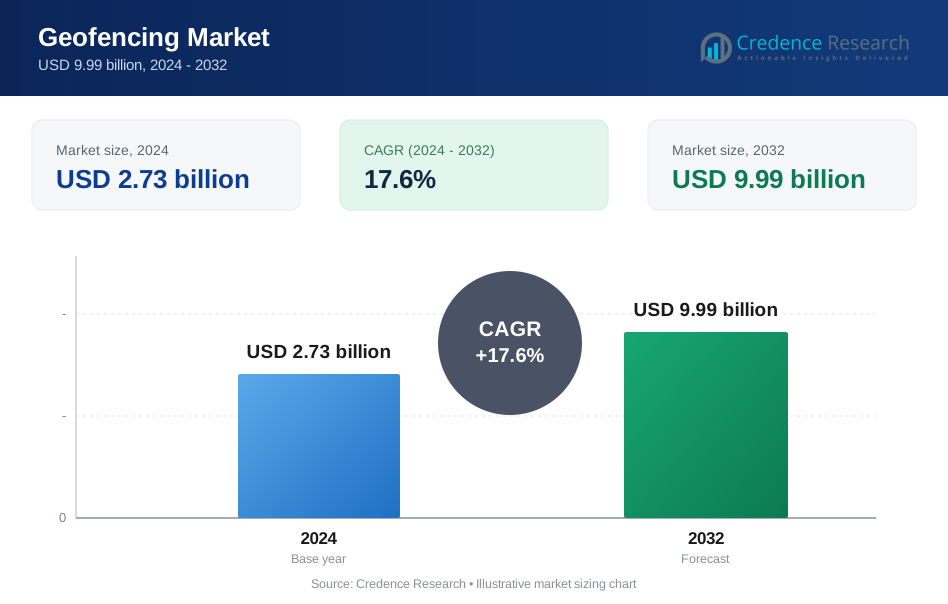
The Geofencing Market size was valued at USD 2.73 billion in 2024 and is anticipated to reach USD 9.99 billion by 2032, at a CAGR of 17.6% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Geofencing Market Size 2024 | USD 2.73 billion |
| Geofencing Market, CAGR | 17.6% |
| Geofencing Market Size 2032 | USD 9.99 billion |
Key drivers of market growth include the rising adoption of smartphones, advancements in GPS technology, and the growing emphasis on targeted marketing strategies. Geofencing enables businesses to engage customers through location-specific offers, notifications, and promotions, fostering deeper consumer engagement and boosting sales. Additionally, the integration of AI and machine learning with geofencing technologies is enhancing location data accuracy, providing businesses with better insights for decision-making. The demand for geofencing is further fueled by the increasing need for automation and real-time tracking in sectors like logistics and fleet management. Furthermore, the growing trend of personalized customer experiences is driving the adoption of geofencing solutions across various industries.
Regionally, North America holds the largest market share due to the rapid adoption of geofencing technologies in retail, healthcare, and automotive sectors. Europe follows closely, driven by the strong presence of key players and increasing investment in smart city infrastructure. The Asia-Pacific region is expected to register the highest growth rate, with countries like China and India leading the way due to expanding smartphone penetration and evolving digital landscapes. The increasing focus on improving urban mobility and traffic management also contributes to the region's strong growth potential.

Market Insights:
- The Geofencing Market is anticipated to grow significantly, reaching USD 9.99 billion by 2032, driven by the increasing demand for location-based services.
- Rising smartphone adoption and the growing use of wearable devices contribute to enhanced geofencing capabilities, enabling businesses to engage customers with personalized offers.
- Advancements in GPS and location-based technologies are improving the precision and effectiveness of geofencing strategies across various industries like retail, healthcare, and logistics.
- Geofencing is becoming an essential tool for targeted marketing, allowing businesses to send location-specific promotions to customers based on their proximity to defined areas.
- The demand for real-time tracking and automation in logistics, fleet management, and public transportation is boosting the adoption of geofencing solutions for route optimization and asset tracking.
- Data privacy concerns, particularly regarding the collection of location-based data, present a significant challenge for the market, with businesses needing to ensure compliance with privacy regulations.
- High initial implementation and maintenance costs could hinder the adoption of geofencing solutions, especially for small and medium-sized enterprises (SMEs) with limited budgets.
Market Drivers:
Rising Adoption of Smartphones and Wearable Devices
The widespread adoption of smartphones is a key driver of the Geofencing Market. Smartphones serve as essential devices for enabling location-based services, offering seamless integration with geofencing technologies. As mobile usage continues to rise globally, businesses leverage geofencing to target customers with personalized promotions and notifications. The growing use of wearable devices also contributes, providing additional data points to enhance location accuracy and improve the user experience.
Advancements in GPS and Location-Based Technologies
GPS and other location-based technologies are critical components that drive the growth of the Geofencing Market. These technologies have evolved significantly, with more accurate and real-time location data now available. Enhanced GPS capabilities allow businesses to implement more precise geofencing strategies, offering better customer targeting and engagement. These advancements are enabling industries to innovate and expand their use of geofencing in various applications, including logistics, retail, and healthcare.
- For instance, Garmin’s GPSMAP 67 series outdoor devices provide location accuracy to within 3 meters, which allows companies in logistics and field service to enable detailed and reliable geofencing applications.
Increased Demand for Targeted Marketing Strategies
Geofencing is becoming a key tool for businesses to execute targeted marketing strategies. By setting virtual boundaries around specific locations, businesses can send personalized offers and advertisements to customers' mobile devices as they enter or exit the defined area. This ability to engage customers based on their proximity to a store, event, or service center enhances consumer interaction and drives sales. The growing emphasis on data-driven, location-based marketing campaigns supports the continued expansion of geofencing technologies.
- For instance, Starbucks used geofencing in the U.S. to trigger mobile push notifications to customers within a 100-meter radius of its stores during its “Happy Hour” campaign, registering increased app-based beverage orders on event days.
Growth in Real-Time Tracking and Automation
The growing need for real-time tracking and automation is another significant factor propelling the Geofencing Market. Industries such as logistics, fleet management, and public transportation benefit from real-time monitoring and automated systems that geofencing enables. Businesses use geofencing for route optimization, asset tracking, and ensuring compliance with regulations. The ability to track goods, vehicles, and personnel in real-time increases operational efficiency, which boosts the adoption of geofencing solutions across these sectors.
Market Trends:
Increasing Integration of Artificial Intelligence and Machine Learning with Geofencing
The Geofencing Market is seeing a growing trend of integrating Artificial Intelligence (AI) and Machine Learning (ML) with location-based technologies. These advanced technologies are enhancing geofencing solutions by improving the accuracy and efficiency of location data analysis. AI and ML algorithms enable businesses to predict customer behavior and tailor geofencing campaigns to individual preferences. By leveraging these technologies, companies can optimize their marketing efforts, streamline operations, and make better-informed decisions. The combination of AI and geofencing also contributes to the creation of smart environments, where businesses can automate notifications, promotions, and offers based on customer movements in real time. The increasing reliance on AI-powered geofencing platforms is pushing the market forward, as industries look to enhance customer engagement through more personalized experiences.
- For instance, smart home solution provider Garadget implemented a geofencing feature that alerts users if they travel 500 meters away from their home and their garage door is still open.
Expansion of Geofencing in Retail and Healthcare Applications
The retail and healthcare sectors are increasingly adopting geofencing technologies to improve customer experiences and operational efficiency. In retail, businesses are utilizing geofencing to send personalized offers to customers when they are near a store, encouraging foot traffic and boosting sales. In healthcare, geofencing is being used to track medical equipment, ensure the safety of patients, and streamline facility operations. Geofencing is also playing a significant role in managing patient flow within hospitals and clinics, improving the overall efficiency of healthcare systems. This expanding use in both industries is accelerating market growth and expanding the scope of geofencing solutions. As these industries continue to embrace location-based technologies, the Geofencing Market is expected to see further expansion and innovation in the coming years.
- For instance, AiRISTA Flow provides a patient wandering system that uses geofencing to improve safety, which can be fully deployed using a facility's existing Wi-Fi infrastructure in just 7 days to provide real-time location tracking and alerts.
Market Challenges Analysis:
Data Privacy and Security Concerns
A significant challenge for the Geofencing Market is the increasing concern over data privacy and security. Geofencing relies heavily on location-based data, which raises privacy issues as sensitive information about a user's movements is constantly being collected and stored. Strict regulations, such as GDPR, require businesses to ensure compliance with data protection laws, adding complexity to the implementation of geofencing solutions. These concerns make some consumers hesitant to opt into geofencing-based marketing or tracking services. As the market grows, businesses must address these privacy concerns by implementing robust data protection measures and ensuring transparency with users to foster trust.
High Costs of Implementation and Maintenance
The initial costs of deploying geofencing technologies can be a barrier for small and medium-sized enterprises (SMEs), limiting their adoption. Setting up geofencing requires investment in hardware, software, and the integration of systems, which may not be feasible for all businesses. Moreover, maintaining and updating these systems can involve significant ongoing expenses, particularly for companies that need to continually adapt their strategies to changing technologies. These high implementation and maintenance costs could slow down the widespread adoption of geofencing, especially in industries where budgets are constrained or ROI may be harder to measure.
Market Opportunities:
Growth in Smart Cities and Urban Development
One of the key opportunities for the Geofencing Market lies in the growth of smart cities and urban development projects. Geofencing can play a pivotal role in enhancing urban mobility, traffic management, and public safety. By enabling real-time tracking and automated responses, it allows municipalities to optimize public services, manage infrastructure efficiently, and improve citizen engagement. The adoption of smart city technologies is expanding, and geofencing can help in areas such as waste management, transportation, and environmental monitoring. As governments continue to invest in these technologies, geofencing offers significant potential for improving city living and urban efficiency, driving further demand in the market.
Increasing Demand for Personalized Consumer Experiences
The growing demand for personalized consumer experiences presents another opportunity for the Geofencing Market. Consumers increasingly expect tailored offers, notifications, and services based on their specific needs and behaviors. Geofencing enables businesses to deliver such personalized experiences by leveraging location-based data to engage customers with targeted marketing and promotions. Retailers, restaurants, and entertainment venues can enhance customer satisfaction and drive loyalty by delivering relevant offers at the right time and place. This demand for personalized services across various sectors, including retail and hospitality, presents a lucrative opportunity for geofencing technologies to expand their reach and functionality.
Market Segmentation Analysis:
By Geofencing Type
The Geofencing Market is primarily segmented into two types: fixed geofencing and mobile geofencing. Fixed geofencing involves defining virtual boundaries around a fixed location, such as a store or a facility, to track customer interactions or assets. Mobile geofencing allows for dynamic boundary creation, based on user location and movement, enhancing real-time engagement with consumers. Mobile geofencing is expected to experience rapid growth due to the increasing adoption of mobile devices and the demand for real-time, location-based marketing.
- For instance, Burger King launched its "Whopper Detour" campaign, creating a geofence around more than 14,000 McDonald's locations. Customers within 600 feet of a McDonald's could order a Whopper for just one cent through the Burger King app.
By Technology
The Geofencing Market can be categorized by technology into GPS, RFID, and Bluetooth Low Energy (BLE). GPS technology dominates the market due to its widespread use in location-based services, providing high accuracy in large geographic areas. RFID and BLE technologies are gaining traction, particularly in indoor environments and close-range tracking. RFID is widely used in asset tracking and supply chain management, while BLE enables proximity marketing and is being integrated into retail environments for enhanced customer interaction.
By Enterprise Type
The Geofencing Market is segmented by enterprise type into small and medium-sized enterprises (SMEs) and large enterprises. Large enterprises currently hold the dominant market share, leveraging geofencing to enhance customer engagement, improve operational efficiency, and optimize supply chain management. However, SMEs are increasingly adopting geofencing solutions due to the availability of cost-effective, scalable options and the growing need for location-based marketing. The market is witnessing a shift as more SMEs recognize the benefits of integrating geofencing into their business operations.
- For instance, smart garage controller company Garadget, an SME, implemented a feature that sends an alert to a user's smartphone if they travel 500 meters away from their home and the garage door has been left open.
Segmentations:
By Geofencing Type:- Fixed Geofencing
- Mobile Geofencing
- GPS
- RFID
- Bluetooth Low Energy (BLE)
- Small and Medium-sized Enterprises (SMEs)
- Large Enterprises
- Retail
- Healthcare
- Transportation and Logistics
- Real Estate
- Government
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America Leads the Geofencing Market
North America holds the largest share of the Geofencing Market, accounting for 38% of the total market. The region's advanced technological infrastructure and high smartphone penetration foster the rapid adoption of geofencing solutions across industries such as retail, healthcare, and automotive. Businesses in the United States and Canada use geofencing to enhance customer engagement with location-based promotions and real-time notifications. Furthermore, the region benefits from a favorable regulatory environment, which supports the growth of personalized services, driving the demand for geofencing technologies. The presence of key players in the market further solidifies North America's dominance.
Europe Shows Strong Growth in Geofencing Adoption
Europe captures 28% of the Geofencing Market share, driven by significant investments in smart city development and urban mobility. Countries like the UK, Germany, and France are integrating geofencing into their infrastructure to improve transportation, traffic management, and public services. The strong regulatory framework in the region ensures consumer privacy and security, which fosters trust in location-based services. Retail chains and healthcare providers are increasingly adopting geofencing to enhance customer experience, further fueling market expansion across Europe.
Asia-Pacific Experiences Rapid Market Expansion
The Asia-Pacific region holds 22% of the Geofencing Market share and is poised for the highest growth rate during the forecast period. Increasing smartphone adoption and urbanization in countries like China, India, and Japan are key drivers of geofencing adoption. The development of smart cities and the growing demand for real-time tracking in sectors such as retail, healthcare, and logistics are accelerating market growth. The rise of e-commerce and the increasing need for location-based services contribute to the rapid expansion of geofencing technologies in this region.
Key Player Analysis:
- Eskimi (Lithuania)
- Bluedot (U.S.)
- LocationSmart (U.S.)
- Radar Labs, Inc. (U.S.)
- Infillion (U.S.)
- fi (U.S.)
- Esri (U.S.)
- GeoMoby (Australia)
- Thumbvista (U.S.)
- Mapsted Corp. (Canada)
Competitive Analysis:
The Geofencing Market is highly competitive, with key players leveraging advanced technologies to offer innovative solutions. Prominent companies dominate the market by integrating geofencing into a variety of applications, enhancing customer engagement, and improving operational efficiency. Emerging firms are also making their mark by providing specialized geofencing solutions tailored to specific industries, offering customized services to meet unique market demands. The market is moderately fragmented, with both large-scale enterprises and agile startups coexisting, each contributing to ongoing innovation. Strategic partnerships and continuous technological advancements are key factors driving competition, as companies strive to enhance their offerings and meet the growing demand for location-based services. Privacy and data security remain critical considerations, with businesses that can effectively address these challenges well-positioned to capitalize on the market's potential.
Recent Developments:
- In May 2025, Bluedot announced that it is now powering the service fleet charging experience for the electric vehicle company Rivian.
- In February 2025, Eskimi hosted its Brand Impact Summit 2025, which featured industry leaders from global brands such as McCann, L'Oreal, and Publicis who discussed brand impact and innovation.
- In April 2025, Bluedot launched its Shared Private Chargers solution, which allows fleets to use existing private depot charging infrastructure and consolidates access, payments, and reporting into a single tool.
Report Coverage:
The research report offers an in-depth analysis based on Geofencing Type, Technology, Enterprise Type, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Geofencing Market will continue to expand as more industries adopt location-based services to enhance customer engagement and operational efficiency.
- Increased smartphone adoption and the growing use of wearable devices will drive demand for mobile geofencing solutions.
- The integration of AI and machine learning will improve geofencing accuracy, enabling more personalized and targeted marketing strategies.
- Geofencing will see greater use in smart city initiatives, enhancing urban mobility, traffic management, and public safety.
- Retailers will increasingly leverage geofencing for proximity marketing, offering personalized promotions based on customer location.
- The demand for geofencing in the healthcare sector will grow, supporting real-time tracking of assets, patients, and personnel in healthcare facilities.
- The logistics and transportation sectors will continue to adopt geofencing for real-time tracking and route optimization, improving efficiency.
- Privacy and data security concerns will prompt regulatory developments, influencing how geofencing solutions handle customer data.
- SMEs will increasingly adopt cost-effective geofencing solutions as technology becomes more accessible and affordable.
- The Asia-Pacific region will experience significant growth, driven by expanding digital infrastructure, e-commerce, and increasing urbanization.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Geofencing, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Geofencing market projected to grow between 2024 and 2032?
Which Geofencing market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Geofencing market?
Who are the leading companies in the Geofencing market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Geofencing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Geofencing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2.73 billion → 2032: USD 9.99 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Geofencing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Geofencing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Geofencing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Geofencing Market Drivers
- 3.3 Geofencing Market Restraints & Challenges
- 3.4 Geofencing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Geofencing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Geofencing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Geofencing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Geofencing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Geofencing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Geofencing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Geofencing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Geofencing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Geofencing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Geofencing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Geofencing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Geofencing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Geofencing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Geofencing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Geofencing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Geofencing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Geofencing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Geofencing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Geofencing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
