
Market Overview
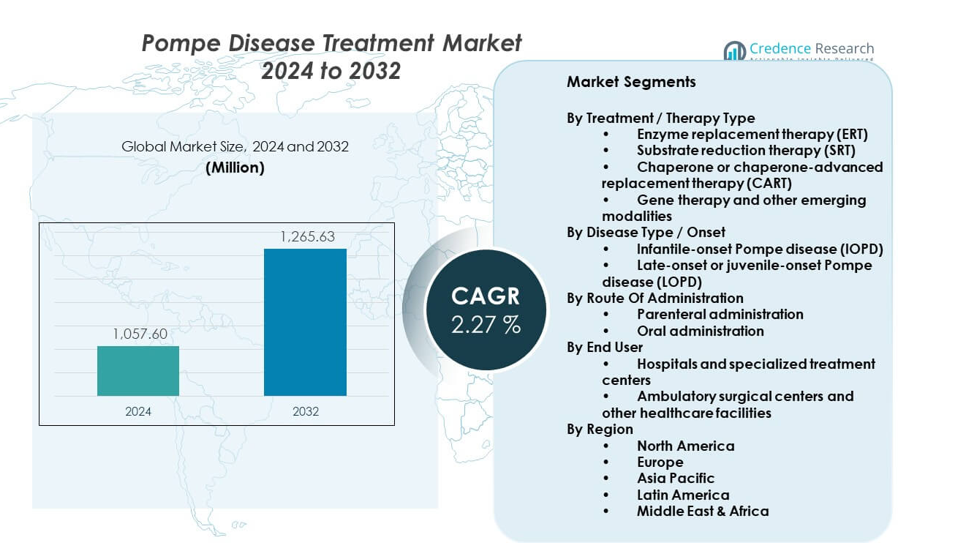
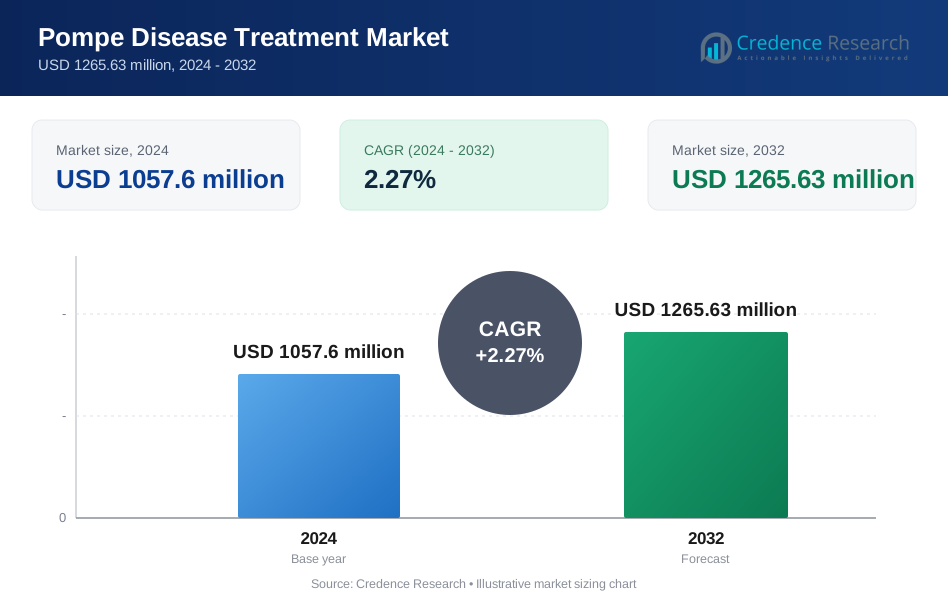
The Pompe Disease Treatment Market is projected to grow from USD 1057.6 million in 2024 to an estimated USD 1265.63 million by 2032, with a CAGR of 2.27% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Pompe Disease Treatment Market Size 2024 | USD 1057.6 million |
| Pompe Disease Treatment Market, CAGR | 2.27% |
| Pompe Disease Treatment Market Size 2032 | USD 1265.63 million |
Market growth is driven by rising disease awareness and improved diagnostic accuracy. Expanded newborn screening programs enable earlier detection and faster treatment initiation. Pharmaceutical companies invest in advanced enzyme formulations to improve muscle uptake. Active clinical pipelines support innovation in gene and adjunct therapies. Better patient survival increases long-term therapy demand. Supportive reimbursement frameworks encourage therapy adoption. Collaboration between research centers and drug developers accelerates treatment progress.
North America leads the market due to strong screening programs and advanced care access. The United States benefits from rare disease funding and specialist availability. Europe follows with established treatment guidelines and public healthcare support. Asia Pacific is emerging with improving diagnostics and policy focus on rare diseases. Japan shows strong clinical adoption due to early screening efforts. China gains momentum through expanding specialty centers. Other regions grow gradually with awareness initiatives.
Market Insights:
- The market stood at USD 1057.6 million in 2024 and is projected to reach USD 1265.63 million by 2032, registering a CAGR of 2.27% due to chronic therapy demand and limited alternatives.
- North America leads with about 45% share due to early diagnosis, strong reimbursement, and specialized centers, while Europe follows with nearly 30% supported by public healthcare systems and rare-disease frameworks.
- Asia Pacific holds around 18% share and represents the fastest-growing region, driven by improving diagnostics, policy focus on rare diseases, and expanding specialty care in key countries.
- By therapy type, enzyme replacement therapy accounts for roughly 70% share due to established clinical use, while gene therapy and advanced modalities collectively represent about 15% with pipeline-driven growth.
- By disease type, late-onset Pompe disease contributes nearly 65% share because of larger patient numbers, whereas infantile-onset cases account for about 35% due to lower incidence.
Market Drivers:
Rising Disease Awareness And Improved Diagnostic Coverage Across Healthcare Systems
Growing awareness of rare neuromuscular disorders supports earlier identification of Pompe disease. Healthcare providers now recognize symptoms faster across age groups. Expanded newborn screening programs detect cases before severe progression. Early diagnosis improves treatment timing and outcomes. The Pompe Disease Treatment Market benefits from this shift toward proactive care. Medical education initiatives strengthen physician confidence in rare disease diagnosis. Patient advocacy groups also promote symptom awareness. Public health agencies support screening inclusion policies.
- For instance, the U.S. Secretary of Health and Human Services accepted the federal advisory committee's recommendation to add Pompe disease to the Recommended Uniform Screening Panel (RUSP) in March 2015. As of late 2024/early 2025, 47 U.S. states and the District of Columbia screen newborns for the condition. All but one state (Alaska) have plans to implement screening by the end of 2026, meaning universal screening is not yet fully implemented in every state.
Advancement Of Enzyme Replacement Therapies With Improved Clinical Outcomes
Continuous innovation in enzyme replacement therapy strengthens treatment reliability. Manufacturers enhance enzyme stability and tissue targeting. Improved formulations reduce immune reactions in long-term use. These advances raise physician confidence in prescribing therapy. The Pompe Disease Treatment Market gains from consistent clinical efficacy. Treatment protocols now show better respiratory and motor outcomes. Hospitals prefer therapies with predictable safety profiles. This progress sustains long-term patient adherence.
- For instance, Sanofi’s alglucosidase alfa has demonstrated sustained improvements in survival and motor outcomes in infantile-onset Pompe disease, with long-term follow-up data published in peer-reviewed journals.
Expansion Of Reimbursement Support For High-Cost Rare Disease Therapies
Supportive reimbursement policies drive therapy access in developed markets. Governments recognize the lifelong burden of Pompe disease. Payers approve coverage for high-cost biologic treatments. This reduces financial barriers for patients and families. The Pompe Disease Treatment Market responds positively to coverage clarity. Insurance approvals encourage treatment initiation without delay. Stable funding improves therapy continuity. Healthcare systems prioritize rare disease support frameworks.
Strengthening Of Clinical Research And Drug Development Pipelines
Ongoing clinical research expands therapeutic options for Pompe disease. Biopharmaceutical companies invest in next-generation therapies. Research centers support trials across pediatric and adult populations. Pipeline depth increases confidence in long-term innovation. The Pompe Disease Treatment Market benefits from diversified treatment approaches. Regulatory agencies support orphan drug development pathways. Faster trial designs improve development timelines. Scientific collaboration accelerates therapeutic progress.
Market Trends:
Shift Toward Next-Generation And Combination-Based Treatment Approaches
Treatment strategies evolve beyond single-therapy dependence. Developers explore combination regimens to enhance effectiveness. These approaches target multiple disease mechanisms. Clinicians seek therapies with broader muscle impact. The Pompe Disease Treatment Market reflects this therapeutic shift. Combination use supports personalized treatment planning. Research data guides regimen selection. Clinical adoption grows with evidence maturity.
- For instance, Amicus Therapeutics reported positive Phase III PROPEL subgroup trial results showing statistically significant improved six-minute walk distance with cipaglucosidase alfa plus miglustat compared with standard enzyme therapy in patients who had previously been receiving standard of care alglucosidase alfa.
Growing Focus On Gene Therapy And Disease-Modifying Solutions
Gene therapy research gains strategic focus in rare diseases. Developers target long-term enzyme production within cells. This approach aims to reduce lifelong infusion dependence. Clinical trials advance cautiously with safety oversight. The Pompe Disease Treatment Market tracks these developments closely. Investors view gene therapy as transformative potential. Regulatory bodies support structured trial frameworks. Long-term outcome data remains a key focus.
- For instance, Astellas Pharma’s AT845 gene therapy program for late-onset Pompe disease reported sustained transgene expression and glycogen reduction in early clinical data disclosed at major neuromuscular conferences.
Increased Integration Of Multidisciplinary Care Models In Treatment Delivery
Care delivery shifts toward integrated clinical management models. Neurologists, pulmonologists, and geneticists coordinate care plans. This improves disease monitoring across organ systems. Treatment centers adopt structured follow-up protocols. The Pompe Disease Treatment Market aligns with holistic care practices. Coordinated care improves quality of life measures. Hospitals invest in specialized rare disease clinics. Patient outcomes benefit from unified oversight.
Rising Use Of Real-World Evidence To Guide Treatment Decisions
Healthcare providers rely more on real-world treatment data. Patient registries capture long-term therapy outcomes. This data informs dosing and care optimization. Regulators accept real-world evidence in evaluations. The Pompe Disease Treatment Market gains insight from post-market studies. Clinicians adjust protocols based on observed effectiveness. Data transparency supports informed decision-making. Long-term tracking improves treatment confidence.
Market Challenges Analysis:
High Treatment Costs And Long-Term Financial Pressure On Healthcare Systems
Pompe disease therapies require complex biologic manufacturing and strict quality controls. These factors keep treatment prices high over long durations. Healthcare budgets face strain when coverage spans a patient’s lifetime. Access gaps persist in cost-sensitive regions and public systems. The Pompe Disease Treatment Market encounters payer scrutiny during reimbursement reviews. Delays in approval affect therapy initiation timelines. Financial counseling remains limited in many care centers. Cost containment discussions influence procurement decisions.
Limited Patient Pool And Operational Complexity In Rare Disease Care
Pompe disease affects a small and dispersed patient population. This limits clinical trial recruitment and real-world data volume. Specialized centers handle diagnosis, infusion, and monitoring. Operational demands increase staffing and infrastructure needs. The Pompe Disease Treatment Market must address care coordination challenges. Travel burdens affect patient adherence in remote areas. Workforce shortages constrain service expansion. Data standardization across centers remains uneven.
Market Opportunities:
Expansion Of Newborn Screening And Early Intervention Programs Globally
Public health authorities expand newborn screening panels worldwide. Early detection enables timely treatment before irreversible damage. Outcomes improve with prompt therapy initiation. Health systems invest in screening infrastructure and training. The Pompe Disease Treatment Market benefits from earlier patient entry. Long-term care pathways become more predictable. Awareness campaigns support policy adoption. Screening expansion opens sustained demand growth.
Development Of Next-Generation Therapies And Personalized Care Pathways
Innovation advances toward therapies with improved delivery and durability. Personalized dosing and monitoring gain clinical interest. Digital tools support adherence and outcome tracking. Partnerships link biotech firms with specialty centers. The Pompe Disease Treatment Market captures value from differentiated solutions. Regulatory incentives support orphan innovation. Care models evolve toward tailored management. These shifts create durable growth opportunities.
Market Segmentation Analysis:
By Treatment / Therapy Type
Enzyme replacement therapy remains the primary treatment option due to established clinical use and proven outcomes. Substrate reduction therapy gains attention for its oral potential and supportive role. Chaperone and chaperone-advanced replacement therapies focus on improving enzyme stability and activity. Gene therapy and other emerging modalities target long-term disease modification and reduced treatment burden. The Pompe Disease Treatment Market reflects gradual diversification across therapy classes. Developers pursue balanced portfolios to address varied patient needs.
- For instance, Amicus Therapeutics has published pharmacokinetic data demonstrating that miglustat stabilizes circulating enzyme exposure when used with enzyme therapy. Developers balance near-term and long-term strategies.
By Disease Type / Onset
Infantile-onset Pompe disease requires early and intensive treatment due to rapid progression. Late-onset Pompe disease represents a larger treated population with chronic management needs. Treatment duration extends across a patient’s lifetime in this segment. It drives sustained demand for maintenance therapies. Disease severity and onset timing guide therapy selection. Clinical focus remains on preserving mobility and respiratory function.
- For instance, international Pompe disease registries sponsored by Sanofi document preserved pulmonary function in late-onset patients who initiate therapy before advanced respiratory decline. Clinical focus remains on maintaining mobility and breathing capacity.
By Route Of Administration
Parenteral administration dominates due to intravenous delivery of enzyme therapies. Hospitals manage infusion protocols and monitoring. Oral administration gains interest for substrate reduction and chaperone approaches. This route aims to reduce treatment burden and improve adherence. It remains under clinical development. Route choice influences care setting and cost structure.
By End User
Hospitals and specialized treatment centers account for the largest share due to complex care needs. These centers provide diagnosis, infusion, and long-term monitoring. Ambulatory surgical centers and other facilities support follow-up and supportive services. Care coordination remains critical across settings.
Segmentation:
By Treatment / Therapy Type
- Enzyme replacement therapy (ERT)
- Substrate reduction therapy (SRT)
- Chaperone or chaperone-advanced replacement therapy (CART)
- Gene therapy and other emerging modalities
By Disease Type / Onset
- Infantile-onset Pompe disease (IOPD)
- Late-onset or juvenile-onset Pompe disease (LOPD)
By Route Of Administration
- Parenteral administration
- Oral administration
By End User
- Hospitals and specialized treatment centers
- Ambulatory surgical centers and other healthcare facilities
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the global market, accounting for about 45% of total revenue. The region benefits from early diagnosis through expanded newborn screening programs. Strong reimbursement frameworks support long-term therapy access. The United States drives most demand due to specialized treatment centers and active clinical research. The Pompe Disease Treatment Market gains stability from established enzyme replacement therapy use. High awareness among clinicians supports timely treatment initiation. Canada contributes through public healthcare coverage and rare disease programs.
Europe
Europe represents nearly 30% of the global market share and maintains steady demand. Public healthcare systems support rare disease treatment access across major countries. Germany, France, Italy, and the United Kingdom lead due to structured care pathways. Regulatory support for orphan drugs encourages therapy availability. The Pompe Disease Treatment Market benefits from coordinated referral networks in Europe. Treatment guidelines support consistent clinical practice. Regional collaboration improves patient tracking and long-term care outcomes.
Asia Pacific, Latin America, And Middle East & Africa
Asia Pacific accounts for around 18% of the market and shows the fastest expansion pace. Japan and China lead due to improving diagnostics and policy focus on rare diseases. India and South Korea increase access through specialized centers. The Pompe Disease Treatment Market gains traction as awareness improves in urban hospitals. Latin America holds about 5% share, led by Brazil and Mexico. The Middle East & Africa contribute nearly 2%, supported by gradual healthcare infrastructure development. Access remains uneven but continues to improve.
Key Player Analysis:
- Sanofi (Genzyme)
- Amicus Therapeutics
- Astellas Pharma
- BioMarin Pharmaceutical
- Oxyrane
- Maze Therapeutics
- AVROBIO Inc
- Genethon
- Audentes Therapeutics (Astellas)
- Valerion Therapeutics
- EpiVax Inc
- Actus Therapeutics
- Sanofi (Genzyme)
- Amicus Therapeutics
- Astellas Pharma
- BioMarin Pharmaceutical
- Oxyrane
- Maze Therapeutics
Competitive Analysis:
The Pompe Disease Treatment Market shows high concentration with a limited number of specialized players. Established companies lead through approved enzyme replacement therapies and strong clinical experience. It favors firms with orphan drug expertise and global regulatory capability. Competitive positioning depends on therapy efficacy, safety profile, and reimbursement access. Pipeline strength plays a key role in long-term differentiation. Companies invest in next-generation biologics and gene-based solutions. Strategic collaborations support faster development and clinical reach. Market competition remains focused on innovation rather than price pressure.
Recent Developments:
- Maze Therapeutics entered into an exclusive worldwide license agreement with Japanese pharmaceutical company Shionogi on May 10, 2024, for its investigational oral Pompe disease therapy MZE001. Under the deal, Shionogi agreed to pay Maze $150 million upfront, with additional milestone payments based on development, regulatory, and commercial achievements plus tiered royalties on future net sales. MZE001 is an oral glycogen synthase 1 (GYS1) inhibitor with the potential to become the first oral therapy for Pompe disease.
- Amicus Therapeutics received FDA approval on September 28, 2023, for Pombiliti (cipaglucosidase alfa-atga) plus Opfolda (miglustat), making it the first and only two-component therapy approved for adults living with late-onset Pompe disease (LOPD) who are not improving on their current enzyme replacement therapy (ERT). Following this approval, Amicus secured a $430 million strategic financing deal from Blackstone Life Sciences and Blackstone Credit. This deal was announced on October 2, 2023. The deal included a $400 million loan for debt refinancing and a $30 million strategic investment in the company's common stock. The company launched the treatment immediately in the United States at a widely reported list price of $650,000 per patient annually (for a patient of median weight).
Report Coverage:
The research report offers an in-depth analysis based on treatment and therapy type, disease onset, route of administration, end user, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Continued focus on early diagnosis through newborn screening programs
- Steady innovation in enzyme replacement therapy formulations
- Growing clinical interest in gene therapy approaches
- Expansion of personalized treatment strategies
- Wider adoption of multidisciplinary care models
- Increased reliance on real-world clinical evidence
- Gradual improvement in access across emerging markets
- Strong regulatory support for orphan drug development
- Deeper collaboration between biotech firms and research centers
- Long-term emphasis on improving patient quality of life
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Pompe Disease Treatment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Pompe Disease Treatment Market projected to grow between 2024 and 2032?
Which Pompe Disease Treatment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Pompe Disease Treatment Market?
Who are the leading companies in the Pompe Disease Treatment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Pompe Disease Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Pompe Disease Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1057.6 million → 2032: USD 1265.63 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Pompe Disease Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Pompe Disease Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Pompe Disease Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Pompe Disease Treatment Market Drivers
- 3.3 Pompe Disease Treatment Market Restraints & Challenges
- 3.4 Pompe Disease Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Pompe Disease Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Pompe Disease Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Pompe Disease Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Pompe Disease Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Pompe Disease Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Pompe Disease Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Pompe Disease Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Pompe Disease Treatment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Pompe Disease Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Pompe Disease Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Pompe Disease Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Pompe Disease Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Pompe Disease Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Pompe Disease Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Pompe Disease Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Pompe Disease Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Pompe Disease Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Pompe Disease Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Pompe Disease Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
