
Grocery, export and health flows shape temperature logistics
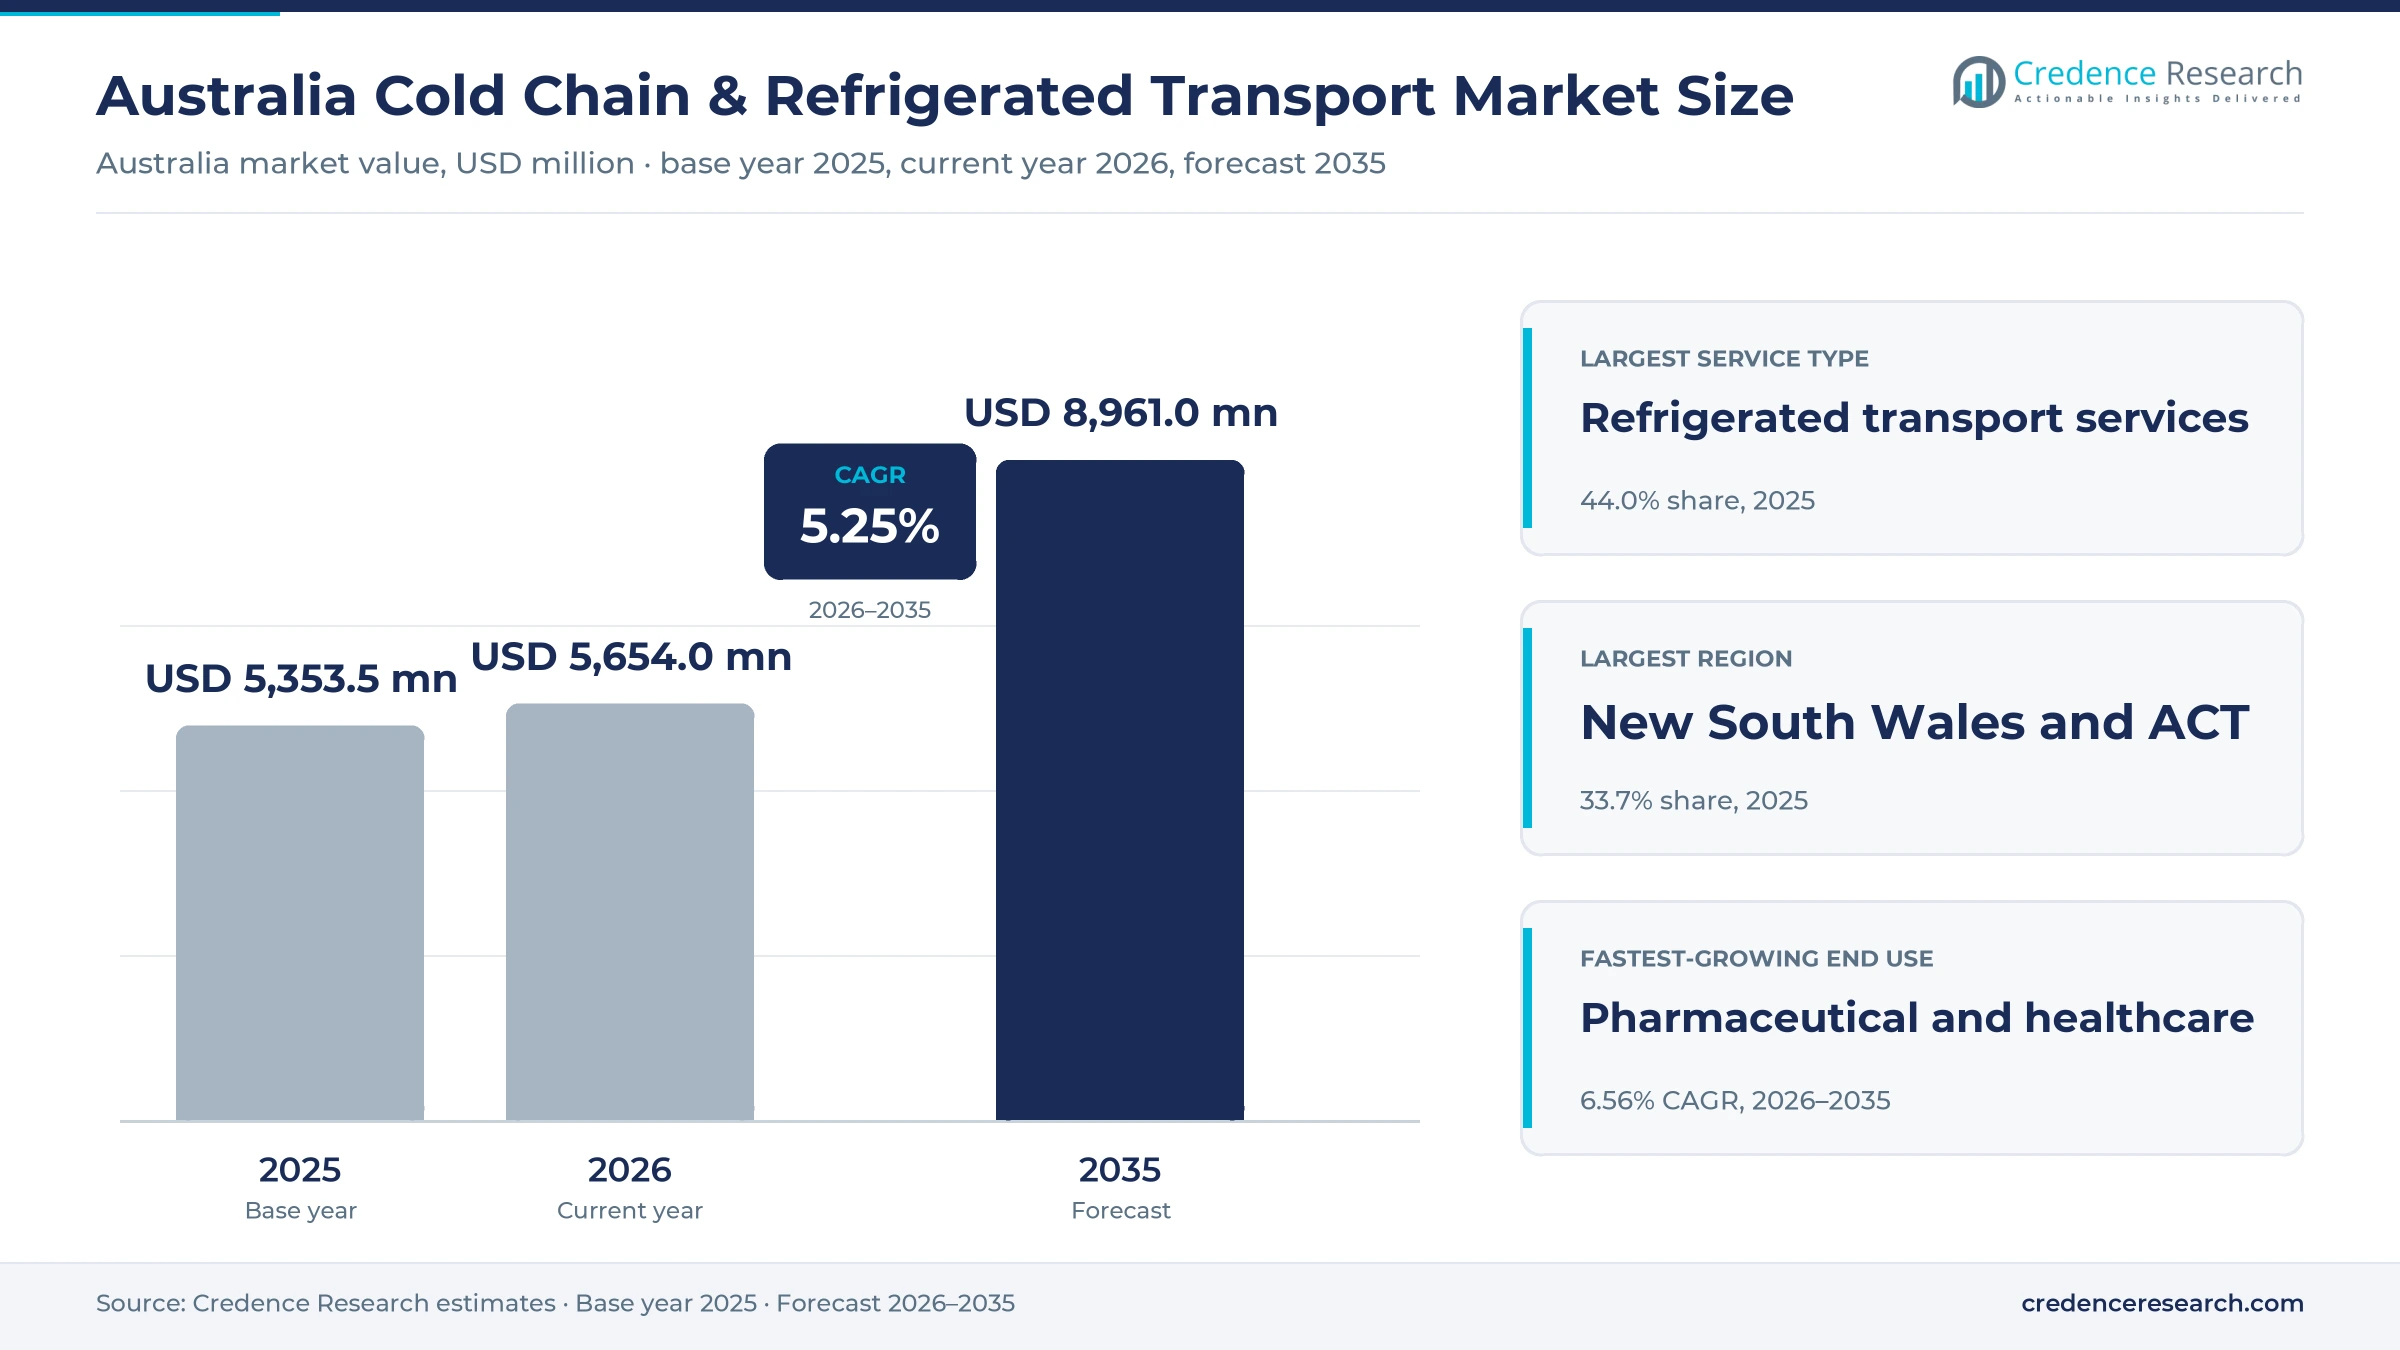
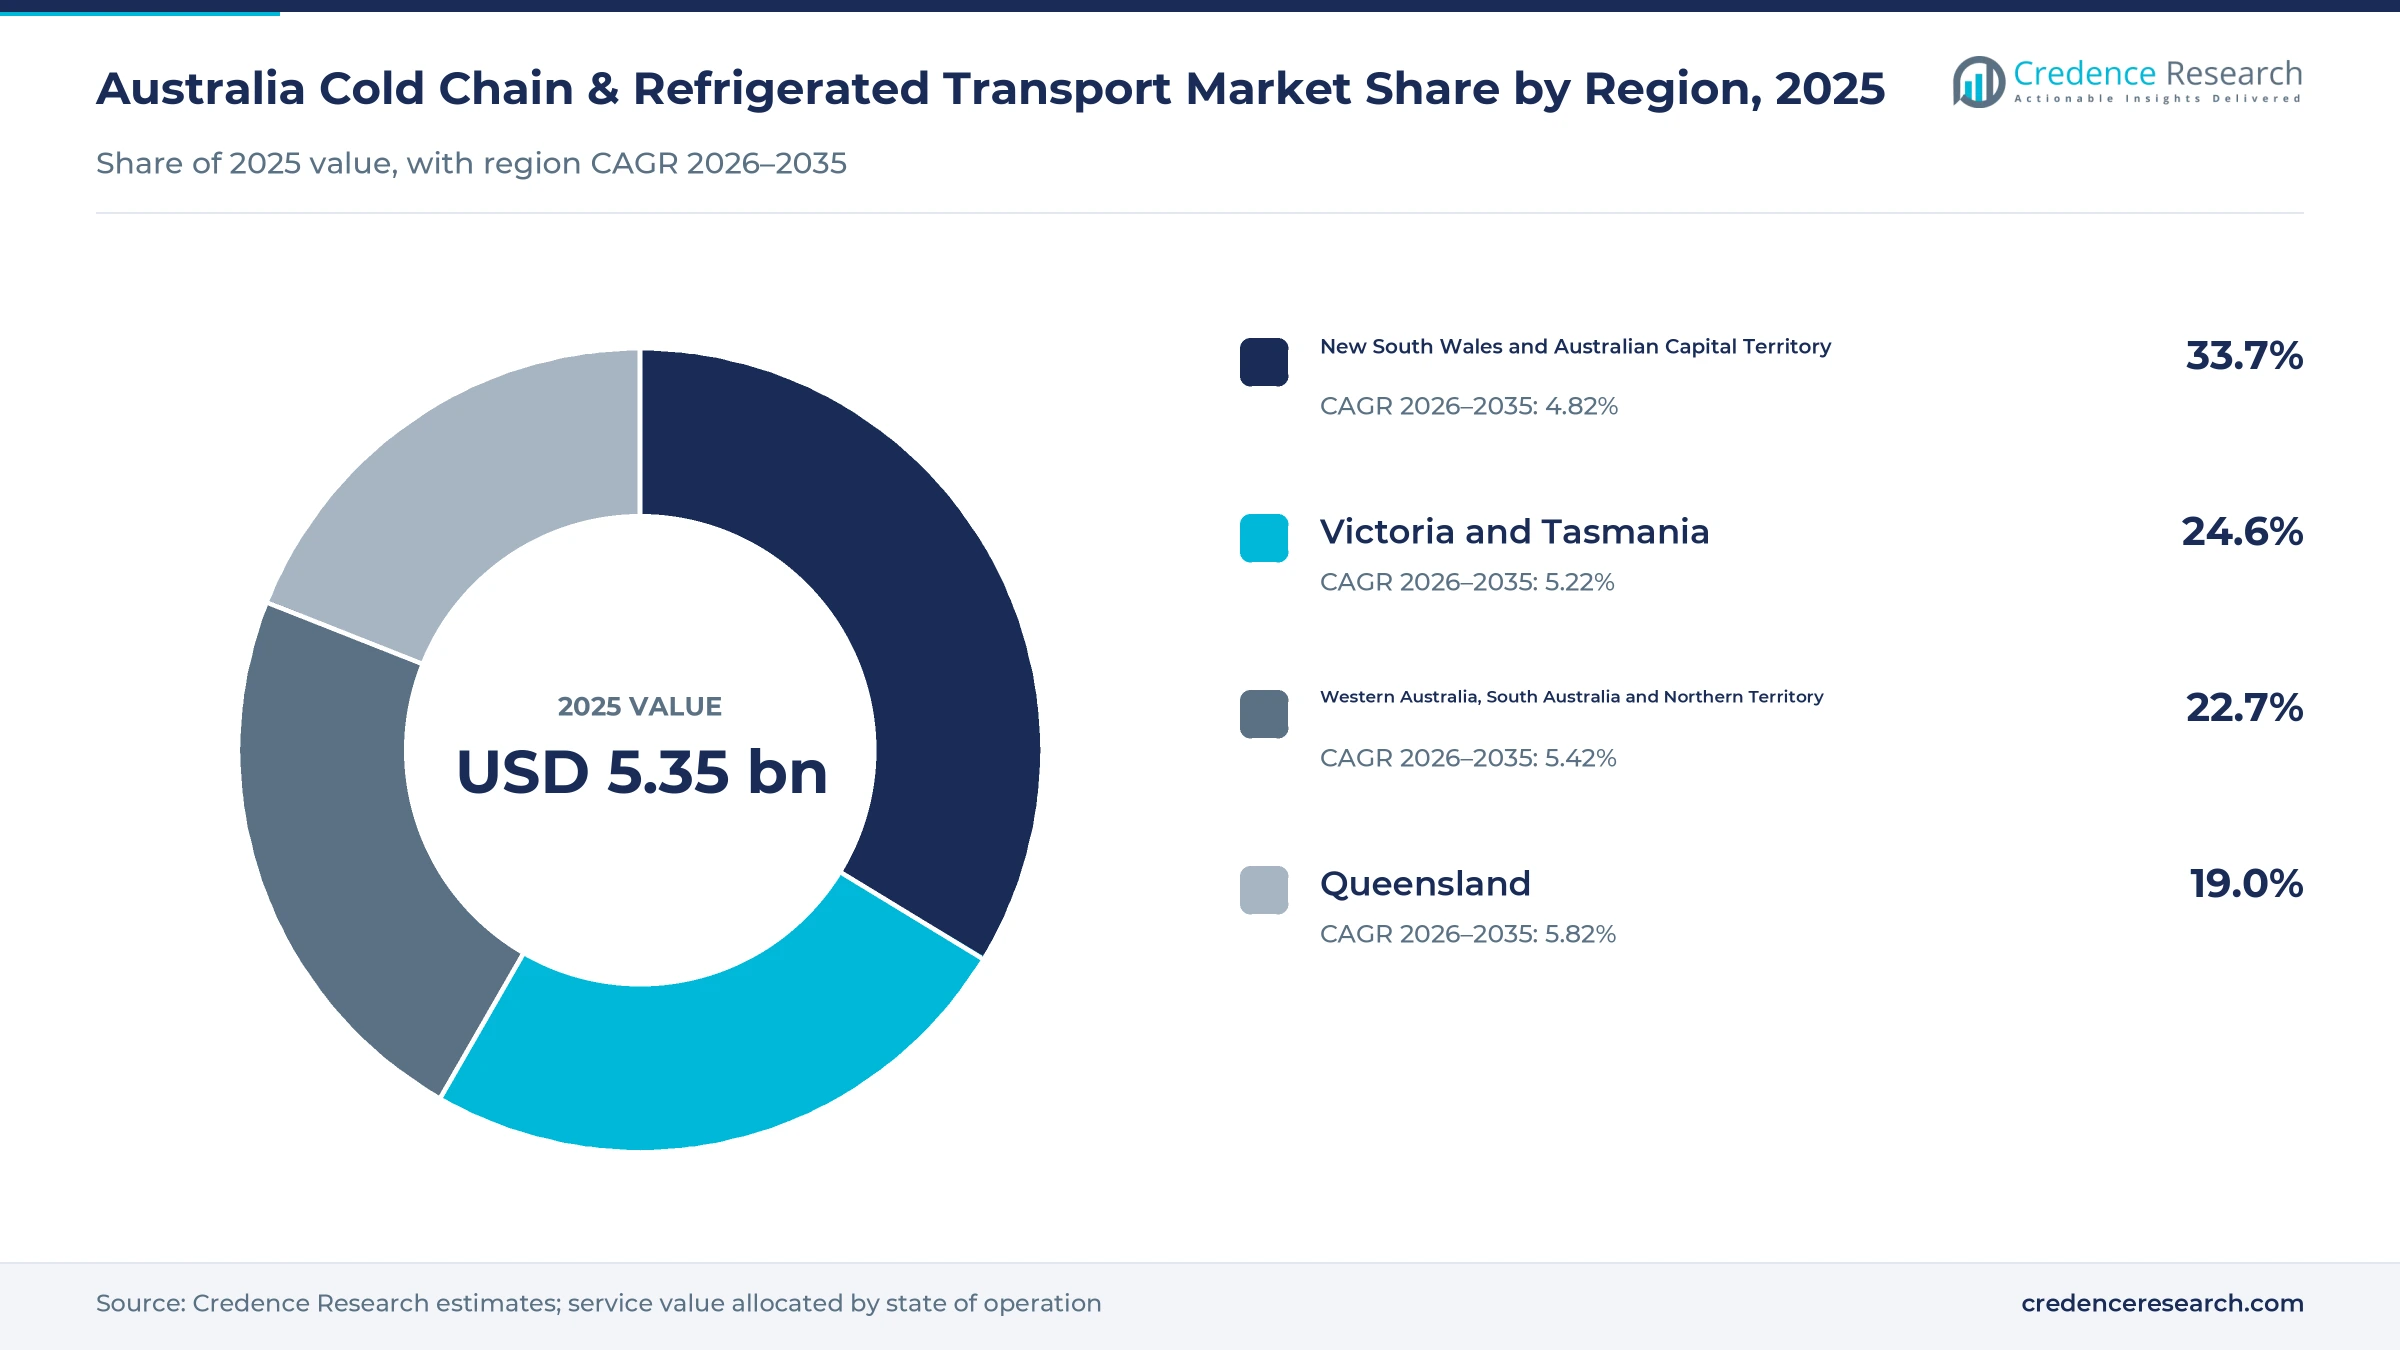
The Australia cold chain and refrigerated transport market was valued at USD 5.35 billion in 2025 and is projected to increase from USD 5.65 billion in 2026 to USD 8.96 billion by 2035, registering a CAGR of 5.25% during 2026–2035. Demand comes from supermarket chains that move chilled and frozen groceries to stores every day, from meat, dairy and horticulture exporters that ship through major ports, and from hospitals and pharmacies that need medicines held between 2 and 8 degrees Celsius. New South Wales and the Australian Capital Territory held the largest regional share, 33.7% in 2025, because Sydney hosts the largest consumer base and the busiest import gateways. Queensland is the fastest-growing region at 5.82% a year, as population growth and beef exports lift volumes. Operators are adding automated frozen stores in Sydney and Melbourne, while larger fleets are buying regional refrigerated carriers to extend national coverage.
Which temperature-controlled services does the estimate count?
The estimate measures revenue from refrigerated storage, refrigerated transport, value-added cold chain services and specialist temperature-controlled handling in Australia. It covers chilled and frozen warehousing, road and rail linehaul, port and airport handling, blast freezing, picking and packing for food, medicines and other sensitive goods. Values are stated at the contract and transaction prices paid by manufacturers, retailers, exporters and healthcare buyers.
The estimate excludes the sale of refrigerated trucks, cold room equipment and packaging, as well as in-house fleets whose costs are not billed to customers. The value chain runs from farms, processors and drug makers through cold stores and refrigerated carriers to supermarkets, foodservice outlets, pharmacies, hospitals and export terminals.
Australia Cold Chain & Refrigerated Transport Market Insights
- The Australia cold chain and refrigerated transport market was valued at USD 5.35 billion in 2025 and is projected to reach USD 8.96 billion by 2035, at a 5.25% CAGR.
- New South Wales and the Australian Capital Territory held a 33.7% share of 2025 value, led by Sydney demand.
- Refrigerated transport services led with a 44.0% share of 2025 value, because daily store deliveries need chilled road freight.
- Australian beef exports reached a record 1,545,759 metric tons in calendar 2025, which lifted demand for chilled and frozen export handling.
- NewCold plans to add 100,000 frozen pallet positions in Sydney by October 2026 and 80,000 in Melbourne by July 2026.
Road transport leads as healthcare handling grows fastest
Why does refrigerated transport lead service value?
Based on service type, the market is categorized into refrigerated storage services, refrigerated transport services, value-added cold chain services and specialist temperature-controlled handling. Refrigerated Transport Services led with a 44.0% share of 2025 value, because long distances between farms, cities and ports need daily chilled freight. Specialist Temperature-Controlled Handling grows fastest at 6.35% a year, as medicines and vaccines need tighter temperature control.
How does healthcare demand outpace food growth?
Based on end-use industry, the market is categorized into food and beverage, pharmaceutical and healthcare, perishable food exports and temperature-sensitive non-food products. Food and Beverage led with a 58.0% share of 2025 value, because supermarkets and foodservice outlets restock chilled goods every day. Pharmaceutical and Healthcare grows fastest at 6.56% a year, as logistics firms add 2 to 8 degree storage for medicines.
Why do road-linked services dominate?
Based on mode of transport, the market is categorized into road-linked services, rail-linked services, sea-gateway-linked services and air-gateway-linked services. Road-Linked Services led with a 71.0% share of 2025 value, because trucks reach every store, farm and hospital. Air-Gateway-Linked Services grow fastest at 6.12% a year, as high-value chilled food and medicines move through airports. Sea-gateway services also gain from record meat exports through Brisbane, Melbourne and Fremantle.
Why are healthcare providers the fastest customers?
Based on customer type, the market is categorized into manufacturers and processors, retailers and wholesalers, foodservice buyers and healthcare providers. Retailers and Wholesalers led with a 41.0% share of 2025 value, because grocery chains buy large dedicated contracts. Healthcare Providers grow fastest at 6.36% a year, as hospitals and pharmacies outsource temperature-controlled storage. Manufacturers and processors also buy storage near ports for export orders.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Refrigerated Transport Services | 44.0% | Specialist Temperature-Controlled Handling | 6.35% |
| By End-Use Industry | Food and Beverage | 58.0% | Pharmaceutical and Healthcare | 6.56% |
| By Mode of Transport | Road-Linked Services | 71.0% | Air-Gateway-Linked Services | 6.12% |
| By Customer Type | Retailers and Wholesalers | 41.0% | Healthcare Providers | 6.36% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Food demand, health rules and exports lift volumes
How does recurring food distribution keep volumes rising?
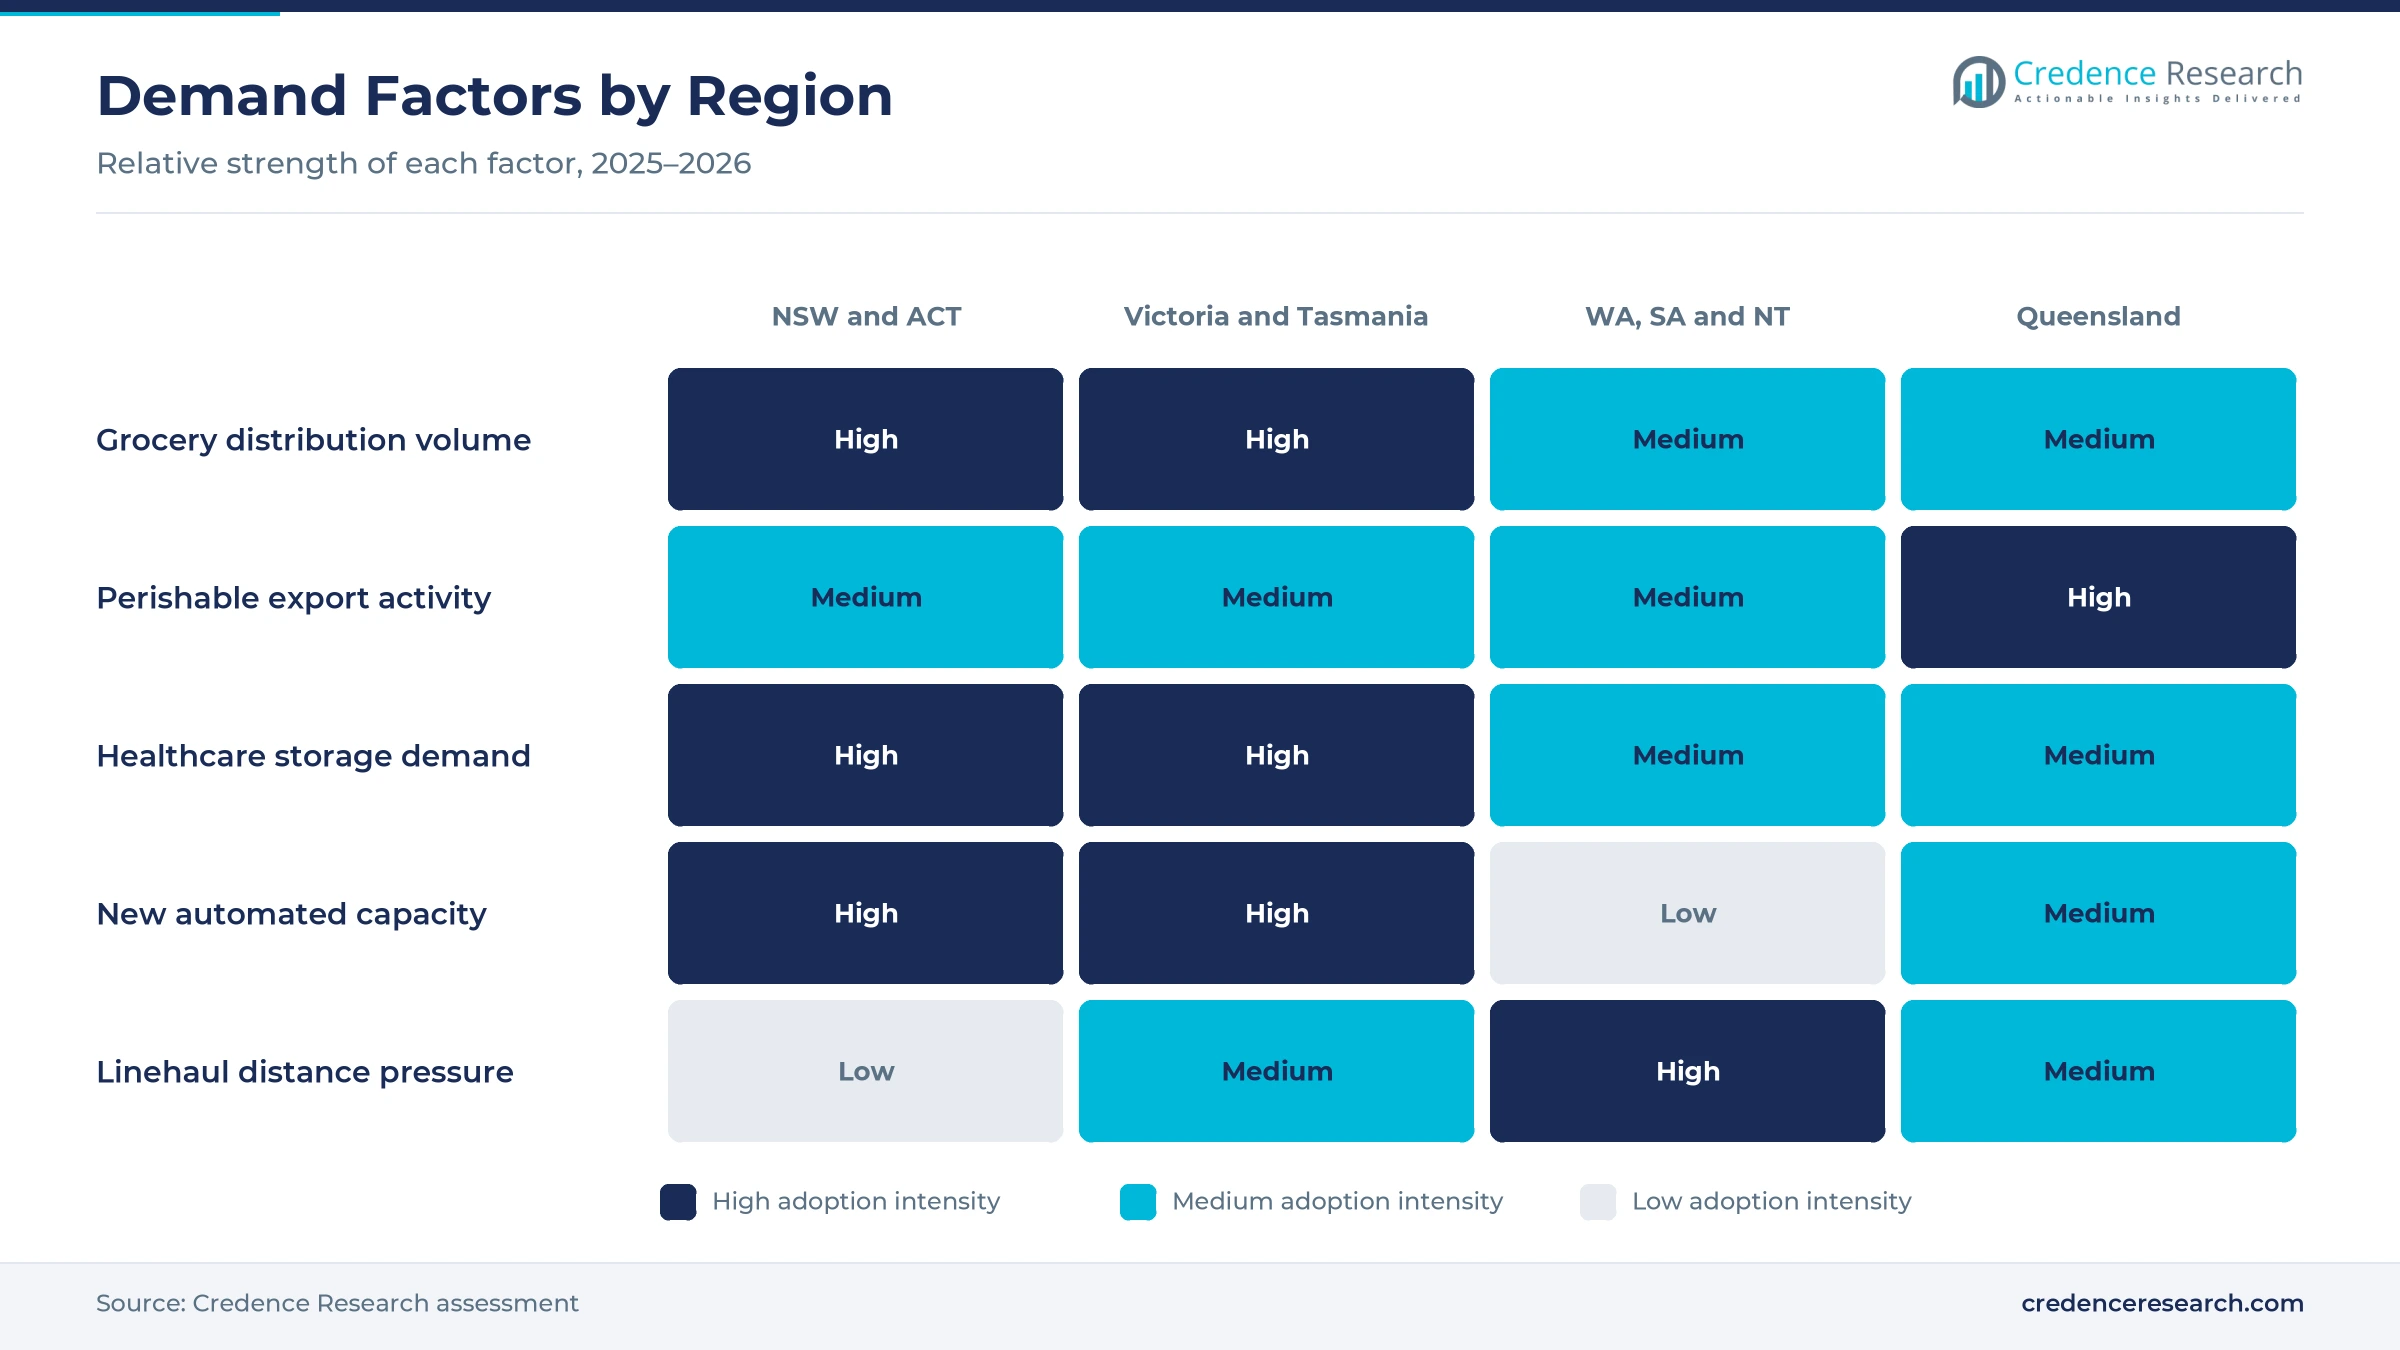
Recurring food distribution keeps volumes rising, because chilled and frozen groceries must be restocked in stores every day. Australia's population reached 27.92 million at March 31, 2026, up 392,700 over the year, according to the Australian Bureau of Statistics. Victoria and Queensland each grew 1.6% over the same year, which adds shoppers in the two fastest-growing large states. Farm production was also forecast at A$86.2 billion for 2024-25, up 4%, which raises the volume of produce, meat and dairy entering cold stores. As a result, retailers and wholesalers hold a 41.0% share of 2025 value, as grocery chains contract chilled transport for frozen food, dairy and fresh produce.
Why does healthcare service complexity raise service value?
Healthcare service complexity raises service value, because medicines and vaccines must stay within narrow temperature ranges from warehouse to patient. National guidelines say vaccines should be stored between 2 and 8 degrees Celsius, and many are damaged outside that range, according to the Department of Health. In December 2024, DHL Supply Chain announced more than A$46 million of automation projects, including a 1,350 square meter cool room at Horsley Park in New South Wales. Toll Healthcare also leased a 10,000 square meter temperature-controlled site at Melbourne Airport for at least 10 years. In turn, pharmaceutical and healthcare grows at 6.56% a year, as clinics replace older vaccine fridges with outsourced storage.
How does perishable export handling lift port-linked demand?
Perishable export handling lifts port-linked demand, because chilled and frozen meat, dairy and produce must be held and loaded at controlled temperatures. Agricultural exports were forecast at A$68.5 billion for 2024-25, or A$72.6 billion including fisheries and forestry. Beef exports reached a record 1.4 million metric tons in fiscal 2024-25, according to Meat & Livestock Australia, with strong gains in China, South Korea and the United States. Chilled red meat exports also rose 11% to 44,715 metric tons in June 2025 alone. As a result, Queensland grows faster than the other regions, as beef processors near Brisbane and northern ports book more blast freezing and container plug-in capacity.
Why does automated storage capacity support growth?
Automated storage capacity supports growth, because new high-bay frozen stores handle more pallets with fewer workers. In June 2025, NewCold said it would add 100,000 frozen pallet positions in Sydney by October 2026 and 80,000 in Melbourne by July 2026. The Melbourne expansion takes that site to 405,000 pallet positions, including 140,000 chilled and ambient spaces. In August 2023, Americold also acquired a temperature-controlled facility at Ormeau in Queensland with about 10,000 pallet positions and room to expand. These projects add frozen space near the largest consumer and export markets. In turn, operators invest in warehouse automation near Sydney and Melbourne, where most grocery and import volumes are handled.
Fleet deals and electric trucks reshape service networks
How is the rise of fleet acquisitions changing coverage?
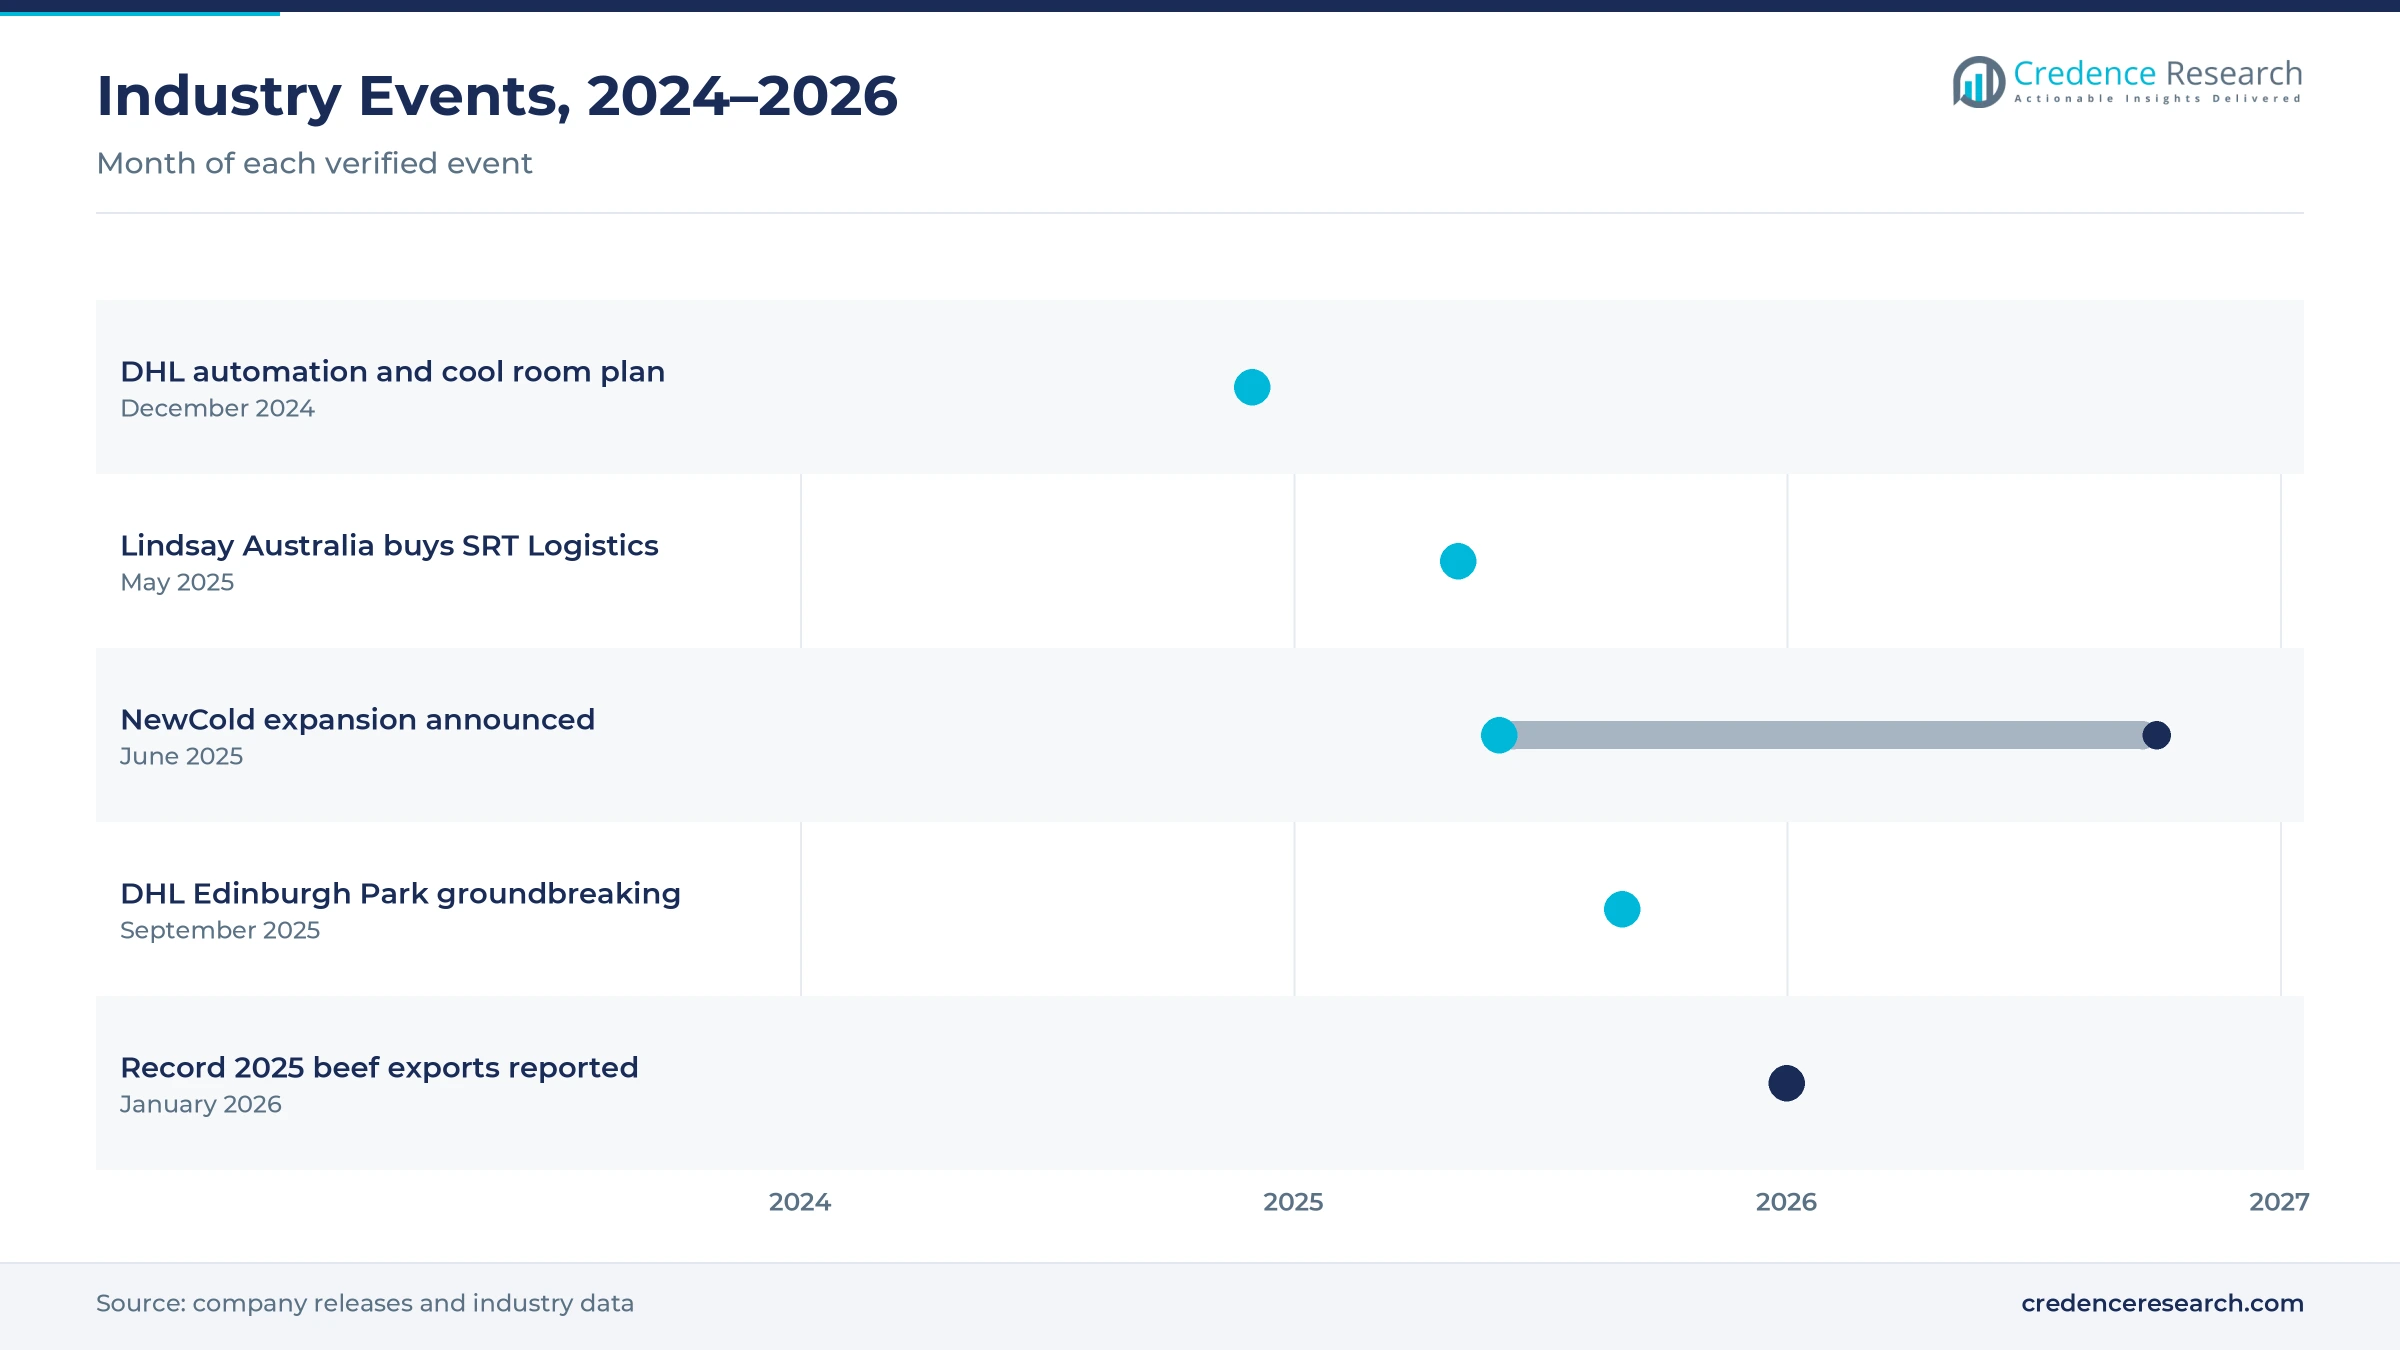
The rise of fleet acquisitions is changing coverage, because national operators want regional refrigerated carriers with local customers and depots. In May 2025, Lindsay Australia agreed to buy SRT Logistics for A$108.2 million, adding Tasmania's largest provider of refrigerated supply chain services. SRT serves horticulture, wholesale and retail food businesses with inbound and outbound freight across Bass Strait. NewCold also bought the transport company Karras, founded in 1976, to link its stores with its own trucks. Lineage entered Australia earlier through its 2019 takeover of Emergent Cold and now reports more than 500,000 pallet positions, including more than 340,000 in Victoria and New South Wales. As a result, Victoria and Tasmania hold 24.6% of 2025 value, as combined storage and transport offers win more contracts from food producers.
Why is the shift to electric refrigerated trucks gaining ground?
The shift to electric refrigerated trucks is gaining ground, because retailers want lower emissions from daily store deliveries. Linfox put a refrigerated Volvo FL Electric into service for Woolworths Group in Melbourne, carrying up to eight pallets with a range of up to 200 kilometers. The truck recharges at the Melbourne Fresh distribution center while it unloads, and a full charge takes nine hours. Linfox and Woolworths have worked together on electric vehicles since 2018, and Woolworths supplies more than 1,000 supermarkets nationally. Linfox also set a goal in 2007 to halve its greenhouse gas emissions and reports that it met it. In turn, urban delivery contracts increasingly specify electric trucks for short chilled routes.
Can Asian demand for chilled beef open new export capacity?
Asian demand for chilled beef opens room for new export capacity, because record volumes need more blast freezing, storage and container handling. Australian beef exports reached a record 1,545,759 metric tons in calendar 2025, more than 202,000 metric tons above the previous record. China took 272,939 metric tons, Japan 257,378 metric tons and South Korea a record 221,350 metric tons during the year. Exports to the United States also hit a record 453,305 metric tons of chilled and frozen beef. As a result, air-gateway-linked services grow at 6.12% a year, the fastest mode, as high-value chilled cuts and premium beef move to Asian buyers.
Is there room for life sciences hubs in smaller states?
Life sciences hubs in smaller states create room for providers, because healthcare networks want local stock instead of long trips from Sydney and Melbourne. In September 2025, DHL Supply Chain broke ground on a 20,000 square meter facility at Edinburgh Park in South Australia, due in the third quarter of 2026. The site will offer ambient, temperature-controlled and cold chain storage for its life sciences and healthcare network. DHL also said it is investing in Adelaide, Brisbane and Perth to expand services in those cities. South Australia alone had about 1.92 million residents at March 31, 2026. In turn, healthcare providers grow at 6.36% a year, the fastest customer group through 2035.
Energy costs, driver shortages and distance strain margins
How do energy costs squeeze cold store margins?
Energy costs squeeze cold store margins, because freezers and chillers run around the clock in a hot climate. Electricity is one of the largest operating costs for frozen warehouses, especially in summer peaks. As a result, operators that sign fixed-price contracts can lose money when power prices rise. Providers respond with rooftop solar, better insulation and automated high-bay stores that cool less air per pallet. Some also shift heavy freezing work to cheaper off-peak hours.
Why do driver shortages limit refrigerated fleets?
Driver shortages limit refrigerated fleets, because long-haul routes need licensed heavy vehicle drivers who will work nights and weekends. Regional operators find it hardest to recruit and keep younger drivers on long routes. In turn, some trucks sit idle during harvest peaks and export surges. Carriers respond with training programs, better rosters, relay driving between depots and more freight moved by rail on long corridors.
How do long distances raise service costs?
Long distances raise service costs, because freight between Perth, Darwin and the east coast travels thousands of kilometers. Trucks need refrigeration fuel, rest breaks and backup units for each trip. As a result, rates for remote areas are far higher than city deliveries. Providers respond with consolidated loads, shared-user depots and rail links that cut cost per pallet on the longest routes. Backhaul loads also help fill trucks returning from remote towns.
Why do compliance rules add cost for healthcare freight?
Compliance rules add cost for healthcare freight, because medicines need validated storage, temperature records and qualified staff. Each breach can force a product write-off and a report to the customer. In turn, smaller carriers struggle to win healthcare contracts from drug makers and hospital groups. Providers respond with data loggers, validated packaging, audited cool rooms and staff training that meet the needs of drug makers and hospitals.
New South Wales leads while Queensland grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales and Australian Capital Territory | 1.80 | 33.7% | 4.82% |
| Victoria and Tasmania | 1.32 | 24.6% | 5.22% |
| Western Australia, South Australia and Northern Territory | 1.22 | 22.7% | 5.42% |
| Queensland | 1.02 | 19.0% | 5.82% |
Why do new South Wales and the ACT hold the largest share?
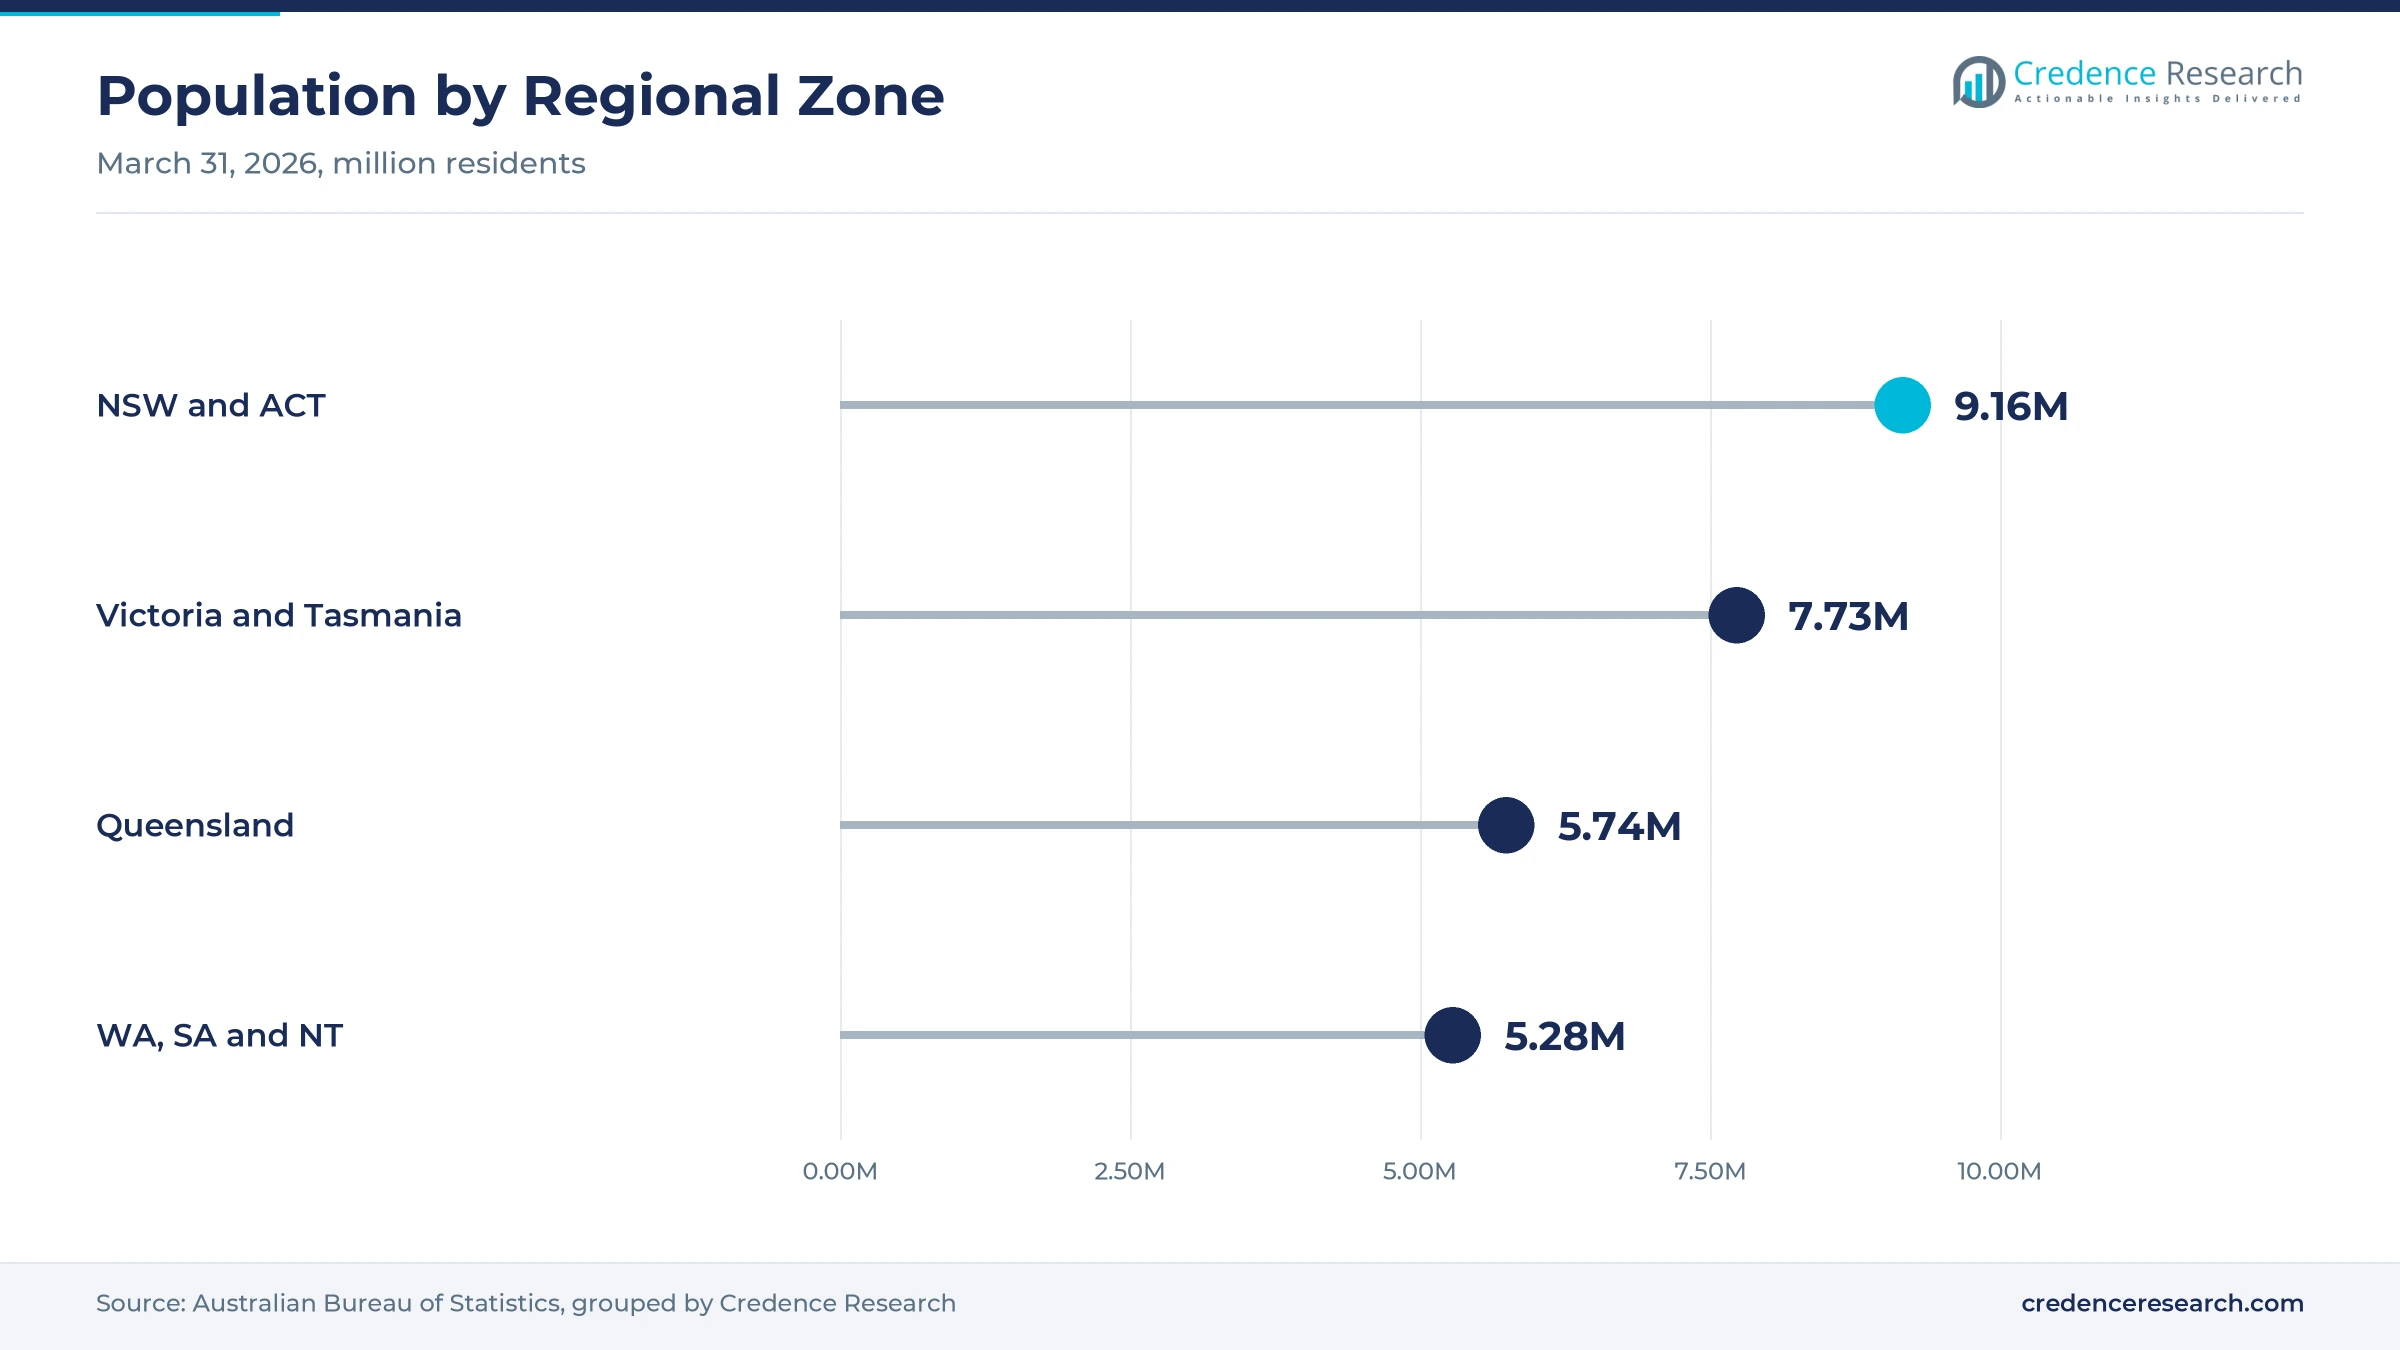
New South Wales and the Australian Capital Territory held 33.7% of 2025 value and grow at 4.82% a year, because the zone had about 9.16 million residents at March 31, 2026. Sydney hosts the busiest import gateways and the largest grocery distribution centers. However, growth is slower than in Queensland because the state already has deep storage capacity. New automated frozen stores in western Sydney should still add capacity through 2026.
How do Melbourne cold stores support Victoria and Tasmania?
Victoria and Tasmania held 24.6% of 2025 value and grow at 5.22% a year, because the zone had about 7.73 million residents at March 31, 2026. Melbourne hosts large automated cold stores and the main port for container trade. In turn, Tasmanian produce and seafood reach mainland markets through refrigerated freight across Bass Strait. The SRT Logistics deal linked that flow to a national fleet, while growing Melbourne suburbs add grocery volume each year.
Why are the western and central states important?
Western Australia, South Australia and the Northern Territory held 22.7% of 2025 value and grow at 5.42% a year, because the zone had about 5.28 million residents at March 31, 2026. Western Australia had the fastest population growth at 2.1%, and long distances make refrigerated linehaul essential. New healthcare storage at Edinburgh Park in Adelaide also adds demand from 2026. Fremantle and Adelaide ports handle chilled meat, seafood and produce exports.
How does Queensland beef and population growth lift demand?
Queensland held 19.0% of 2025 value and grows fastest at 5.82% a year, because the state had about 5.74 million residents and grew 1.6% in the year to March 2026. The state is a major beef processing and export base, and agriculture still added about 2.3% of national output in 2025, according to World Bank data. As a result, export stores near the Port of Brisbane keep adding capacity.
Automated stores and fleet deals marked 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In December 2024, DHL Supply Chain announced more than A$46 million of automation projects, including a cool room at Horsley Park. | Added 2 to 8 degree storage for up to 30 healthcare customers from 2027 |
| In May 2025, Lindsay Australia agreed to buy SRT Logistics for A$108.2 million. | Added Tasmania's largest refrigerated supply chain provider to a national fleet |
| In June 2025, NewCold announced new frozen capacity in Sydney and an expansion in Melbourne. | Planned 180,000 extra frozen pallet positions across two cities by October 2026 |
| In September 2025, DHL Supply Chain broke ground on a facility at Edinburgh Park in South Australia. | Planned 20,000 square meters with cold chain storage, due in the third quarter of 2026 |
| In January 2026, industry data showed Australian beef exports reached a record 1,545,759 metric tons in 2025. | Confirmed rising demand for chilled and frozen export handling |
Automation, telematics and cleaner fleets lift efficiency
- Automated high-bay frozen stores use cranes and shuttles in deep-frozen chambers, which raises pallet density and cuts labor in hot conditions.
- Real-time temperature telematics track trailer and room temperatures on every load, which gives healthcare and export customers proof of compliance.
- Electric refrigerated trucks serve short urban routes from distribution centers to stores, which lowers emissions and fuel use.
- Validated passive packaging holds medicines at 2 to 8 degrees, 15 to 25 degrees or minus 20 degrees, which supports last-mile healthcare deliveries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
National networks compete on capacity and coverage
Competition is led by national networks that combine cold stores, refrigerated fleets and port access. Lineage reports more than 500,000 pallet positions in Australia after entering the market in 2019, while NewCold runs automated frozen stores in Melbourne and is adding a Sydney site. Americold added a 10,000 pallet facility at Ormeau in Queensland in 2023. Linfox runs dedicated grocery transport, including electric refrigerated trucks for Woolworths Group. Lindsay Australia expanded into Tasmania through the SRT Logistics deal, while Toll Group and DHL Supply Chain compete for healthcare contracts with temperature-controlled sites in Melbourne and Sydney. Rivals compete on capacity near ports, national coverage, automation, compliance records and contract length.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Lineage Logistics Australia | Cold storage network | Reports more than 500,000 pallet positions |
| NewCold Australia | Automated cold store operator | Adding frozen capacity in Sydney and Melbourne |
| Americold Australian Holdings | Cold storage network | Added 10,000 pallet site at Ormeau |
| Linfox Logistics | Dedicated contract carrier | Runs electric refrigerated trucks for Woolworths |
| Lindsay Australia | Refrigerated transport group | Bought Tasmania's SRT Logistics in 2025 |
| Toll Group | Healthcare logistics provider | Leases 10,000 square meter site at Melbourne Airport |
| DHL Supply Chain | Contract logistics provider | Building cold chain site in South Australia |
Credence Research view on Australian temperature logistics
Credence Research's view is that Australian demand for cold chain and refrigerated transport will grow steadily, because population growth, record exports and healthcare outsourcing all add temperature-controlled volume. Refrigerated transport remains the largest service, while healthcare handling adds the fastest growth from a smaller base. New automated frozen stores in Sydney and Melbourne should ease capacity limits from 2026. However, energy costs, driver shortages and long distances will keep pressure on margins. Operators with national networks and port access should gain share.
Trade, population and company data anchor the sizing
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines Australian Bureau of Statistics population data, ABARES farm production and export forecasts, red meat export statistics, health department storage guidelines, World Bank data and company announcements on cold store capacity and fleet deals. Regional shares follow the client split for 2025, while segment splits and growth rates are Credence Research estimates. Sources used are public reports, official statistics, trade press and company releases, and no interviews or surveys were used.
Export demand and automated storage carry growth to 2035
Cold chain and refrigerated transport revenue in Australia is expected to reach USD 8.96 billion by 2035, a 5.25% CAGR during 2026–2035, as food demand, exports and healthcare needs keep volumes rising. Growth should be strongest in Queensland, where beef exports and population growth meet new port-side capacity. After 2026, automated stores in Sydney and Melbourne should lower handling costs. Weaker export prices or higher power costs would lower this outlook, while faster healthcare outsourcing would raise it. Networks with automation and national coverage are expected to gain the most.
Frequently Asked Questions
How big is the Australia cold chain and refrigerated transport market?
Which service type leads cold chain spending in Australia?
Which region leads the Australian market?
How do beef exports affect cold chain demand?
What temperature range do vaccines need in Australia?
Which end-use industry is growing fastest?
Who are the leading cold chain providers in Australia?
What are the main challenges for operators?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Refrigerated Transport Services
- 1.2.2 Refrigerated Storage Services
- 1.2.3 Value-Added Cold Chain Services
- 1.2.4 Specialist Temperature-Controlled Handling
- 1.3 By End-Use Industry
- 1.3.1 Food and Beverage
- 1.3.2 Perishable Food Exports
- 1.3.3 Pharmaceutical and Healthcare
- 1.3.4 Temperature-Sensitive Non-Food Products
- 1.4 By Mode of Transport
- 1.4.1 Road-Linked Services
- 1.4.2 Sea-Gateway-Linked Services
- 1.4.3 Air-Gateway-Linked Services
- 1.4.4 Rail-Linked Services
- 1.5 By Customer Type
- 1.5.1 Retailers and Wholesalers
- 1.5.2 Manufacturers and Processors
- 1.5.3 Foodservice Buyers
- 1.5.4 Healthcare Providers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 5.35 billion → 2035: USD 8.96 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Cold Chain & Refrigerated Transport Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Cold Chain & Refrigerated Transport Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Cold Chain & Refrigerated Transport Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Cold Chain & Refrigerated Transport Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Cold Chain & Refrigerated Transport Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Cold Chain & Refrigerated Transport Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Cold Chain & Refrigerated Transport Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Cold Chain & Refrigerated Transport Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 5.35 billion → 2035: USD 8.96 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Cold Chain & Refrigerated Transport Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Refrigerated Transport Services
- 12.3.7.2 Refrigerated Storage Services
- 12.3.7.3 Value-Added Cold Chain Services
- 12.3.7.4 Specialist Temperature-Controlled Handling
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Food and Beverage
- 12.4.7.2 Perishable Food Exports
- 12.4.7.3 Pharmaceutical and Healthcare
- 12.4.7.4 Temperature-Sensitive Non-Food Products
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Mode of Transport - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Road-Linked Services
- 12.5.7.2 Sea-Gateway-Linked Services
- 12.5.7.3 Air-Gateway-Linked Services
- 12.5.7.4 Rail-Linked Services
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Customer Type - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Retailers and Wholesalers
- 12.6.7.2 Manufacturers and Processors
- 12.6.7.3 Foodservice Buyers
- 12.6.7.4 Healthcare Providers
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Cold Chain & Refrigerated Transport End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Cold Chain & Refrigerated Transport Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Cold Chain & Refrigerated Transport Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Cold Chain & Refrigerated Transport Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Linfox Logistics
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Americold Australian Holdings
- 18.4 Lineage Logistics Australia
- 18.5 NewCold Australia
- 18.6 Toll Group
- 18.7 Lindsay Australia
- 18.8 DHL Supply Chain
- 18.9 CEVA Logistics
- 18.10 QMC Logistics
- 18.11 Foodboss
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

