
Market Overview:
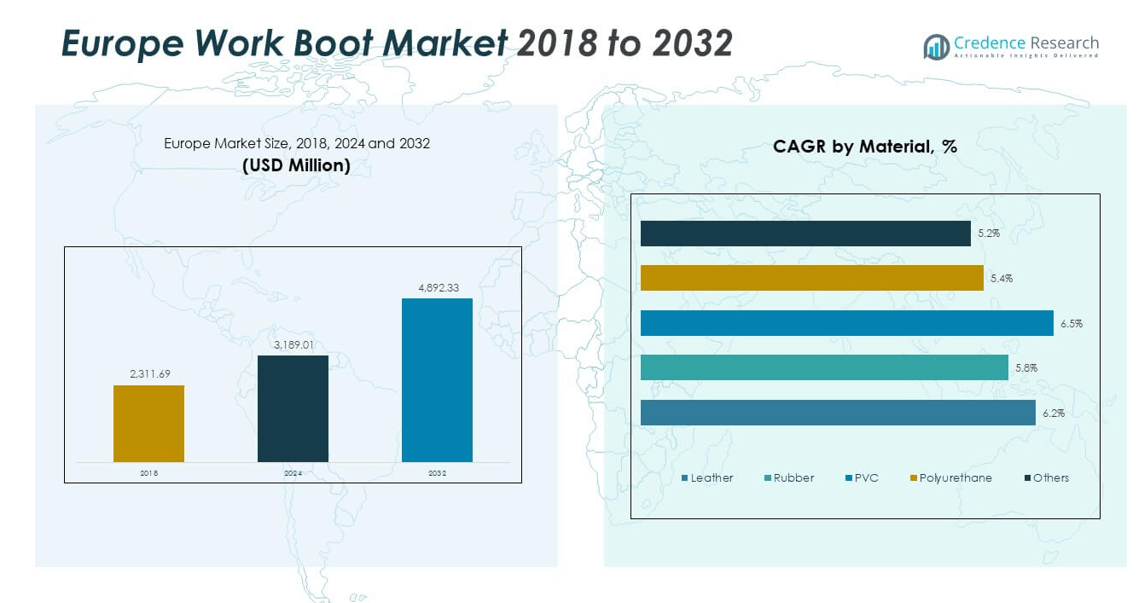
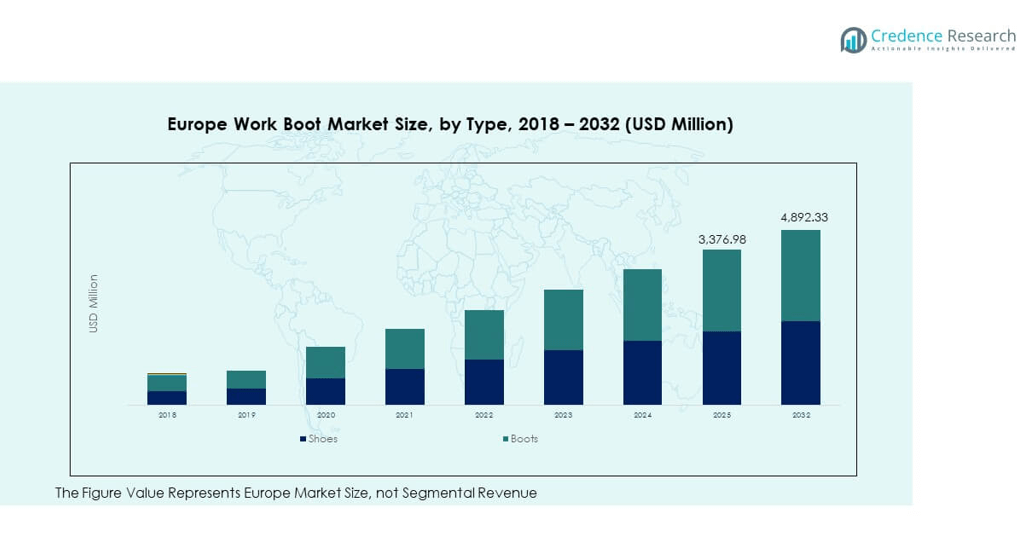
The Europe Work Boot Market size was valued at USD 2,311.69 million in 2018 to USD 3,189.01 million in 2024 and is anticipated to reach USD 4,892.33 million by 2032, at a CAGR of 5.44% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Work Boot Market Size 2024 | USD 3,189.01 million |
| Europe Work Boot Market, CAGR | 5.44% |
| Europe Work Boot Market Size 2032 | USD 4,892.33 million |
The market growth is driven by rising demand for protective footwear across industrial, construction, and manufacturing sectors. Increasing workplace safety regulations and awareness of occupational hazards are major factors encouraging adoption. Technological innovations, such as lightweight composite materials, ergonomic designs, and improved durability, enhance user comfort and productivity. Growing emphasis on sustainability and eco-friendly production processes also supports market expansion among key European manufacturers.
Regionally, Western Europe dominates the Europe Work Boot Market due to strong industrial infrastructure and strict safety compliance standards in countries like Germany, France, and the UK. Eastern Europe shows growing demand, driven by expanding construction activities and industrial modernization. Southern European nations are emerging markets, supported by tourism, logistics, and light manufacturing industries, which are steadily adopting protective footwear for improved workplace safety and performance.
Market Insights:
- The Europe Work Boot Market was valued at USD 2,311.69 million in 2018, reached USD 3,189.01 million in 2024, and is projected to reach USD 4,892.33 million by 2032, expanding at a CAGR of 5.44% during the forecast period.
- Western Europe (46%), Northern & Central Europe (31%), and Southern & Eastern Europe (23%) together dominate the regional landscape. Western Europe leads due to established industries, stringent EU safety regulations, and widespread adoption of premium-quality protective footwear.
- Southern and Eastern Europe (23%) is the fastest-growing region, supported by rising construction activities, infrastructure investments, and stronger workplace safety mandates across developing economies.
- By type, boots hold a 63% share in the Europe Work Boot Market, driven by higher durability, impact protection, and suitability for heavy-duty operations in industrial environments.
- Shoes account for 37% of the market, appealing to sectors such as light manufacturing, logistics, and maintenance services that prioritize comfort, flexibility, and lighter protection levels.
Market Drivers:
Rising Industrial Safety Regulations Strengthening the Adoption of Protective Footwear
Growing emphasis on workplace safety across construction, mining, and manufacturing sectors drives strong demand for durable protective footwear. The Europe Work Boot Market benefits from strict compliance laws like EU PPE Regulation (EU) 2016/425, enforcing the use of certified safety gear. Industries are prioritizing boots with advanced slip resistance, insulation, and impact protection. Rising construction and industrial projects in Germany, the UK, and France expand product demand. Companies focus on improving worker comfort through lightweight and ergonomic materials. It supports long-hour operations in demanding environments. Increasing penalties for safety violations encourage employers to invest in certified work boots. The growing shift toward sustainability in production enhances market credibility and growth potential.
- For instance, the UVEX 2 Construction boot was certified to S3 protection class under EN ISO 20345:2022, providing penetration resistance via its steel midsole and SRC slip resistance. The boot uses water-repellent leather and a foamed polyurethane scuffcap for durability in heavy-duty environments.
Growing Construction and Infrastructure Projects Boosting Safety Footwear Demand
Expanding infrastructure development across Europe creates new opportunities for work boot manufacturers. Ongoing residential and commercial construction projects raise the demand for heavy-duty footwear that ensures worker protection. The Europe Work Boot Market witnesses strong orders from road, rail, and renewable energy construction sectors. Governments promote worker safety to reduce on-site accidents and maintain project efficiency. The need for waterproof, anti-puncture, and reinforced designs gains prominence. Manufacturers focus on integrating comfort technologies such as shock absorption and breathable linings. It helps increase worker productivity and reduce fatigue during long shifts. The trend also supports customization based on country-specific safety standards and climate conditions.
- For instance, Dunlop Protective Footwear is internationally recognized for supplying protective boots to major rail and infrastructure projects, and its products are used in the general construction sector due to their quality and safety standards.
Technological Advancements Enhancing Product Performance and Worker Comfort
Innovations in material science are improving the durability and comfort of safety footwear. The use of composite toe caps, memory foam insoles, and anti-static soles enhances product performance. The Europe Work Boot Market is increasingly shaped by innovation that combines protection with design flexibility. Smart manufacturing technologies improve production efficiency and product consistency. Companies invest in automation and 3D modeling to reduce production errors. It enables the creation of ergonomic designs suited to multiple job environments. Integration of antimicrobial and odor-control features adds hygiene value. Continuous R&D efforts in materials like thermoplastic polyurethane (TPU) are expanding product lifespan and sustainability.
Rising Awareness of Worker Health and Comfort in Industrial Environments
Employers recognize the link between worker comfort and productivity, driving preference for ergonomic boots. Growing focus on fatigue reduction encourages adoption of lightweight, cushioned designs. The Europe Work Boot Market gains traction among industries prioritizing employee welfare and retention. Demand for boots with moisture control and temperature regulation features continues to rise. Companies integrate breathable membranes to enhance comfort during prolonged use. It reduces injuries caused by foot strain or sweat accumulation. The increasing inclusion of gender-specific designs widens customer reach across sectors. The trend strengthens the market’s alignment with employee wellness programs and corporate safety goals.
Market Trends:
Sustainability and Eco-Friendly Materials Transforming Product Development
Environmental responsibility is becoming a core focus among European footwear manufacturers. Companies are adopting recycled rubber, biodegradable leather, and water-based adhesives to minimize carbon impact. The Europe Work Boot Market is witnessing a clear shift toward sustainable material sourcing. Brands highlight eco-label certifications to meet green procurement policies. Consumers and industries prefer boots with minimal environmental footprint without compromising protection. It encourages suppliers to reengineer production lines for energy efficiency. Growing awareness of circular economy practices supports sustainable disposal and recycling initiatives. The trend also fosters brand differentiation in a highly competitive market.
- For instance, Elten GmbH launched new models with linings made of 75% recycled materials and laces made of 100% recycled content, demonstrating measurable reductions in material consumption and waste in accordance with European foot protection standards.
Digital Retail Expansion and E-Commerce Integration Strengthening Sales Channels
Online retail growth is reshaping distribution dynamics for industrial footwear. E-commerce platforms enable direct access to a wider customer base, including small contractors and independent workers. The Europe Work Boot Market experiences rapid digital adoption supported by brand-owned websites and third-party portals. Enhanced product visualization tools and AI-driven size recommendation systems improve purchase confidence. It helps manufacturers reduce returns and enhance customer satisfaction. Digital marketing campaigns target niche industrial segments and urban consumers seeking style with function. Partnerships with logistics firms ensure faster product delivery across Europe. The trend enhances competitiveness and accessibility in both B2B and B2C markets.
- For instance, leading safety footwear brands such as UVEX and Elten provide robust e-commerce solutions, allowing their products to reach customers across Europe with rapid logistics and online sales platforms backed by company data on their official websites.
Growing Demand for Custom-Fit and Ergonomic Footwear Designs
End users increasingly prefer customized solutions to match their work environment and comfort needs. The demand for tailor-fit designs reflects the broader shift toward personalization in industrial gear. The Europe Work Boot Market is adopting modular design features for flexibility in fit and support. Manufacturers are leveraging 3D scanning and digital fitting technologies to enhance accuracy. It allows the creation of boots that adapt to diverse foot shapes and working conditions. Premium brands focus on ergonomic soles that improve posture and reduce strain. This focus supports worker retention and reduces workplace fatigue. Rising awareness of health-oriented footwear reinforces this trend across Europe.
Integration of Smart Technologies in Industrial Footwear
Smart technology integration is transforming traditional work boots into connected safety tools. Embedded sensors track temperature, pressure, and step count to prevent fatigue-related injuries. The Europe Work Boot Market is adopting wearable innovations to align with Industry 4.0 environments. IoT-enabled boots can alert supervisors about hazardous movements or unsafe conditions. Manufacturers explore Bluetooth connectivity for real-time data transmission and predictive maintenance. It promotes smarter workplace safety management across sectors like logistics and construction. The integration of tech improves safety accountability while enhancing comfort. Growing R&D funding for smart PPE solutions supports this evolving trend in Europe.
Market Challenges Analysis:
High Product Cost and Competition from Low-Cost Imports Affecting Profit Margins
Premium safety footwear often carries higher production costs due to quality materials and certifications. Many local producers face pricing pressure from cheaper imports originating from Asia. The Europe Work Boot Market struggles to balance product quality with affordability in competitive segments. Manufacturers must manage fluctuating raw material prices and labor costs. It limits profitability for small and mid-sized brands competing against large global players. Some end users still prefer low-cost, non-certified alternatives despite safety risks. The challenge lies in convincing buyers about the long-term value of durable and compliant boots. Branding, warranty, and certification awareness are key to countering this issue.
Complex Supply Chains and Sustainability Compliance Burdening Production Efficiency
European manufacturers face growing challenges in maintaining sustainable and transparent supply chains. The enforcement of new environmental laws and traceability standards increases operational costs. The Europe Work Boot Market experiences delays due to sourcing constraints in leather and rubber supplies. It impacts production schedules and delivery timelines. Rising logistics costs across Europe further strain manufacturing profitability. Companies must balance environmental responsibility with cost competitiveness. Adopting circular production models requires capital investment and technical expertise. Ensuring supplier compliance with sustainability goals remains a key industry challenge.
Market Opportunities:
Expanding Demand from Women Workforce and Service Sector Employees
Rising female participation in construction, logistics, and manufacturing industries creates new opportunities for manufacturers. The Europe Work Boot Market benefits from the demand for gender-specific, stylish, and comfortable footwear. Brands design boots with better fitting, lighter weight, and aesthetic appeal to target this segment. It encourages diversification of product portfolios to attract a wider audience. Service sectors such as hospitality and healthcare also require non-slip safety footwear. The expansion of these industries fuels steady product adoption. Marketing strategies focused on inclusivity and ergonomics strengthen future growth prospects.
Adoption of Advanced Materials and Smart Manufacturing Practices
The growing shift toward advanced materials and automated production improves product efficiency and cost control. The Europe Work Boot Market leverages 3D printing, robotics, and AI for faster customization. These technologies help reduce waste and improve consistency in production. Companies investing in such innovation enhance their global competitiveness. It aligns with European Union’s sustainability and digitalization goals. The focus on comfort, lightweight design, and intelligent safety solutions creates new product categories. Partnerships with technology providers will accelerate innovation and expand market potential.
Market Segmentation Analysis:
By Type
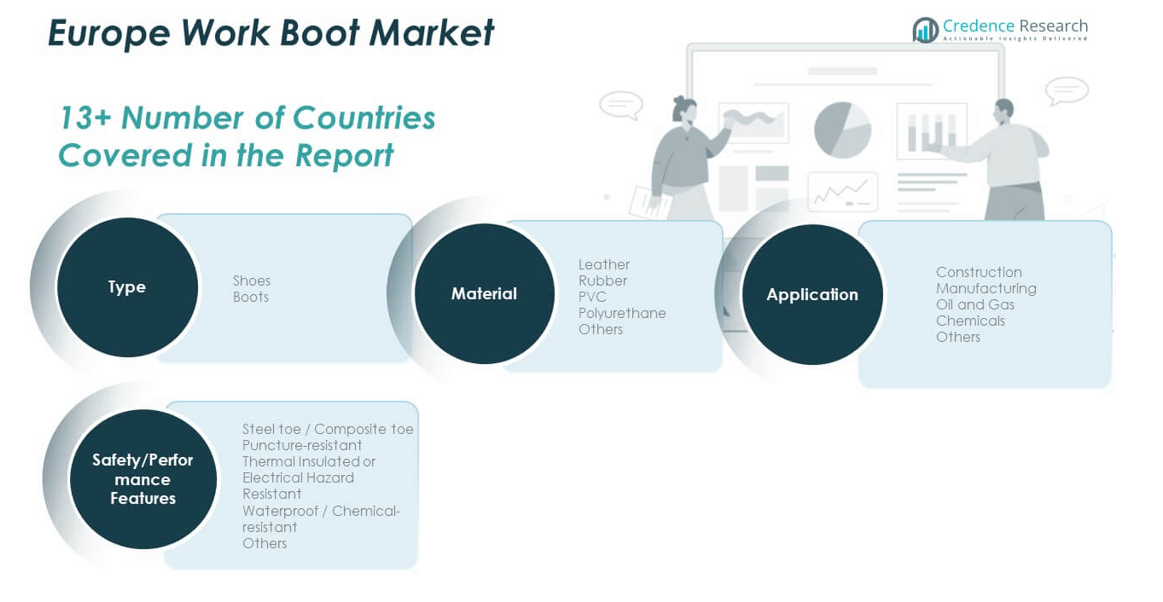
The Europe Work Boot Market is divided into shoes and boots. Boots dominate due to their superior protection, durability, and suitability for heavy industrial use. Shoes hold a steady share in sectors requiring mobility and light-duty performance. Growing demand for safety compliance and comfort features supports both categories. Manufacturers focus on designing flexible, lightweight products for diverse working environments. The introduction of hybrid models combining durability with casual styling expands adoption in non-industrial applications.
- For instance, the UVEX 2 Construction model, designed as a boot, delivers stability, all-round protection, and safe slip resistance with anatomically shaped soles, supporting workers in high-risk industrial environments. Shoes and hybrid designs, such as those listed by Elten, meet a range of standards for comfort and safety across various sectors.
By Application
Key application areas include construction, manufacturing, oil and gas, chemicals, and others. Construction leads due to strict safety mandates and extensive use of heavy equipment. Manufacturing and oil and gas sectors follow, driven by the need for protection from mechanical and chemical hazards. Chemical industries prefer boots with corrosion and slip resistance. Other applications such as logistics and maintenance services contribute through rising urban infrastructure projects and labor mobility.
- For instance, Elten GmbH’s product lines are certified for protection against heat up to 200°C and incorporate polyurethane midsoles, making them suitable for applications in construction, manufacturing, and chemical industries. These boots are CE-labeled and compliant with EN ISO 20345 for worker safety across multiple industrial settings.
By Material
Leather and rubber dominate due to their resilience, comfort, and water resistance. PVC and polyurethane materials are gaining preference for being lightweight, affordable, and easy to maintain. It enables manufacturers to serve varied climates and cost segments. Eco-friendly material development aligns with Europe’s sustainability focus. Continuous material innovation enhances durability, flexibility, and comfort across product lines.
By Safety/Performance Features
Segments include steel toe or composite toe, puncture-resistant, thermal insulated or electrical hazard resistant, waterproof or chemical-resistant, and others. Steel and composite toe designs remain in high demand for superior impact protection. Puncture and waterproof variants cater to harsh industrial conditions. Thermal and electrical hazard-resistant footwear ensure safety across diverse work settings.
Segmentation:
By Type:
- Shoes
- Boots
By Application:
- Construction
- Manufacturing
- Oil and Gas
- Chemicals
- Others
By Material:
- Leather
- Rubber
- PVC
- Polyurethane
- Others
By Safety/Performance Features:
- Steel Toe / Composite Toe
- Puncture-Resistant
- Thermal Insulated or Electrical Hazard Resistant
- Waterproof / Chemical-Resistant
- Others
By Country:
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Regional Analysis:
Western Europe – Established Industrial Powerhouse (46% Market Share)
Western Europe dominates the Europe Work Boot Market, accounting for 46% of total revenue in 2024. The region benefits from strong manufacturing, construction, and automotive sectors across Germany, France, and the United Kingdom. Strict occupational safety regulations and enforcement of EU standards drive steady product demand. The high concentration of industrial and infrastructure projects sustains consistent purchasing patterns. Manufacturers in this region focus on premium materials, ergonomic designs, and eco-friendly production methods. It maintains leadership through advanced R&D capabilities and robust distribution networks. Growing adoption of certified protective footwear across both public and private sectors continues to strengthen market maturity.
Northern and Central Europe – Innovation and Technology Integration (31% Market Share)
Northern and Central Europe collectively hold 31% of the market, supported by countries like Sweden, Finland, Denmark, and Poland. These regions emphasize innovation, safety, and technological integration in industrial operations. The Europe Work Boot Market here benefits from rapid adoption of lightweight, insulated, and weather-resistant designs suited for cold environments. Local manufacturers invest in automation and digital customization technologies. It supports higher efficiency, sustainability, and better customer experience. Industrial modernization programs and worker safety campaigns encourage widespread product adoption. High consumer awareness and preference for sustainable materials continue to shape purchasing behavior.
Southern and Eastern Europe – Emerging Construction and Infrastructure Hubs (23% Market Share)
Southern and Eastern Europe collectively represent 23% of the regional market, with Italy, Spain, Russia, and other developing economies showing strong growth. Expanding construction, logistics, and oil sectors drive increasing demand for durable, affordable work boots. Governments are strengthening occupational safety frameworks to reduce workplace injuries and enhance compliance. It creates new opportunities for international brands to enter emerging industrial zones. Local manufacturers focus on cost-effective production and regional customization. Rising infrastructure investments, especially in urban and transport projects, continue to boost long-term product adoption. Growing workforce safety awareness further enhances regional market potential.
Key Player Analysis:
- Black Diamond
- Timberland PRO
- KEEN Utility
- Skechers Work
- Red Wing Shoes
- Wolverine
- Carhartt, Inc.
- Ariat
- Sievi
- Anbu Safety
- Carolina Shoe Company
- Honeywell International
Competitive Analysis:
The Europe Work Boot Market is characterized by strong competition among established brands and regional manufacturers. Key players focus on expanding their product portfolios, enhancing safety standards, and integrating advanced comfort technologies. It emphasizes sustainable materials and lightweight construction to meet evolving industrial demands. Global brands such as Timberland PRO, Red Wing Shoes, and Honeywell International dominate premium categories through innovation and certification compliance. Regional companies like Sievi and Anbu Safety compete by offering cost-effective, durable solutions tailored to local industries. Continuous R&D and digital sales platforms strengthen competitive positioning across the region.
Recent Developments:
- In September 2025, Black Diamond unveiled its Fall/Winter 2025–26 collection, introducing mountain performance apparel such as the Recon Stretch Kit and Dawn Patrol Kit, which feature advanced waterproof materials and reinforced durability for harsh European outdoor working environments.
- In May 2025, Timberland PRO partnered with Pabst Blue Ribbon to launch a limited-edition work boot and apparel collection in US, featuring professional-grade waterproof work boots infused with PBR branding, designed for both durability and post-work relaxation; these products became available in late May and were offered through July 2025.
- KEEN Utility introduced the Stronglite work boot in late September 2025, specifically tailored for tough job environments in Europe; this model features waterproof membranes, a carbon toe, slip-resistant sole, and advanced cushioning with KEEN.FUSION bonding for improved longevity.
- Skechers expanded its performance retail concept to Europe in May 2025 by opening its first flagship performance store in Ghent, Belgium. This store showcases football, running, golf, and work boot products equipped with Glide-Technology and Hyper Burst Pro Technology-marking its strategic move to strengthen its footprint in European work footwear.
- Red Wing Shoes made a significant impact in Fall 2024 and Spring 2025 by collaborating with Fendi for the Milan Fashion Week, unveiling exclusive Classic Moc designs on global runways; these high-profile partnerships were accompanied by new men’s products and distinctive women’s styles available in Europe.
Report Coverage:
The research report offers an in-depth analysis based on type, application, material, and safety/performance features. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will increase with industrial modernization and stricter workplace safety regulations.
- Lightweight and ergonomic materials will dominate product innovation cycles.
- Digital retail and direct-to-consumer channels will expand brand reach.
- Sustainability initiatives will drive the shift toward recyclable and biodegradable materials.
- Smart boots with integrated sensors will gain traction in advanced industrial sectors.
- Construction and oil industries will remain core revenue contributors across Europe.
- Regional manufacturers will strengthen competitiveness through design flexibility and cost efficiency.
- Premium brands will continue focusing on comfort, durability, and performance differentiation.
- Technological collaborations will enhance production automation and quality consistency.
- Evolving labor laws and occupational safety standards will shape long-term demand growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Work Boot Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Europe Work Boot Market projected to grow between 2024 and 2032?
Which Europe Work Boot Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Europe Work Boot Market?
Who are the leading companies in the Europe Work Boot Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,189.01 million → 2032: USD 4,892.33 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Work Boot Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Work Boot Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Work Boot Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Work Boot Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Work Boot Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Work Boot Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Work Boot Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Work Boot Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,189.01 million → 2032: USD 4,892.33 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Work Boot Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Work Boot Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Europe Work Boot Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Europe Work Boot Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

