
Dacha plots and Chinese-made supply shape demand
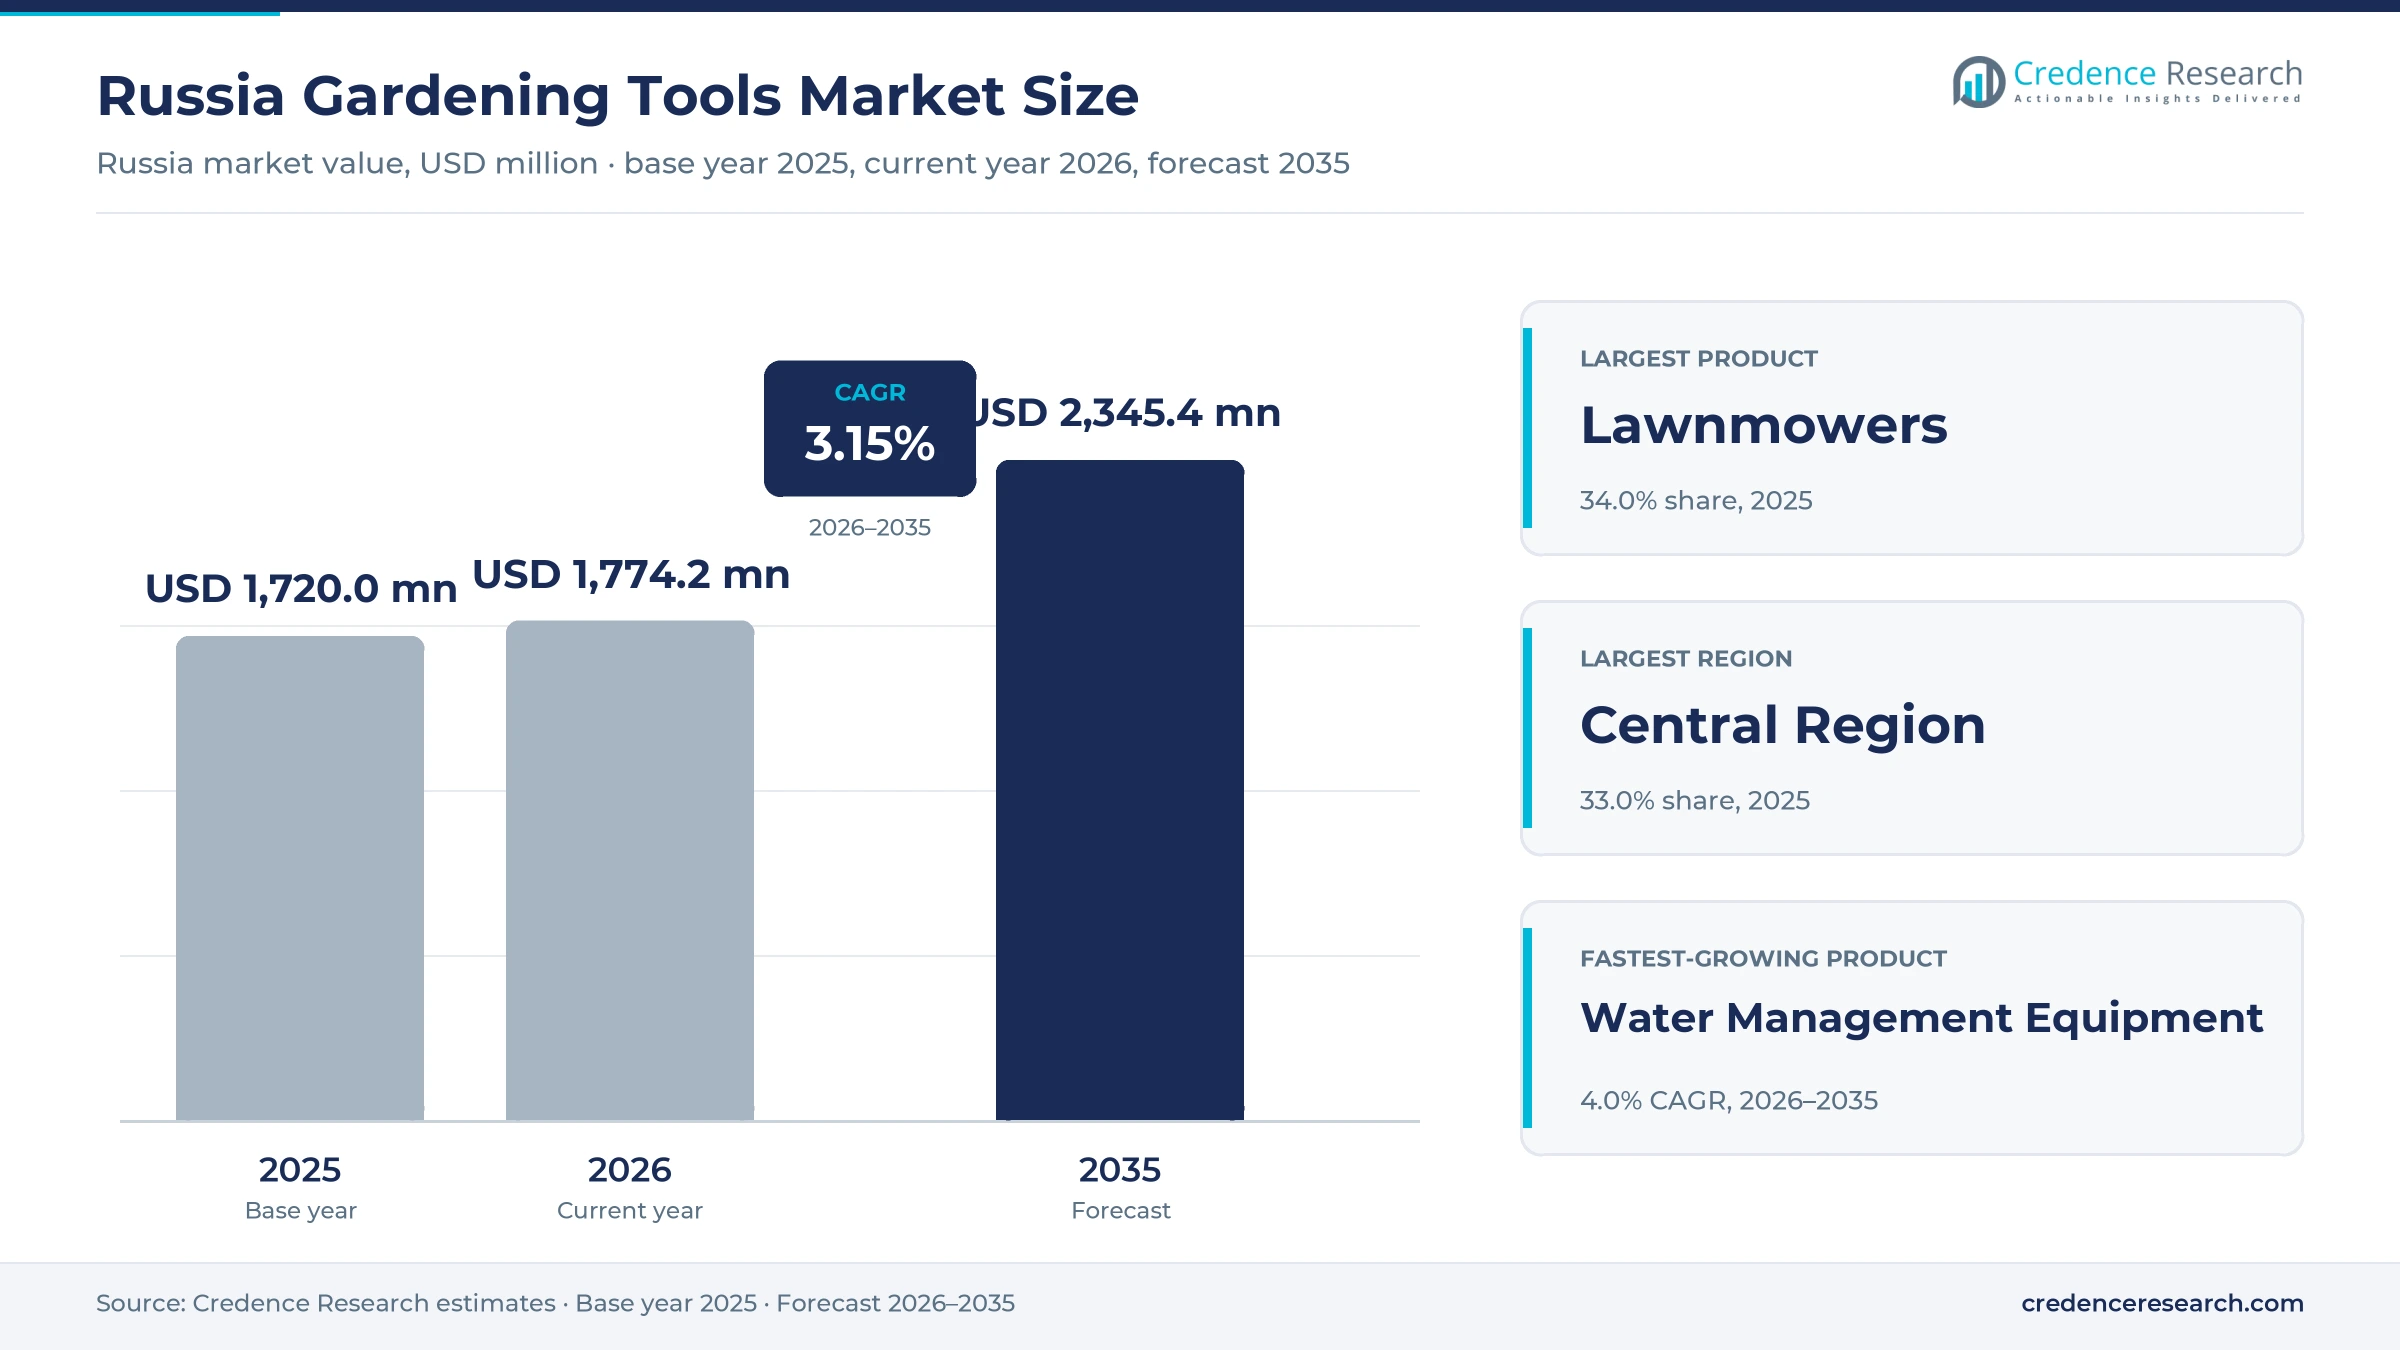
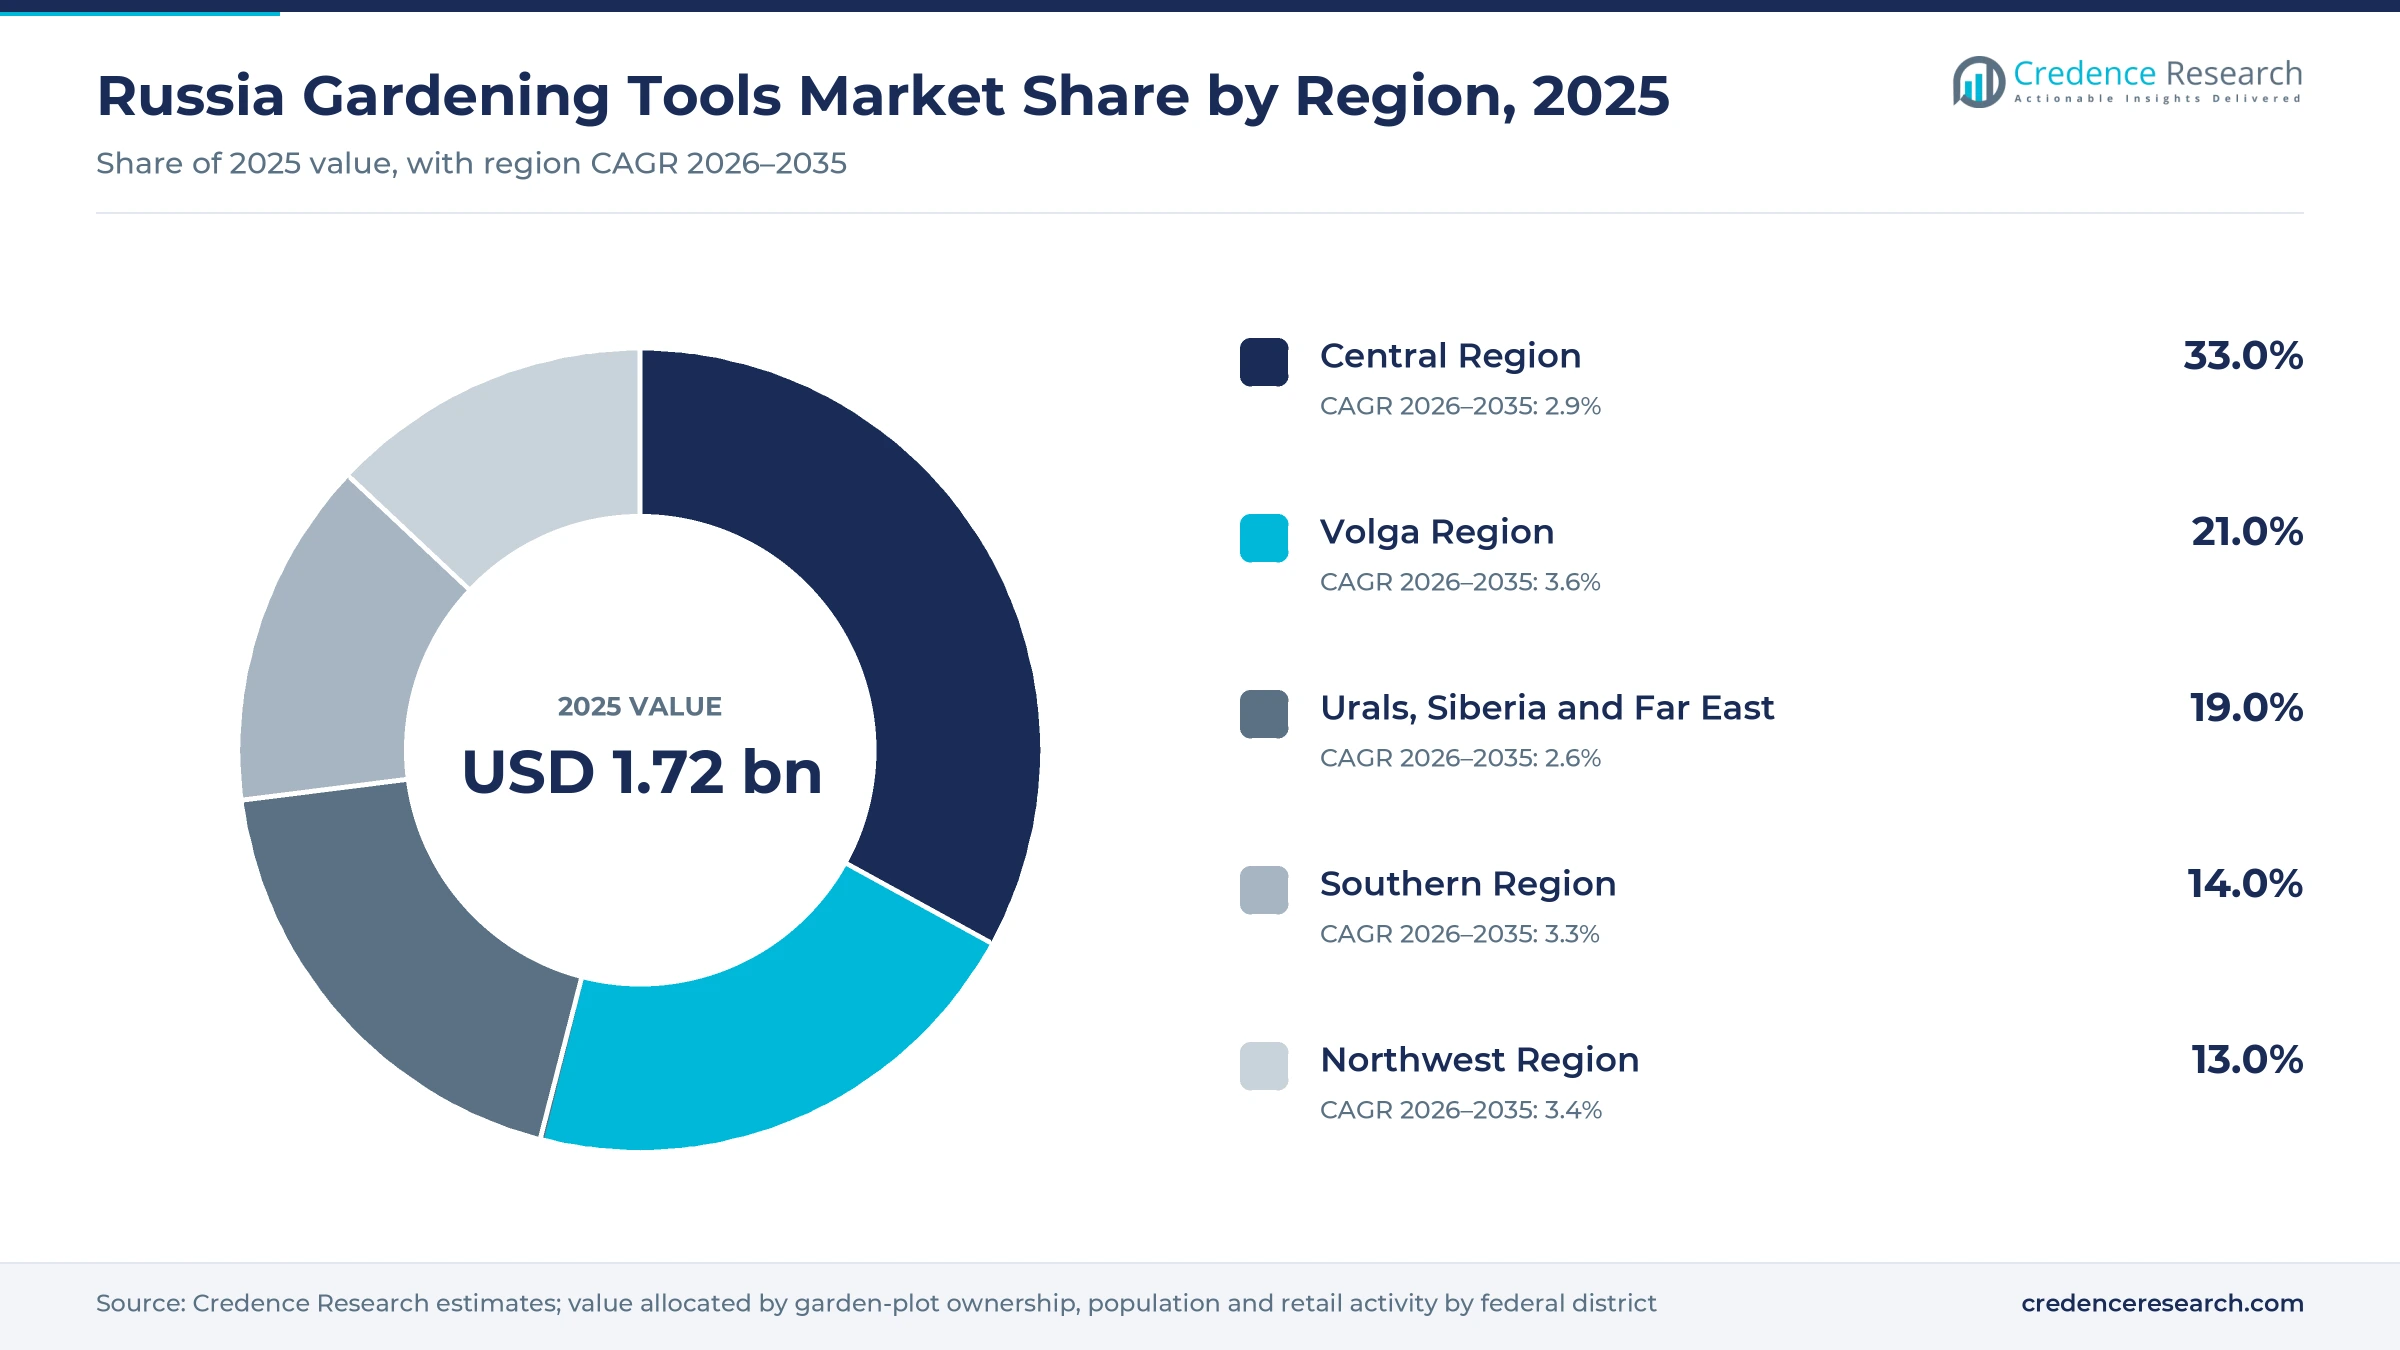
The Russia gardening tools market was valued at USD 1.72 billion in 2025 and is projected to increase from USD 1.77 billion in 2026 to USD 2.35 billion by 2035, registering a CAGR of 3.15% during 2026–2035. Demand comes mainly from owners of dacha and garden plots, who buy lawnmowers, trimmers, hand tools and watering equipment for a short spring and summer season, and from landscaping firms and property managers. Central Region held the largest regional share, 33.0% in 2025, because Moscow Oblast has the most garden-plot owners in the country. Volga Region is the fastest-growing region at 3.6% a year, as cities such as Kazan, Perm and Samara post the sharpest gains in online orders. The main commercial change since 2022 is a supply shift, with Chinese battery brands and Russian importers replacing Western makers that left or cut deliveries, while marketplaces took over a growing part of seasonal buying.
Why does seasonal stock decide who earns in Russian garden equipment?
The market counts hand tools such as shovels, rakes and pruners, powered lawnmowers, trimmers and edgers, and hoses, sprayers and drip systems sold to households and professional users. Households buy most equipment in April, May and June, so retailers and importers commit to inventory months ahead of a season that weather can shorten or extend.
Most powered equipment is made in China and sold under Chinese or Russian-owned brands, while hand tools and watering products include a larger share of domestic manufacturing. Value sits with brand owners that hold stock, run service centers and price aggressively on marketplaces, while snow throwers, garden furniture, seeds and fertilizers fall outside the scope.
Russia Gardening Tools Market Insights
- The Russia gardening tools market grows from USD 1.72 billion in 2025 to USD 2.35 billion by 2035 at a 3.15% CAGR, led by battery equipment and online channels.
- The Central Region held 33.0% of 2025 value, reflecting the largest concentration of garden-plot owners in Moscow Oblast.
- Lawnmowers held 34.0% of 2025 value, because each unit carries a check many times higher than a hand tool purchase.
- In spring 2025, average garden goods prices in Russian retail rose 15% while unit sales fell 16%, according to Kontur Market receipts.
- Brands that combine stocked warehouses near Moscow, service centers and marketplace storefronts are taking the share that Western makers gave up after 2022.
Mowers lead value while watering kits grow fastest
Segment shares and growth rates are Credence Research estimates built from retail receipts, retailer category data and the mix of household and professional buyers in Russia. Lawnmowers dominate value because of their ticket size, while watering products and online channels gain the most share through 2035.
Why do lawnmowers lead while watering kits grow fastest?
Based on product, the market is categorized into lawnmowers, hand tools, trimmers and edgers, and water management equipment. Lawnmowers led with 34.0% of 2025 value because one mower costs as much as dozens of hand tools, and unit demand held up online, with dacha owners buying 2.5 times as many lawn mowers in April and early May 2025, Kontur reported. Water Management Equipment grows fastest at 4.0% a year as buyers rebuild watering on their plots, with online sales of hoses up 200% and irrigation systems up 145% in 2025, the manufacturer Tsikl reported. Trimmers lag, as their unit sales fell 17% at VseInstrumenti.ru in spring 2025.
Households dominate and professional buyers grow faster
Based on end user, the market is categorized into residential and commercial buyers. Residential led with 82.0% of 2025 value because about 14.4 million Russians owned registered garden plots in early 2025, according to Rosreestr data reported by RBC Realty, and most of them maintain the land themselves. Commercial buyers grow fastest at 3.7% a year as landscaping firms, building operators and municipal contractors professionalize their equipment, with company purchases of garden goods at VseInstrumenti.ru up 15% in April 2026. These buyers favor petrol and high-voltage battery models with service contracts.
DIY chains still lead but marketplaces take the growth
Based on distribution channel, the market is categorized into home centers, online retail and marketplaces, hardware stores, lawn and garden specialty stores, and discount stores. Home Centers led with 31.0% of 2025 value because buyers still prefer to inspect mowers and trimmers, and Lemana PRO, the former Leroy Merlin chain, runs 143 stores, according to The Moscow Times. Online Retail and Marketplaces grow fastest at 4.3% a year as online sales of garden goods rose 185% in 2025 and marketplaces reached 20% of the category, according to Tsikl data published by Sostav.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Lawnmowers | 34.0% | Water Management Equipment | 4.0% |
| By End User | Residential | 82.0% | Commercial | 3.7% |
| By Distribution Channel | Home Centers | 31.0% | Online Retail and Marketplaces | 4.3% |
Ticket size, not volume, sets value in the category
Prices in the category span two orders of magnitude, from a few hundred rubles for a rake to tens of thousands for a mower, so the product mix decides value more than unit counts do. Most powered equipment is imported from China and priced off the yuan and the ruble, so currency moves pass into shelf prices within a season. Entry battery mowers list from about RUB 28,000, close to the average check for a mower, while premium models cost more than twice that. Brand owners keep margin through batteries and accessories, which buyers add after the first purchase. The table shows average checks and list prices, not trade terms.
| Product | Typical price or fee | Basis |
|---|---|---|
| Lawn mower, retail average check | RUB 24,064 | Kontur Market receipts, April to early May 2025 |
| Battery walk-behind mower, entry models | From RUB 28,000 to RUB 30,000; premium from RUB 75,000 | Rossiyskaya Gazeta review, July 2025 |
| Chainsaw, retail average check | RUB 9,882 | Kontur Market receipts, April to early May 2025 |
| Pruner, retail average check | RUB 1,310 | Kontur Market receipts, April to early May 2025 |
| Shovel and rake, retail average check | RUB 507 and RUB 355 | Kontur Market receipts, April to early May 2025 |
| Basic watering and care starter kit | From RUB 12,000 | Tsikl, May 2025 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Plot ownership, marketplaces and batteries lift sales
Plot registration widens the base of dacha buyers
A larger base of formally owned plots expands the pool of households that equip a garden from scratch. Registered garden plots reached about 12.5 million by February 2023, up roughly 30% in three years, Deputy Prime Minister Viktoria Abramchenko said, as reported by Interfax. Rosreestr data show the number of owners rose to about 14.4 million in early 2025, led by Moscow Oblast, Leningrad Oblast, Bashkortostan, Novosibirsk Oblast and Sverdlovsk Oblast. Purchase data from Odnoklassniki and Chek Index show the average dacha goods check rose 13% to RUB 3,564 in the first half of 2024, with tool purchases up 10%. New plot owners buy complete starter sets, which favors suppliers that bundle hand tools, hoses and an entry-level mower.
Marketplaces bring the full range to every region
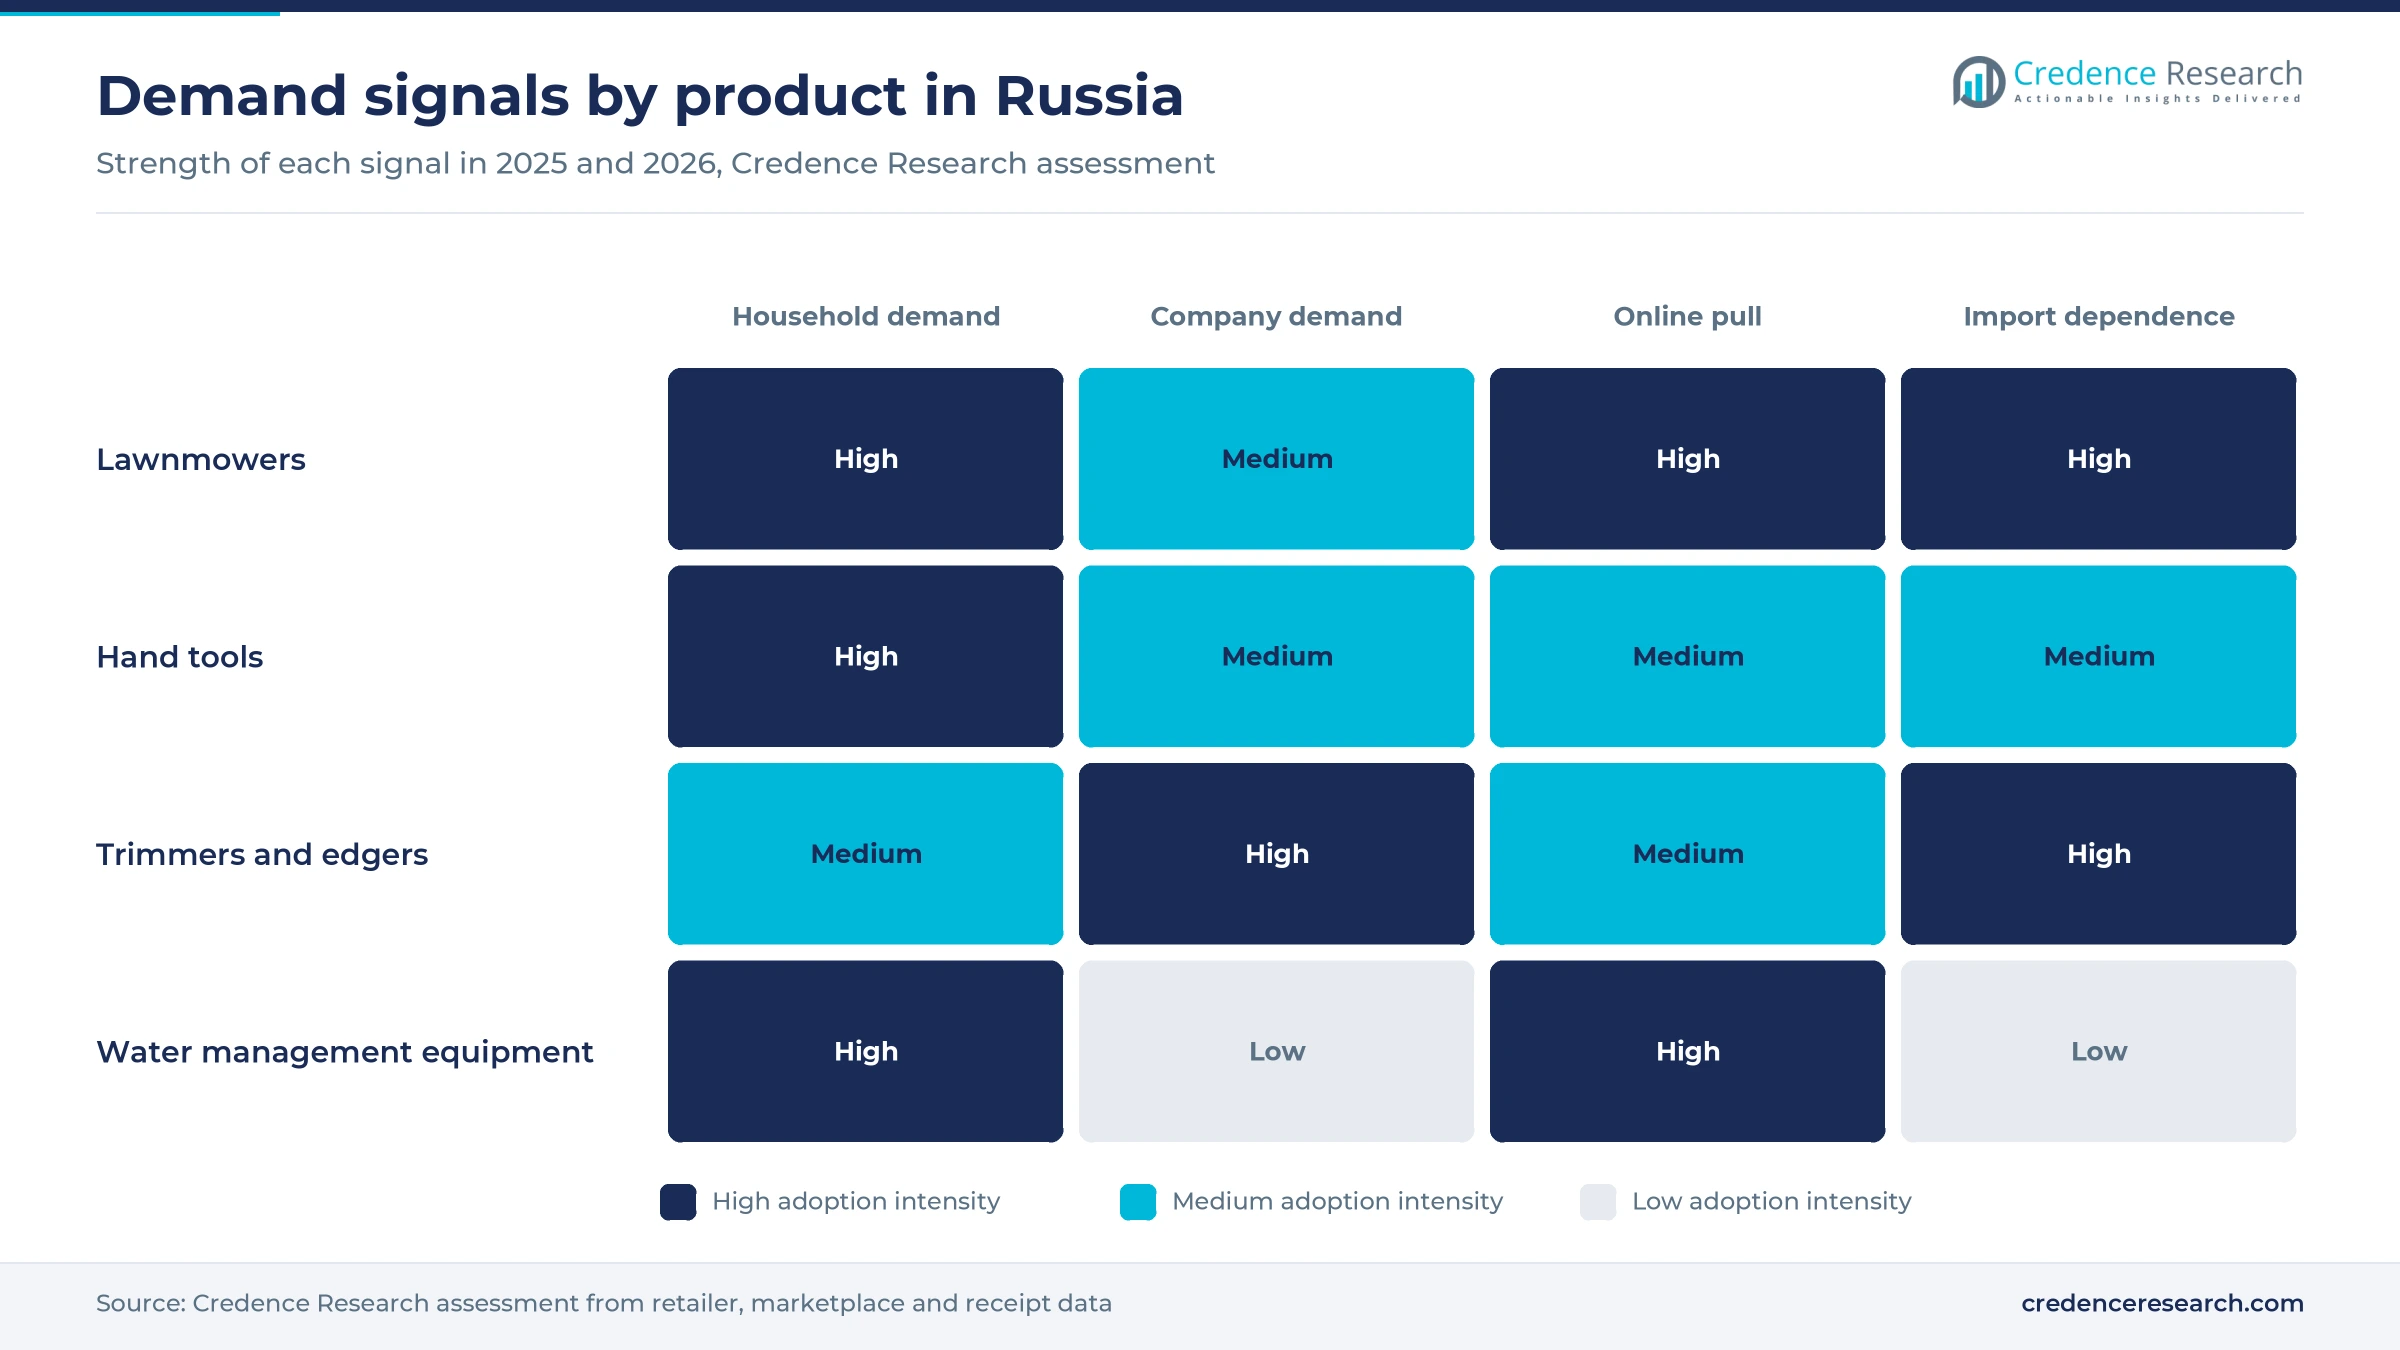
Marketplaces lift demand because they put the whole range of mowers, trimmers and spare parts in front of buyers far from a DIY hypermarket. Ozon sales of dacha goods doubled in April and early May 2025, with the garden equipment category passing RUB 2 billion and garden tools RUB 1 billion on the platform in those weeks, according to Kontur. Across DIY categories, marketplace sales rose 42.5% in 2025 while the 11 largest universal DIY chains lost 2%, Delovoy Peterburg reported. Wildberries reported its DIY category turnover up 54% in 2025, the same source said. Suppliers that manage marketplace pricing, content and delivery gain reach, while store-only brands lose visibility.
Battery platforms replace petrol in household equipment
Battery equipment raises spending per buyer, because households buy a platform of tools, batteries and chargers rather than one engine. The share of battery models in garden equipment rose from about zero in 2017 to about 30% in 2023, according to the Russian power tool trade association RATPE, as cited by Business FM in June 2025. Greenworks reported a 20% share of the battery segment in 2024 and said battery products generated 1.2% service requests per unit sold against 4.3% for petrol. Demand for battery and corded electric mowers favors brands that keep one battery voltage across mowers, trimmers and blowers.
Professional buyers re-equip for the landscaping season
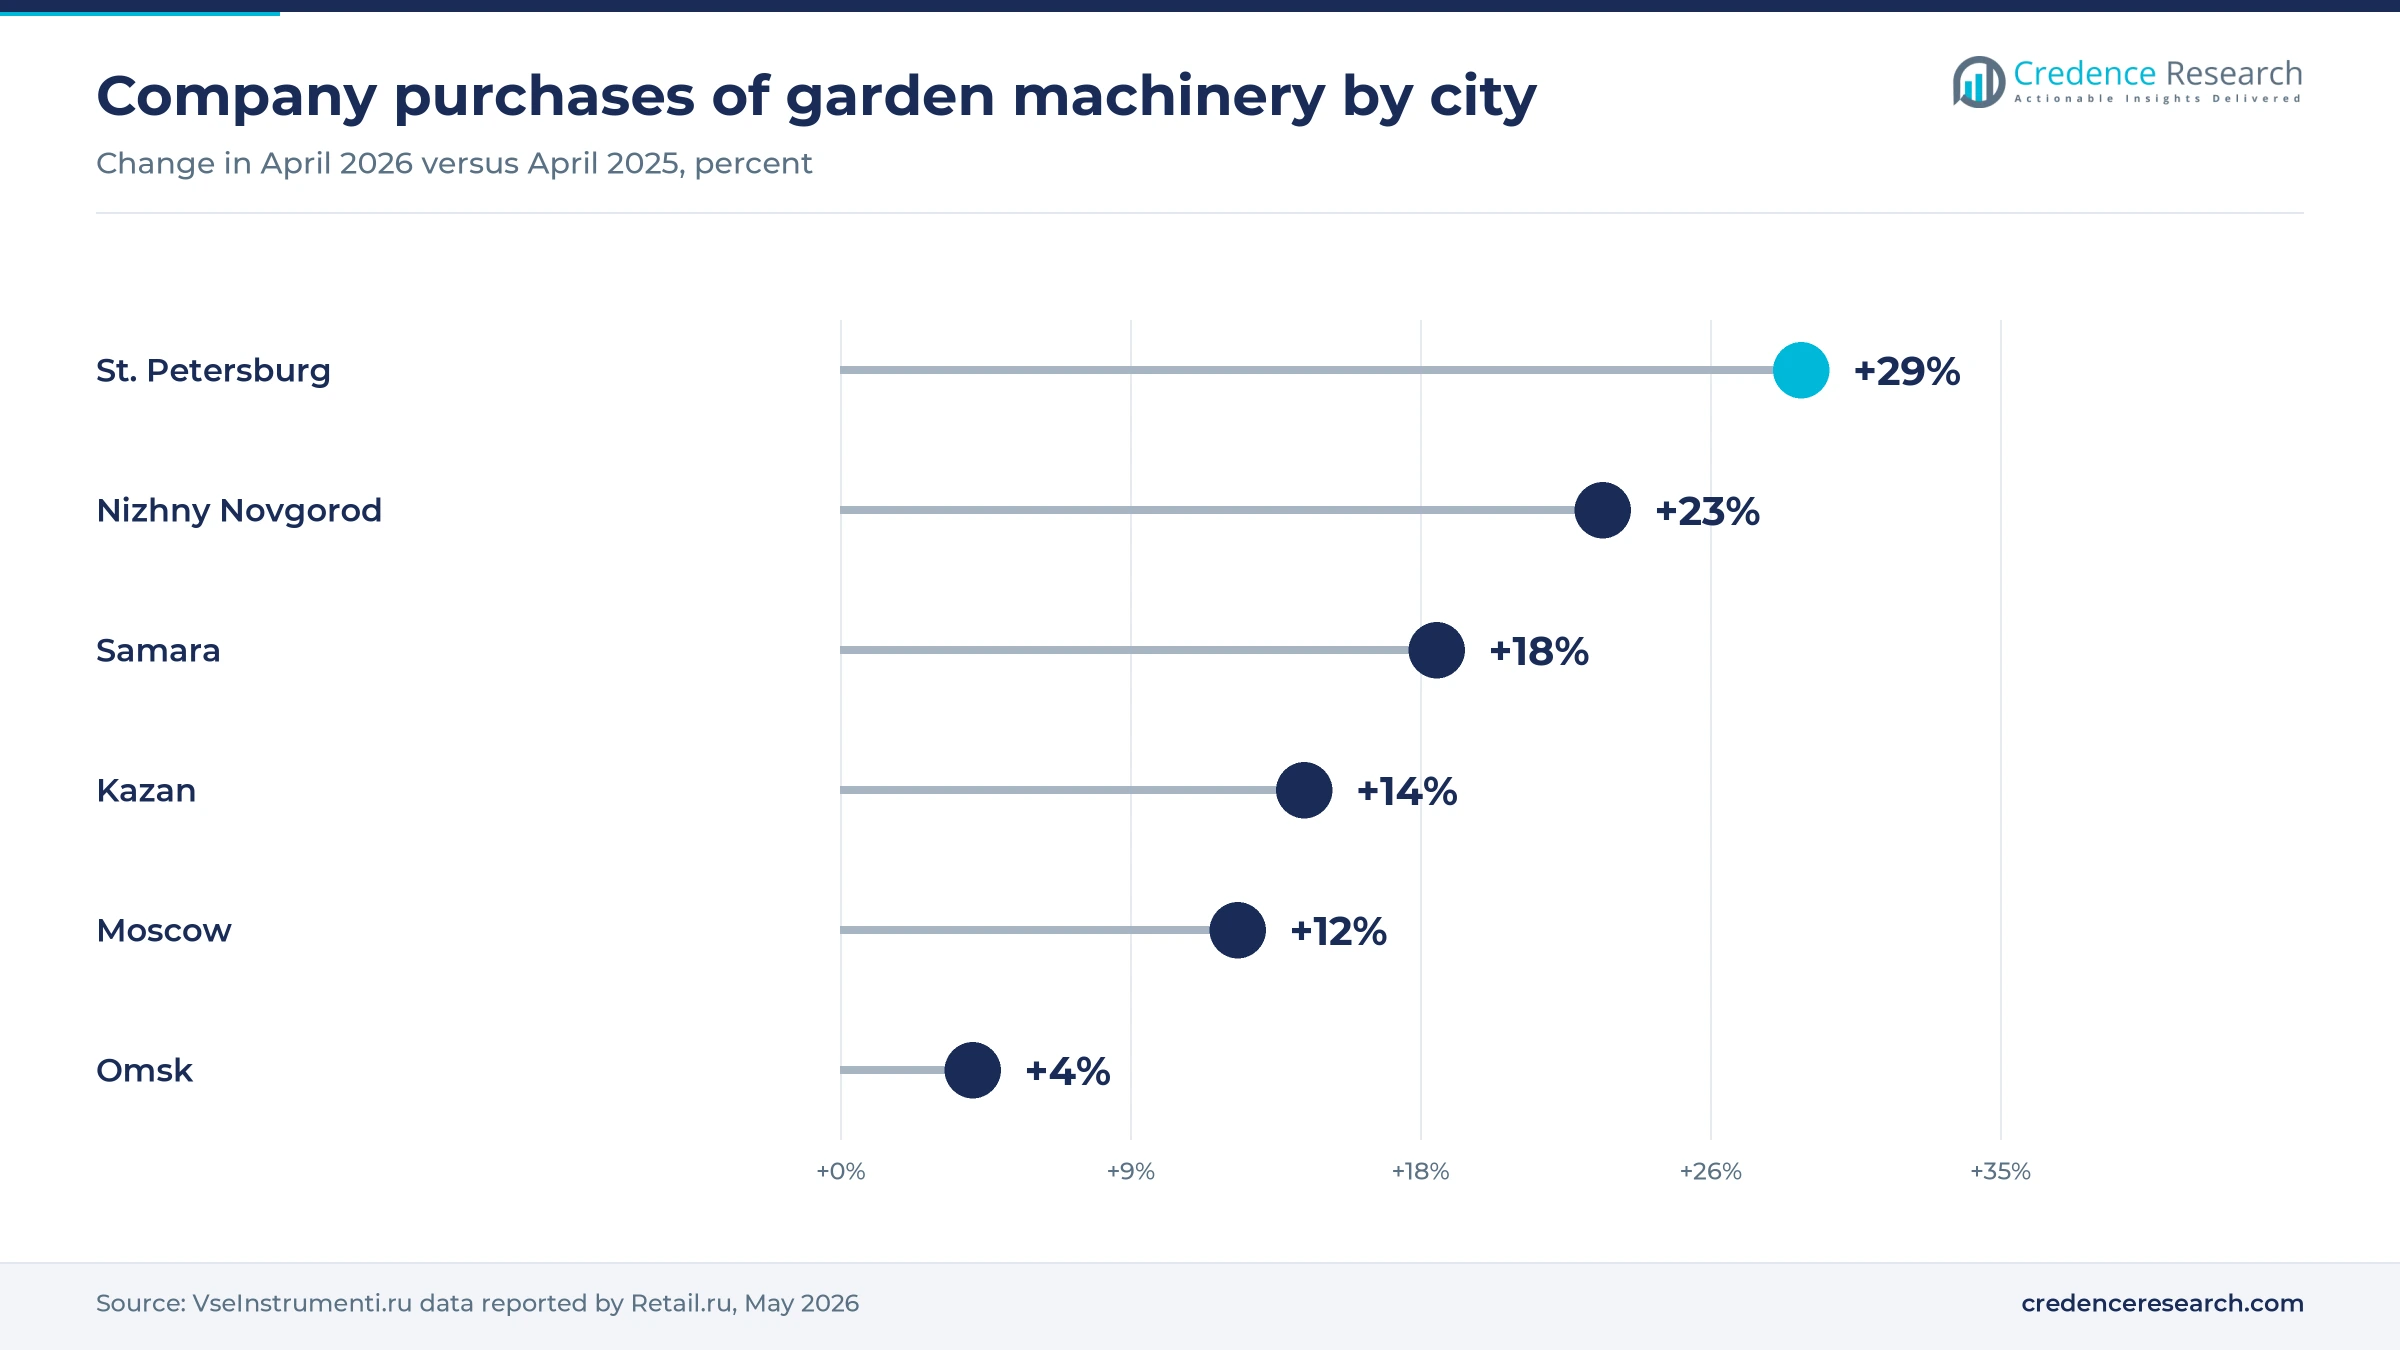
Company buyers add a second, steadier demand stream because landscaping, property and municipal contractors replace equipment on a work schedule rather than a hobby budget. Company purchases accounted for 75.2% of VseInstrumenti.ru merchandise sales in 2025, according to Retail.ru. In April 2026, its company sales of garden tools and equipment rose 1.2 times and garden machinery 7%, with St. Petersburg up 29%. Demand for wheelbarrows and construction carts rose 18% at the retailer in spring 2025. These buyers reward suppliers that offer invoicing, delivery to work sites and fast repair, and they buy petrol and high-voltage battery models that carry higher tickets than household tools.
Private labels, watering upgrades and service gaps
Retailers and importers shift toward owned brands
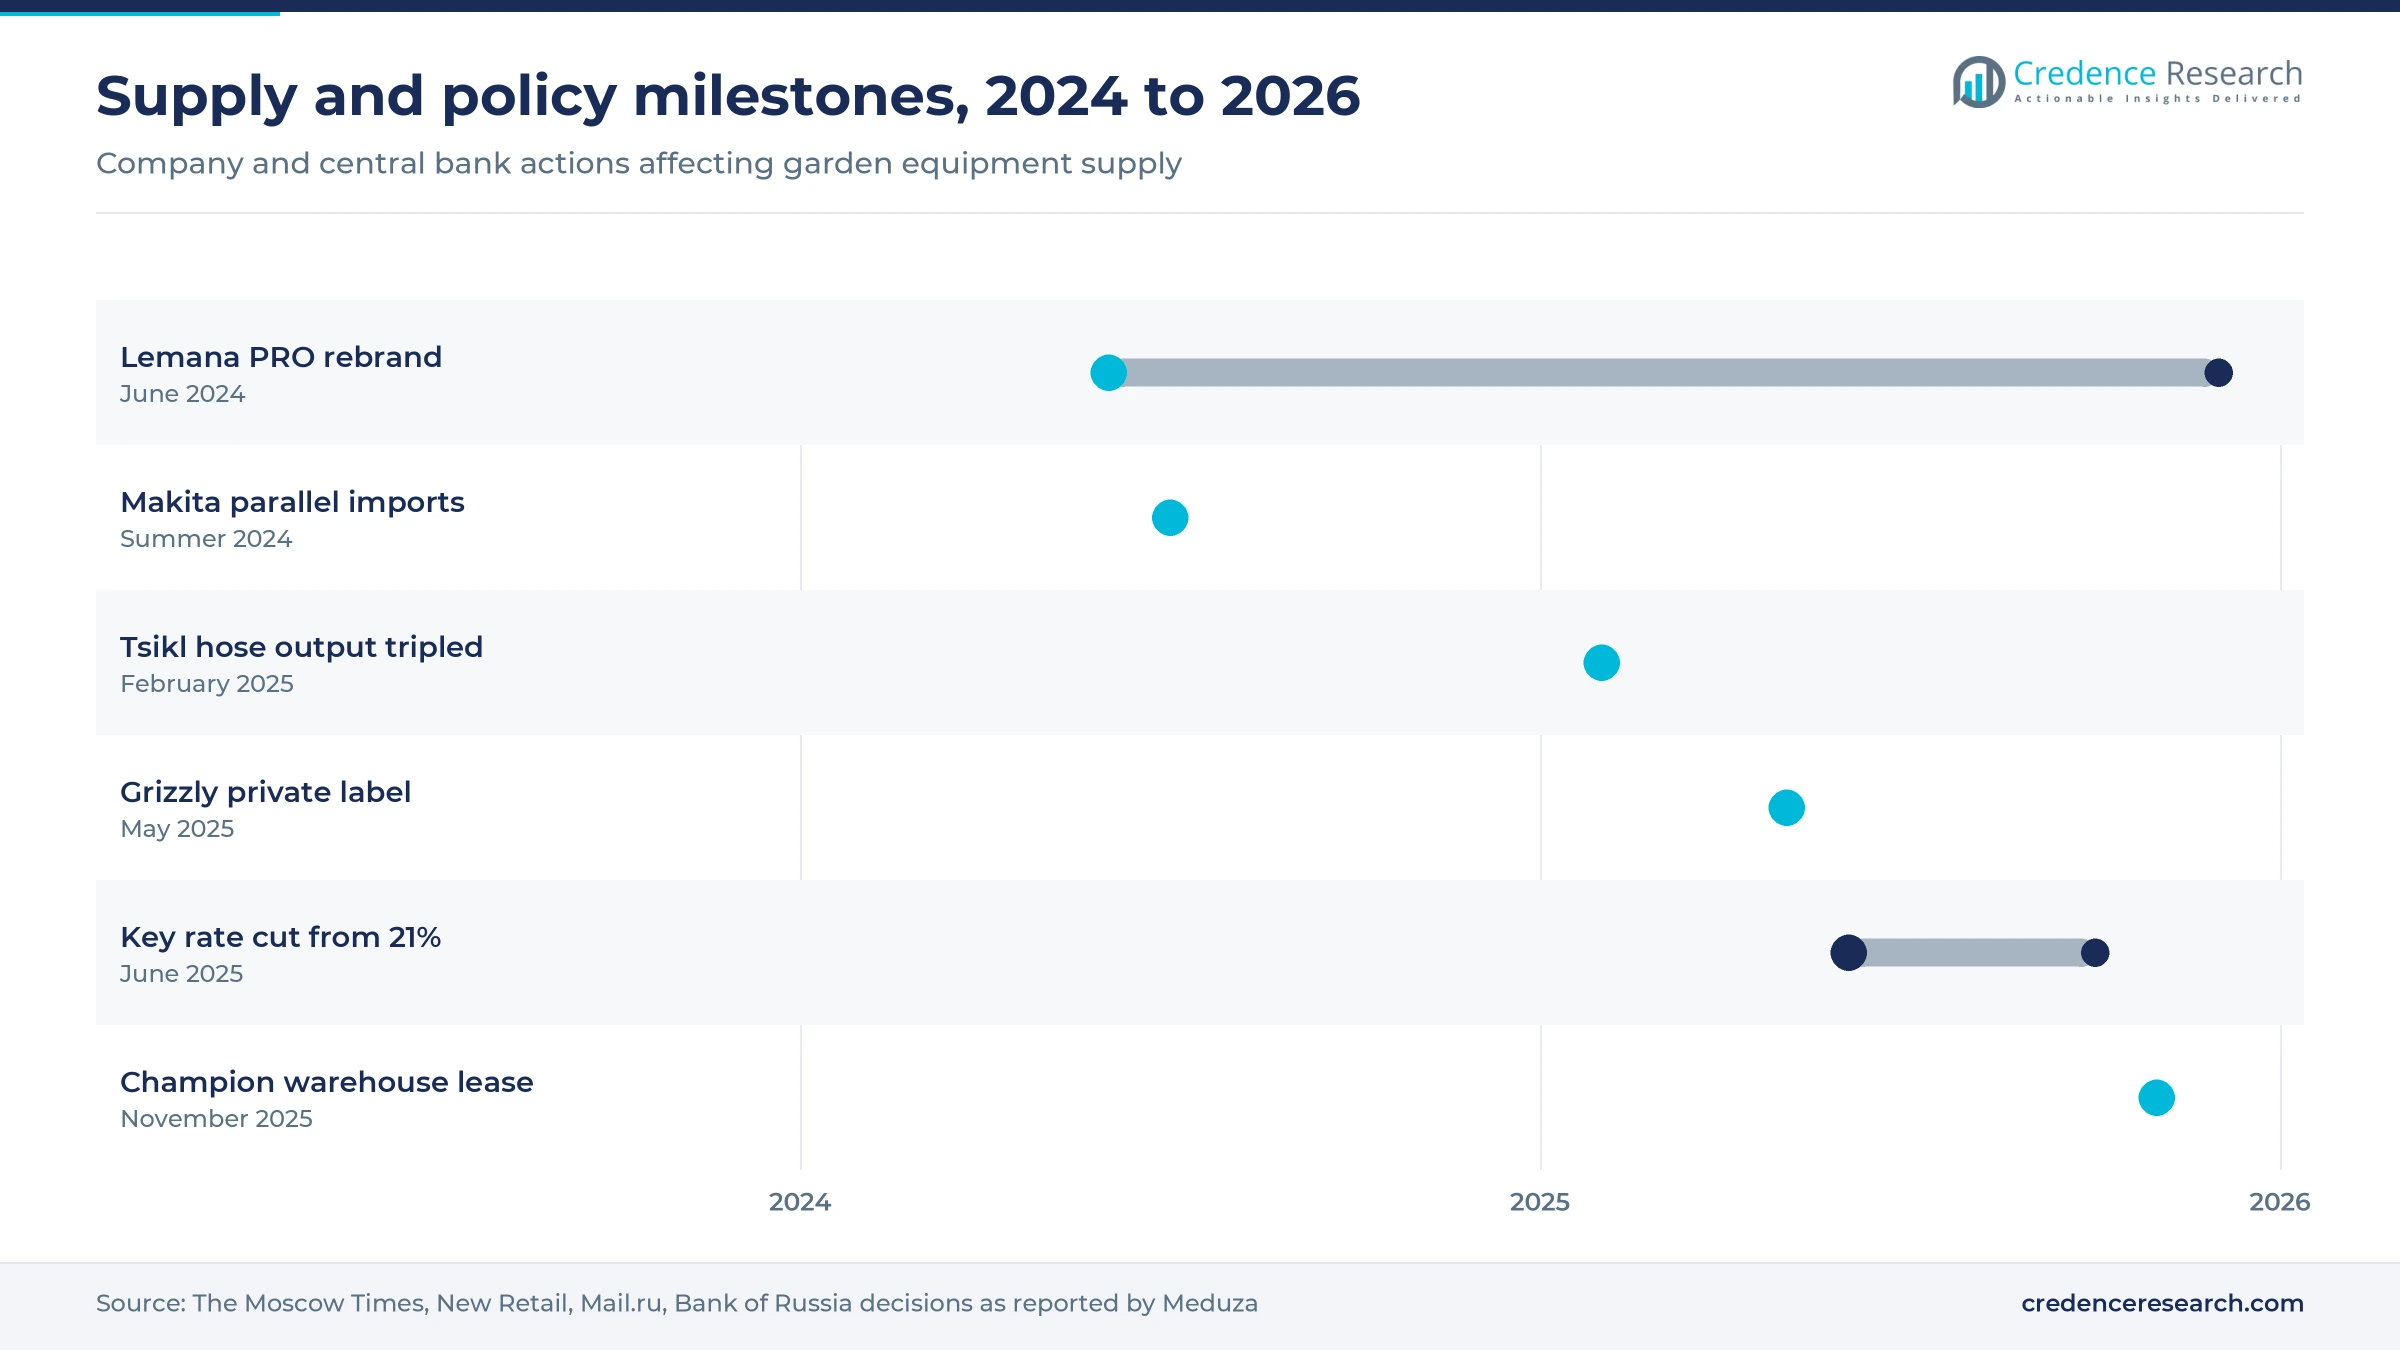
Large retailers and importers are shifting toward owned brands and owned logistics to control supply from China, creating openings for mid-priced equipment that carries a retailer warranty. VseInstrumenti.ru launched its Grizzly private label for garden machinery, generators and cleaning equipment in May 2025, with more than 150 items, New Retail reported. Vald, which develops the Champion brand, leased about 16,500 square meters of warehouse space in Pushkino, Moscow Oblast, citing supply risk for China-made goods, Mail.ru reported in November 2025. Greenworks bought about 40,000 square meters at a Domodedovo logistics park, the same report said. Stock held near Moscow shortens the reaction time to a hot or early season.
Watering upgrades emerge as summers run hotter
Households are shifting from buckets and single hoses toward drip lines, sprayers and reinforced hoses, creating openings for domestic plastics makers across watering and plant care. Tsikl, which sells the ZHUK hose brand, tripled its hose output in 2025, according to a company release carried by New Retail in February 2025. Ahead of a summer forecast as unusually hot, the company reported marketplace sales of hoses up 65% and drip systems up 42% in May 2025, with May and June accounting for about half of yearly purchases. Its premium Garden ZHUK line, launched in 2024, grew 92% in 2025, according to the Sostav data. Local production gives these suppliers shorter lead times than importers of powered equipment.
Service networks offer an opening after brand exits
The exit or retreat of Western brands leaves owners of older equipment short of parts and repair, an opening for suppliers that build service capacity. Makita held up to a fifth of the power tool market by value in 2021, 5% by the end of 2022 and no more than 1.5% in early 2025, New Retail reported in July 2025, and experts tied any recovery to restoring warranty service. Greenworks said in June 2025 that it runs about 400 service centers across the country. Husqvarna still directs Russian buyers to service centers of its local unit. Workshops and brands that repair petrol mowers and trimmers from former Western makers can capture this aftermarket.
Regional cities open a second wave of online demand
Fast online growth in Volga and Ural cities is an opening for suppliers that stock regional warehouses rather than serving every order from Moscow. In April 2026, VseInstrumenti.ru reported garden knife sales up 12 times in Kazan, six times in Perm and four times in Samara, against 1.8 times in Moscow, Retail.ru said in May 2026. Pole pruner sales rose four times in Perm and three times in Yekaterinburg, while hand combi systems rose 4.5 times in Voronezh and three times in Novosibirsk. Brands that place stock and service close to these cities can win buyers who previously relied on local markets and on slow deliveries from central warehouses.
Price inflation, costly credit and a short season
Price increases push buyers to cut volumes
Higher prices reduce the number of items households buy, which hurts sellers of low-ticket hand tools most. Average garden goods prices in Russian retail rose 15% in April and early May 2025 while unit sales fell 16%, according to Kontur Market receipts. The average pruner check rose 35% while pruner unit sales fell 40%. Discount and hardware stores are most exposed, and value lines with fewer features are the usual response.
Costly credit squeezes seasonal inventory
High interest rates raise the cost of holding stock bought months before the season, which hits importers that pay Chinese factories in advance. The Bank of Russia kept its key rate at 21% until June 2025 and had cut it only to 16.5% by Oct. 24, 2025. Small importers and regional dealers without cheap funding are most exposed, and consumer installment plans for mowers also become more expensive under these rates.
Parallel imports and counterfeits erode trust
Products that arrive without official supply carry no factory warranty, which raises risk for buyers of premium brands. Makita products entered Russia through parallel imports from summer 2024, and counterfeits caused sharp price swings, New Retail reported in July 2025. Buyers of professional equipment are most exposed, because a failed engine without warranty support stops paid work in the middle of the season.
A short season concentrates sales risk
A compressed season means one cold or wet spring can leave importers with unsold stock for a full year. Peak online sales of garden goods run up to 10 times the off-season level, Tsikl data show, a wider swing than in physical retail. Importers that commit to Chinese factory orders in winter are most exposed, and warehouse space near Moscow only partly reduces the risk.
Central Russia leads while the Volga grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Central Region | 0.57 | 33.0% | 2.9% |
| Volga Region | 0.36 | 21.0% | 3.6% |
| Urals, Siberia and Far East | 0.33 | 19.0% | 2.6% |
| Southern Region | 0.24 | 14.0% | 3.3% |
| Northwest Region | 0.22 | 13.0% | 3.4% |
Central region leads on Moscow Oblast plot owners
Moscow Oblast has the most garden-plot owners in Russia, according to Rosreestr and higher incomes there support battery platforms and premium mowers. The Central Region held 33.0% of 2025 value and grows at 2.9% a year. Major brand warehouses sit in Moscow Oblast, so buyers there get the widest stocked range. Growth trails the national rate, because Moscow was among the slower cities in the April 2026 online growth figures.
Volga Region grows fastest on city online orders
Kazan, Perm and Samara posted the largest jumps in online garden-tool orders in April 2026, which makes the Volga the most dynamic zone for sellers. The Volga Region held 21.0% of 2025 value and grows fastest at 3.6% a year. Bashkortostan ranks among the top five regions by garden-plot owners and recorded the steepest garden price rise in spring 2025, at 19%, according to Kontur. Regional stock and service points decide who captures this demand.
Urals and Siberia buy for a short, cold season
Novosibirsk and Sverdlovsk oblasts rank among the top five regions by garden-plot owners, yet a shorter season limits the use of powered equipment. The Urals, Siberia and Far East zone held 19.0% of 2025 value and grows at 2.6% a year, the slowest of the five zones. Novosibirsk Oblast retail garden sales fell only 4% in spring 2025, against 16% nationally. Company buyers in Omsk raised garden-tool purchases 4.5 times in April 2026, so professional demand partly offsets the climate.
Southern Region benefits from a longer growing season
A longer growing season in Krasnodar and Rostov raises use of trimmers and watering equipment per plot. The Southern Region held 14.0% of 2025 value and grows at 3.3% a year. Company purchases of garden tools in Krasnodar doubled in April 2026, according to VseInstrumenti.ru, while Rostov Oblast retail garden sales fell 19% in spring 2025, more than the national decline. Professional and household demand therefore move in different directions in the zone.
Northwest Region gains from St. Petersburg buyers
Leningrad Oblast ranks second in Russia by garden-plot owners, according to Rosreestr, which gives St. Petersburg sellers a dense dacha belt within reach. The Northwest Region held 13.0% of 2025 value and grows at 3.4% a year. Leningrad Oblast retail garden sales fell only 4% in spring 2025, and sales of construction and finishing materials and tools in St. Petersburg rose 68% in 2025, above the national rate, Delovoy Peterburg reported. Online sellers with local pickup points gain most in the zone.
Warehouses, private labels and Makita mark 2025
| Development | Status and market relevance |
|---|---|
| In June 2024, the former Russian business of Leroy Merlin announced its rebranding as Lemana PRO across 143 stores. | Rebranding announced; completion was planned for 2025, keeping the largest DIY chain in the garden category. |
| In February 2025, Tsikl reported that it had tripled production of ZHUK and Garden ZHUK watering hoses. | Capacity expansion completed, according to a company release; volumes are not independently verified. |
| In May 2025, VseInstrumenti.ru launched its Grizzly private label for garden machinery, generators and cleaning equipment. | Commercial launch; more than 150 items in 2025 put a retailer-owned brand against importers. |
| In July 2025, Makita reopened an official Ozon storefront and planned direct deliveries of part of its range by autumn 2025. | Plan; completion of direct deliveries is not confirmed in public sources. |
| In November 2025, Vald, which develops the Champion brand, leased about 16,500 square meters of warehouse space in Pushkino. | Lease reported; it adds stocked capacity near Moscow to cut supply risk for China-made goods. |
Battery platforms are displacing two-stroke engines
- Battery platforms from 24V to 82V let one battery serve a mower, trimmer and blower, which raises the value of the first sale and locks buyers into a brand.
- Two-stroke petrol engines still power most trimmers and chainsaws in remote plots without reliable electricity, but they carry higher service needs and fuel costs.
- Drip lines and reinforced hoses cut water use and labor on vegetable plots, and domestic makers can produce them close to buyers.
- Robotic mowers remain a small niche because few Russian plots have large lawns, although global robotic lawn mowers set the technology that battery brands bring in.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Asian brands and local importers filled the 2022 gap
Competition rests on stocked inventory, service coverage and marketplace pricing rather than on factory ownership in Russia. Greenworks reports the largest share of battery equipment and backs its position with a large service network and warehouse space near Moscow. Champion, PATRIOT and Huter sell petrol and electric mowers, trimmers and cultivators at mid-range prices through DIY chains and marketplaces. Makita is rebuilding its presence through an Ozon storefront, while Husqvarna equipment remains available through an official dealer and local service centers. Tsikl competes in watering with domestic hose production and its own marketplace storefronts. DENZEL adds premium self-propelled battery mowers at the top of the price range. Retailers such as VseInstrumenti.ru now compete with their own labels, which narrows the space for importers without a brand. Buyers compare warranty terms and spare parts as closely as prices, because many petrol models from departed brands now lack official support.
How did the supply side reorganize after 2022?
The supply side is fragmented and runs mostly on Chinese manufacturing sold under Chinese, Russian-owned and remaining Japanese and European brands. Several Western makers left or cut deliveries in 2022, as Fiskars withdrew completely on March 7, 2022 and Deere suspended shipments the same month. Interfax described STIHL as having left the market in July 2023, and Husqvarna booked restructuring costs in Russia in 2022. Entry barriers now sit in working capital, warehouse space, service networks and marketplace ranking rather than in manufacturing. Margins sit with brand owners that control stock and service, while contract factories and marketplaces earn thinner fixed fees.
Brands and suppliers that sell garden equipment in Russia
| Company | Type | Role in the market |
|---|---|---|
| Greenworks | Battery equipment maker | Battery mowers, trimmers and blowers on 24V to 82V platforms with own service centers |
| Champion (Vald LLC) | Brand owner and importer | Petrol and electric mowers, trimmers and chainsaws made in China for Russia |
| PATRIOT | Brand owner and importer | Trimmers, lawn mowers, cultivators and blowers sold through DIY chains and marketplaces |
| Huter | Brand owner and importer | Trimmers, lawn mowers, cultivators and blowers with official warranty and service |
| Makita Corporation | Power tool maker | Battery mowers and trimmers, rebuilding supply through an official Ozon storefront |
| Husqvarna Group | Outdoor power equipment maker | Mowers, trimmers and chainsaws sold through an official dealer and local service |
| Tsikl (ZHUK) | Local manufacturer | Watering hoses, sprayers and drip systems under the ZHUK brand |
| DENZEL | Brand owner | Premium self-propelled battery lawn mowers sold through Russian retailers |
Service networks, not price alone, will win share
Credence Research's view is that the Russia gardening tools category will be won on service and stock, not on the lowest price. The exits of 2022 removed brands that buyers trusted for repairs, and the receipts from spring 2025 show households cutting item counts as prices climb. Suppliers that keep parts, warranty and stock close to buyers can hold prices, while unbranded imports compete only on the shelf price. Battery platforms reward brands that keep buyers inside one system. The evidence on total sales is thin, because no official statistic covers the category, so these estimates carry a wider margin than for most consumer goods.
Estimates rest on plots, receipts and retail data
The report uses 2025 as the base year and projects values from 2026 to 2035 in U.S. dollars. This edition replaces an earlier estimate that was an order of magnitude below what ruble spending on garden equipment implies, with a value rebuilt from plot ownership, retail receipt averages and marketplace category sales. Market values come from the Credence Research model, built from garden-plot ownership data from Rosreestr, retail receipt data from Kontur Market, marketplace and retailer category data, company releases and IMF macroeconomic projections. Regional, segment and channel shares are Credence Research estimates built from the same public sources. The 2025 value converts ruble spending at an average 2025 exchange rate. No interviews or surveys were conducted for this edition, and gaps in public data are noted in the text.
Battery conversion sets the pace to 2035
Through 2035, the Russia gardening tools market depends less on new buyers than on what existing plot owners replace. Battery platforms should keep displacing petrol engines in household equipment, while petrol models hold on in remote and professional uses. Marketplaces should take a larger part of sales as regional cities catch up with Moscow, and retailer brands should claim more of the mid-price range. Watering products grow fastest by product as summers run hotter. The main risks are a weaker ruble, costly credit and a return to strict import limits, any of which would raise shelf prices and slow replacement cycles.
Ruble stability and battery uptake set the range of outcomes
The range of outcomes depends mostly on household budgets, the ruble and the speed of the battery shift. The IMF projects 1.1% real GDP growth and 5.6% inflation for Russia in 2026, which points to modest real income gains, according to its country page. A weaker ruble would raise prices of imported equipment and cut volumes, while stable rates and cheaper credit would speed the replacement of petrol mowers with battery platforms.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 1.6% | USD 2.06 billion | The ruble weakens sharply, credit stays costly and households delay mower replacement. |
| Base | 3.15% | USD 2.35 billion | Modest income growth, gradual rate cuts and steady battery conversion of household equipment. |
| Upside | 4.3% | USD 2.60 billion | Faster rate cuts, a stable ruble and wider service networks speed battery platform sales. |
Frequently Asked Questions
How big is the Russia gardening tools market?
Which product leads the Russia gardening tools market?
Which product segment grows fastest?
Which region leads demand for gardening equipment in Russia?
Did Western garden equipment brands leave Russia?
Which companies sell garden equipment in Russia now?
How fast are online sales of garden goods growing in Russia?
What restrains growth of the Russia gardening tools market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Lawnmowers
- 1.2.2 Hand Tools
- 1.2.3 Trimmers and Edgers
- 1.2.4 Water Management Equipment
- 1.3 By End User
- 1.3.1 Residential
- 1.3.2 Commercial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.72 billion → 2035: USD 2.35 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Russia Gardening Tools Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Russia Gardening Tools Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Russia Gardening Tools Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Russia Gardening Tools Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Russia Gardening Tools Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Russia Gardening Tools Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Russia Gardening Tools Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Russia Gardening Tools Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.72 billion → 2035: USD 2.35 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Russia Gardening Tools Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Lawnmowers
- 12.3.7.2 Hand Tools
- 12.3.7.3 Trimmers and Edgers
- 12.3.7.4 Water Management Equipment
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Russia Gardening Tools End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Russia Gardening Tools Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Russia Gardening Tools Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Russia Gardening Tools Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Greenworks
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Champion (Vald LLC)
- 18.4 PATRIOT
- 18.5 Huter
- 18.6 Makita Corporation
- 18.7 Husqvarna Group
- 18.8 Tsikl (ZHUK)
- 18.9 DENZEL
- 18.10 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

