
Market Overview:
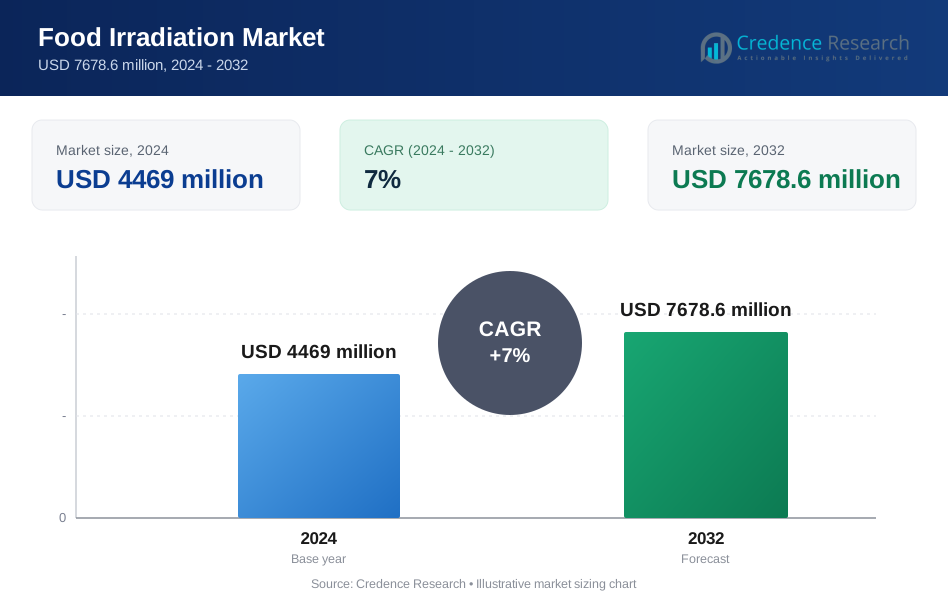
The Food Irradiation Market size was valued at USD 4469 million in 2024 and is anticipated to reach USD 7678.6 million by 2032, at a CAGR of 7% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Irradiation Market Size 2024 | USD 4469 million |
| Food Irradiation Market, CAGR | 7% |
| Food Irradiation Market Size 2032 | USD 7678.6 million |
Key growth drivers include escalating concerns over food safety, pathogen control, and foodborne illnesses, which are bolstering demand for effective preservation methods. Technological innovations—particularly in electron beam and X-ray irradiation systems—are enhancing efficiency and processing speed, further supporting adoption. Additionally, regulatory backing and harmonization efforts, along with rising consumer awareness about safe, long-lasting food products, are creating fertile ground for market expansion.
Regionally, Asia-Pacific emerged as the leading market in 2024, driven by growing regulatory acceptance, regional cooperation initiatives, and increasing consumer confidence in countries aligning with Codex and IAEA standards. North America follows closely, supported by FDA approvals for phytosanitary irradiation of fresh produce and meat, coupled with a gradual shift in consumer sentiment toward irradiated foods. Europe also contributes to market growth, though at a more modest pace, as stricter regulatory frameworks and varying levels of consumer acceptance continue to influence adoption.

Market Insights:
- The Food Irradiation Market was valued at USD 4469 million and is projected to reach USD 7678.6 million by 2032, advancing at a CAGR of 7%.
- Rising concerns over food safety and pathogen control drive adoption, with irradiation proving effective against Salmonella, E. coli, and Listeria.
- Technological progress in electron beam and X-ray systems enhances efficiency, scalability, and cost-effectiveness for commercial use.
- Strong regulatory support from bodies such as FDA, WHO, and IAEA validates irradiation and encourages broader adoption across industries.
- High capital costs and limited infrastructure availability continue to challenge market expansion, particularly in developing regions.
- Asia-Pacific holds 42% of the market, supported by regulatory cooperation, government initiatives, and rising consumer acceptance.
- North America with 28% and Europe with 19% maintain significant positions, backed by FDA approvals and selective EU regulatory frameworks.
Market Drivers:
Rising Need for Food Safety and Pathogen Control
The Food Irradiation Market is driven by the urgent demand to combat foodborne illnesses and improve overall food safety. It addresses pathogens such as Salmonella, E. coli, and Listeria, which pose significant risks to public health and supply chains. Governments and international bodies support irradiation for its ability to reduce microbial contamination without altering nutritional value. It strengthens consumer trust by delivering safer products while ensuring compliance with strict safety regulations.
- For instance, UV-C LED irradiation treatment reduced Salmonella on chicken breast by 3.48 Log CFU/cm² after 60 seconds of exposure, demonstrating effective pathogen control without compromising food quality.
Advancements in Irradiation Technologies for Efficiency and Scalability
Technological improvements in electron beam and X-ray irradiation systems are reshaping market growth. The Food Irradiation Market benefits from faster processing speeds, energy efficiency, and adaptability across multiple food categories. It allows manufacturers to integrate cost-effective solutions that reduce operational bottlenecks. These advancements ensure scalability, making irradiation a viable option for both developed and emerging markets.
- For instance, Ion Beam Applications produces industrial electron accelerators capable of delivering electron energies greater than 10 MeV with average beam powers up to 700 kW, enabling high throughput food irradiation at commercial scales.
Regulatory Support and Global Harmonization of Standards
Government approvals and harmonized international standards are expanding the Food Irradiation Market globally. It receives strong backing from organizations such as the FDA, WHO, and IAEA, which validate irradiation as a safe and effective preservation method. Regulatory clarity encourages producers to adopt the technology without hesitation. Growing alignment across markets supports consistent implementation, which reduces barriers to trade and promotes wider adoption.
Growing Consumer Awareness and Demand for Extended Shelf Life
Rising awareness of food quality and shelf life benefits reinforces growth in the Food Irradiation Market. It appeals to consumers seeking safe, long-lasting products with minimal chemical preservatives. Retailers and food processors leverage irradiation to reduce spoilage and wastage, which enhances sustainability goals. Increasing acceptance among consumers creates a favorable environment for broader adoption in both domestic and export-oriented markets.
Market Trends:
Adoption of Advanced Irradiation Technologies and Process Innovations
The Food Irradiation Market is witnessing steady adoption of advanced technologies such as electron beam, gamma, and X-ray systems that enhance efficiency and safety. It benefits from faster processing speeds, reduced energy consumption, and adaptability to a wide range of food categories including spices, fruits, vegetables, and meat. Companies are investing in automated systems that improve precision, scalability, and cost-effectiveness for commercial use. The integration of digital monitoring and quality assurance tools ensures consistency in dosage control and compliance with international standards. Growing emphasis on sustainable operations is driving innovation toward energy-efficient irradiation systems that align with environmental regulations. Strategic collaborations between technology providers and food processors are shaping the evolution of irradiation methods into mainstream food preservation solutions.
- For instance, Sterigenics expanded its Gurnee, Illinois facility adding gamma irradiation capacity to process up to 5 million cubic feet annually, enhancing scalable and efficient food irradiation services.
Shifts in Consumer Acceptance and Expansion of Global Trade Applications
Consumer perception is shifting as awareness about the safety and benefits of irradiation grows, supporting broader market penetration. The Food Irradiation Market is increasingly positioned as a solution for extending shelf life and reducing food waste, which aligns with global sustainability objectives. It is gaining traction in regions where regulatory bodies and governments endorse irradiation for phytosanitary purposes, particularly in fruits and vegetables meant for export. Expanding international trade creates demand for standardized treatments that meet Codex and IAEA guidelines, ensuring acceptance across diverse markets. Food retailers and exporters rely on irradiation to comply with import regulations and reduce spoilage during long-distance shipping. The steady rise in acceptance among both consumers and regulators is reinforcing its role in building resilient food supply chains.
- For instance, the Codex Alimentarius standard allows a maximum absorbed irradiation dose of 10 kGy for food, facilitating global regulatory acceptance of irradiated products.
Market Challenges Analysis:
High Capital Costs and Limited Infrastructure Deployment
The Food Irradiation Market faces significant challenges from high capital investment and limited infrastructure availability. It requires specialized irradiation facilities and advanced equipment, which demand substantial upfront costs that small and medium-sized enterprises find difficult to manage. Limited access to irradiation centers in developing regions restricts adoption, creating an uneven distribution of technology. Operational expenses, including energy consumption and compliance with safety protocols, further elevate the cost burden. Market players encounter delays in scaling operations where infrastructure and technical expertise are insufficient. These barriers hinder broader penetration despite proven safety and effectiveness.
Consumer Perception and Regulatory Complexity Across Regions
Negative consumer perceptions present a key challenge for the Food Irradiation Market, with lingering misconceptions about food safety and nutritional impacts. It struggles with skepticism that slows acceptance despite extensive validation from global health organizations. Varying regulatory frameworks across regions complicate international trade and create uncertainty for exporters. The lack of uniform standards increases compliance costs and forces companies to adapt to multiple guidelines. Limited awareness campaigns reduce opportunities to educate consumers on the benefits of irradiated foods. Persistent doubts and regulatory complexity restrict growth potential, requiring stronger collaboration between industry stakeholders and policy makers.
Market Opportunities:
Expansion of Global Trade and Growing Demand for Safe Food Supply
The Food Irradiation Market presents strong opportunities through its role in supporting global trade and ensuring safe food supply chains. It enables compliance with international phytosanitary standards, which is critical for exporters of fruits, vegetables, and spices. Rising cross-border demand for fresh produce and meat products creates a need for uniform treatments that extend shelf life while reducing spoilage. Governments and trade bodies are increasingly promoting irradiation to overcome quarantine barriers and enhance export competitiveness. The expansion of international trade in perishable goods reinforces the strategic importance of irradiation as a market enabler. Growing recognition of its role in food safety ensures new opportunities for suppliers and technology providers.
Integration with Sustainability Goals and Rising Consumer Acceptance
Sustainability initiatives create another avenue of growth for the Food Irradiation Market, with companies leveraging irradiation to reduce food waste and limit reliance on chemical preservatives. It supports the circular economy by extending product usability and reducing disposal costs in retail and distribution. Consumers are gradually embracing irradiated foods as awareness campaigns highlight safety and nutritional retention. Opportunities arise from the demand for clean-label products that balance safety with minimal processing. The foodservice and retail sectors are expected to expand adoption as they align product offerings with sustainability goals. These factors open pathways for broader integration of irradiation into mainstream food preservation strategies.
Market Segmentation Analysis:
By Source
The Food Irradiation Market is divided into gamma rays, electron beams, and X-rays, with gamma rays holding a dominant share due to their extensive use in sterilization of spices, herbs, and dry foods. It remains a widely adopted source because of deep penetration capability and reliable performance in bulk treatment. Electron beams are expanding their role, driven by shorter processing times, cost efficiency, and suitability for fresh produce and packaged goods. X-rays are gaining traction for their flexibility and ability to handle larger product volumes with uniform penetration, making them an emerging choice in regions investing in modern irradiation systems.
- For instance, China operated about 130 cobalt-60 gamma irradiation facilities in 2019, responsible for treating 70 to 80 percent of irradiated food products in the country, demonstrating the significant scale of gamma ray use in food sterilization.
By Technology
The Food Irradiation Market is segmented into contract irradiation services and in-house irradiation facilities. Contract services lead the market, offering food processors a cost-effective solution by eliminating the need for capital-intensive infrastructure while ensuring compliance with safety regulations. It allows small and medium enterprises to access advanced treatment without operational risk. In-house facilities are increasing among large-scale food manufacturers that seek operational control, efficiency, and integration of irradiation into supply chains. Rising demand for safe, long-lasting food products supports adoption across both models, reinforcing irradiation technology as a critical element in global food preservation strategies.
- For instance, Bühler Group opened its Grain Innovation Center in Uzwil, Switzerland, in October 2024, equipped with 2,000 square meters of cutting-edge processing infrastructure to enhance in-house irradiation integration and operational efficiency for large clients.
Segmentations:
By Source
- Gamma Rays
- Electron Beams
- X-Rays
By Technology
- Contract Irradiation Services
- In-House Irradiation Facilities
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific Leading Growth Through Regulatory Support and Rising Adoption
Asia-Pacific accounted for 42% of the Food Irradiation Market, making it the largest regional contributor. It benefits from regulatory cooperation under Codex and IAEA standards, creating a favorable framework for exporters of fruits, vegetables, and spices. Countries such as China and India are investing in irradiation facilities to strengthen food safety and enhance export competitiveness. Growing consumer awareness of safe and long-lasting food products supports domestic demand. Rising trade activities and government initiatives ensure that Asia-Pacific remains the dominant growth hub for the sector.
North America Advancing with FDA Approvals and Expanding Applications
North America represented 28% of the Food Irradiation Market, supported by strong regulatory frameworks and expanding application scope. It is driven by FDA approvals that cover irradiation for fresh produce, poultry, and red meat, improving safety and reducing microbial risks. The region shows positive consumer adoption trends as awareness of irradiation benefits expands. Food processors and retailers are leveraging the technology to reduce spoilage and enhance product consistency. Investment in advanced irradiation technologies and collaborations between suppliers and distributors reinforce the region’s leadership. These factors position North America as a key driver of commercial adoption.
Europe Maintaining Moderate Growth with Stringent Regulatory Oversight
Europe held 19% of the Food Irradiation Market, reflecting more cautious adoption under strict regulatory conditions. It operates under EU directives that permit irradiation for limited food categories, restricting broader growth opportunities. Consumer skepticism remains, although safety endorsements from global health organizations are gradually improving acceptance. The region emphasizes compliance and traceability, which increase operational costs for producers. Growth is concentrated in countries allowing broader use of irradiation for spices, herbs, and select foods. Europe maintains steady but moderate expansion within the global market landscape.
Key Player Analysis:
- Food Technology Service
- Inc IONISOS SA
- ScanTech Sciences
- Inc GRAY STAR
- Inc STERIS
- Nordion
- SADEX Corporation
Competitive Analysis:
The Food Irradiation Market is characterized by a mix of established players and specialized service providers competing on technology, capacity, and regulatory compliance. Leading companies focus on expanding irradiation facilities, adopting advanced electron beam and X-ray systems, and strengthening partnerships with food processors. It emphasizes innovation in cost-efficient solutions to improve scalability and cater to diverse food categories such as spices, fresh produce, and meat. Competitive strategies include mergers, acquisitions, and collaborations aimed at broadening service networks and aligning with global safety standards. Market participants also invest in consumer awareness initiatives to address misconceptions and support adoption. With regulatory support and growing trade requirements, competition intensifies as firms seek to capture market share by delivering reliable, compliant, and sustainable irradiation solutions.
Recent Developments:
- In March 2025, Greystar and Trilogy Real Estate Group announced an exclusive strategic partnership, expanding Greystar's presence in key Midwest markets through property management under a white-label structure.
- In June 2025, STERIS purchased over 100,000 square feet of medical office space in Coon Rapids, Minnesota, expanding its footprint in the region.
Market Concentration & Characteristics:
The Food Irradiation Market demonstrates a moderately concentrated structure, with a few global players dominating facility ownership and technology supply while regional providers serve niche applications. It is defined by high entry barriers due to capital-intensive infrastructure, strict regulatory requirements, and the need for specialized expertise. Market characteristics include reliance on gamma ray sources for bulk sterilization, growing adoption of electron beam and X-ray technologies for efficiency, and rising use of contract irradiation services among small and medium enterprises. It is shaped by regulatory backing from organizations such as FDA, WHO, and IAEA, which reinforces safety compliance and encourages wider adoption. Consumer awareness, international trade requirements, and demand for extended shelf life are influencing the competitive dynamics, positioning irradiation as a critical solution within global food preservation and safety frameworks.
Report Coverage:
The research report offers an in-depth analysis based on Source, Technology and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Food Irradiation Market will expand with broader acceptance of electron beam and X-ray technologies, which provide faster processing and energy efficiency.
- Demand will rise from exporters of fruits, vegetables, and spices seeking compliance with international phytosanitary standards.
- It will gain traction as governments continue endorsing irradiation for food safety, strengthening regulatory confidence worldwide.
- Retailers and food processors will adopt irradiation to reduce spoilage and extend shelf life, aligning with sustainability objectives.
- Consumer perception is expected to improve through awareness campaigns highlighting safety, nutritional retention, and reduced reliance on chemical preservatives.
- Growth opportunities will emerge in developing regions where infrastructure investment and regulatory frameworks are strengthening.
- Contract irradiation services will witness steady expansion as small and medium enterprises rely on third-party facilities to reduce capital burden.
- Large-scale food producers will increase in-house facility adoption to achieve greater control over quality and supply chains.
- It will play a stronger role in reducing food waste and ensuring reliable supply in global trade, particularly for perishable goods.
- Ongoing innovation in automated systems and digital monitoring will enhance efficiency, scalability, and operational consistency across the industry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Food Irradiation, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Food Irradiation Market projected to grow between 2024 and 2032?
Which Food Irradiation market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Food Irradiation Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Food Irradiation Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Food Irradiation Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4469 million → 2032: USD 7678.6 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Food Irradiation Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Food Irradiation Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Food Irradiation Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Food Irradiation Market Drivers
- 3.3 Food Irradiation Market Restraints & Challenges
- 3.4 Food Irradiation Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Food Irradiation Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Food Irradiation Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Food Irradiation category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Food Irradiation Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Food Irradiation Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Food Irradiation market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Food Irradiation Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Food Irradiation Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Food Irradiation Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Food Irradiation (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Food Irradiation Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Food Irradiation Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Food Irradiation Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Food Irradiation Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Food Irradiation Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Food Irradiation Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Food Irradiation Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Food Irradiation Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Food Irradiation Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
